

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Single-Use Sensors Market to reach USD 984M by 2032

Single-Use Sensors Market 2026: Strategic Playbook for Bioprocess Leaders
Executive snapshot
As single-use technologies become standard across biologics manufacturing, single-use sensors have emerged from niche components to strategic levers for process control, speed-to-clinic and cost optimization. Our PW Consulting Single Use Sensors Market study (base year 2025; historical 2020–2025; forecast 2026–2032) quantifies this transition: the market reached approximately USD 392.0 Million in 2025 and is set to expand at a compound annual growth rate (CAGR) of 14.2% over the forecast window, crossing roughly USD 984.0 Million by 2032. For executives preparing decisions in 2026, these macro signals are not theory — they are the economic backdrop that will shape procurement, R&D prioritization, partnerships and M&A for the next three to five years.
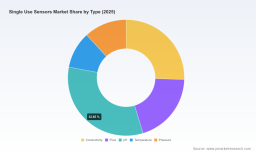
Single Use Sensors Market
Why this matters for 2026 strategic decisions
-
From tactical sourcing to platform strategy: The rapid growth of demand for disposable sensors transforms them from commodity purchases into critical path elements for single-use bioprocess platforms. Decisions made in 2026 about supplier qualification, platform compatibility and inventory buffers will determine time-to-market for new drug candidates and the resilience of commercial supply chains.
Single Use Sensors Market -
Regulatory and validation timings are decisive: Unlike many consumables, sensors require integration into process validation, sterilization regimes and quality systems (ISO 13485, USP Class suitability, gamma sterilization validation). Lead times for qualification can be measured in quarters; delaying a decision on sensor platform architecture in 2026 can cascade into missed clinical or commercial milestones.
Single Use Sensors Market -
Cost-to-serve and unit economics: As adoption scales, the per-run economics of single-use bioprocesses are increasingly sensitive to sensor selection — both direct unit cost and indirect impacts such as validation, reuse of electronics, and sensor reliability. The market’s double-digit CAGR signals both pricing pressure and opportunity for differentiated, value-based offerings.
What our report delivers — practical assets for 2026 planning
The report is structured to be operationally actionable for leadership teams and program managers. Highlights include:
-
Proprietary market sizing and forecast model (2020–2032) with scenario analyses that stress-test adoption curves and technology substitution effects under multiple commercialization timelines.
-
Technology roadmaps identifying near-term (1–2 years) and medium-term (3–6 years) innovations in sensor chemistries, sterilization compatibility (e.g., gamma-sterilizable designs), and integration approaches (patches, inline, preinstalled cartridges).
-
Vendor scorecards and procurement playbooks that map supplier capabilities (manufacturing certifications, cleanroom class, materials compliance) to the operational requirements of biomanufacturers.
-
Regulatory and validation checklists tailored for single-use sensor adoption, including recommended testing regimes, documentation strategies for FDA/EMA submissions, and change-control templates to reduce downstream risk.
-
Commercial frameworks — pricing strategies, channel models (OEM, direct, distributor), and contract terms crafted for 2026 negotiation cycles.
-
M&A and partnership decision matrices that help evaluate bolt-on opportunities versus internal development, with payback timelines under current market growth assumptions.
Competitive landscape: how incumbents and specialists stack up
The competitive field is a mix of specialized innovators and capitalized instrument OEMs. Our market concentration analysis shows an industry moving toward consolidation: the top three players account for a meaningful portion of market share while the top five are responsible for the majority of sales — a structure that creates both barriers and strategic openings.
-
PendoTECH (Portsmouth, NH, USA) — Strengths: certified manufacturing (FDA-registered, ISO 13485), controlled cleanroom production and a portfolio spanning pressure, pH, conductivity, temperature and optical sensors. Implication: well positioned to supply GMP-grade sensor assemblies and attractive OEM partnerships.
-
Levitronix (Bedford, MA, USA) — Strengths: LEVIFLOW ultrasonic inline flow sensors built from gamma-robust polypropylene and compliant materials. Implication: differentiates via non-invasive flow measurement and materials engineered for sterilization robustness — a clear fit for operators prioritizing sterility assurance.
-
Broadley-James (Irvine, CA, USA) — Strengths: SingleSense® line of preinstalled pH, DO and pCO2 sensors with long shelf life and FDA-compliant materials. Implication: value proposition centers on convenience and reduced assembly risk for bag-based workflows.
-
Hamilton Company (Reno, NV, USA) — Strengths: patch-style single-use pH and DO sensors designed for compatibility across bioreactor bag platforms. Implication: platform-agnostic interoperability that appeals to multi-vendor facilities.
-
Sartorius AG (Göttingen, Germany) — Strengths: integrated single-use sensors with gamma-sterilizable options and deep bioreactor integration. Implication: as a systems supplier, Sartorius can bundle sensors with bioreactor platforms to capture higher share of wallet.
-
Thermo Fisher Scientific (Waltham, MA, USA) — Strengths: acquisition-driven expansion (e.g., Finesse Solutions optical sensors) and global commercial reach. Implication: ability to quickly scale new sensor technologies via established channels.
-
Danaher Corporation (Washington, DC, USA) — Strengths: Cytiva platform provides established routes to market for single-use probes and sensors. Implication: major incumbent with integration advantages and cross-selling opportunities across process equipment.
-
Parker Hannifin Corporation (Cleveland, OH, USA) — Strengths: flow and pressure monitoring solutions tied to fluidic systems. Implication: well-suited for integrated process control offerings where sensors are bundled with fluid handling equipment.
-
Eppendorf AG (Hamburg, Germany) — Strengths: sensor patches and optical pH/DO solutions geared to single-use bioreactors. Implication: focuses on ease-of-use and integration for benchtop and small-scale manufacturing.
Strategically, the field presents three archetypes buyers will face in 2026: (1) system integrators that bundle sensors with platforms, (2) specialized suppliers offering differentiated chemistries or form factors, and (3) OEM/contract manufacturers providing private-label solutions. Each archetype implies different negotiation levers and risk profiles.
Key strategic imperatives for 2026
-
Lock down validated supplier lanes early: Prioritize supplier qualification and cross-validate sterilization claims. Given validation lead times, locking agreements and performing interoperability tests in 2026 prevents downstream delays.
-
Design for compatibility: Choose sensor architectures that minimize platform lock-in (e.g., interoperable electronics or modular patch interfaces) to protect portfolio flexibility as the market evolves.
-
Prioritize sterilization-proof materials and supply security: Gamma-robust materials and USP-compliant polymers will be table stakes for broad adoption. Secure multiple material sources and audit supply chains for critical polymers.
-
Use procurement as a strategic lever: Negotiate volume-based pricing tied to validated performance metrics, but also include clauses for rapid ramp-up support and co-development for future sensor features.
-
Scan for bolt-on innovation targets: For platform vendors and private-equity-backed companies, 2026 is fertile for targeted M&A — buying specialty sensor tech can accelerate capability without long internal development cycles.
A pragmatic decision framework for 2026
When assessing options this year, apply a two-step framework:
-
Qualify (Now): Regulatory fit (materials, ISO/FDA), sterilization compatibility, and manufacturing certifications. These are non-negotiables and should be verified through audits or third-party validation reports.
-
Optimize (Next 6–18 months): Total cost of ownership (unit cost, validation cost, failure rate), integration roadmap (electronics, data compatibility), and strategic optionality (IP, co-development rights).
Closing: why our report is a 2026 decision catalyst
For executives, 2026 will be a year where sensor decisions compound into competitive advantage or operational drag. Our report provides the empirically grounded market sizing and the playbooks that translate those numbers into procurement actions, product roadmaps and M&A priorities. We intentionally preview strategic signals here while withholding the granular regional, application and price-point tables that operational teams use to run negotiations and build business cases — those proprietary segment matrices, supplier scorecards and transaction-ready models are available in the full PW Consulting Single Use Sensors Market report.
Contact PW Consulting to schedule a brief that maps the report’s insights directly to your 2026 roadmap and procurement calendar. In a market growing at double-digit rates and reshaping how biologics are developed and commercialized, timely choices about sensors will be disproportionately consequential.
For detailed analysis of this topic, please visit the official page: Single Use Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com