

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
All-In-One CRM to Reach USD 175B by 2032 at 12.4% CAGR — PW Consulting

All‑In‑One CRM Software Market: Strategic Frames for 2026
Executive snapshot
By 2025 the All‑In‑One CRM Software market had matured into a billion‑dollar category with clear momentum: from roughly 50.5 billion USD in 2020 the market expanded to approximately 83.2 billion USD in 2025. PW Consulting’s forecast models project continuation of this trajectory, reaching roughly 96.7 billion USD in 2026 and more than 175.0 billion USD by 2032 — an effective compound annual growth rate of 12.4% over the 2026–2032 forecast horizon. This pace reflects both accelerating adoption of agentic AI, broader cloud modernization, and the commercialization of automation at scale.
All-In-One CRM Software Market
Why this research matters for 2026 decision-makers
-
Timing is now strategic: 2026 is a turning point where pilots and point solutions must either scale into platform bets or be retired. The market growth profile shows a window for aggressive platform capture during enterprise digital transformation programs.
All-In-One CRM Software Market -
Vendor choice is multi‑dimensional: decisions are no longer about feature checklists alone. You must evaluate platform composability, AI modality support, data residency and governance, integration cost, and a vendor’s route to ongoing value delivery.
All-In-One CRM Software Market -
Capital allocation requires precision: whether you represent corporate IT, a business unit owner, or an investor, the market’s growth and concentration dynamics demand calibrated investment and M&A playbooks to secure defensible positions.
Macro takeaways for 2026 planning
-
Scale and speed: With the market nearly doubling over the previous five years and still expanding at double‑digit CAGR, procurement cycles should prioritize scalable architectures that reduce marginal integration cost as usage grows.
-
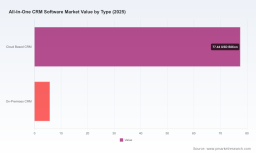
Cloud‑first is table stakes: The dominant delivery model is cloud, enabling frequent product updates, built‑in analytics, and rapid AI upgrades. On‑premises remains relevant for niche regulatory reasons but is not the growth vector.
-
Consolidation dynamics: Market concentration metrics indicate a moderate top‑end concentration — leading vendors control a majority but there remains substantial runway for challenger platforms offering specialization, vertical depth, or disruptive pricing and go‑to‑market models.
-
AI drives re‑segmentation: Agentic AI and autonomous connectors are creating new product layerings — from smart agents that execute routine sales activity to autonomous marketing orchestration that reduces manual campaign labor.
What this report gives you — in practical terms
PW Consulting’s All‑In‑One CRM Software Market study is designed as an operational playbook for 2026. Key deliverables include:
-
Robust market sizing and demand modeling (historical 2020–2025, base year 2025, forecast 2026–2032) expressed in consistent USD billion terms and stress‑tested under alternative adoption scenarios.
-
Vendor scorecards that go beyond capability matrices to evaluate developer ecosystems, AI partner readiness, integration velocity, and realistic TCO profiles over three‑ and five‑year horizons.
-
Go‑to‑market and buyer decision frameworks with step‑by‑step procurement templates, RFP checklists, and implementation risk heatmaps tailored for enterprises and channel partners.
-
M&A and investment diagnostics highlighting build vs buy inflection points, defensible moats, and realistic exit multiples under conservative and aggressive growth scenarios.
-
Integration blueprints for common enterprise architectures, including data governance patterns, identity orchestration, and recommended middleware approaches to prevent long tail technical debt.
Competitive landscape — how leading vendors are positioning
The competitive field is a mix of global platform incumbents, scale challengers, and specialist stacks. Key dynamics we track across vendors include platform breadth, AI/agent roadmaps, verticalization strategies, and partner ecosystems.
-
Salesforce — The Customer 360 narrative continues to center Salesforce’s strategy: uniting sales, service, marketing, commerce, and agent capabilities into an operational fabric. Recent product releases in 2026 extended Agentforce capabilities and analytics across the Customer 360 suite, underlining a push to capture higher‑value enterprise deals and to lock in cross‑cloud data advantages.
-
HubSpot — HubSpot’s Customer Platform emphasizes usability and an agentic ecosystem. The Spring 2026 Spotlight introduced Breeze Agents and smarter deal progression features, signaling an intent to lower the activation cost for midmarket accounts while progressively moving upmarket.
-
ActiveCampaign — ActiveCampaign’s strategy is to operationalize autonomous marketing. In early 2026 the company shipped an autonomous marketing connector for Anthropic’s Claude, illustrating how third‑party LLM integrations are being productized to reduce human orchestration in campaign execution.
-
Creatio — Creatio positions itself as an AI‑native no‑code platform. Recent enterprise wins demonstrate its appeal to institutions seeking rapid configuration and cross‑org unification without heavy engineering lift.
-
Zoho CRM — Zoho continues to push deeper automation into daily workflows. Q1 2026 updates focused on workflow ergonomics and natural language formula generation, reinforcing Zoho’s strategy of embedding pro‑productivity tools at low cost.
-
Specialists and SMB stacks — Vendors like 1CRM, ConvergeHub, Salesmate, and others compete on focused use cases: order management, loyalty, lead prioritization, and price‑performance for SMBs. These vendors remain important acquisition targets and talent pools for larger platforms building vertical depth.
Technology and operational dynamics shaping vendor advantage
-
Agentic AI is redefining workflows: Embedded AI agents that can execute prospecting, follow‑ups, and parts of service workflows shift value from feature breadth to agent effectiveness and observability.
-
No‑code / low‑code matters beyond speed: Platforms that let business users compose end‑to‑end processes reduce governance friction, but successful deployments demand strong guardrails and audit trails.
-
Data governance as a competitive moat: Vendors that can provide enterprise‑grade data controls, lineage, and cleanroom capabilities will win larger deals where privacy and compliance are non‑negotiable.
-
Partner ecosystems compress time‑to‑value: System integrators and ISVs that package vertical accelerators (e.g., financial services member onboarding, retail loyalty orchestration) will shorten sales cycles and increase stickiness.
Strategic playbook: what each stakeholder should prioritize in 2026
-
Enterprise CIO / CDO: Build a 36‑month platform roadmap that budgets for AI enablement, data plumbing, and a vendor consolidation plan. Prioritize platforms with composable APIs and clear migration paths for legacy CRM data.
-
Chief Revenue / Marketing Officers: Test agentic automations in controlled pilots tied to revenue KPIs. Expect initial lift in lead conversion and operational efficiency; measure net impact on pipeline economics, not just activity metrics.
-
ISVs and system integrators: Invest in packaged vertical accelerators and clear SLAs for AI behavior. Time‑to‑value packaged solutions will beat bespoke implementations in most midmarket segments.
-
Private equity and strategic investors: Focus diligence on recurring revenue quality, partner attrition metrics, and the asset’s capacity to plug into larger platform ecosystems. The best targets will show defensible product differentiation and accelerating net retention.
Why PW Consulting’s report is the right toolkit for 2026
We combine quantitative rigor (full historical series 2020–2025; base year 2025; detailed forecasts 2026–2032; currency in USD billions; modeled at a 12.4% CAGR through the forecast window) with qualitative, execution‑oriented insight: vendor playbooks, implementation checklists, and acquisition scorecards. The study is intentionally structured to support both strategic and tactical workstreams — from boardroom strategy to procurement and implementation squads.
Next steps — how to use this preview
-
Request the full vendor scorecards to benchmark platform choices against your integration and AI maturity.
-
Use the TCO and migration templates to model three migration pathways — lift‑and‑shift, phased modernization, and greenfield replacement — and quantify incremental savings and business outcomes.
-
Engage PW Consulting for a short diagnostic to map your CRM estate to the market’s growth segments and identify immediate efficiency levers for 2026.
Closing
The All‑In‑One CRM Software market in 2026 is neither a commodity nor a simple vendor selection exercise — it is a strategic architecture decision that will shape go‑to‑market execution and customer economics for years. PW Consulting’s research provides the macro context, competitive read, and practical tools you need to make those decisions with confidence. For full segmentation tables, granular regional and use‑case analysis, and vendor benchmarking data, consult the complete report and supporting datasets.
For detailed analysis of this topic, please visit the official page: All-In-One CRM Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com