

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Next-Gen Advanced Batteries to Reach USD 324M by 2032 (7.1% CAGR)

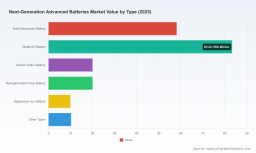
Next-Generation Advanced Batteries Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As governments and corporations pursue decarbonization and electrification, next-generation battery technologies have moved from laboratory promise to boardroom priority. PW Consulting’s latest market study — Next-Generation Advanced Batteries Market (base year 2025, forecast 2026–2032) — quantifies a clear upward trajectory: the global market expanded substantially through the first half of the decade and is projected to continue growing at a compound annual growth rate of approximately 7.1% across the forecast horizon. For executives planning capital allocation, strategic partnerships, or R&D roadmaps in 2026, this study reframes risk and opportunity with pragmatic, decision-grade insight.
Next-Generation Advanced Batteries Market
Why this preview matters for 2026 decisions
-
Timing matters: 2026 is the inflection year for many commercialization and scale-up milestones. Several pilot lines, validation programs, and gigafactory projects are transitioning toward industrialization, creating short windows to secure supply, intellectual property positions, and offtake arrangements.
Next-Generation Advanced Batteries Market -
Value at scale: while early-stage technologies still present execution risk, the market-size trajectory underscores material commercial potential. Our study translates macro momentum into portfolio-level consequences — which technology bets compress time-to-market, which require additional material-security measures, and which demand alternative go-to-market models.
Next-Generation Advanced Batteries Market -
Concentration and competitive dynamics: the market is meaningfully concentrated among a small set of frontrunners. The leading three firms control a dominant share of the market’s revenue and technology mindshare; the five largest firms widen that moat further. For incumbents and new entrants alike, understanding where the power centers sit is essential for negotiating JV terms, licensing deals, or vertical integration.
Market trajectory and macro context
From a quantifiable perspective, the global advanced-batteries market has more than recovered from pandemic-induced disruptions and is set on a sustained expansion path through 2032. The base-year assessment (2025) provides a robust benchmark for board-level scenario planning; the forecasted CAGR of about 7.1% reflects a market driven by transportation electrification, grid-scale storage needs, and incremental adoption across industrial and consumer segments. PW Consulting’s models integrate demand-side drivers, manufacturing scale economics, and technology learning curves to produce actionable topline forecasts and downside scenarios for 2026 planning cycles.
Key dynamics shaping 2026 strategy
-
Capital deployment and industrial policy: large-scale public and private investments have reshaped capacity expectations. A pronounced pipeline of announced manufacturing projects and significant federal funding streams have materially derisked certain buildout scenarios, but they also raise the stakes for choosing the right technology partners and geographic footprints.
-
Technology readiness vs. deployment cadence: advanced chemistries (e.g., solid-state, sodium-ion, metal-air variants) show differentiated maturation timelines. Several firms have moved from cell-level R&D into validation and pilot production, prompting a two-speed market where early commercial adopters will enjoy first-mover advantages if they can accept near-term premiums for performance.
-
Supply-chain and raw-material dynamics: upstream investments and new mining/processing capacity are changing availability patterns for critical inputs. At the same time, next-generation chemistries alter raw-material requirements — both an opportunity and a supply-chain re-engineering challenge.
-
Standardization and industrialization: pilot production counts and emerging roadmaps for solid electrolytes and related systems show that manufacturing know-how is consolidating. Standardization milestones and qualification roadmaps in 2026 will determine which platforms are scalable and which remain experimental.
-
Regulatory tailwinds: infrastructure and incentive policies continue to accelerate deployment. Recent legislative measures and funding programs have made battery manufacture and domestic supply-chain investments a strategic priority in several markets, altering cost, competitiveness, and partnership rationales.
Competitive landscape — who matters and why
Our competitive analysis synthesizes company-level strategy, technology readiness, and recent milestones to help buyers and investors prioritize engagements. Select examples from the report illustrate the diversity of strategic postures:
-
QuantumScape (San Jose, CA): pursuing lithium-metal solid-state cells with a focus on validating automotive-rate cycle life and integration with large OEM platforms. Recent cell validations at automotive discharge profiles underscore a pivot from lab proofs to vehicle-system validation.
-
Solid Power (Louisville, CO): specializing in all-solid-state lithium-metal cells for EVs and storage, with partnerships oriented toward automotive OEM qualification and scale-up support.
-
Enovix (Fremont, CA): advancing high-energy-density silicon-anode architectures with manufacturing designs optimized for compact, high-energy applications.
-
Factorial Energy and ProLogium: both prioritize solid-state approaches but differ in material pathways and commercialization strategies; one emphasizes material innovation to improve safety and scalability, while the other is actively executing on gigafactory buildouts in locations aimed at serving localized demand pools.
-
Ambri and Peak Energy: target long-duration and grid-focused applications with distinct chemistries (molten-salt, sodium-ion), representing an alternative risk/reward profile for system integrators and utilities.
-
Smaller technology suppliers (e.g., Natrion, SES AI) are important as enablers — supplying separators, electrolyte technologies, and cell designs that can be licensed or co-developed at scale.
These snapshots are expanded in the report with supplier maps, capability matrices, and scenario-tested competitive playbooks. Recent corporate events — from cell validation milestones to gigafactory announcements and pilot-line investments — are surfaced and interpreted for 2026 strategic action.
What PW Consulting’s full study delivers (practical content)
PW Consulting’s full report is designed as an operational toolkit for executives making capital and partnership decisions this year. It includes:
-
Granular, model-driven demand forecasts across the 2026–2032 horizon, accompanied by sensitivity analyses and downside stress cases to test portfolio robustness.
-
Technology readiness assessments and commercialization timelines: not just TRL scores, but manufacturability indices and capital-intensity profiles for alternate technology paths.
-
Supply-chain risk maps and raw-material scenarios that account for announced capacity pipelines, funding flows, and geopolitical variables.
-
Competitive benchmarking: R&D positioning, patent landscapes, and a “partner fit” matrix to fast-track M&A, JV, or licensing conversations.
-
Investment playbooks and project prioritization frameworks calibrated for CFOs and investment committees, with hurdle-rate and payback analyses tailored to different risk appetites.
-
Operational checklists for establishing pilot lines, transitioning to mass production, and accelerating qualification with OEMs and system integrators.
-
Regulatory and incentive navigation guides, detailing how major policy instruments and funding windows can be leveraged in market entry and expansion strategies.
How to use this intelligence in 2026
-
Prioritize optionality: use our decision tree to size investments that preserve optionality across two or three technically plausible chemistries rather than committing to a single-path long-lead asset prematurely.
-
Lock strategic partnerships early: for buyers and OEMs, securing validated cell supply or co-development agreements in 2026 will shorten OEM qualification cycles and provide competitive differentiation into the early 2030s.
-
De-risk procurement: integrate raw-material hedging and multi-sourcing strategies informed by our supply-chain scenarios to mitigate single-source exposure during scale-up.
-
Align policy and capital plays: synchronize investment timing with anticipated policy funding windows and local incentive programs to maximize subsidy capture and reduce capital costs.
-
Plan for standardization outcomes: invest in modular manufacturing and qualification processes that can adapt to emerging standards and reduce retooling risk as production practices converge.
Closing — the competitive edge for 2026
For corporate leaders and investors, 2026 will separate strategic winners from laggards. The market’s structural growth, coupled with concentrated competitive dynamics and accelerating industrial policy, creates a narrow opportunity corridor for those who plan deliberately: secure validated partners, stage investments to preserve flexibility, and align internal operating models to a faster qualification cadence. PW Consulting’s Next-Generation Advanced Batteries Market study is calibrated to these realities — offering the forecast precision, scenario analytics, and operational playbooks decision-makers need right now.
Next step
This preview intentionally highlights the strategic signals without disclosing the proprietary segment-level forecasts and granular supplier economics contained in the full report. For the complete dataset, interactive models, and tailored advisory options to inform your 2026 capital and partnership decisions, access the full study and our consulting services through PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Next-Generation Advanced Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com