

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
PW Consulting: Bake‑Stable Pastry Fillings Market to Grow at 5.2% CAGR, Reaching USD 2,067.7 Million by 2032 as Europe Leads with USD 504.6M Share
By pmarketresearch, 2026-07-07
Bake Stable Pastry Fillings Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market research—Bake Stable Pastry Fillings Market (Base year: 2025, Forecast: 2026–2032)—equips senior leaders, R&D heads, and M&A teams with the actionable intelligence required to move from reactive operations to proactive market shaping in 2026. The report synthesizes five years of historical dynamics (2020–2025) and presents a detailed forward view: the global bake-stable pastry fillings market, measured in USD Million, expands from the 2025 base and is forecast to grow at a 5.2% compound annual growth rate (CAGR) through 2032. By the end of the forecast horizon the market reaches an estimated USD 2,067.66 Million, underscoring a materially enlarging opportunity for ingredient suppliers, co-manufacturers and bakery brands.
Bake Stable Pastry Fillings Market
Why this preview matters for 2026 strategy
2026 is a pivot year: raw material volatility has begun to moderate following acute price spikes, consumer expectations are accelerating around clean-label and functional attributes, and production technologies for high-throughput bakeries are rapidly maturing. For executives deciding product portfolios, capital allocation, or partnership strategies this report functions as both compass and toolkit—highlighting which trade-offs deliver durable margin expansion and which moves risk commoditization.
Bake Stable Pastry Fillings Market
-
Timing decisions on plant capacity and pilot facilities: with market momentum accelerating in 2026, our modeling clarifies the window where incremental capacity yields premium utilization rather than oversupply.
Bake Stable Pastry Fillings Market -
Formulation and ingredient sourcing: the report assesses how formulation choices (starch systems, pectin profiles, clean-label stabilizers) translate into bake stability, shelf life, and cost-to-serve across industrial and foodservice channels.
-
M&A and partnering: concentration metrics indicate meaningful room for consolidation and bolt-on plays that can rapidly increase scale in strategically aligned subsegments.
What the PW Consulting report delivers (practical, actionable content)
This is not a high-level narrative. The report contains hands-on assets designed for implementation teams:
-
Executive dashboards and a downloadable financial model that let you scenario-test price, raw material shifts, and channel mix impacts on margin and working capital through 2032.
-
Go-to-market playbooks for three priority customer profiles (industrial bakeries, foodservice operators, retail/home-baking brands), including tailored sampling protocols, shelf-life validation plans, and commercial KPIs for distributor partnerships.
-
Formulation decision trees and lab-to-line scale-up checklists: guidance on selecting starch systems, fruit concentrates, and oil phases to optimize migration, rheology, and bake stability under high-temperature processes.
-
Supplier scorecards and cost-optimization levers: procurement scripts and benchmarking tools to negotiate ingredient contracts and hedging strategies against raw-material swings.
-
Regulatory and clean-label compliance matrixes: where to prioritize ingredient transparency and how to structure claims without compromising product stability or shelf life.
-
Three investment case studies that show step-by-step returns from product innovation, capacity expansion, and channel diversification—complete with sensitivity analyses and recommended KPIs.
Market dynamics and raw material context
Several forces are converging on the bake-stable fillings value chain. First, raw-material price shocks of the recent past have not vanished but demonstrate different trajectories across commodity classes. Cocoa experienced an extreme spike into early 2025 and then corrected significantly by mid‑2026, while retail fresh fruit prices have shown modest year-on-year increases even as farm-level price pressure may ease in 2026. Sugar and sweetener pricing has been volatile on a year-on-year basis, with short-term monthly easing in early 2026. These shifts matter because they change not only input costs but also formulation choices (e.g., transitions to fruit concentrates, different sweetener matrices, or stabilized fruit prep methods).
Second, regulatory and consumer-driven clean-label preferences are now structural. Demand for bake-stable fillings that avoid artificial additives, certain stabilizers, or high‑fructose sweeteners is driving R&D investment in alternative hydrocolloids, pectin systems, and enzymatic process controls. Companies that can translate clean-label claims into robust, bake-stable performance will win access to premium channels.
Segmentation and concentration—what to watch (high level)
The market’s growth dynamic is broad-based across flavors, applications and geographies. Our segmentation analysis tracks regional demand, flavor categories (fruit-based; chocolate and nut-based; cream/custard-based) and application channels (industrial/wholesale, foodservice, retail/home baking) to reveal where structural growth and margin uplift opportunities reside. Rather than publishing every granular split here, the report provides interactive segment matrices that allow users to isolate the exact segments most relevant to their strategy.
Concentration is moderate: the top three players control a meaningful share of the market while the top five extend that influence—indicating both brand advantages and space for acquisitive growth by well-capitalized challengers. This structure means mid-sized operators can still capture specialist premium niches, especially where they can demonstrate formulation superiority or channel intimacy.
Competitive landscape—what incumbents are doing
We profile the strategic moves and product architectures of the market’s core suppliers. Highlights include:
-
Puratos Group (Groot-Bijgaarden, Belgium) has invested in pilot plant capacity and innovation ecosystems to accelerate commercialization of high‑stability fruit and cream systems—targeting commercial bakeries that require scaleable, clean-label fillings.
-
Dawn Foods (Jackson, Michigan, USA) continues to leverage its BakeFill and PlusFill families, emphasizing high fruit content and formulations optimized for freeze-thaw and bake stability across a wide set of bakery formats.
-
AGRANA (Vienna, Austria) is focusing on thermostable fruit preparations that preserve shape and color under aggressive baking; their recent trade show activity underscores a push into all‑in‑one ingredient solutions including vegan options.
-
Bakels Group (Lucerne, Switzerland) and Andros Chef (Cajarc, France) are expanding ready‑to‑use and clean‑label offerings, serving both industrial and home-baking channels with vegan and preservative‑free lines.
-
Metarom USA (New Hampshire, USA) positions itself as a technical partner for custom flavor and filling systems—publishing technical criteria for selection of bake‑stable fillings that help industrial buyers reduce technical risk.
-
Barry Callebaut (Zurich, Switzerland) remains an important supplier of chocolate- and caramel-based bake-stable fillings, investing in heat-tolerant chocolate constructs for high-temperature processing.
Recent events validate these strategic tracks: Puratos’s facility launch in mid‑2025 accelerates application testing for commercial customers; Metarom’s technical publications in 2025 are shaping procurement criteria at industrial bakeries; and AGRANA’s trade-show rollouts confirmed interest in consolidated ingredient packages that reduce supplier complexity.
Innovation priorities for 2026
Based on lab-to-line analysis and customer interviews, five innovation vectors offer the highest commercial upside in 2026:
-
Clean-label hydrocolloid matrices that deliver bake stability without artificial additives.
-
High-fruit-load preparations that maintain structure and color when subjected to long bake cycles or prolonged shelf storage.
-
Thermostable chocolate and caramel fillings engineered for industrial tunnel ovens and fryer applications.
-
Stabilized low-sugar and reduced-calorie fillings that preserve mouthfeel and water activity control.
-
Modular co-manufacturing models (private label plus innovation tiers) that reduce customer time-to-market.
Go-to-market, risk mitigation and M&A playbook
The report provides step-by-step playbooks to execute on commercial opportunities while controlling risk. These include rapid qualification protocols for new fillings, procurement hedging templates tied to raw-material indices, and integration checklists for bolt-on acquisitions—addressing integration of R&D, supply chain, sales channels, and regulatory files.
For M&A teams, our valuation frameworks incorporate scenario testing under different raw‑material volatility regimes and channel-shift assumptions. Given the current competitive concentration and growth profile, opportunistic acquisitions that bring either proprietary formulation technology or differentiated channel access are likely to deliver above-average returns.
Methodology and reliability
The PW Consulting analysis combines bottom-up supplier reporting, proprietary demand modeling, and primary interviews across the value chain. Our base year is 2025 with historical trend analysis from 2020–2025 and scenario-driven forecasts for 2026–2032. We integrate commodity price research, regulatory trend tracking, and supplier capacity mapping to produce pragmatic scenario outputs suitable for board-level decision-making.
How to use this intelligence in 2026
Practical next steps for executive teams:
-
Run a tailored scenario in the report’s model to test the impact of a 10–20% raw-material swing on your product portfolio and determine which SKUs to rationalize or scale.
-
Prioritize pilot plant investments for one or two clean-label fillings that can be rolled out across key channels within 12–18 months.
-
Use supplier scorecards and procurement playbooks to renegotiate contracts keyed to performance metrics rather than purely on price.
-
Evaluate bolt-on acquisitions that offer proprietary formulation IP or exclusive R&D relationships with regional bakery networks.
Conclusion — a pragmatic call to action
For leaders preparing 2026 budgets and three‑year roadmaps, the bake‑stable pastry fillings market represents a concrete growth corridor with actionable levers. The industry is neither fully consolidated nor technologically static: ingredient suppliers that pair formulation know‑how with strong go‑to‑market execution will capture disproportionate value. PW Consulting’s full report converts the market’s macro signal—steady growth at a 5.2% CAGR into 2032—into operational blueprints, commercial scripts, and investment cases designed to be executed in 2026.
To access the full dataset, interactive models, and supplier scorecards referenced in this preview, please visit the report’s source webpage where the comprehensive report and supporting appendices are available for download.
For detailed analysis of this topic, please visit the official page: Bake Stable Pastry Fillings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: At-Home Hair Removal Devices Market Poised to Expand at a 7.2% CAGR Through 2032
By pmarketresearch, 2026-07-07
At-Home Hair Removal Devices Market 2026: Strategic Imperatives from PW Consulting’s New Industry Deep Dive
Executive preview
PW Consulting’s latest market research on At-Home Hair Removal Devices provides an authoritative, action-oriented vantage point for executives preparing 2026 strategic plans. The global market reached USD 725.5 Million in our base year (2025) and is positioned to expand to approximately USD 777.7 Million in 2026, accelerating to an estimated USD 1,180.3 Million by 2032. This trajectory represents a compound annual growth rate (CAGR) of 7.2% across the 2026–2032 forecast window, reflecting sustained consumer demand, technology diffusion, and regulatory maturation.
At Home Hair Removal Devices Market
Why this matters for corporate decisions in 2026
-
Timing matters: The market’s steady, above-market CAGR signals a window in which product launches, regulatory approvals, and channel investments can compound value quickly. Companies that align 2026 product roadmaps with validated safety and ease-of-use claims will accelerate adoption curves.
At Home Hair Removal Devices Market -
Regulatory clarity creates optionality: Recent regulatory activity is lowering barriers for credible entrants while imposing predictable compliance costs. Organizations that build regulatory strategy into product design and commercialization timelines will de-risk launch investments and access larger addressable segments faster.
At Home Hair Removal Devices Market -
Concentration and M&A signals: Market concentration is moderate—lead players hold meaningful shares but fragmentation persists—creating fertile ground for bolt-on acquisitions, strategic alliances, and private-label plays that can unlock scale economies or channel access in 2026.
-
Cost and supply-side pressures: Upward pressure on raw material and electronic component costs is compressing gross margins for manufacturers. Firms that prioritize supply-chain resilience and design-for-cost will protect margins even as pricing dynamics evolve.
Market dynamics: what the numbers tell us (and what we intentionally withhold)
Our topline market sizing provides a clear growth arc from 2023 through 2032. After the market’s recovery and expansion in the early 2020s, 2025 stands as a practical planning baseline (USD 725.5 Million) from which corporate 2026 budgets and resource allocations should be built. Forecasts show the sector growing to roughly USD 777.7 Million in 2026 and continuing to expand to more than USD 1.18 Billion by 2032 under a 7.2% CAGR.
While this release shares the high-level trajectory and underlying growth drivers, we intentionally limit disclosure of granular regional, technology and channel splits in this preview. The full report contains the detailed segmentations, sensitivity scenarios, and proprietary demand-models that corporate teams use to allocate R&D, CAPEX, and commercial resources with confidence.
Regulation, reimbursement and product safety: recent developments and implications
-
Regulatory pathway: At-home IPL and laser devices continue to be regulated as Class II medical devices in major markets that require 510(k) clearances for over‑the‑counter marketing. 2025–2026 has seen ongoing 510(k) activity that is validating new models and enabling market entry for established and emerging vendors alike.
-
Recent signals: Multiple manufacturers received 510(k) clearances for ice-cooling and other design enhancements in 2025. For corporate strategists, this trend means that technological differentiation—combined with clear, evidence-based safety claims—can be converted into commercial advantage more rapidly than in the prior decade.
-
Reimbursement reality: At-home hair removal remains predominantly cosmetic and is generally not covered by health insurers. Professional procedures may qualify for reimbursement under specific medical indications, but these are specialty cases. For most device manufacturers, ROI models should therefore assume predominantly cash-pay consumer demand.
-
Supply chain considerations: Rising costs for plastics, metals, and electronic components are non-trivial. Companies should prioritize dual-sourcing, negotiate long-term agreements, and explore design optimizations to reduce part counts and BOM costs without sacrificing safety or efficacy.
Competitive landscape: who’s shaping the market and what they’re doing
The competitive field blends heritage consumer-electronics brands, focused medical-device specialists, and nimble regional challengers. Key companies profiled in our analysis include:
-
Philips (Amsterdam, Netherlands) — A major incumbent offering the Lumea IPL series with SkinAI enhancements and multi‑attachment versatility. Philips leverages global brand equity and service networks to support premium positioning. ( https://www.philips.com)
-
Braun / Procter & Gamble (Kronberg im Taunus, Germany) — The Silk Expert Pro IPL devices emphasize adaptive skin-tone sensing for safety and consistent performance, grounded in consumer trust built over decades. ( https://us.braun.com)
-
Tria Beauty (San Leandro, California, USA) — A specialist distributor of diode‑laser at-home devices, offering higher‑power, clinical-grade laser technology targeted at customers seeking long‑term permanence. ( https://www.triabeauty.com)
-
Ulike (Hangzhou, China; R&D presence in Seoul) — Competitive advantage from cooling‑enhanced IPL systems designed for painless experiences, and aggressive digital marketing in Asia-Pacific markets. ( https://www.ulike.com)
-
Cyden Ltd / SmoothSkin (Swansea, UK) — Focused IPL product portfolio engineered for consumer adoption and broad retail distribution. ( https://www.smoothskin.com)
-
Remington (USA; owned by Spectrum Brands) — Longstanding consumer grooming brand presence with IPL product lineups targeting mainstream retail. ( https://www.remingtonproducts.com)
-
Silk’n (Home Skinovations; Israel) — Developer of IPL and alternative light-based at-home devices emphasizing compact design and price accessibility. ( https://silkn.com)
Collectively, the market shows a moderate level of concentration: the top three firms account for roughly one-third of the market, while the leading five capture close to half. That structure creates both defensive imperatives for incumbents and acquisition or niche‑opportunity pathways for challengers.
Strategic playbook for 2026: five concrete moves
-
Embed regulatory planning in product development: Allocate budget to preclinical testing and 510(k)-or-equivalent documentation early. First-to-market clearances for safety-enhancing design features (e.g., active cooling, skin-tone sensing) translate to durable shelf advantage.
-
Prioritize channel segmentation and digital-first go-to-market: E-commerce continues to be a dominant acquisition channel; however, hybrid strategies that blend online education, subscription consumables, and limited experiential retail create higher lifetime value.
-
Design for cost without diluting trust: Modular product platforms reduce SKUs and lower inventory risk. Standardize electronics across models; differentiate via software, attachments, and service.
-
Pursue tactical M&A and partnership plays: With moderate concentration, bolt-on acquisitions can deliver rapid access to geographic or technology niches. Consider partnerships with dermatology clinics and telehealth platforms to create hybrid care-to-consumer funnels.
-
Operational resilience and component strategy: Hedge exposure to commodity cycles via long-term supplier contracts, early component qualifying, and by exploring alternative materials or assembly geographies that preserve regulatory compliance.
What PW Consulting’s full report delivers (highly practical content)
This release is an executive preview. The complete report is an operational toolkit designed for 2026 decision-makers and includes:
-
Proprietary demand models (historical 2020–2025 and forecast 2026–2032) with scenario analytics to stress-test investment cases;
-
Segment-level playbooks across region, technology, and channel (note: granular segment data withheld in this preview to protect proprietary modeling and to direct stakeholders to the full report);
-
Regulatory pathway matrices and step-by-step 510(k) preparation checklists for teams planning U.S. launches;
-
Commercialization templates: sample launch plans, promotional mixes, and SKU rationalization frameworks tailored to different buyer personas;
-
Supplier risk heatmaps, BOM cost scenarios, and sourcing playbooks to preserve margins under raw material inflation;
-
Competitive benchmarking with strategic implications—detailed profiles, go-to-market tactics, and M&A targets;
-
Scorecards and KPIs for performance tracking post-launch—adoption metrics, unit economics, and churn drivers for subscription models.
Call to action
For senior leaders and product teams mapping 2026 strategy, the full PW Consulting report transforms high-level industry trends into executable programs. If your board is aiming to position for accelerated growth, mitigate regulatory and supply risks, and capture outsized share within the next 18 months, the full dossier contains the segmented forecasts, playbooks, and vendor-level intelligence necessary to move from intent to impact.
Contact PW Consulting to access the complete report and to schedule a strategy briefing. Our analysts will walk your leadership team through tailored scenario planning that uses the report’s proprietary models to quantify investment choices, prioritize markets, and sequence product and regulatory milestones for 2026 execution.
For detailed analysis of this topic, please visit the official page: At Home Hair Removal Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bipolar Laparoscopic Forceps Market Reaches USD 825.5 Million in 2025, Signaling Robust Growth
By pmarketresearch, 2026-07-06
Bipolar Laparoscopic Forceps Market — Strategic Preview for 2026 Decision-Making
Executive Summary
PW Consulting’s latest market research on the Bipolar Laparoscopic Forceps market provides a focused, decision-oriented briefing for executives planning moves in 2026. The global market has expanded steadily through the first half of the decade, and our analysis quantifies a clear growth trajectory underpinned by clinical adoption, device innovation, and material/regulatory shifts. While this release intentionally withholds detailed subsegment figures to preserve the full-service value of the report, it demonstrates the strategic lines of sight leaders need to prioritize in the coming 12–18 months.
Bipolar Laparoscopic Forceps Market
Market Snapshot (macro)
Using 2025 as the base year, PW Consulting measures the global Bipolar Laparoscopic Forceps market in USD Million and models performance across a 2026–2032 forecast period. The market recorded robust growth from the start of the decade and reached a significant milestone in the base year. Our forecast translates into a compound annual growth rate (CAGR) of 6.15% for the period ahead, reflecting steady demand from hospitals and ambulatory surgery centers, continued preference for minimally invasive procedures, and product refresh cycles driven by clinical and environmental priorities.
Bipolar Laparoscopic Forceps Market
Key headline figures (presented at the aggregate level) underscore predictable expansion and the size of the opportunity for equipment manufacturers, distributors, and private equity participants looking to enter or scale within the segment. For access to the complete time-series tables and downloadable datasets, consult the full report on the PW Consulting site.
Bipolar Laparoscopic Forceps Market
What the Report Contains — Practical, Actionable Deliverables
- Proprietary market model calibrated to manufacturer sell‑through, hospital procurement cycles, and device replacement rates — designed for scenario analysis across 2026 budget cycles.
- End‑user intelligence: synthesis of hospital procurement criteria, preference drivers (durability, ergonomics, compatibility with energy platforms), and sterilization/cycle cost considerations.
- Regulatory and reimbursement compendium: device classification roadmap, key compliance checkpoints for product updates, and practical guidance on coding environments relevant to laparoscopic bipolar coagulation.
- Commercial playbooks: go‑to‑market options for OEMs, value propositions for distributors, bundle/consumable approaches for energy-platform vendors, and tender management templates for supply agreements.
- Supply chain and manufacturing risk matrix: vulnerability scoring for contract manufacturing locations, single‑sourcing exposure, and recommendations for nearshoring and dual‑sourcing strategies.
- Environmental and materials guidance: assessment of PVC‑free disposable solutions, life‑cycle tradeoffs of disposable vs. reusable instruments, and hospital sustainability procurement levers.
- Scenario planning tools: three pathway scenarios (base, accelerated adoption, and constrained procurement) with operating assumptions to stress test investment decisions.
Market Dynamics — Drivers, Frictions, and Inflection Points
- Clinical adoption and procedure mix: Continued migration to minimally invasive approaches sustains baseline demand, while pockets of procedure-specific innovation (instrument multifunctionality, integrated irrigation) create incremental replacement cycles.
- Regulatory and reprocessing burden: Reusable laparoscopic bipolar forceps require rigorous cleaning, inspection, and validated sterilization (gravity displacement, ethylene oxide, hydrogen peroxide plasma systems such as Sterrad, or broad‑spectrum washer‑sterilizers like Steris) in accordance with manufacturer IFUs. These operational requirements drive hospital TCO calculations and influence preference for disposable alternatives in select settings.
- Materials and sustainability trends: The emergence of PVC‑free disposable forceps — introduced in recent regional rollouts — is reshaping supplier differentiation, especially where environmental purchasing policies are enforced.
- Technology convergence: Compatibility with electrosurgical platforms and energy generators is a competitive lever. Devices optimized for precise coagulation, non‑stick performance, and integrated irrigation are winning clinical preference in high‑volume theatres.
- Market structure: The market shows moderate concentration among leading global OEMs, leaving clear space for specialized entrants and regional champions, particularly those offering localized service, lower capital intensity, or compelling environmental credentials.
Competitive Landscape — Profiles and Strategic Posture
Our report includes a detailed competitive assessment of incumbent and emerging providers. Below is an executive synthesis of the core players covered:
- B. Braun / Aesculap (Melsungen, Germany): Broad portfolio of reusable and single‑use bipolar forceps with recent product introductions emphasizing irrigation and non‑stick coatings. Strengths: deep clinical relationships, service networks, and integrated product ecosystems.
- Medtronic (Dublin, Ireland): Focus on compatibility of bipolar instruments with energy platforms; leverages platform breadth to drive procurement bundling. Strengths: global sales channels and strong presence in hospital purchasing frameworks.
- Karl Storz (Tuttlingen, Germany): Notable for rotating bipolar designs and narrow‑profile offerings for gynecology and general surgery. Strengths: high‑precision engineering and brand recognition among specialty surgeons.
- Boer Medical (Hangzhou, China) and Zhejiang Geyi Medical Instrument (China): Cost‑competitive disposable and reusable lines with increasingly sophisticated manufacturing capabilities. Strengths: scale and cost agility for price‑sensitive markets.
- Advin Health Care (Ahmedabad, India): Regional supplier with emphasis on reusable instruments and cable‑integrated Maryland variants. Strengths: localized manufacturing and distribution, rapid response to tender requirements.
- Purple Surgical (United Kingdom): Differentiates with multifunctional bipolar cutting forceps that integrate dissection, coagulation, and transection. Strengths: niche product innovation and surgeon‑driven design.
Notable recent product moves included the launch of an irrigating disposable bipolar forceps with higher irrigation output and non‑stick features by Aesculap (Oct 2025) and the regional introduction of PVC‑free disposable options by Duomed (July 2024). These developments crystallize two near‑term battlegrounds: performance enhancement (irrigation, non‑stick) and sustainability/material compliance (PVC‑free disposables).
Implications for 2026 Strategy
We translate the above dynamics into six strategic imperatives for market participants planning activity in 2026:
- Prioritize platform compatibility and clinical evidence: Devices that demonstrate superior clinical outcomes (reduced OR time, lower instrument exchange rates) and seamless integration with electrosurgical platforms will command price premiums and preferred formulary positions.
- Optimize the reusable vs. disposable calculus: Hospitals will increasingly quantify sterilization costs, turnaround times, and environmental KPIs. Vendors should arm purchasers with transparent TCO and carbon‑footprint models and offer hybrid supply models (consumables + service).
- Differentiate on materials and sustainability: PVC‑free materials and reduced adhesive chemistries are becoming procurement filters in advanced markets; product roadmaps should include compliance milestones for these materials.
- Invest in service and training: Given the procedural sensitivity of bipolar instruments, structured surgeon and OR‑team training programs — combined with data capture on OR performance — are powerful retention tools for OEMs and distributors.
- Mitigate supply chain concentration risk: With moderate market concentration, agile players that offer guaranteed supply continuity through diversified manufacturing footprints will win tenders during periods of supply stress.
- Scan for M&A and partnership opportunities: Small innovators with differentiated materials, irrigation technologies, or digital OR integrations are attractive targets for incumbents seeking rapid capability acquisition.
How Buyers and Investors Should Use the Report
- Procurement teams: Use the report’s vendor scorecards and TCO calculators to streamline tender specifications and to negotiate bundled energy‑platform contracts.
- Product and R&D leaders: Leverage the clinical preference mapping and sterilization constraint matrix to prioritize design targets and materials choices for 2026 development cycles.
- Private equity and corporate development: Apply the concentration analysis and scenario models to size investment theses, identify consolidation targets, and stress‑test exit multiples under alternate adoption scenarios.
Regulatory and Reimbursement Checklist (Practical)
- Device classification alignment: Laparoscopic manual instruments, including bipolar forceps, are regulated as Class II devices under common regulatory frameworks — ensure documentation aligns with relevant product codes and guidance.
- Sterilization validation: Reusable devices must have validated reprocessing instructions; suppliers should provide validated IFUs for all recommended sterilization modalities.
- Reimbursement awareness: Procedural coding regimes commonly used for laparoscopic sterilization/coagulation should be factored into hospital economic models and budget impact analyses.
Conclusion and Next Steps
For decision-makers preparing capital, product, or M&A moves in 2026, the Bipolar Laparoscopic Forceps market presents a mix of steady organic growth and pockets of disruptive opportunity driven by materials innovation and platform integration. PW Consulting’s full report supplies the granular datasets, regional and application splits, and downloadable models required to finalize commercial plans. This preview has surfaced the strategic levers — sterilization economics, material choices, platform compatibility, and service‑led retention — that are likely to determine winners over the next planning cycle.
Accessing the Full Report
PW Consulting offers the complete research package, including the full time‑series market model, segment‑level forecasts, pricing curves, and supplier scorecards. Because the most commercially sensitive subsegment data are gated to preserve client value, please contact PW Consulting for access to the full dataset and bespoke advisory options tailored to your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Bipolar Laparoscopic Forceps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Ear Wax Removal Drops Market Poised for 4.52% CAGR Through 2032, New Report Finds
By pmarketresearch, 2026-07-06
Ear Wax Removal Drops Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to present a high-level briefing on our latest market research: the Ear Wax Removal Drops Market — an actionable intelligence suite designed to inform C-suite, product heads, and corporate development teams preparing strategic decisions in 2026. This release highlights the report’s most relevant strategic takeaways, underscores the analytical rigor behind our forecasts, and outlines the decisions market participants should prioritize — while reserving the report’s granular tables and proprietary segment-level numbers for subscribers and website access.
Ear Wax Removal Drops Market
Market pulse: growth trajectory and recent inflection
Our model shows the ear wax removal drops market demonstrating steady recovery and mid-single-digit growth after a period of short-term volatility. From an estimated industry size in 2020, the market reached USD 245.0 Million in our base year of 2025. Looking forward, we project compounded expansion through the 2026–2032 forecast horizon at a 4.52% CAGR, taking the market toward approximately USD 334 Million by 2032. Those headline numbers reflect the net impact of consumer behaviour normalization post-pandemic, renewed retail channel investment, and pockets of product innovation.
Ear Wax Removal Drops Market
Importantly, the historical series underlying our baseline reveals non-linear movement: a strong recovery from early-2020s lows, a brief softening in 2024 that corrected into a stronger 2025. These dynamics are symptomatic of a market where consumer access, channel mix, and episodic promotional activity materially influence near-term revenue flows.
Ear Wax Removal Drops Market
Why this matters for 2026 decisions
For executives, the 4.52% CAGR and the market’s rebound to USD 245 Million in 2025 are not merely statistics — they are inputs into capital allocation, product roadmaps, and M&A screening. Specifically:
- Portfolio prioritization: Firms must weigh incremental investment in incremental product variants (e.g., comfort, sensitivity, dual-action formulas) against broader opportunities in adjacent ear-care categories.
- Channel strategy: As omni-channel retail continues to mature, firms need granular customer-acquisition economics to determine whether to prioritize direct-to-consumer digital channels, reinforced retail shelf placement, or partnerships with clinical service providers.
- M&A and partnerships: The market’s moderate concentration profile signals attractive bolt-on and capability-acquisition targets for mid-sized players seeking scale or distribution leverage.
Competitive landscape — who matters and why
The market is characterized by a mix of established consumer-health brands, clinically oriented DTC players, private-label suppliers and specialized medical-device adjunct partners. Our competitive map highlights several strategic archetypes rather than ranking by headline share alone:
- Legacy consumer-health incumbents: These firms leverage strong retail distribution, recognizable brands and OTC category expertise to defend shelf presence and pricing.
- Clinically anchored entrants: Companies with clinician outreach and doctor-recommended positioning focus on clinical differentiation and bundled care kits that target pre-irrigation and patient-managed care use cases.
- Value/generic suppliers: A robust generic supply chain supports price-sensitive channels and distributor-led programs that can compress margins but expand volume.
- Adjunct-device and system partners: Producers of ear irrigation systems and complementary devices create cross-sell opportunities for drops targeted at pre-irrigation softening.
Representative names we examine in-depth include major brand owners known for carbamide peroxide-based OTC solutions, a clinician-oriented DTC company with rapid product-line extension in 2026, several specialist ear-health firms with combined product-and-device plays, and manufacturers of private-label generics. Our report provides strategic profiles, cross-comparative matrices of capabilities, and a short list of high-priority M&A targets based on capability gaps and distribution reach.
Regulatory and formulation dynamics — a functional roadmap
At the active-ingredient level, carbamide peroxide (commonly used at a clinically supported strength) remains the dominant chemistry for ear wax softening, acting by releasing oxygen to disrupt cerumen structure. Regulators treat many of these formulations as OTC monograph products in key markets; this continuity reduces regulatory uncertainty but requires careful label and claim management if companies pursue new efficacy or symptom-specific claims.
From a go-to-market perspective, this regulatory stability favors fast-to-market extensions and low-friction line innovations. However, any shift toward new active chemistries, combination claims (e.g., analgesic adjuncts), or device-drug combination products will require early regulatory engagement and possibly additional clinical substantiation.
Supply chain and raw material risk
Active pharmaceutical ingredients and sterile filling capacity are the two levers we identify as most likely to constrain near-term scalability. Although carbamide peroxide is widely used, periodic supply tightness, raw-material cost volatility and the need for specialized filling to maintain product stability can create pinch-points. Our recommended mitigants include dual-sourcing agreements, contracted fill-slot capacity, and strategic inventory policies tuned to promotional calendars.
Innovation hotspots and commercial playbooks
Based on primary interviews and our demand-model sensitivity analysis, three innovation themes will disproportionately influence winners in 2026–2028:
- Clinical differentiation: Evidence-based claims and clinician endorsements create durable premium positioning — particularly for products bundled in pre-irrigation or home-care kits.
- Experience design: Packaging, applicator ergonomics, and consumer instructions materially affect repeat use and referral behavior in OTC categories.
- Channel-native formats: Subscription and DTC bundles (including trial kits with device cross-sells) raise lifetime-value metrics and reduce dependence on promotional retail cycles.
For incumbents, the near-term playbook is to combine defensive SKU rationalization with selective innovation focused on convenience and evidence. For challengers, aggressive clinical investment and targeted digital acquisition can deliver disproportionate traction without the expense of broad retail rollouts.
Market concentration & competitive posture
Our concentration analysis indicates the market is moderately consolidated: the top three firms account for a material, but not dominant, portion of market value, and the top five increase that concentration meaningfully. This structure creates room for both brand incumbents to protect market share and for agile challengers to capture niche or channel-specific growth. The consequence for strategy teams is clear — scale matters for trade negotiation, but nimbleness and clinical legitimacy matter for growth.
What our report contains — practical tools for 2026 execution
PW Consulting’s full report is explicitly designed for strategic action. Highlights include:
- A transparent market model (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario sweeps that stress-test channel shifts, pricing pressure, and clinical adoption rates.
- Product- and channel-level growth drivers with playbooks for retail, e-commerce, and clinical channels — including CAC/LTV benchmarks and promotional elasticity assumptions.
- M&A scorecards and a prioritized shortlist of targets by strategic fit (distribution, clinical evidence, manufacturing capability).
- Regulatory impact matrix and suggested labeling strategies consistent with OTC monograph guidelines in major markets.
- Supply-chain resilience templates with recommended sourcing options, contract-fill KPIs, and inventory policy benchmarks calibrated to promotional frequency.
- Commercial launch blueprints: go-to-market timelines, pilot metrics, digital acquisition cohorts, and sample messaging frameworks.
Each module contains executable templates — from detailed financial model inputs to clinician outreach scripts and packaging heuristics — enabling business teams to convert insight into 90–180 day action plans.
Strategic recommendations for 2026 planning
- Prioritize clinician-endorsed product extensions that can be marketed through both professional and retail channels; incremental pricing power follows credible clinical claims.
- De-risk production with dual sourcing and strategic fill contracts; incorporate raw-material hedges into supplier agreements where feasible.
- Accelerate DTC pilots that bundle product and experience (e.g., starter kits with clear instructions and device cross-sell) to boost customer lifetime value and gather first-party usage data.
- Target bolt-on M&A to close distribution or formulation gaps rather than to chase small, unscalable standalone revenue pools.
- Allocate measurable R&D spend to user-experience improvements and packaging innovations that improve adherence and repeat purchase.
Final note — why our report is strategically valuable
In a market that is stable but competitive, the difference between marginal and material returns often lies in preparation: understanding channel economics, regulatory boundary conditions, and where clinical proof converts into pricing power. PW Consulting’s Ear Wax Removal Drops Market report synthesizes historical performance, forward-looking scenario modeling, competitive landscaping and practical playbooks to enable confident, evidence-based decision-making in 2026.
To preserve the value of our proprietary segmentation tables, granular regional breakdowns and the full set of downloadable forecasting models, we have intentionally kept this briefing high-level. For complete data tables, split-by-channel and split-by-type forecasts, company scorecards, and the full suite of strategic templates, please visit our report page to purchase or request a briefing.
For detailed analysis of this topic, please visit the official page: Ear Wax Removal Drops Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bronchiolitis Obliterans Syndrome Market Poised to Grow at a 6.5% CAGR, Unlocking New Opportunities
By pmarketresearch, 2026-07-06
Bronchiolitis Obliterans Syndrome Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As the clinical and commercial landscape around Bronchiolitis Obliterans Syndrome (BOS) accelerates toward potential first-in-class therapies, PW Consulting presents a high-level synthesis of strategic implications extracted from our full market research report. This preview is designed to orient executive decision-making in 2026: where to allocate R&D capital, how to structure clinical and reimbursement strategies, and which competitive moves are most likely to determine market leadership. For decision-makers who require the full segmentation datasets, forecast tables, and transaction-ready financial models, the complete report is available on our website.
Bronchiolitis Obliterans Syndrome Market
Market trajectory: a compact macro snapshot
BOS is moving from a largely supportive-care market into one defined by targeted, disease-modifying interventions. Our modeling — based on a 2025 base year and a forecast window to 2032 — shows the global BOS therapeutics market growing from approximately USD 385.0 Million in 2025 to roughly USD 598.31 Million by 2032, representing a compound annual growth rate (CAGR) of about 6.5% over the forecast period. This trajectory reflects the confluence of several forces: an active clinical pipeline, increasing adoption drivers tied to improved post-transplant survival, and an emergent commercial readiness among a small set of specialized biopharma players.
Bronchiolitis Obliterans Syndrome Market
Why 2026 is a pivotal planning horizon
- Near-term clinical inflection points: Several late-stage and mid-stage assets are expected to report pivotal readouts or interim data over the next 12–24 months. These data will materially re-shape clinical practice guidelines and payer perceptions.
- Regulatory momentum: With no FDA-approved therapies currently labeled specifically for BOS, the pathway to approval for targeted inhaled immunosuppressants and novel anti-fibrotic/inflammatory agents is both an opportunity and a regulatory challenge. Orphan and expedited pathways increase the probability of earlier market entry but heighten payer scrutiny on comparative and real-world value.
- Commercial readiness versus fragmentation: Although a limited number of companies are driving innovation, market concentration remains moderate — creating a window for focused entrants to capture clinically meaningful share if they deliver differentiated outcomes and credible value propositions.
Competitive landscape: positioning and implications
Our research highlights a compact competitive set with differentiated strategies that will determine therapeutic adoption curves and partnership opportunities.
Bronchiolitis Obliterans Syndrome Market
- Zambon (Milan): Advancing an inhaled, liposomal cyclosporine A candidate through pivotal Phase 3 programs positions Zambon to be the first mover if regulatory and reimbursement hurdles are cleared. The company’s development pathway maximizes the clinical logic for local delivery to the lung while leveraging orphan/fast-track designations to expedite review.
- Quince Therapeutics (South San Francisco): The May 2026 acquisition of OrphAI and an associated financing package to advance inhaled sirolimus underscores a strategy of consolidation and acceleration. Quince’s mid-stage program, with expected data in the near-to-medium term, makes it a likely strategic partner or acquisition target for larger respiratory players seeking differentiated inhaled mTOR modulation.
- Incyte Corporation (Wilmington, DE): Clinical evidence from a multicenter Phase 2 program suggests JAK inhibition may have a role in post-HCT BOS. These data expand the therapeutic rationale beyond inhaled local therapies into systemic immune-modulatory approaches for distinct patient subpopulations.
- Genentech (Roche) and GSK: Both companies are strategically active in immuno-inflammatory and anti-fibrotic respiratory research. Their participation — whether through internal development or targeted partnerships — increases the likelihood of combination strategies and raises the bar for clinical differentiation.
Strategic takeaway: industry moves in 2026 will be characterized by clinical readouts triggering alliance activity. Companies with near-term data should prioritize payer engagement and real-world evidence (RWE) frameworks now, while companies without imminent readouts should evaluate bolt-on acquisitions or licensing to accelerate clinic-to-commercial timelines.
Regulatory and reimbursement dynamics to anticipate
- Regulatory designations are necessary but not sufficient: Orphan and expedited designations can accelerate approval, but post-approval coverage and reimbursement will hinge on robust evidence that demonstrates durable improvements in lung function, reduction in exacerbations, and downstream cost offsets related to reduced hospitalizations and lung retransplantation rates.
- Payer focus on population definition and real-world effectiveness: Payers will press manufacturers to define the patient populations that derive the highest incremental benefit (e.g., post-lung transplant vs. post-HCT) and will demand pragmatic evidence from registries and claims-based studies.
- Economic burden as an engagement lever: The lifetime and annualized cost burden of BOS are substantial and can be mobilized to support value-based contracting. Expect an appetite for outcomes-based agreements in major markets, especially where a therapy alters the natural history post-transplant.
Report deliverables: what executives will find inside
PW Consulting’s full Bronchiolitis Obliterans Syndrome report consolidates clinical, commercial, and financial intelligence into operational tools for 2026 planning. Key deliverables include:
- Market sizing and scenario-driven forecasts to 2032 (base year 2025), including sensitivity analyses under alternative clinical uptake and pricing assumptions.
- Granular disease segmentation and patient-flow models that link transplant volumes, incidence rates, and therapeutic adoption curves to revenue projections.
- Comprehensive pipeline mapping with triage-level assessments of mechanism-of-action risk, development timelines, and competitive overlap.
- Regulatory and HTA playbooks tailored to major jurisdictional archetypes (emerging vs. mature markets), including dossier priorities and evidence generation roadmaps.
- Commercial go-to-market blueprints: launch sequencing, pricing frameworks, channel strategies, and provider engagement templates.
- M&A and partnership screening: valuations, deal-structuring options, and integration risk checklists tuned to BOS-specific assets.
- Financial models and value-case appendices to support investor presentations, internal capital allocation, and pricing negotiations.
Strategic imperatives for corporate leaders in 2026
- Prioritize rapid but rigorous evidence development: Design adaptive trials, integrate patient-reported outcomes, and invest in registry partnerships now to ensure market access evidence is available at launch.
- Differentiate clinically and economically: Demonstrable impacts on long-term lung function decline, retransplantation rates, or hospitalization days will be the primary commercial differentiators. Plan head-to-head or pragmatic comparative studies where feasible.
- Engage payers early with modeled value propositions: Use payer-focused economic models showing total cost of care reductions and consider staged risk-sharing arrangements tied to clinically meaningful endpoints.
- Consider strategic M&A and alliance plays: Mid-sized biotechs with near-term data will be attractive partners for large respiratory franchises seeking inhaled delivery technologies and BOS-specific expertise.
- Operationalize manufacturing and distribution for inhaled therapeutics: For inhaled formulations, ensure scalable manufacturing and inhalation-device compatibility; device choice and supply reliability will materially affect uptake among transplant centers.
- Segment commercialization by clinical pathway: Customize sales and medical affairs engagement models to transplant centers, HCT programs, and pulmonology networks, rather than using a one-size-fits-all respiratory sales approach.
Risk factors and mitigation
Key risks that could materially alter the market outlook include disappointing pivotal readouts, unexpected safety signals for systemic immunomodulators, or payer reluctance to reimburse therapies at prices that support developer economics. Mitigants include staged launch strategies, external validation via independent registries, and conditional reimbursement agreements that de-risk payer exposure.
What this means for investors and partners
The BOS market represents a high-value niche with clear clinical need and a concentrated set of pharmaceutical actors. Our concentration analysis indicates a market where a few well-capitalized players could capture disproportionate value if they secure favorable regulatory outcomes and reimbursement. For investors and corporate development teams, the optimal strategy in 2026 is selective, data-driven backing of assets that balance clinical differentiation with pragmatic evidence-generation plans.
Next steps: converting insight into action
PW Consulting’s full report equips leadership teams with the data and tactical playbooks to act decisively in 2026. If your priorities include assessing acquisition targets, designing a reimbursement dossier, or building a launch-ready commercialization plan for a BOS asset, our report provides the granular inputs and executable templates to move from strategy to implementation.
To access the full forecasts, segment-level analyses, and our deal-ready financial models, please visit the PW Consulting report page or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Bronchiolitis Obliterans Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Cone Beam Imaging (CBCT) Market to Surge at an 8.25% CAGR Through 2032
By pmarketresearch, 2026-07-06
Cone Beam Imaging (CBCT) Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new Cone Beam Imaging (CBCT) Market report (base year 2025; forecast period 2026–2032) is designed to be a decision‑grade briefing for executives planning products, investments, and go‑to‑market moves in the year ahead. At the macro level, the global CBCT market was valued at approximately USD 1.85 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 8.25% through 2032, reaching just over USD 3.2 billion by the end of the projection window. These topline dynamics reflect a market that is expanding quickly enough to support new investment and consolidation, but also maturing around a set of technology, regulatory, and reimbursement constraints that will shape winners and losers in 2026 and beyond.
Cone Beam Imaging Cbct Market
Why this report matters for 2026 planning
- Timing of technology transition: 2025–2026 marked a seismic step for software-enabled CBCT workflows. Multiple AI‑enhanced analysis tools received regulatory clearance in late 2025 and early 2026, accelerating clinicians’ ability to extract diagnostic value from 3D data and creating meaningful differentiation opportunities for platform owners.
- Consolidation and concentration: Market concentration is high and rising — the top three vendors account for a majority share of industry revenue, and the top five control nearly four out of five dollars spent. That concentration both raises barriers to entry and creates strategic openings for mid‑market players with narrow, high‑value propositions.
- Capital intensity and buyer mix: Hospitals and multi‑site dental chains remain important purchasers, sustaining demand for higher‑capacity units and integrated service contracts. At the same time, limited comprehensive reimbursement coverage for CBCT procedures in many regions continues to be a brake on volume expansion in outpatient and smaller dental practices.
What is in the report — practical deliverables for 2026 action
This report has been built as an operational playbook rather than a high‑level briefing. It combines primary interviews, vendor financials, installation datasets, and a bottom‑up device build‑out model to produce both strategic insight and executable outputs for commercial teams. Key deliverables include:
Cone Beam Imaging Cbct Market
- Topline market sizing and year‑over‑year market movement (2020–2025 historical plus a 2026–2032 forecast), with scenario pathways for conservative, base, and aggressive adoption curves.
- Supplier and product mapping (device form factors, FOV tiers, imaging resolution, and software ecosystems), with go‑to‑market implications for OEMs and channel partners.
- Competitive profiles and playbooks for leading vendors, emphasizing product differentiation, service economics, and partnership levers.
- Regulatory and reimbursement trackers, including a pragmatic checklist for filing strategies and payer evidence generation to support reimbursement pilots.
- Commercial diligence templates: pricing models, service margin tables, and customer segmentation frameworks for prioritizing sales effort across hospitals, dental chains, and private clinics.
- Investment and M&A screening: value drivers, multiples sensitivity, and a shortlist of capability gaps that should be targeted by acquirers and investors.
To respect the “trailer” principle and to protect our proprietary segmentation work, the report deliberately reserves detailed regional, application, and type breakdown tables for purchasers of the full study. Readers can expect those granular splits and vendor‑level revenue matrices within the full report package.
Cone Beam Imaging Cbct Market
Competitive landscape — who to watch and why
The CBCT vendor ecosystem now blends legacy imaging OEMs with agile specialty players and software innovators. Key firms we profile and benchmark include:
- Dentsply Sirona (Charlotte, NC, USA) — a market incumbent with integrated dental imaging solutions and advanced 3D treatment‑planning software. Strength lies in deep clinical relationships and bundled offerings across consumables and imaging.
- Planmeca Oy (Helsinki, Finland) — known for systems with low‑dose imaging and integrated facial scanning. Recent device introductions targeting North America strengthen its competitive posture in premium channels.
- VATECH Co., Ltd. (Hwaseong‑si, South Korea) — differentiated by auto‑switching and dose‑management features, a strong regional footprint, and competitive manufacturing economics.
- Carestream Dental (Atlanta, GA, USA) — multi‑field‑of‑view platforms with AI features and modular imaging suites targeted at larger dental group practices.
- J. Morita (Kyoto, Japan) and PreXion (Japan) — recognized for high‑resolution imaging and depth in endodontic and radiologic applications.
- Cefla/NewTom (Imola, Italy) — positions that span dental to select medical use cases, emphasizing diagnostic flexibility.
- CurveBeam (USA) — an example of a successful niche player focused on weight‑bearing and extremity CBCT systems, now extending into orthopedic workflows with AI capabilities.
- Asahi Roentgen (Japan) — compact, reliable systems that appeal to space‑constrained clinics.
Alongside hardware suppliers, a new class of software vendors is changing the competitive equation. Notably, several AI companies won regulatory clearances in the 2025–2026 window — examples include 510(k) clearances for AI‑enabled CBCT review platforms and orthodontic analysis tools. These software approvals accelerate product roadmaps for vendors that can quickly integrate validated AI modules into their imaging suites.
Recent regulatory and market events — implications for commercial strategy
- Multiple FDA 510(k) clearances for AI‑enabled CBCT software in 2025–2026 have reduced a key barrier to clinical adoption of automated 3D analysis. Manufacturers and channel partners should treat validated AI as a feature that materially affects purchasing decisions and pricing power.
- New device introductions into North America by established international vendors have intensified competition in higher‑end segments. This increases the importance of service excellence, bundled warranties, and flexible financing to protect margin.
- Reimbursement remains uneven. Until payers adopt structured codes that reflect CBCT’s unique clinical value, adoption in lower‑resource settings will rely on demonstrated ROI in procedural outcomes and practice throughput rather than on fee‑for‑service reimbursement alone.
Strategic implications and 2026 playbook
- For OEMs: Prioritize modular platform strategies that allow rapid integration of third‑party FDA‑cleared AI modules. Differentiate on service and training economics; predictable uptime and validated clinical workflows will be decisive in enterprise tenders.
- For software vendors: Pursue regulatory clearance early, but pair clearance with real‑world evidence from pilot deployments in multi‑site dental chains or hospital radiology departments to accelerate adoption.
- For hospital systems and large dental groups: Implement phased adoption pilots tied to clinical KPIs (implant accuracy, orthodontic planning time, reduction in follow‑up imaging). Use those pilots as the foundation for internal reimbursement and capital allocation plans.
- For investors and acquirers: Target businesses that enhance installed base monetization — service, consumables, analytics subscriptions — and consider tuck‑ins that add AI or workflow software to hardware incumbents to capture higher recurring revenue.
- For distributors: Build financing products and outcome‑based service contracts to address CapEx constraints at smaller clinics. Bundling installation, training, and software subscriptions will increase lifetime customer value.
Risks, monitoring metrics, and scenario levers
Key risks that should be monitored through 2026 include reimbursement policy evolution, the pace of regulatory acceptance for new AI capabilities, and competitive pricing pressure from lower‑cost manufacturers. We recommend tracking a short list of leading indicators on a monthly cadence:
- Rate of FDA 510(k) clearances for CBCT‑related AI and software modules.
- Consolidation activity among top suppliers and resulting shifts in CR3/CR5 concentration.
- Payer announcements and regional reimbursement pilot programs.
- Installation and service backlog data from major hospital systems and dental chains.
Next steps — how PW Consulting supports 2026 execution
PW Consulting’s CBCT market study is intentionally operational: the full report includes the granular regional and application breakdowns, vendor revenue matrices, model inputs, and slide‑ready charts that make the case for board‑level decisions, product roadmaps, and M&A theses. For leadership teams preparing 2026 budgets, the study provides the empirical scaffolding to prioritize initiatives that increase utilization, shorten sales cycles, and extract recurring revenue from installed fleets.
To access the detailed splits, vendor scorecards, and the financial model behind our topline forecasts — or to commission a tailored due‑diligence or go‑to‑market engagement — contact PW Consulting. Our analysts will map the report’s insights into a short, practical action plan tailored to your organization’s strategic horizon.
For detailed analysis of this topic, please visit the official page: Cone Beam Imaging Cbct Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Black Beer Market to Expand at 4.52% CAGR Through 2032
By pmarketresearch, 2026-07-06
Black Beer Market 2026 Briefing: Strategic Imperatives for C-Suites
PW Consulting presents an executive preview of our new Black Beer Market report — a decision-ready, scenario-driven intelligence package designed to inform capital allocation, innovation roadmaps, and M&A scouting through 2026 and beyond. This release outlines the report’s strategic value and highlights the macro dynamics that will shape competitive advantage in dark beer (stout, porter, dark lager and related styles) over the 2026–2032 forecast horizon. In keeping with our “trailer” principle, we surface the analytical framework, headline market trajectory and tactical recommendations while withholding granular segment tables and regional breakdowns to encourage direct access to the full dataset and model files.
Black Beer Market
Headline Market Signals
- Market scale and trajectory: The global black beer market reached an estimated USD 12.5 Billion in our 2025 base year. Our model projects steady expansion across the 2026–2032 forecast window at a compounded growth rate consistent with a multi-year recovery and premiumization trend.
- Compound growth: The 2026–2032 forecast uses a 4.52% CAGR as the central scenario, reflecting a balance between premium craft momentum, on-trade recovery variability and input cost pressure.
- Concentration profile: The category exhibits a moderate-to-high degree of concentration among leading brewers, with the top three and top five firms commanding material shares of the global market (concentration metrics are included in the full report).
- Product innovation: Barrel-aging, limited seasonal variants and cross-category flavor innovations (e.g., coffee, cocoa, nut infusions) remain primary demand drivers for incremental premiumization.
- Channel evolution: On-trade rebalancing and omnichannel off-trade expansion are reshaping go-to-market economics; new-format experiences and premium tap activations are becoming more determinative of brand equity.
Why this Matters for 2026 Planning
2026 is the year many brewers and beverage investors will decide whether to double down on premium dark offerings, optimize supply chains for cost resilience, or pursue M&A to capture growth pockets. The headline market trajectory provides a data-backed foundation for three immediate 2026 decisions:
Black Beer Market
- Portfolio prioritization — which SKUs to scale within stout/porter/dark-lager portfolios to maximize margin capture during premiumization.
- Capex and capacity allocation — where to invest in barrel-aging, packaging, and limited-release production lines that can command higher price realization.
- M&A and partnership targeting — how to use concentration dynamics and company archetypes to build a disciplined acquisition funnel that supports geographic or craft-led expansion.
What the Report Contains — Practical, Actionable Deliverables
The full PW Consulting report is built around pragmatic modules that translate data into executable plans. Key contents include:
Black Beer Market
- Market model and scenarios: An interactive model covering historical performance (2020–2025) and multiple 2026–2032 forecast scenarios (central, conservative, upside) enabling sensitivity testing on price, volume, and channel mix.
- Go-to-market playbooks: Tactical playbooks for on-trade and off-trade rollouts, including promotional cadence, premium tap programs, and retailer negotiation levers calibrated for dark beer economics.
- SKU and portfolio optimization toolkit: Decision matrices and margin impact simulations for SKU rationalization, limited-release programming, and SKU migration from regional to national scale.
- Procurement and input-cost playbook: Hedging strategies, supplier diversification templates, and tactical sourcing options to mitigate barley and malt price volatility.
- Supply-chain stress tests: Scenario-based stress testing for logistics, packaging (glass, cans, keg), and capacity constraints to prioritize resilience investments versus opportunistic growth.
- M&A and partnership library: Valuation benchmarks, integration checklists, and a short-list of acquisition archetypes (craft specialists, barrel-aging facilities, regional distribution platforms) aligned to different strategic intents.
- Consumer and innovation frameworks: Segmentation heuristics, launch calendars for seasonal releases, and idea-to-market timelines drawing on recent successful case studies.
- Regulatory & sustainability heatmap: Compliance considerations for labeling, taxation, and emerging ESG disclosure expectations that affect brand positioning and supply costs.
Competitive Landscape — Who’s Setting the Pace
The competitive fabric of the black beer category is a mix of global incumbents leveraging scale and craft specialists driving product innovation. High-level company archetypes and tactical positioning are covered in the report; notable profiles include:
- Diageo (Guinness) — The archetypal global stout leader, with a dominant flagship draught offering and a strategy centered on geographic scale, brew-house modernization and experiential marketing.
- Anheuser-Busch InBev — Leveraging craft acquisitions and sub-brands (including Goose Island) to participate in high-margin barrel-aged and specialty stout subsegments while using distribution depth to scale seasonal launches.
- Sierra Nevada & Brooklyn Brewery — Craft-oriented portfolios emphasizing quality ingredients and limited-release programs that sustain premium pricing and strong taproom economics.
- Heineken & Carlsberg — Global brewers with strategic craft investments and dark-beer extensions that aim to capture incremental share without disrupting core lager portfolios.
Recent category activity underscores the direction of competitive play: in mid-2025 Goose Island refreshed its Bourbon County Stout family with new barrel-aged variants, and late-2025 saw a wave of craft seasonal imperial stouts introduced by regional brewers. These moves illustrate two concurrent dynamics — incumbents scaling craft equity through brand extensions and craft brewers leaning into limited drops as a primary growth engine.
Supply-Chain and Input-Cost Dynamics — The Procurement Imperative
Raw-material and malting-barley dynamics are central to 2026 planning. Our synthesis of market inputs highlights three facts for procurement teams:
- Price environment: North American barley prices and global malting-barley indices softened through 2025; current benchmarks indicate a more balanced market in early 2026 versus the recent volatile cycles.
- Usage shift: US malting-barley use has been trending lower amid structural declines in some beer volumes, altering supplier bargaining dynamics and seasonal availability.
- Operational risk: Barrel-aging and high adjunct recipes materially increase input-cost per SKU and extend inventory cycles — requiring capital and working-capital planning distinct from standard lager production.
Recommended procurement actions in the report include blended forward contracting, multi-origin sourcing playbooks, and a margin-protection matrix that ties input choices to SKU pricing levers. These are presented as executable templates ready for finance and procurement teams to adopt in 2026.
Strategic Recommendations for 2026 Decision-Making
- Prioritize premium core growth: Concentrate investment on high-margin stout and porter SKUs with proven taproom traction and limited-release halo effects; redeploy capital from underperforming mass-dark SKUs.
- Invest selectively in barrel infrastructure: For brewers targeting premiumization, allocate capex to controlled barrel-aging capacity and partnering models (co-aging/co-pack) rather than modular short-term leases.
- Design channel-specific pricing architectures: Differentiate pricing and packaging between on-trade premium experiences and off-trade convenience formats to protect margin while expanding reach.
- Use M&A to fill capability gaps: Target acquisitions that provide either premium brewing expertise or distribution access rather than purely volume-driven consolidation plays.
- Hedge input exposure pragmatically: Implement partial forward contracts and supplier diversification to smooth input-cost volatility while retaining upside to price recovery.
- Embed sustainability into product narratives: Use raw-material traceability and low-impact packaging as premium differentiators that justify price premiums to increasingly eco-aware consumers.
- Operationalize limited releases: Treat seasonal and barrel-aged drops as full P&L initiatives (forecasting, marketing, and logistics) to avoid margin leakage from ad-hoc launches.
Methodology Snapshot & Accessing the Full Report
PW Consulting’s Black Beer Market report uses 2025 as the base year with historical analysis spanning 2020–2025 and forward projections through 2032. The central forecast adopts a 4.52% CAGR across the 2026–2032 window; revenue figures are expressed in USD (Billion). The full publication includes the complete time-series model, disaggregated regional and channel splits, competitor scorecards, M&A candidate lists, and downloadable Excel models for bespoke scenario analysis.
For corporate strategy teams, investor groups, and operating executives, this report is intended as both a diagnostic and an operational playbook: identify where to invest, what to divest, and how to structure deals in a market that is expanding in absolute terms while consolidating at the top.
To obtain the full market dataset, model files, and a tailored briefing from PW Consulting’s beverage practice, please visit our website or contact our industry leads for a private walkthrough. The full report is the only place where the granular segment-level shares, regional splits and company-level financial benchmarks are published in full.
For detailed analysis of this topic, please visit the official page: Black Beer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Disposable Alcohol Wipes Market to Expand at a 5.48% CAGR Through 2032
By pmarketresearch, 2026-07-06
Disposable Alcohol Wipes Market: Strategic Outlook for 2026 — PW Consulting Industry Brief
PW Consulting’s latest market research note on the Disposable Alcohol Wipes market synthesizes five years of historical data (2020–2025) with a rigorous forecast through 2032. The market demonstrated a pronounced retracement from pandemic-era peaks—moving from an industry high in 2020 before contracting in 2021–2023 and recovering into 2024–2025—reaching an estimated total market size of USD 722.9 Million in our 2025 base year. Under our central scenario the market resumes steady growth across 2026–2032 at a compound annual growth rate (CAGR) of 5.48%, with the market expanding to roughly USD 1,050.2 Million by 2032. For executives preparing 2026 strategy, these topline dynamics are the starting point for reshaping supply chains, product portfolios, regulatory posture, and M&A agendas.
Disposable Alcohol Wipes Market
What this brief delivers for 2026 decision-makers
-
Actionable context for immediate priorities: inventory strategy, raw material risk mitigation, and short-cycle product launches that respond to institutional procurement cycles.
Disposable Alcohol Wipes Market -
A framework to prioritize R&D and sustainability investments that align with buyer willingness-to-pay and regulatory trajectories.
Disposable Alcohol Wipes Market -
Competitive positioning intelligence across incumbent manufacturers, contract producers, distributors, and new entrants to inform partnership, private-label, and acquisition decisions.
-
A concise set of KPIs and early-warning indicators designed to convert market-level forecasts into boardroom-ready operating targets for 2026.
Why the 2026 planning horizon is pivotal
Two converging forces make 2026 a hinge year: first, macro recovery of demand as healthcare and commercial budgets normalize post-crisis, and second, persistent cost and regulatory pressures that will re-shape margins and product claims. Our historical series—an industry peak in 2020, contraction in subsequent years, followed by recovery to the 2025 base—illustrates that winners will be those who translate topline growth into durable margin gains by 2026, not those who simply chase volume.
Report scope and practical contents
-
Market sizing and forecasting model (2020–2032) with scenario variants (base, downside, upside) and sensitivity to raw-material indices.
-
Go-to-market playbooks for four commercial archetypes—pure-play branded manufacturers, contract manufacturers, distributors/private-label operators, and mixed-model incumbents—complete with channel economics and pricing matrices.
-
Supply-chain mapping and supplier risk heatmaps that quantify exposure to alcohol feedstocks and polymer substrates, plus recommended sourcing contingencies.
-
Regulatory and quality-compliance checklists tailored to EPA and FDA pathways for disinfectant and prep-pad products, and a waste-disposal compliance primer.
-
Manufacturing diagnostics and capital-expenditure benchmarks to support capacity expansion or conversion decisions (e.g., switch to biodegradable substrates).
-
Competitive scorecards, M&A screening templates, and a prioritized shortlist of acquisition targets and contract-manufacturing partners (detailed listings reserved for the full report).
Competitive landscape — what incumbents and challengers are doing
The market is characterized by a mix of legacy brand owners, healthcare-specialist manufacturers, industrial suppliers, and agile contract manufacturers. Market concentration is moderate: the top three players account for roughly 38% of industry revenue, while the top five account for just over half. This structure supports both competition and selective consolidation opportunities.
-
Nice-Pak Products, Inc. — With a history of product innovation and hospital-grade offerings, Nice-Pak remains a reference point for product reliability. Their strength is in established manufacturing footprints and institutional relationships; the strategic consideration for rivals is that Nice-Pak can mobilize scale-based cost defenses quickly.
-
PDI Healthcare — A specialist in infection-prevention, PDI’s clinical credibility and focus on germicidal formulations make it a primary supplier for healthcare procurement teams. Competitors should anticipate continued demand from regulated clinical settings and consider clinical-evidence investments to compete effectively.
-
Clorox — Leveraging powerful consumer and institutional brands, Clorox combines marketing reach with institutional sales channels. Their ability to bridge retail and pro channels pressures mid-market firms to clarify channel strategies and differentiation.
-
Ecolab — Ecolab’s recent launch of a 100% plastic-free, EPA-registered disinfectant wipe with 1-minute hospital disinfection demonstrates how sustainability and performance claims can coexist. Expect greater product differentiation around biodegradability and reduced plastic use.
-
Kimberly-Clark, 3M, Cardinal Health — These companies emphasize critical-cleaning, lab-use, and distribution scale. Their advantage is a portfolio-led cross-sell into existing healthcare and industrial customers.
-
Contract manufacturers and OEMs (e.g., Diamond Wipes International; Zhejiang-based manufacturers) — They continue to shape private-label economics and speed-to-market for new formulations. For buyers, contract partners are pivotal for rapid SKU expansion or regional supply security.
Recent industry events underscore these dynamics: Ecolab’s July 2024 launch of a degradable, fast-acting disinfectant wipe signals a growing premium for sustainability-performance hybrids; several suppliers introduced natural-ingredient lines in 2025 aimed at travel and personal-care channels; and a September 2025 FDA Class II recall of certain prep pads highlighted continuing regulatory and quality-compliance vulnerabilities for some manufacturers. These developments are instructive for 2026 planning: differential product claims will drive premiumization, while regulatory missteps will be costly reputationally and financially.
Key market dynamics and risk vectors
-
Raw-material volatility: Isopropyl alcohol (IPA) and other alcohol feedstocks represent the single largest input cost exposure in 2025; industry data show IPA accounting for a material majority share of raw-material outlays for alcohol wipes, with price swings of 15–25% year-over-year in recent cycles. Non-woven substrates—often polypropylene/polyester blends—remain the next-largest cost bucket and are sensitive to petrochemical price moves and supply-chain disruptions.
-
Regulatory complexity: EPA registration for disinfectant claims and FDA oversight for certain prep-pad and antiseptic products impose distinct development and labeling pathways. Disposal rules for solvent-contaminated wipes add compliance costs for customers and producers.
-
Trade and tariff considerations: Imports from key manufacturing hubs face duty and classification regimes that affect landed cost; for example, certain disinfectant wipes are classified under specific HTS codes with general duty structures that should be built into sourcing economics.
-
Quality and cGMP risk: Recalls and regulatory actions are leading indicators of potential demand shocks and buyer reallocation—companies should audit quality systems and supplier controls as priority investments for 2026.
-
Innovation vectors: Rapid contact-time disinfection, plastic-free substrates, bio-based alcohols, and single-dose sterile formats are converging into distinct value propositions across healthcare, commercial cleaning, and personal-care channels.
Strategic playbook for 2026 (prioritized and executable)
-
Near term (0–12 months): Implement raw-material hedging and dual-sourcing for IPA and non-woven substrates; execute a focused regulatory compliance audit; launch 1–2 SKU pilots that emphasize either faster kill time or demonstrable sustainability credentials; refresh commercial terms with large distributors to protect margin.
-
Medium term (12–36 months): Invest selectively in substrate-conversion lines (biodegradable or lower-plastic content); pursue tuck-in acquisitions to fill capability gaps (contract manufacturing, specialized formulations, or regional distribution); digitize customer channels to capture higher-margin DTC and specialist procurement segments.
-
Operational KPIs to monitor: raw-material price index vs. cost pass-through rate, SKU-level margin by channel, quality incident frequency, share of revenue from sustainability-labelled SKUs, and time-to-EPA/FDA approval for new claims.
-
M&A and partnership filters: prioritize targets with clean quality histories, backward-integration potential for substrates or alcohol supply, and assets that accelerate entry into attitudinally premium segments (e.g., healthcare-certified biodegradable wipes).
How PW Consulting helps
The full PW Consulting report contains the granular datasets, supplier scorecards, and financial models required to convert the strategic playbook above into executable 2026 operating plans. It includes concealed subsegment splits, region/application level KPIs, and a ranked list of short- and medium-term M&A targets that are excluded from this brief by design—our “trailer” approach is intended to surface the insight needed to act quickly while directing readers who require transaction-grade detail to the full report.
For procurement heads, R&D leaders, corporate development teams, and investment committees preparing budgets and deal pipelines for 2026, our analysis translates market growth (CAGR 5.48% through 2032) and structural risk into a prioritized set of choices: protect margin with disciplined sourcing; win share through certified performance and sustainability claims; and use M&A or capacity investments to lock in advantaged cost positions.
To access the full dataset, the proprietary segmentation tables, and the comprehensive M&A shortlist that underpin the strategic recommendations above, please visit the PW Consulting report landing page or contact your PW advisor for an executive briefing and data license.
For detailed analysis of this topic, please visit the official page: Disposable Alcohol Wipes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: K–12 Education Furniture Market to Grow at a 5.25% CAGR, Reaching USD 7.44 Billion by 2032
By pmarketresearch, 2026-07-06
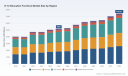
K–12 Education Furniture Market: Strategic Outlook to 2032 — A PW Consulting Preview
PW Consulting today publishes an executive preview of our forthcoming K–12 Education Furniture Market report, a practice-oriented intelligence product designed to guide school systems, manufacturers, investors, and procurement teams as they set budgets and strategies for 2026 and beyond. The sector is at an inflection point: after recovering from mid‑decade shocks to materials and global supply chains, the global K–12 education furniture market is estimated at USD 5,200.0 Million in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of 5.25% through our forecast window (2026–2032), with a 2032 market projection in the neighborhood of USD 7,439.9 Million.
K 12 Education Furniture Market
Why this preview matters for 2026 decision cycles
- Capital planning: School district capital expenditure cycles and multi‑year renovation programs initiated in 2026 will lock in furniture specifications for the rest of the decade. Our analysis highlights timing windows and procurement levers that materially affect total cost of ownership (TCO).
- Supply‑side risk management: Raw material volatility and regulatory shifts in 2025–2026 increase the value of hedged sourcing strategies and near‑shoring options. Manufacturers and buyers who act early can protect margins and avoid late‑cycle price escalations.
- Product portfolio alignment: Pedagogical trends toward collaborative, flexible, and inclusive learning spaces are translating into quantifiable demand shifts across product types and classroom typologies—an insight we describe in operational terms to inform 2026 R&D and SKUs rationalization.
Market trajectory at a glance (operational intelligence)
Historical tracking across 2020–2025 shows recovery and renewed momentum following pandemic-era dislocation. The market size rose from the low‑to‑mid‑thousands in 2020 and reached USD 5,200.0 Million in 2025. From a strategic perspective, a sustained mid‑single digit CAGR (5.25%) to 2032 implies steady expansion, but not runaway growth—an environment that rewards operational efficiency, targeted innovation, and disciplined commercial execution rather than broad, undifferentiated capacity expansion.
K 12 Education Furniture Market
Two practical implications follow: first, incremental share can be captured through differentiated specification (durability, ergonomics, low‑VOC materials, modularity); second, disciplined pricing and service contracts (maintenance, warranty, replacement cycles) will be central to securing long‑term institutional buyers.
K 12 Education Furniture Market
What PW Consulting’s full report delivers (hands‑on tools for 2026)
- Methodology and transparent market model: our sizing framework decomposes demand drivers (new construction, replacement cycles, refurbishment), procurement cadence, and life‑cycle assumptions so clients can re‑run scenarios against their own inputs.
- Practical buyer personas and procurement playbooks: procurement templates for public and private K–12 buyers, including tender language, specification checklists (structural integrity, low VOC, fire safety, ergonomics), and scoring matrices to evaluate bids beyond sticker price.
- Supply chain heatmap and cost drivers: a supplier‑level risk map that highlights exposure to key materials (steel, aluminum, softwood lumber) and logistics chokepoints, with mitigation tactics such as alternate material designs and inventory strategies.
- Commercial playbook for manufacturers and distributors: go‑to‑market segmentation, channel economics, service offering design (installation, repair, lifecycle programs), and digital tools for order management and asset tracking.
- M&A and partnership leads: identification of attractive consolidation targets and strategic partnerships aligned to modular furniture, ergonomic innovation, and regional manufacturing footprints—scored by strategic fit, integration complexity, and expected payback horizons.
- Scenario analysis: three practical scenarios (baseline growth, cost‑inflation stress, and demand‑acceleration driven by education reform) enabling rapid financial and operational sensitivity testing for boardrooms and investment committees.
Competitive landscape — who to watch and what they reveal
The sector remains moderately consolidated: the top three companies account for a significant minority of the market, while the top five increase that share to a larger but still non‑dominant proportion—an axis that supports both incumbent advantage and emerging challenger opportunities. Key players to monitor include legacy U.S. manufacturers with strong K–12 pedigrees and design‑led firms that have translated workplace ergonomics into classroom solutions.
- Virco Manufacturing Corporation — a long‑standing U.S. manufacturer focusing on durable, education‑grade desks, chairs, tables and storage solutions. Their trade show presence and product refresh cadence remain important demand signals.
- KI Furniture (Krueger International) — increasingly active in capacity and technology investment. Recent facility expansion and new seating technology rolled out in early 2026 indicate a bet on higher‑value, differentiated seating systems and campus‑grade outdoor collections.
- Artcobell, Paragon, Allied School Furniture, Smith System, VS America, and HON — each offers complementary strengths in design, domestic manufacturing, or channel reach; their product roadmaps and procurement partnerships influence specification trends across districts.
- Herman Miller and School Specialty — bring research‑based design and integrated procurement capabilities that appeal to districts pursuing evidence‑driven learning environments and turn‑key sourcing.
Recent developments—facility expansions, product launches, and trade show activity—are early indicators of strategic intent. Buyers and investors should interpret these signals as directional evidence of where manufacturers expect growth and margin expansion to occur.
Regulatory and input‑cost landscape: actionable risk framing
- Tariffs and raw material cost pressure: Elevated tariffs on steel and aluminum (dating from 2025) and ongoing duties on certain timber products have materially raised input costs for furniture manufacturers. For 2026 planners, this increases the value of alternative material specifications, value‑engineering, and supplier diversification.
- Standards and compliance: Educational furniture must comply with structural integrity tests, low‑VOC material standards, ergonomic guidelines, and fire safety regulations. Failure to anticipate specification changes creates procurement delays and potential liability—build compliance checkpoints into product development and tender responses.
- Pedagogical design demands: Flexibility, inclusivity, and whole‑child support are not marketing phrases—they carry procurement implications (adjustable ergonomic ranges, mobility, inclusive seat designs, accessible storage) that should be reflected in modular product families and warranty/service programs.
Practical 2026 playbook — prioritized actions for each stakeholder
- For manufacturers: accelerate modularization and platform‑based product design; lock in strategic suppliers for critical commodities; pilot maintenance‑as‑a‑service offerings to extend customer lifetime value.
- For district procurement teams: adopt total cost of ownership (TCO) scoring in tenders; include lifecycle maintenance and end‑of‑life recycling clauses; pilot outcomes‑oriented procurement with a 3–5 year review cadence.
- For investors and private equity: prioritize targets with differentiated intellectual property in ergonomics/modularity, robust channel partnerships, and domestic manufacturing that mitigates tariff exposure.
- For architects and specifiers: incorporate lifecycle, maintenance, and sustainability metrics into early stage design decisions; engage furniture vendors earlier to align build schedules and installation scopes.
Why this report is strategic for 2026 decision-making
Our analysis translates market forecasts into operational choices: where to invest in capacity, how to reprice contracts to protect margins, which product attributes win tenders, and what consolidation moves create durable advantage. With a measured growth outlook—neither contractionary nor hyper‑growth—2026 is a year for selective investment, risk reduction, and the re‑weighting of portfolios toward higher‑margin, service‑enhanced offerings.
Access and next steps
The full PW Consulting K–12 Education Furniture Market report contains the detailed segmentation tables, regional and product breakouts, downloadable financial models, procurement templates, and the comprehensive list of M&A targets and supplier risk maps. This preview intentionally omits granular segment share figures and confidential appendices to preserve the value of the primary report and data downloads.
For executives preparing 2026 budgets and strategy sessions, obtaining the full report will provide the numerical granularity, model access, and operational templates required to move from insight to action.
PW Consulting remains available for bespoke workshops, scenario‑planning sessions, and due‑diligence support tailored to vendor selection, procurement reform, or acquisition screening in the K–12 education furniture space.
For detailed analysis of this topic, please visit the official page: K 12 Education Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Self‑Healing Gel Market to Expand at 9.85% CAGR, New Insights Report Finds
By pmarketresearch, 2026-07-06
Self-Healing Gel Market 2026: Strategic Preview — What Leading Companies Must Know Now
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive preview of our new Self Healing Gel Market report — a focused intelligence asset designed to shape executive decisions in 2026. This briefing distills the report’s high-conviction findings, strategic implications, and recommended plays without disclosing the proprietary segment-level datapoints and scenario tables reserved for report subscribers. Think of this as a trailer: it demonstrates our analytical depth and the decisions it enables, while inviting you to access the full dossier for the operational detail your teams will act on.
Self Healing Gel Market
Market Trajectory — Macro Facts You Need to Anchor Strategy
The self-healing gel market has moved from a novel materials niche into a rapid-growth commercial market. Our analysis shows expansion from a market size of USD 175.0 million in 2020 to USD 285.5 million in 2025, driven by accelerating adoption in biomedical applications, soft robotics, and advanced coatings. Looking ahead, the market is projected to reach approximately USD 318.5 million in 2026 and rise to roughly USD 551.2 million by 2032, reflecting a compound annual growth rate (CAGR) of 9.85% over the forecast window (2026–2032).
Self Healing Gel Market
These macro numbers encapsulate three practical truths for corporate leaders: 1) demand is real and recurring, not merely speculative; 2) the market’s scale by 2032 supports meaningful R&D and manufacturing investments; and 3) timing is crucial — first-mover and fast-follower strategies will yield asymmetric returns when combined with credible regulatory and clinical evidence plans.
Self Healing Gel Market
Why This Report Matters for 2026 Decisions
- Portfolio Prioritization — We provide a repeatable framework to evaluate whether to invest in hydrogel-based formulations, elastomeric self-healing chemistries, or supramolecular approaches based on stage-gate economics and clinical time-to-value.
- Regulatory & Reimbursement Roadmaps — The report aligns product profiles to accelerated approval pathways (notably in the U.S.) and models reimbursement sensitivity across major markets so you can budget compliance and evidence-generation investments accurately.
- Commercial Go-to-Market Timing — We map the product commercialization clock: from pilot clinical programs through to scale manufacturing and tender cycles, highlighting windows in 2026–2028 where commercialization investments yield the highest upside.
- Supply Chain & Cost Resilience Playbook — With polymer and biomaterial price volatility as a structural risk, the report includes hedging strategies, dual-sourcing scenarios, and process intensification options to protect gross margins during raw-material shocks.
What the Report Contains — Practical Tools for Leadership
- Executive scenarios (base, conservative, upside) linked to action checklists for R&D, regulatory, and commercial teams.
- Technology radar that ranks self-healing chemistries by maturity, scalability, and IP risk.
- Regulatory sequencing playbooks for FDA and EMA, including accelerated pathway points and typical evidentiary packages by intended use-case.
- Reimbursement sensitivity models and sample payer-communication templates for advanced wound care and regenerative products.
- Supplier and partner benchmark matrix with negotiation levers and contract templates tuned to volatile input costs.
- M&A and partnership scorecards to identify tuck-in assets versus platform acquisitions and to size integration risks.
- Clinical evidence prioritization roadmap mapping minimal viable evidence packages to commercial milestones.
Competitive Landscape — How Incumbents and Innovators Are Positioned
The competitive landscape blends established medical-device and material firms with nimble biotech innovators. Market concentration metrics indicate a moderately fragmented market: the top three players account for approximately 22.4% of market revenue, while the top five reach about 35.8%. That fragmentation signals both opportunity and the need for disciplined positioning.
- Advanced Medical Solutions Group PLC (UK) — A proven player in advanced wound care with hydrogels embedded in clinical pathways. Strengths include clinical relationships and product breadth. Their strategic play will likely emphasize incremental innovation and channel expansion.
- Axelgaard Manufacturing Co. Ltd. (Fallbrook, CA) — Known for AmGel hydrogels across wound care, sensing, and stimulation. Technical know-how in device integration gives them advantage in bundled solutions and OEM partnerships.
- Cardinal Health (Dublin, OH) — Distribution scale and portfolio breadth make Cardinal a critical commercial partner for any developer seeking rapid market access in acute-care settings.
- Hydromer Inc. (Branchburg, NJ) — Specialist in hydrophilic coatings and device-focused hydrogels; their IP around coatings can create defensible niches in implantable and sensor applications.
- Gel4Med Inc. (USA) — An innovator with peptide-based biomimetic matrices; recent clinical and regulatory milestones indicate they are transitioning from R&D to scalable commercialization. Their profile makes them an attractive partner or acquisition target for incumbents seeking next-generation matrices.
- Alliqua Biomedical, Contura International S.A., Smith & Nephew Plc, 3M Company — Each brings complementary strengths: channel reach, manufacturing scale, or R&D muscle. Expect aggressive IP defense, selective partnerships, and targeted product launches.
Strategically, the choices firms face in 2026 are binary at the portfolio level: expand and defend with capital and clinical evidence, or seek partnering/licensing to de-risk and accelerate time-to-market. Our report quantifies the trade-offs for both approaches.
Recent Catalyst Events and Their Strategic Implications
- Aug 2025 — Gel4Med published real-world evidence out of Massachusetts General Hospital / Harvard Medical School demonstrating accelerated diabetic foot ulcer healing with its biomimetic matrix. Strategic implication: robust real-world datasets materially shorten payer conversations and support premium pricing strategies for regenerative products.
- Oct 2023 — Gel4Med cleared via FDA 510(k), establishing a regulatory precedent for similar synthetic matrices. Strategic implication: a replicable pathway exists for certain device-class gels, but variant formulations still face full regulatory scrutiny in many uses.
- Mar 2025 — Research teams reported a stiff, rapidly self-healing hydrogel mimicking human skin. Strategic implication: materials science breakthroughs are enabling new clinical use-cases (e.g., load-bearing soft-tissue repair) that expand addressable markets beyond classic wound care.
- Feb 2025 — Polysaccharide-based self-healing systems enabling pH-triggered release were published, highlighting programmable delivery potential. Strategic implication: combining self-healing matrices with controlled-release chemistries creates differentiated clinical value propositions and new IP possibilities.
Dynamics and Risks — What Could Alter the 2026 Playbook
- Regulatory variation: While some jurisdictions offer accelerated pathways for advanced wound care, stringent approval requirements in others raise compliance costs and elongate timelines. A calibrated regulatory investment plan is essential.
- Raw material volatility: Polymers and biomaterials remain subject to price and supply swings. Tactical recommendations include dual-sourcing, long-term offtake contracts, and process redesign for material yield improvements.
- Reimbursement hurdles: Despite clinical uptake in specialized centers, broad payer coverage lags, particularly for higher-cost regenerative solutions. Evidence strategies must be tailored to payer value drivers early in development.
- Clinical scalability: Demonstrating consistent manufacturing and long-term outcomes is non-trivial for some self-assembling chemistries; quality-by-design and early scale-up investment reduce downstream risk.
Recommended 2026 Playbook — Tactical Moves with Strategic Impact
- Short-term (0–12 months): prioritize targeted evidence generation (real-world and short-term RCTs) for your highest-margin use-case; secure strategic supply agreements to protect against polymer price spikes.
- Medium-term (12–36 months): invest selectively in manufacturing capacity for differentiated chemistries or secure licensing arrangements that preserve upside while limiting capex exposure.
- Long-term (36+ months): pursue value-accretive M&A to acquire clinical datasets, distribution channels, or platform IP when valuations align with modeled synergies in our report scenarios.
How PW Consulting’s Report Supports Execution
Subscribers receive the full dataset, including scenario-by-segment forecasts, vendor scorecards, regulatory evidence templates, and downloadable financial models calibrated to your assumed commercialization timeline. For boards, the report provides a succinct investment thesis for capital allocation in 2026; for product teams, it offers the tactical evidence and supply-chain steps required to hit commercialization milestones.
Next Steps
This preview outlines why 2026 is a pivotal year for companies operating in or entering the self-healing gel ecosystem. For the complete segmentation tables, proprietary company profiles, and the decision-ready financial models cited herein, visit the PW Consulting report page or contact our Industry Insights team to arrange a briefing. The full report contains the granular inputs and playbooks your teams will need to convert strategic intent into operational progress.
PW Consulting — translating material science momentum into board-level clarity and market-winning execution.
For detailed analysis of this topic, please visit the official page: Self Healing Gel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com