

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Cone Beam Imaging (CBCT) Market to Surge at an 8.25% CAGR Through 2032

Cone Beam Imaging (CBCT) Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new Cone Beam Imaging (CBCT) Market report (base year 2025; forecast period 2026–2032) is designed to be a decision‑grade briefing for executives planning products, investments, and go‑to‑market moves in the year ahead. At the macro level, the global CBCT market was valued at approximately USD 1.85 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 8.25% through 2032, reaching just over USD 3.2 billion by the end of the projection window. These topline dynamics reflect a market that is expanding quickly enough to support new investment and consolidation, but also maturing around a set of technology, regulatory, and reimbursement constraints that will shape winners and losers in 2026 and beyond.
Cone Beam Imaging Cbct Market
Why this report matters for 2026 planning
- Timing of technology transition: 2025–2026 marked a seismic step for software-enabled CBCT workflows. Multiple AI‑enhanced analysis tools received regulatory clearance in late 2025 and early 2026, accelerating clinicians’ ability to extract diagnostic value from 3D data and creating meaningful differentiation opportunities for platform owners.
- Consolidation and concentration: Market concentration is high and rising — the top three vendors account for a majority share of industry revenue, and the top five control nearly four out of five dollars spent. That concentration both raises barriers to entry and creates strategic openings for mid‑market players with narrow, high‑value propositions.
- Capital intensity and buyer mix: Hospitals and multi‑site dental chains remain important purchasers, sustaining demand for higher‑capacity units and integrated service contracts. At the same time, limited comprehensive reimbursement coverage for CBCT procedures in many regions continues to be a brake on volume expansion in outpatient and smaller dental practices.
What is in the report — practical deliverables for 2026 action
This report has been built as an operational playbook rather than a high‑level briefing. It combines primary interviews, vendor financials, installation datasets, and a bottom‑up device build‑out model to produce both strategic insight and executable outputs for commercial teams. Key deliverables include:
Cone Beam Imaging Cbct Market
- Topline market sizing and year‑over‑year market movement (2020–2025 historical plus a 2026–2032 forecast), with scenario pathways for conservative, base, and aggressive adoption curves.
- Supplier and product mapping (device form factors, FOV tiers, imaging resolution, and software ecosystems), with go‑to‑market implications for OEMs and channel partners.
- Competitive profiles and playbooks for leading vendors, emphasizing product differentiation, service economics, and partnership levers.
- Regulatory and reimbursement trackers, including a pragmatic checklist for filing strategies and payer evidence generation to support reimbursement pilots.
- Commercial diligence templates: pricing models, service margin tables, and customer segmentation frameworks for prioritizing sales effort across hospitals, dental chains, and private clinics.
- Investment and M&A screening: value drivers, multiples sensitivity, and a shortlist of capability gaps that should be targeted by acquirers and investors.
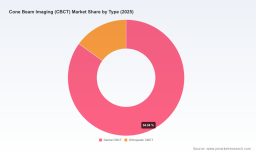
To respect the “trailer” principle and to protect our proprietary segmentation work, the report deliberately reserves detailed regional, application, and type breakdown tables for purchasers of the full study. Readers can expect those granular splits and vendor‑level revenue matrices within the full report package.
Cone Beam Imaging Cbct Market
Competitive landscape — who to watch and why
The CBCT vendor ecosystem now blends legacy imaging OEMs with agile specialty players and software innovators. Key firms we profile and benchmark include:
- Dentsply Sirona (Charlotte, NC, USA) — a market incumbent with integrated dental imaging solutions and advanced 3D treatment‑planning software. Strength lies in deep clinical relationships and bundled offerings across consumables and imaging.
- Planmeca Oy (Helsinki, Finland) — known for systems with low‑dose imaging and integrated facial scanning. Recent device introductions targeting North America strengthen its competitive posture in premium channels.
- VATECH Co., Ltd. (Hwaseong‑si, South Korea) — differentiated by auto‑switching and dose‑management features, a strong regional footprint, and competitive manufacturing economics.
- Carestream Dental (Atlanta, GA, USA) — multi‑field‑of‑view platforms with AI features and modular imaging suites targeted at larger dental group practices.
- J. Morita (Kyoto, Japan) and PreXion (Japan) — recognized for high‑resolution imaging and depth in endodontic and radiologic applications.
- Cefla/NewTom (Imola, Italy) — positions that span dental to select medical use cases, emphasizing diagnostic flexibility.
- CurveBeam (USA) — an example of a successful niche player focused on weight‑bearing and extremity CBCT systems, now extending into orthopedic workflows with AI capabilities.
- Asahi Roentgen (Japan) — compact, reliable systems that appeal to space‑constrained clinics.
Alongside hardware suppliers, a new class of software vendors is changing the competitive equation. Notably, several AI companies won regulatory clearances in the 2025–2026 window — examples include 510(k) clearances for AI‑enabled CBCT review platforms and orthodontic analysis tools. These software approvals accelerate product roadmaps for vendors that can quickly integrate validated AI modules into their imaging suites.
Recent regulatory and market events — implications for commercial strategy
- Multiple FDA 510(k) clearances for AI‑enabled CBCT software in 2025–2026 have reduced a key barrier to clinical adoption of automated 3D analysis. Manufacturers and channel partners should treat validated AI as a feature that materially affects purchasing decisions and pricing power.
- New device introductions into North America by established international vendors have intensified competition in higher‑end segments. This increases the importance of service excellence, bundled warranties, and flexible financing to protect margin.
- Reimbursement remains uneven. Until payers adopt structured codes that reflect CBCT’s unique clinical value, adoption in lower‑resource settings will rely on demonstrated ROI in procedural outcomes and practice throughput rather than on fee‑for‑service reimbursement alone.
Strategic implications and 2026 playbook
- For OEMs: Prioritize modular platform strategies that allow rapid integration of third‑party FDA‑cleared AI modules. Differentiate on service and training economics; predictable uptime and validated clinical workflows will be decisive in enterprise tenders.
- For software vendors: Pursue regulatory clearance early, but pair clearance with real‑world evidence from pilot deployments in multi‑site dental chains or hospital radiology departments to accelerate adoption.
- For hospital systems and large dental groups: Implement phased adoption pilots tied to clinical KPIs (implant accuracy, orthodontic planning time, reduction in follow‑up imaging). Use those pilots as the foundation for internal reimbursement and capital allocation plans.
- For investors and acquirers: Target businesses that enhance installed base monetization — service, consumables, analytics subscriptions — and consider tuck‑ins that add AI or workflow software to hardware incumbents to capture higher recurring revenue.
- For distributors: Build financing products and outcome‑based service contracts to address CapEx constraints at smaller clinics. Bundling installation, training, and software subscriptions will increase lifetime customer value.
Risks, monitoring metrics, and scenario levers
Key risks that should be monitored through 2026 include reimbursement policy evolution, the pace of regulatory acceptance for new AI capabilities, and competitive pricing pressure from lower‑cost manufacturers. We recommend tracking a short list of leading indicators on a monthly cadence:
- Rate of FDA 510(k) clearances for CBCT‑related AI and software modules.
- Consolidation activity among top suppliers and resulting shifts in CR3/CR5 concentration.
- Payer announcements and regional reimbursement pilot programs.
- Installation and service backlog data from major hospital systems and dental chains.
Next steps — how PW Consulting supports 2026 execution
PW Consulting’s CBCT market study is intentionally operational: the full report includes the granular regional and application breakdowns, vendor revenue matrices, model inputs, and slide‑ready charts that make the case for board‑level decisions, product roadmaps, and M&A theses. For leadership teams preparing 2026 budgets, the study provides the empirical scaffolding to prioritize initiatives that increase utilization, shorten sales cycles, and extract recurring revenue from installed fleets.
To access the detailed splits, vendor scorecards, and the financial model behind our topline forecasts — or to commission a tailored due‑diligence or go‑to‑market engagement — contact PW Consulting. Our analysts will map the report’s insights into a short, practical action plan tailored to your organization’s strategic horizon.
For detailed analysis of this topic, please visit the official page: Cone Beam Imaging Cbct Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com