

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Disposable Alcohol Wipes Market to Expand at a 5.48% CAGR Through 2032

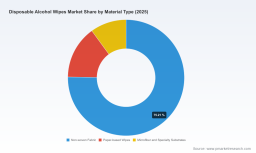
Disposable Alcohol Wipes Market: Strategic Outlook for 2026 — PW Consulting Industry Brief
PW Consulting’s latest market research note on the Disposable Alcohol Wipes market synthesizes five years of historical data (2020–2025) with a rigorous forecast through 2032. The market demonstrated a pronounced retracement from pandemic-era peaks—moving from an industry high in 2020 before contracting in 2021–2023 and recovering into 2024–2025—reaching an estimated total market size of USD 722.9 Million in our 2025 base year. Under our central scenario the market resumes steady growth across 2026–2032 at a compound annual growth rate (CAGR) of 5.48%, with the market expanding to roughly USD 1,050.2 Million by 2032. For executives preparing 2026 strategy, these topline dynamics are the starting point for reshaping supply chains, product portfolios, regulatory posture, and M&A agendas.
Disposable Alcohol Wipes Market
What this brief delivers for 2026 decision-makers
-
Actionable context for immediate priorities: inventory strategy, raw material risk mitigation, and short-cycle product launches that respond to institutional procurement cycles.
Disposable Alcohol Wipes Market -
A framework to prioritize R&D and sustainability investments that align with buyer willingness-to-pay and regulatory trajectories.
Disposable Alcohol Wipes Market -
Competitive positioning intelligence across incumbent manufacturers, contract producers, distributors, and new entrants to inform partnership, private-label, and acquisition decisions.
-
A concise set of KPIs and early-warning indicators designed to convert market-level forecasts into boardroom-ready operating targets for 2026.
Why the 2026 planning horizon is pivotal
Two converging forces make 2026 a hinge year: first, macro recovery of demand as healthcare and commercial budgets normalize post-crisis, and second, persistent cost and regulatory pressures that will re-shape margins and product claims. Our historical series—an industry peak in 2020, contraction in subsequent years, followed by recovery to the 2025 base—illustrates that winners will be those who translate topline growth into durable margin gains by 2026, not those who simply chase volume.
Report scope and practical contents
-
Market sizing and forecasting model (2020–2032) with scenario variants (base, downside, upside) and sensitivity to raw-material indices.
-
Go-to-market playbooks for four commercial archetypes—pure-play branded manufacturers, contract manufacturers, distributors/private-label operators, and mixed-model incumbents—complete with channel economics and pricing matrices.
-
Supply-chain mapping and supplier risk heatmaps that quantify exposure to alcohol feedstocks and polymer substrates, plus recommended sourcing contingencies.
-
Regulatory and quality-compliance checklists tailored to EPA and FDA pathways for disinfectant and prep-pad products, and a waste-disposal compliance primer.
-
Manufacturing diagnostics and capital-expenditure benchmarks to support capacity expansion or conversion decisions (e.g., switch to biodegradable substrates).
-
Competitive scorecards, M&A screening templates, and a prioritized shortlist of acquisition targets and contract-manufacturing partners (detailed listings reserved for the full report).
Competitive landscape — what incumbents and challengers are doing
The market is characterized by a mix of legacy brand owners, healthcare-specialist manufacturers, industrial suppliers, and agile contract manufacturers. Market concentration is moderate: the top three players account for roughly 38% of industry revenue, while the top five account for just over half. This structure supports both competition and selective consolidation opportunities.
-
Nice-Pak Products, Inc. — With a history of product innovation and hospital-grade offerings, Nice-Pak remains a reference point for product reliability. Their strength is in established manufacturing footprints and institutional relationships; the strategic consideration for rivals is that Nice-Pak can mobilize scale-based cost defenses quickly.
-
PDI Healthcare — A specialist in infection-prevention, PDI’s clinical credibility and focus on germicidal formulations make it a primary supplier for healthcare procurement teams. Competitors should anticipate continued demand from regulated clinical settings and consider clinical-evidence investments to compete effectively.
-
Clorox — Leveraging powerful consumer and institutional brands, Clorox combines marketing reach with institutional sales channels. Their ability to bridge retail and pro channels pressures mid-market firms to clarify channel strategies and differentiation.
-
Ecolab — Ecolab’s recent launch of a 100% plastic-free, EPA-registered disinfectant wipe with 1-minute hospital disinfection demonstrates how sustainability and performance claims can coexist. Expect greater product differentiation around biodegradability and reduced plastic use.
-
Kimberly-Clark, 3M, Cardinal Health — These companies emphasize critical-cleaning, lab-use, and distribution scale. Their advantage is a portfolio-led cross-sell into existing healthcare and industrial customers.
-
Contract manufacturers and OEMs (e.g., Diamond Wipes International; Zhejiang-based manufacturers) — They continue to shape private-label economics and speed-to-market for new formulations. For buyers, contract partners are pivotal for rapid SKU expansion or regional supply security.
Recent industry events underscore these dynamics: Ecolab’s July 2024 launch of a degradable, fast-acting disinfectant wipe signals a growing premium for sustainability-performance hybrids; several suppliers introduced natural-ingredient lines in 2025 aimed at travel and personal-care channels; and a September 2025 FDA Class II recall of certain prep pads highlighted continuing regulatory and quality-compliance vulnerabilities for some manufacturers. These developments are instructive for 2026 planning: differential product claims will drive premiumization, while regulatory missteps will be costly reputationally and financially.
Key market dynamics and risk vectors
-
Raw-material volatility: Isopropyl alcohol (IPA) and other alcohol feedstocks represent the single largest input cost exposure in 2025; industry data show IPA accounting for a material majority share of raw-material outlays for alcohol wipes, with price swings of 15–25% year-over-year in recent cycles. Non-woven substrates—often polypropylene/polyester blends—remain the next-largest cost bucket and are sensitive to petrochemical price moves and supply-chain disruptions.
-
Regulatory complexity: EPA registration for disinfectant claims and FDA oversight for certain prep-pad and antiseptic products impose distinct development and labeling pathways. Disposal rules for solvent-contaminated wipes add compliance costs for customers and producers.
-
Trade and tariff considerations: Imports from key manufacturing hubs face duty and classification regimes that affect landed cost; for example, certain disinfectant wipes are classified under specific HTS codes with general duty structures that should be built into sourcing economics.
-
Quality and cGMP risk: Recalls and regulatory actions are leading indicators of potential demand shocks and buyer reallocation—companies should audit quality systems and supplier controls as priority investments for 2026.
-
Innovation vectors: Rapid contact-time disinfection, plastic-free substrates, bio-based alcohols, and single-dose sterile formats are converging into distinct value propositions across healthcare, commercial cleaning, and personal-care channels.
Strategic playbook for 2026 (prioritized and executable)
-
Near term (0–12 months): Implement raw-material hedging and dual-sourcing for IPA and non-woven substrates; execute a focused regulatory compliance audit; launch 1–2 SKU pilots that emphasize either faster kill time or demonstrable sustainability credentials; refresh commercial terms with large distributors to protect margin.
-
Medium term (12–36 months): Invest selectively in substrate-conversion lines (biodegradable or lower-plastic content); pursue tuck-in acquisitions to fill capability gaps (contract manufacturing, specialized formulations, or regional distribution); digitize customer channels to capture higher-margin DTC and specialist procurement segments.
-
Operational KPIs to monitor: raw-material price index vs. cost pass-through rate, SKU-level margin by channel, quality incident frequency, share of revenue from sustainability-labelled SKUs, and time-to-EPA/FDA approval for new claims.
-
M&A and partnership filters: prioritize targets with clean quality histories, backward-integration potential for substrates or alcohol supply, and assets that accelerate entry into attitudinally premium segments (e.g., healthcare-certified biodegradable wipes).
How PW Consulting helps
The full PW Consulting report contains the granular datasets, supplier scorecards, and financial models required to convert the strategic playbook above into executable 2026 operating plans. It includes concealed subsegment splits, region/application level KPIs, and a ranked list of short- and medium-term M&A targets that are excluded from this brief by design—our “trailer” approach is intended to surface the insight needed to act quickly while directing readers who require transaction-grade detail to the full report.
For procurement heads, R&D leaders, corporate development teams, and investment committees preparing budgets and deal pipelines for 2026, our analysis translates market growth (CAGR 5.48% through 2032) and structural risk into a prioritized set of choices: protect margin with disciplined sourcing; win share through certified performance and sustainability claims; and use M&A or capacity investments to lock in advantaged cost positions.
To access the full dataset, the proprietary segmentation tables, and the comprehensive M&A shortlist that underpin the strategic recommendations above, please visit the PW Consulting report landing page or contact your PW advisor for an executive briefing and data license.
For detailed analysis of this topic, please visit the official page: Disposable Alcohol Wipes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com