

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bake‑Stable Pastry Fillings Market to Grow at 5.2% CAGR, Reaching USD 2,067.7 Million by 2032 as Europe Leads with USD 504.6M Share

Bake Stable Pastry Fillings Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market research—Bake Stable Pastry Fillings Market (Base year: 2025, Forecast: 2026–2032)—equips senior leaders, R&D heads, and M&A teams with the actionable intelligence required to move from reactive operations to proactive market shaping in 2026. The report synthesizes five years of historical dynamics (2020–2025) and presents a detailed forward view: the global bake-stable pastry fillings market, measured in USD Million, expands from the 2025 base and is forecast to grow at a 5.2% compound annual growth rate (CAGR) through 2032. By the end of the forecast horizon the market reaches an estimated USD 2,067.66 Million, underscoring a materially enlarging opportunity for ingredient suppliers, co-manufacturers and bakery brands.
Bake Stable Pastry Fillings Market
Why this preview matters for 2026 strategy
2026 is a pivot year: raw material volatility has begun to moderate following acute price spikes, consumer expectations are accelerating around clean-label and functional attributes, and production technologies for high-throughput bakeries are rapidly maturing. For executives deciding product portfolios, capital allocation, or partnership strategies this report functions as both compass and toolkit—highlighting which trade-offs deliver durable margin expansion and which moves risk commoditization.
Bake Stable Pastry Fillings Market
-
Timing decisions on plant capacity and pilot facilities: with market momentum accelerating in 2026, our modeling clarifies the window where incremental capacity yields premium utilization rather than oversupply.
Bake Stable Pastry Fillings Market -
Formulation and ingredient sourcing: the report assesses how formulation choices (starch systems, pectin profiles, clean-label stabilizers) translate into bake stability, shelf life, and cost-to-serve across industrial and foodservice channels.
-
M&A and partnering: concentration metrics indicate meaningful room for consolidation and bolt-on plays that can rapidly increase scale in strategically aligned subsegments.
What the PW Consulting report delivers (practical, actionable content)
This is not a high-level narrative. The report contains hands-on assets designed for implementation teams:
-
Executive dashboards and a downloadable financial model that let you scenario-test price, raw material shifts, and channel mix impacts on margin and working capital through 2032.
-
Go-to-market playbooks for three priority customer profiles (industrial bakeries, foodservice operators, retail/home-baking brands), including tailored sampling protocols, shelf-life validation plans, and commercial KPIs for distributor partnerships.
-
Formulation decision trees and lab-to-line scale-up checklists: guidance on selecting starch systems, fruit concentrates, and oil phases to optimize migration, rheology, and bake stability under high-temperature processes.
-
Supplier scorecards and cost-optimization levers: procurement scripts and benchmarking tools to negotiate ingredient contracts and hedging strategies against raw-material swings.
-
Regulatory and clean-label compliance matrixes: where to prioritize ingredient transparency and how to structure claims without compromising product stability or shelf life.
-
Three investment case studies that show step-by-step returns from product innovation, capacity expansion, and channel diversification—complete with sensitivity analyses and recommended KPIs.
Market dynamics and raw material context
Several forces are converging on the bake-stable fillings value chain. First, raw-material price shocks of the recent past have not vanished but demonstrate different trajectories across commodity classes. Cocoa experienced an extreme spike into early 2025 and then corrected significantly by mid‑2026, while retail fresh fruit prices have shown modest year-on-year increases even as farm-level price pressure may ease in 2026. Sugar and sweetener pricing has been volatile on a year-on-year basis, with short-term monthly easing in early 2026. These shifts matter because they change not only input costs but also formulation choices (e.g., transitions to fruit concentrates, different sweetener matrices, or stabilized fruit prep methods).
Second, regulatory and consumer-driven clean-label preferences are now structural. Demand for bake-stable fillings that avoid artificial additives, certain stabilizers, or high‑fructose sweeteners is driving R&D investment in alternative hydrocolloids, pectin systems, and enzymatic process controls. Companies that can translate clean-label claims into robust, bake-stable performance will win access to premium channels.
Segmentation and concentration—what to watch (high level)
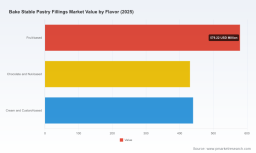
The market’s growth dynamic is broad-based across flavors, applications and geographies. Our segmentation analysis tracks regional demand, flavor categories (fruit-based; chocolate and nut-based; cream/custard-based) and application channels (industrial/wholesale, foodservice, retail/home baking) to reveal where structural growth and margin uplift opportunities reside. Rather than publishing every granular split here, the report provides interactive segment matrices that allow users to isolate the exact segments most relevant to their strategy.
Concentration is moderate: the top three players control a meaningful share of the market while the top five extend that influence—indicating both brand advantages and space for acquisitive growth by well-capitalized challengers. This structure means mid-sized operators can still capture specialist premium niches, especially where they can demonstrate formulation superiority or channel intimacy.
Competitive landscape—what incumbents are doing
We profile the strategic moves and product architectures of the market’s core suppliers. Highlights include:
-
Puratos Group (Groot-Bijgaarden, Belgium) has invested in pilot plant capacity and innovation ecosystems to accelerate commercialization of high‑stability fruit and cream systems—targeting commercial bakeries that require scaleable, clean-label fillings.
-
Dawn Foods (Jackson, Michigan, USA) continues to leverage its BakeFill and PlusFill families, emphasizing high fruit content and formulations optimized for freeze-thaw and bake stability across a wide set of bakery formats.
-
AGRANA (Vienna, Austria) is focusing on thermostable fruit preparations that preserve shape and color under aggressive baking; their recent trade show activity underscores a push into all‑in‑one ingredient solutions including vegan options.
-
Bakels Group (Lucerne, Switzerland) and Andros Chef (Cajarc, France) are expanding ready‑to‑use and clean‑label offerings, serving both industrial and home-baking channels with vegan and preservative‑free lines.
-
Metarom USA (New Hampshire, USA) positions itself as a technical partner for custom flavor and filling systems—publishing technical criteria for selection of bake‑stable fillings that help industrial buyers reduce technical risk.
-
Barry Callebaut (Zurich, Switzerland) remains an important supplier of chocolate- and caramel-based bake-stable fillings, investing in heat-tolerant chocolate constructs for high-temperature processing.
Recent events validate these strategic tracks: Puratos’s facility launch in mid‑2025 accelerates application testing for commercial customers; Metarom’s technical publications in 2025 are shaping procurement criteria at industrial bakeries; and AGRANA’s trade-show rollouts confirmed interest in consolidated ingredient packages that reduce supplier complexity.
Innovation priorities for 2026
Based on lab-to-line analysis and customer interviews, five innovation vectors offer the highest commercial upside in 2026:
-
Clean-label hydrocolloid matrices that deliver bake stability without artificial additives.
-
High-fruit-load preparations that maintain structure and color when subjected to long bake cycles or prolonged shelf storage.
-
Thermostable chocolate and caramel fillings engineered for industrial tunnel ovens and fryer applications.
-
Stabilized low-sugar and reduced-calorie fillings that preserve mouthfeel and water activity control.
-
Modular co-manufacturing models (private label plus innovation tiers) that reduce customer time-to-market.
Go-to-market, risk mitigation and M&A playbook
The report provides step-by-step playbooks to execute on commercial opportunities while controlling risk. These include rapid qualification protocols for new fillings, procurement hedging templates tied to raw-material indices, and integration checklists for bolt-on acquisitions—addressing integration of R&D, supply chain, sales channels, and regulatory files.
For M&A teams, our valuation frameworks incorporate scenario testing under different raw‑material volatility regimes and channel-shift assumptions. Given the current competitive concentration and growth profile, opportunistic acquisitions that bring either proprietary formulation technology or differentiated channel access are likely to deliver above-average returns.
Methodology and reliability
The PW Consulting analysis combines bottom-up supplier reporting, proprietary demand modeling, and primary interviews across the value chain. Our base year is 2025 with historical trend analysis from 2020–2025 and scenario-driven forecasts for 2026–2032. We integrate commodity price research, regulatory trend tracking, and supplier capacity mapping to produce pragmatic scenario outputs suitable for board-level decision-making.
How to use this intelligence in 2026
Practical next steps for executive teams:
-
Run a tailored scenario in the report’s model to test the impact of a 10–20% raw-material swing on your product portfolio and determine which SKUs to rationalize or scale.
-
Prioritize pilot plant investments for one or two clean-label fillings that can be rolled out across key channels within 12–18 months.
-
Use supplier scorecards and procurement playbooks to renegotiate contracts keyed to performance metrics rather than purely on price.
-
Evaluate bolt-on acquisitions that offer proprietary formulation IP or exclusive R&D relationships with regional bakery networks.
Conclusion — a pragmatic call to action
For leaders preparing 2026 budgets and three‑year roadmaps, the bake‑stable pastry fillings market represents a concrete growth corridor with actionable levers. The industry is neither fully consolidated nor technologically static: ingredient suppliers that pair formulation know‑how with strong go‑to‑market execution will capture disproportionate value. PW Consulting’s full report converts the market’s macro signal—steady growth at a 5.2% CAGR into 2032—into operational blueprints, commercial scripts, and investment cases designed to be executed in 2026.
To access the full dataset, interactive models, and supplier scorecards referenced in this preview, please visit the report’s source webpage where the comprehensive report and supporting appendices are available for download.
For detailed analysis of this topic, please visit the official page: Bake Stable Pastry Fillings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com