

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: K–12 Education Furniture Market to Grow at a 5.25% CAGR, Reaching USD 7.44 Billion by 2032

K–12 Education Furniture Market: Strategic Outlook to 2032 — A PW Consulting Preview
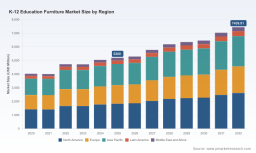
PW Consulting today publishes an executive preview of our forthcoming K–12 Education Furniture Market report, a practice-oriented intelligence product designed to guide school systems, manufacturers, investors, and procurement teams as they set budgets and strategies for 2026 and beyond. The sector is at an inflection point: after recovering from mid‑decade shocks to materials and global supply chains, the global K–12 education furniture market is estimated at USD 5,200.0 Million in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of 5.25% through our forecast window (2026–2032), with a 2032 market projection in the neighborhood of USD 7,439.9 Million.
K 12 Education Furniture Market
Why this preview matters for 2026 decision cycles
- Capital planning: School district capital expenditure cycles and multi‑year renovation programs initiated in 2026 will lock in furniture specifications for the rest of the decade. Our analysis highlights timing windows and procurement levers that materially affect total cost of ownership (TCO).
- Supply‑side risk management: Raw material volatility and regulatory shifts in 2025–2026 increase the value of hedged sourcing strategies and near‑shoring options. Manufacturers and buyers who act early can protect margins and avoid late‑cycle price escalations.
- Product portfolio alignment: Pedagogical trends toward collaborative, flexible, and inclusive learning spaces are translating into quantifiable demand shifts across product types and classroom typologies—an insight we describe in operational terms to inform 2026 R&D and SKUs rationalization.
Market trajectory at a glance (operational intelligence)
Historical tracking across 2020–2025 shows recovery and renewed momentum following pandemic-era dislocation. The market size rose from the low‑to‑mid‑thousands in 2020 and reached USD 5,200.0 Million in 2025. From a strategic perspective, a sustained mid‑single digit CAGR (5.25%) to 2032 implies steady expansion, but not runaway growth—an environment that rewards operational efficiency, targeted innovation, and disciplined commercial execution rather than broad, undifferentiated capacity expansion.
K 12 Education Furniture Market
Two practical implications follow: first, incremental share can be captured through differentiated specification (durability, ergonomics, low‑VOC materials, modularity); second, disciplined pricing and service contracts (maintenance, warranty, replacement cycles) will be central to securing long‑term institutional buyers.
K 12 Education Furniture Market
What PW Consulting’s full report delivers (hands‑on tools for 2026)
- Methodology and transparent market model: our sizing framework decomposes demand drivers (new construction, replacement cycles, refurbishment), procurement cadence, and life‑cycle assumptions so clients can re‑run scenarios against their own inputs.
- Practical buyer personas and procurement playbooks: procurement templates for public and private K–12 buyers, including tender language, specification checklists (structural integrity, low VOC, fire safety, ergonomics), and scoring matrices to evaluate bids beyond sticker price.
- Supply chain heatmap and cost drivers: a supplier‑level risk map that highlights exposure to key materials (steel, aluminum, softwood lumber) and logistics chokepoints, with mitigation tactics such as alternate material designs and inventory strategies.
- Commercial playbook for manufacturers and distributors: go‑to‑market segmentation, channel economics, service offering design (installation, repair, lifecycle programs), and digital tools for order management and asset tracking.
- M&A and partnership leads: identification of attractive consolidation targets and strategic partnerships aligned to modular furniture, ergonomic innovation, and regional manufacturing footprints—scored by strategic fit, integration complexity, and expected payback horizons.
- Scenario analysis: three practical scenarios (baseline growth, cost‑inflation stress, and demand‑acceleration driven by education reform) enabling rapid financial and operational sensitivity testing for boardrooms and investment committees.
Competitive landscape — who to watch and what they reveal
The sector remains moderately consolidated: the top three companies account for a significant minority of the market, while the top five increase that share to a larger but still non‑dominant proportion—an axis that supports both incumbent advantage and emerging challenger opportunities. Key players to monitor include legacy U.S. manufacturers with strong K–12 pedigrees and design‑led firms that have translated workplace ergonomics into classroom solutions.
- Virco Manufacturing Corporation — a long‑standing U.S. manufacturer focusing on durable, education‑grade desks, chairs, tables and storage solutions. Their trade show presence and product refresh cadence remain important demand signals.
- KI Furniture (Krueger International) — increasingly active in capacity and technology investment. Recent facility expansion and new seating technology rolled out in early 2026 indicate a bet on higher‑value, differentiated seating systems and campus‑grade outdoor collections.
- Artcobell, Paragon, Allied School Furniture, Smith System, VS America, and HON — each offers complementary strengths in design, domestic manufacturing, or channel reach; their product roadmaps and procurement partnerships influence specification trends across districts.
- Herman Miller and School Specialty — bring research‑based design and integrated procurement capabilities that appeal to districts pursuing evidence‑driven learning environments and turn‑key sourcing.
Recent developments—facility expansions, product launches, and trade show activity—are early indicators of strategic intent. Buyers and investors should interpret these signals as directional evidence of where manufacturers expect growth and margin expansion to occur.
Regulatory and input‑cost landscape: actionable risk framing
- Tariffs and raw material cost pressure: Elevated tariffs on steel and aluminum (dating from 2025) and ongoing duties on certain timber products have materially raised input costs for furniture manufacturers. For 2026 planners, this increases the value of alternative material specifications, value‑engineering, and supplier diversification.
- Standards and compliance: Educational furniture must comply with structural integrity tests, low‑VOC material standards, ergonomic guidelines, and fire safety regulations. Failure to anticipate specification changes creates procurement delays and potential liability—build compliance checkpoints into product development and tender responses.
- Pedagogical design demands: Flexibility, inclusivity, and whole‑child support are not marketing phrases—they carry procurement implications (adjustable ergonomic ranges, mobility, inclusive seat designs, accessible storage) that should be reflected in modular product families and warranty/service programs.
Practical 2026 playbook — prioritized actions for each stakeholder
- For manufacturers: accelerate modularization and platform‑based product design; lock in strategic suppliers for critical commodities; pilot maintenance‑as‑a‑service offerings to extend customer lifetime value.
- For district procurement teams: adopt total cost of ownership (TCO) scoring in tenders; include lifecycle maintenance and end‑of‑life recycling clauses; pilot outcomes‑oriented procurement with a 3–5 year review cadence.
- For investors and private equity: prioritize targets with differentiated intellectual property in ergonomics/modularity, robust channel partnerships, and domestic manufacturing that mitigates tariff exposure.
- For architects and specifiers: incorporate lifecycle, maintenance, and sustainability metrics into early stage design decisions; engage furniture vendors earlier to align build schedules and installation scopes.
Why this report is strategic for 2026 decision-making
Our analysis translates market forecasts into operational choices: where to invest in capacity, how to reprice contracts to protect margins, which product attributes win tenders, and what consolidation moves create durable advantage. With a measured growth outlook—neither contractionary nor hyper‑growth—2026 is a year for selective investment, risk reduction, and the re‑weighting of portfolios toward higher‑margin, service‑enhanced offerings.
Access and next steps
The full PW Consulting K–12 Education Furniture Market report contains the detailed segmentation tables, regional and product breakouts, downloadable financial models, procurement templates, and the comprehensive list of M&A targets and supplier risk maps. This preview intentionally omits granular segment share figures and confidential appendices to preserve the value of the primary report and data downloads.
For executives preparing 2026 budgets and strategy sessions, obtaining the full report will provide the numerical granularity, model access, and operational templates required to move from insight to action.
PW Consulting remains available for bespoke workshops, scenario‑planning sessions, and due‑diligence support tailored to vendor selection, procurement reform, or acquisition screening in the K–12 education furniture space.
For detailed analysis of this topic, please visit the official page: K 12 Education Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com