

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
PW Consulting: Oxygenator Market to Hit USD 312.0 Million by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-08
Oxygenator Market: Strategic Preview for 2026 Decision-Makers
PW Consulting presents a concise strategic preview of the Oxygenator Market designed to inform executive decision-making in 2026. This briefing synthesizes our base-year analysis (2025) and the forward-looking forecast (2026–2032), highlighting the structural forces, regulatory inflection points, and competitive dynamics that will shape opportunity and risk. The full PW Consulting Oxygenator Market study contains the granular tables, segment-level forecasts, and executable playbooks that underpin the conclusions below; this preview intentionally omits those proprietary segment details to preserve the value of the complete report and to direct readers to the full intelligence.
Oxygenator Market
Market at a Glance — Macro Trajectory
The Oxygenator Market has demonstrated steady expansion across the past five years, growing from an estimated USD 165.5 Million in 2020 to USD 211.5 Million in 2025 (base year). PW Consulting’s forecast projects continued growth through 2032, with an expected market value of approximately USD 312.0 Million by the end of the forecast horizon. Our modeled outlook uses a compound annual growth rate (CAGR) of 5.8% for 2026–2032 under a baseline scenario, reflecting recovery after episodic demand shocks and continued adoption of extracorporeal life support technologies.
Oxygenator Market
Why This Study Matters for 2026
- Capital allocation: Clarifies which product classes and clinical applications are likely to deliver scale and margin expansion versus those that will require subsidy or strategic partnership.
- Regulatory and reimbursement timing: Maps how recent policy and recall events create windows of commercial opportunity and new compliance burdens.
- M&A and partnership targeting: Identifies pockets of consolidation and the attributes of assets that will command premium valuations.
- Operational resilience: Guides sourcing, manufacturing footprint, and inventory strategies to mitigate near-term supply volatility while preserving cost competitiveness.
What the Full Report Delivers (Practical, Transaction-Ready Outputs)
- Robust market-sizing and methodology appendix (top-down and bottom-up reconciliations) with yearly time series from 2020 through 2032.
- Segment-level forecasts by product type, application, and region—each with sensitivity scenarios and downside/upside cases for stress-testing strategic plans.
- Vendor scorecards and a commercial positioning matrix that benchmark clinical performance attributes, regulatory clearances, manufacturing capability, and go-to-market reach.
- Go-to-market playbooks for OEMs and distributors: channel strategy, pricing playbooks tied to reimbursement dynamics, and hospital procurement engagement scripts.
- M&A heatmap and valuation frameworks that convert clinical and regulatory advantages into implied deal multipliers.
- Operational checklists for regulatory readiness, quality surveillance, and post-market clinical follow-up programs essential for U.S. and EU market access.
Market Dynamics and Key Drivers in 2026
The underlying growth trajectory is being shaped by a combination of demand-side clinical trends and supply-side technological advances. Key themes for 2026 include:
Oxygenator Market
- Clinical adoption: Increased use of extracorporeal support for respiratory failure and expanding indications in cardiac surgery continue to drive installed-base expansion and consumable replacement cycles.
- Technology differentiation: Membrane and hollow-fiber designs are the central battlegrounds—manufacturers that reduce priming volume, lower pressure drop, and improve gas-exchange efficiency will capture clinical preference and procurement leverage.
- Regulatory and reimbursement shocks: Recent regulatory actions and payment policy changes are recalibrating hospital economics for ECMO and CPB procedures.
- Concentration and scale: The market is moderately concentrated, with the top tier of vendors controlling the majority of commercial volume—this creates both entry barriers and acquisition targets for nimble challengers.
Regulatory & Reimbursement Inflection Points (Actionable Signals)
- CMS and Medicare: The 2026 policy cycle introduced important changes affecting inpatient and outpatient payment rates for procedures involving oxygenators. These updates materially affect unit economics for hospitals and, by extension, pricing leverage for suppliers.
- Procedure-level reimbursement: Effective April 1, 2026, a new HCPCS code was established for a branded ECMO treatment under the Hospital Outpatient Prospective Payment System—creating a discrete pathway for reimbursement capture but also signaling increased coding scrutiny.
- MS-DRG assignment changes: Modifications to MS-DRG assignment for ECMO procedures in CY 2026 have the potential to reduce hospital reimbursement for certain peripheral ECMO cases—this will pressure total cost-of-care metrics hospitals use to select consumables and device vendors.
- Safety signals: The FDA issued a Class 2 recall in late 2025 related to CO2 gas transfer performance for a widely used oxygenator. Conversely, several manufacturers secured 510(k) clearances into 2025–2026, illustrating both the risk of brand erosion from performance events and the opportunity created by new entrants or newly-cleared products.
Competitive Landscape — Strategic Implications
PW Consulting’s vendor analysis focuses on product-engineering attributes, regulatory positioning, manufacturing control, and channel strength. Key players include established global OEMs, specialized ECMO suppliers, and regional manufacturers with growing export capability. Highlights and implications:
- Sorin Group (Italy): With recent FDA clearance for a next-generation integrated oxygenator-reservoir product (late 2025), the company is positioned to expand in regulated markets. Strategic implication: incumbents should anticipate renewed competitive pressure in integrated CPB solutions and consider strengthening product differentiation through clinical evidence and bundled service models.
- Terumo Cardiovascular Systems (USA): Vertical integration in hollow-fiber production and a strong CPB/ECMO product family confer durable product-performance advantages. Strategic implication: competitor responses should prioritize niche clinical evidence or cost-leadership to offset Terumo’s manufacturing scale.
- Medtronic (USA): A broad portfolio with biosurface technologies remains influential; however, recent performance-related recalls underscore reputational and supply risks. Strategic implication: rivals should be ready to exploit temporary capacity or trust gaps, while Medtronic must invest in corrective actions and targeted physician outreach.
- Specialist and regional suppliers (multiple European and Chinese firms): These players are innovating around priming volumes, pressure drop, and neonatal/pediatric designs, and some have begun penetrating regulated markets following 510(k) approvals. Strategic implication: multinationals should assess partnership, licensing, or selective acquisition to secure technology advantages and cost-efficient supply chains.
Strategic Playbook — Priorities for 2026
- Prioritize regulatory readiness and quality surveillance. Allocate resources to real-time post-market monitoring and rapid corrective action plans; regulatory events can quickly open commercial windows or close access corridors.
- Reassess pricing strategy against the new reimbursement landscape. Run hospital-level economic models tying device acquisition cost to total procedure economics under updated MS-DRG and outpatient payment rules.
- Invest in clinical evidence that maps device features to measurable hospital outcomes: shorter ICU stays, lower blood-product use, or reduced reinterventions are persuasive in procurement discussions.
- Build supply-chain redundancy. Identify single points of failure in fibers, membranes, and key polymer suppliers and implement dual-sourcing or co-investment strategies.
- Pursue targeted M&A and partnerships: prioritize assets that offer regulatory clearances in key geographies, differentiated membrane technology, or cost-advantage in high-volume consumables.
- Design hospital engagement pilots that de-risk switching costs for procurement leaders—bundle device, training, and performance guarantees to overcome incumbent inertia.
How to Use the Full PW Consulting Oxygenator Market Study
The complete PW Consulting report contains the underlying datasets, including regional, product-type, and application-level forecasts; detailed vendor market shares and financial proxies; a database of primary interviews; and downloadable Excel models for scenario testing. For 2026 strategy workstreams—whether capital allocation, commercial planning, or M&A diligence—the full study provides the quantitative backbone and ready-to-run templates that reduce time-to-decision and lower execution risk.
Closing — Immediate Next Steps
For executives preparing 2026 budgets and strategic plans, the Oxygenator Market is shifting from a product-led to an outcomes-led procurement dynamic under clearer reimbursement and regulatory signals. Use this preview to prioritize which internal analyses to accelerate: regulatory impact modeling, hospital value-mapping, and vendor benchmarking should be at the top of the list. PW Consulting stands ready to provide tailored briefings, custom market models, and due-diligence support drawn from the full Oxygenator Market study.
To access the full dataset, vendor scorecards, and executable playbooks referenced in this preview, please visit the PW Consulting Oxygenator Market research page or contact our advisory team for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Oxygenator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Foot Care Market to Reach $5.48B by 2032 at 6.84% CAGR — PW Consulting
By pmarketresearch, 2026-07-08
Foot Care Products Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies set priorities for 2026, the foot care products market presents a compelling mix of steady growth, technical fragmentation and regulatory inflection points. Our PW Consulting study — anchored on a 2025 base year with historical coverage from 2020–2025 and forward-looking forecasts to 2032 — finds the global market expanding from roughly USD 2.7 Billion in 2020 to an estimated USD 3.45 Billion in 2025, with projections to exceed USD 5.4 Billion by 2032 at a compound annual growth rate (CAGR) of approximately 6.84% over the 2026–2032 forecast window.
Foot Care Products Market
This briefing is designed as a strategic “teaser”: it surfaces the actionable trends and decision levers that will matter most to executives in 2026 while deliberately withholding detailed segment-level datapoints so that commercial, product and M&A teams will consult the full report for the granular inputs required to execute.
Foot Care Products Market
Why this matters for 2026 planning
- Predictable scale with room for differentiation: The market’s mid-single-digit CAGR and sustained increase in absolute market size create breathing space for new products, channel experiments and targeted M&A without requiring hyper-aggressive share-snatching plays.
- Fragmentation drives specialization opportunities: Low concentration among top players signals that focused plays — premium therapeutic formulations, clinically-oriented solutions for high-risk cohorts, or digitally enabled orthotic services — can scale commercially without immediate head-to-head confrontation with dominant incumbents.
- Regulation and reimbursement are fast-moving levers: 2026 is the year reimbursement pathways and certification frameworks materially affect provider behavior and payer access. Companies that align product design and go-to-market to these evolving rules will secure advantaged distribution into clinical channels.
Market trajectory and implications
From a sizing perspective, the market’s expansion is both organic and structural: consumer wellness habits, aging populations, and greater attention to preventive podiatric care underpin baseline growth, while medical reimbursement shifts and technical improvements in materials and sterilization protocols are unlocking higher-value clinical use cases.
Foot Care Products Market
For strategy teams, the arithmetic is straightforward. A market growing at roughly 6.8% annually across the forecast horizon favors measurable, staged investments: pilot launches and controlled geography rollouts in 2026–2027; scale-up and vertical integration (manufacturing, sterilization, clinical partnerships) in 2028–2030; and consolidation or strategic exits post-2030 as higher-margin niches solidify.
Competitive landscape — who to watch
The market is populated by a mix of consumer-focused brands, specialty device and formulation players, and regionally dominant clinical suppliers. Below are strategic profiles of several notable competitors that our clients frequently benchmark against:
- Aetrex Worldwide, Inc. (Princeton, NJ; https://www.aetrex.com) — Aetrex’s strength lies in blending hardware (orthotics, insoles) with digital diagnostics (foot-scanning and fit technologies). For 2026 strategies, they represent a benchmark for integrating technology-driven differentiation into retail and clinical channels.
- PediFix Inc. (Hauppauge, NY; https://www.pedifix.com) — Known for practical, consumer-oriented protection and comfort solutions (pads, wraps, blisters), PediFix exemplifies a playbook focused on wide retail distribution, low-cost manufacturing and brand trust in everyday-use categories.
- Alva-Amco Pharmacal Companies, Inc. (Sterling, VA; https://www.alvaamco.com) — With heritage in topical OTC formulations and private-label manufacturing, Alva-Amco is a case study in leveraging contract manufacturing and formulation know-how to serve both mass retail and professional dermatology/podiatry segments.
- Blistex Inc. (Oak Brook, IL; https://www.blistex.com) — Traditionally a consumer lip-care player, Blistex’s corporate capabilities in brand marketing and OTC product development illustrate how consumer healthcare firms can credibly diversify into adjacent foot-care balms and barrier formulations.
- Footlogix (Sammamish, WA; https://www.footlogix.com) — Positioned as a professional “pediceutical” brand, Footlogix shows how salon and clinic-first distribution can command premium pricing and professional endorsement — important for targeting higher-margin clinical channels and establishing therapy-backed claims.
- Diabetik Foot Care India Private Limited (Chennai, TN; https://www.diabetikfootcare.com) — An example of a geographically focused specialist targeting diabetic foot care and related high-risk cohorts. Their model highlights the commercial potential of tailored solutions in large emerging markets with growing chronic disease burdens.
Across the competitive set, success factors converge on three themes: clinical credibility, scalable manufacturing/sterilization capability, and omnichannel access (retail + clinical + e-commerce). Our full report maps capability matrices and channel economics for each player.
Regulatory, reimbursement and operational dynamics
Two regulatory/reimbursement developments in 2026 are particularly consequential:
- Regulatory approval landscape: Recent approvals for OTC foot care formulations underscore an easing pathway for novel topical products when supported by robust safety data and appropriate labeling. Companies investing in clinical evidence generation can accelerate market entry.
- Reimbursement & certification shifts: Changes to local coverage determinations and Medicare coding mean that certified nurses holding recognized foot-care credentials may deliver certain at‑risk foot care services under physician supervision. This broadens institutional access for products validated for clinical use and creates a new buyer segment within health systems and home health networks.
Operational standards are tightening too. Best-practice device reprocessing per Spaulding classification and manufacturer-specified sterilization cycles are now routine expectations in clinical purchasing decisions. Single-use accessoryization (e.g., disposable emery bands) and clear manufacturer sterilization protocols materially influence procurement choices and total cost of ownership calculations.
What the full PW Consulting report delivers (actionable contents)
We design the full study to be execution-ready for commercial, product and corporate development teams. Key deliverables include:
- Validated market-size models (2020–2032) and scenario analyses calibrated to alternative macroeconomic and reimbursement outcomes.
- Segmentation matrices by product, category and region with interactive sensitivity sliders for custom planning (note: detailed segment tables are available in the paid report).
- Channel and route-to-market economics: retailer margins, clinical procurement dynamics, and DTC/e‑commerce unit economics.
- Regulatory and reimbursement playbooks: required certifications, coding strategies, and payer engagement templates tied to the latest CMS and professional association guidelines.
- Manufacturing & sterilization benchmarking: supplier directories, quality checklists, CAPEX/OPEX models for in-house vs contract reprocessing, and compliance checklists aligned to Spaulding protocols.
- Competitive capability maps and M&A target shortlists, including valuations and integration risk assessments for tuck-in vs platform deals.
- Practical go-to-market plans and 18–36 month pilots for three strategic archetypes: consumer scale, clinical premium, and diagnostic-enabled orthotic platforms.
Decision playbook for 2026
- Prioritize clinical validation now: invest in limited clinical trials or real‑world evidence projects tied to reimbursement pathways. This accelerates access to institutional channels unlocked by 2026 credentialing shifts.
- Secure sterilization-certainty: ensure manufacturing and packaging are aligned with required sterilization cycles and single-use accessory standards; this reduces friction in clinical procurement.
- Test adjunct digital services: pilots of foot-scanning or tele-podiatry tied to product bundles can unlock higher lifetime value and stronger differentiation without heavy initial CAPEX.
- Balance channel focus: pursue a hybrid model where consumer retail fuels volume while higher-margin clinical products and professional partnerships protect profitability and limit commoditization.
Frequently asked technical & compliance questions
- What sterilization and reprocessing standards should product teams design for?
Design to meet Spaulding-classification reprocessing where applicable. For components intended as single-use (e.g., emery bands), reflect that in packaging and master-case economics. Where reprocessing is required, specify manufacturer-recommended steam sterilization cycles and validate via biological indicators to satisfy institutional procurement policies.
- Which certifications materially affect clinical adoption?
Recognition by professional bodies and alignment with clinically recognized certifications for providers increases product uptake. Also consider seals or endorsements that demonstrate impact on normal foot function and clinical utility when targeting podiatry or orthotics buyers.
- How should firms approach reimbursement engagement?
Map product use-cases to specific payer rules and local coverage determinations. If products address at-risk cohorts, ensure provider credentialing requirements and documentation templates are embedded into sales materials to minimize denials and administrative friction.
Conclusion and next steps
The foot care products market is attractive for 2026 investment: large enough to matter, fragmented enough to permit targeted wins, and dynamic enough that regulatory and clinical trends can be leveraged for disproportionate advantage. The path to outsized returns runs through clinical credibility, sterilization and supply-chain certainty, and intelligent channel orchestration.
PW Consulting’s full Foot Care Products Market report contains the detailed segmentation tables, competitive financials, vendor scorecards and executable playbooks that teams need to convert this strategic preview into 2026 deals and launches. To access the comprehensive dataset, model files, and bespoke advisory options, please follow the link on our website to request the complete report and schedule a strategy briefing.
For detailed analysis of this topic, please visit the official page: Foot Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: American Ginseng Market Set to Grow at 5.2% CAGR Through 2032
By pmarketresearch, 2026-07-08
American Ginseng Market 2026: Strategic Imperatives for Boardroom Decisions
Executive preview
As companies plan capex, R&D, and market-entry playbooks for 2026, the American ginseng market presents a mix of steady expansion, regulatory complexity, and product-innovation opportunities. Our PW Consulting market study—anchored on a 2025 base year—shows the market has expanded from roughly USD 215 million in 2020 to USD 267 million in 2025, and is projected to reach about USD 383 million by 2032, implying a multi-year compound annual growth rate (CAGR) of roughly 5.2%. These headline figures encapsulate predictable growth that supports near-term investment while highlighting longer-term upside for differentiated strategies.
American Ginseng Market
Why this report matters to corporate leaders in 2026
- Timing investment with growth: The mid-single-digit CAGR and the projected acceleration into the early 2030s mean that 2026 is a pivotal year to convert feasibility studies into staged investments—particularly in processing capacity, product formulation, and export logistics.
- Managing fragmentation: Market structure metrics indicate a highly fragmented supplier base (with the top-three and top-five players accounting for a minority share), so incumbent and new entrants alike must plan for consolidation risk, supply partnerships, or targeted M&A to secure scale advantages.
- Regulatory and compliance as strategic levers: Export controls and certification regimes materially affect unit economics and market access; proactive compliance and traceability programs can create defensible commercial advantages.
- Product and channel innovation: Advances in extract technologies and consumer-facing formats are expanding addressable use cases across supplements, functional foods, and personal care—a multi-channel go-to-market approach will be required to capture premium margins.
Macro trajectory and investment windows
The market’s historical growth from 2020 to 2025 demonstrates resilience through shifting consumer trends and supply dynamics. With the market size increasing year-over-year and a projected climb from the 2026 estimate into the high hundreds of millions by the early 2030s, executive teams should view 2026 as the first inflection window to operationalize scale investments. Key decision triggers include committing to processing lines that support value-added formats and sizing inventory strategies to mitigate raw-material seasonality without exposing balance sheets to elevated working capital risk.
American Ginseng Market
Competitive landscape — strategic read
Primary commercial participants in the American ginseng ecosystem include trade boards, large growers/processors, and private-label specialists. Their strategic postures illustrate the routes to market that will compete for industry returns in 2026 and beyond:
American Ginseng Market
- Trade & origin boards (e.g., Ginseng Board of Wisconsin): Function as market shapers—authenticity seals, wholesale showrooms, and export-promotion activities create institutional trust and a pathway for premium-positioned origin branding. Recent public funding to support export promotion and packaging underscores how board-level initiatives can lower barriers to international expansion.
- Bulk suppliers with private-label capabilities (e.g., Wisconsin Grown Ginseng LLC): These operators compete on scale, consistency of raw material, and flexibility in packaging/formatting for commercial customers. Their value lies in meeting the needs of manufacturers seeking predictable supply and turnkey private-label execution.
- Product specialists (e.g., Dairyland Ginseng): Focused on finished goods—tea lines, private-label teas and herbal products—these firms are adept at translating raw-material provenance into consumer-facing propositions, an increasingly important source of margin capture.
Recent moves in the broader ecosystem—such as the launch of water-soluble American ginseng extracts and increased industry representation at summits on sustainability and packaging—signal that product innovation and sustainability credentials will be decisive differentiators in the next 12–36 months.
Regulatory and certification dynamics
Regulatory frameworks and origin certification are non-trivial determinants of market access and price realization. U.S. export controls require dedicated permitting workflows for commercial shipments, and state-level certification programs establish the documentation necessary to move product across borders. For export-oriented strategies, alignment with permitting authorities and adoption of recognized seals of authenticity are operational prerequisites. Companies that embed compliant traceability into procurement and packaging processes will find it easier to secure premium channels and international buyers.
Supply chain, sourcing, and risk mitigation
American ginseng remains a crop with seasonality and concentration risk. Supply security planning should address three dimensions simultaneously:
- Supplier diversification and contract structuring: Multi-year supply agreements with origins certified for compliance reduce volatility; however, covenant terms and price collars are essential to share risk across the value chain.
- Value-added processing investments: Building or partnering for extraction and water-soluble technologies can shift economics away from raw-root arbitrage toward higher-margin formulations that appeal to functional-food and pharma customers.
- Traceability and certification: Implementing end-to-end traceability—aligned to recognized seals—protects access to regulated export markets and platforms that require documented provenance.
Commercial plays and product strategies
Our analysis identifies three commercial plays with clear applicability in 2026:
- Premium origin branding: Leverage authenticity seals and origin stories to capture consumer willingness to pay in specialty channels and premium supplements—particularly important for players that control certified cultivation and can demonstrate sustainable practices.
- Innovation-led formulation: Invest in extract and solubility technologies to enable clean-label, functional ready-to-drink, and pharmaceutical-grade applications; these formats unlock new customer segments and higher ASPs.
- Private-label and B2B supply solutions: Build scalable private-label capabilities for large wellness brands and retailers that prefer turnkey product sourcing and customizable packaging—this play benefits manufacturers with robust quality assurance and flexible logistics.
M&A and partnership considerations
The current concentration metrics indicate a dispersed market with opportunities for strategic consolidation. For acquirers, attractive targets include vertically integrated growers with export-ready certifications, specialty processors with proprietary extraction capabilities, and brand owners with differentiated consumer propositions. Partnerships with trade boards and funded promotional programs can accelerate market entry into priority export regions without the full cost of greenfield expansion.
Practical contents of the PW Consulting report
This study is designed for executives and investment committees who need actionable inputs for 2026 decision cycles. It includes:
- Macro market sizing and demand modeling (base year 2025, historical 2020–2025, and forecast 2026–2032), with scenario analysis for conservative, base, and upside cases.
- Supplier and processing value-chain maps, including a raw-material risk-index and recommended contractual terms to manage seasonality.
- Regulatory matrix and export-play checklist outlining permitting pathways, certification requirements, and compliance timelines for major export corridors.
- Competitive profiling of leading origin boards, bulk suppliers, and private-label specialists—covering capabilities, go-to-market vectors, and partnership opportunities.
- Go-to-market playbooks tailored to three strategic archetypes: origin-branded premium, innovation-led formulators, and scale-focused private-label suppliers.
- Financial benchmarking and ROI scenarios for processing-capex, extraction-tech adoption, and targeted M&A.
- Packaging, sustainability, and traceability playbooks aligned to buyer and regulator expectations.
Recent industry developments to watch
Recent activity reinforces key takeaways from our modeling: product innovation is accelerating (notably new water-soluble extracts introduced in 2025), industry associations are pushing sustainability and packaging standards at major summits, and export-promotion funding has been allocated to origin boards to stimulate international demand. These developments point to a sharper bifurcation between commoditized raw-root supply and value-added, branded or formulated products commanding higher margins.
Strategic imperatives for 2026 decision-makers
- Prioritize supply security: Execute multi-year contracts, diversify sourcing, and fast-track certification to avoid mid-cycle supply shocks.
- Invest selectively in processing: Move up the value chain with extraction and solubility capabilities that serve functional foods and pharma applications.
- Build export-ready operations: Align packaging, documentation, and traceability to expedite access to international buyers, leveraging public export-promotion programs where possible.
- Design a layered M&A roadmap: Identify tuck-in targets that close capability gaps—especially in processing technologies and branded products.
- Use pricing and channel segmentation: Differentiate low-cost bulk supply from premium branded offerings; avoid a one-size-fits-all pricing strategy.
What we intentionally leave for subscribers
In line with our “trailer” principle, this introduction showcases strategic depth and essential executive takeaways while withholding detailed segmented tables and granular regional/application-level figures that are central to tactical planning. The full report contains exhaustive segmentation matrices, pricing curves by format, buyer-level demand elasticities, and downloadable supplier-contact templates—resources designed to move from strategy to execution.
Next steps
If your team is preparing investment approvals, RFPs, or supply agreements in 2026, this market study will accelerate decision cycles by converting market forecasts into executable playbooks. Access the complete report for the detailed tables, supplier lists, and plug-and-play commercial templates that power operational rollouts and M&A diligence.
For detailed analysis of this topic, please visit the official page: American Ginseng Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Disposable Lighters Market to Hit USD 344.8M by 2032 at 4.0% CAGR
By pmarketresearch, 2026-07-08
Disposable Lighters Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our new Disposable Lighters Market study. This article is written as a high-impact trailer: it demonstrates the analytical depth and the decision-ready perspectives contained in the full study while intentionally withholding granular segment-level figures to encourage executive teams to consult the complete report for transaction-grade details.
Disposable Lighters Market
Market snapshot: trajectory you cannot ignore
Using 2025 as the base year, the disposable lighters market has demonstrably recovered and expanded from its early‑decade base. Between 2020 and 2025 the market moved from the low‑hundreds to a materially larger base, and our forecasting framework projects continued growth through 2032. The model embedded in the report shows the market expanding at a steady compound annual growth rate of 4.0% across the 2026–2032 forecast window, with an implied acceleration in certain channels and product tiers driven by lifestyle trends, regulatory responses and supply‑side optimization.
Disposable Lighters Market
These headline dynamics translate into a predictable but strategically challenging environment for manufacturers, private labelers, distributors and investors: steady top‑line growth coupled with rising compliance costs, evolving consumer preferences and concentrated competitive forces that favour scale, design capability and regulatory agility.
Disposable Lighters Market
Why this report matters for 2026 corporate decisions
- Investment prioritization: Our integrated financial and regulatory scenarios let CFOs and strategy teams size the ROI for capital investment — from tooling and automation to new product lines — under multiple policy outcomes.
- Portfolio optimization: Operators must choose where to balance premiumization, value SKUs and refillable alternatives. The study maps margin profiles, SKU profitability and channel elasticity to guide SKU rationalization and NPD timing.
- Regulatory compliance as a competitive moat: With child‑resistant standards and single‑use restrictions rising globally, early movers in compliant design and EPR systems can reduce total cost of ownership and create barriers to late entrants.
- M&A and partnership playbooks: The report surfaces target archetypes and screening metrics for bolt‑on acquisitions, OEM partnerships and upstream supplier investments that accelerate scale and lower unit economics.
- Supply‑chain risk management: Sourcing strategies that trade off labour and input cost volatility against lead‑time and compliance risk are modelled and stress‑tested for 2026 capital plans.
What the full report contains (executive summary of deliverables)
- Comprehensive market sizing and validated historical series (2020–2025) with an audited baseline for 2025 and granular forecasts to 2032, including scenario variants reflecting regulatory stringency and material‑cost shocks.
- Market concentration analysis and competitive positioning maps that identify capability gaps and consolidation opportunities; our CR3 and CR5 concentration metrics are included to show market structure implications for strategy.
- Practical go‑to‑market playbooks for OEMs, branded players and private label distributors — covering distribution levers, pricing tactics, trade promotion ROI and assortment strategies for retail, e‑commerce and B2B channels.
- Regulatory impact models covering child‑resistant standards, single‑use plastics policies, trade restrictions and anticipated producer responsibility obligations — with cost pass‑through and margin impact scenarios.
- Supply‑chain diagnostic and sourcing playbook: cost‑curve modelling, supplier risk scoring, reshoring vs. nearshoring tradeoffs, and recommended contracting templates for component and fuel suppliers.
- Product and material transition roadmap that translates compliance imperatives into engineering requirements, prototype timelines and unit‑cost implications for bioplastics, metal hybrids and refillable architectures.
- Transaction support materials including target screening matrices, indicative valuation multipliers by archetype, and integration checklist items tailored to M&A in this sector.
- Model access: an interactive financial model used to generate the published scenarios (available to clients under license).
Competitive landscape: what incumbents and challengers are doing
The disposable lighters industry is marked by a mix of global branded giants, regional specialists, OEM heavyweights and niche luxury houses. Market concentration metrics indicate that the top three and top five players control a substantial portion of the market, creating high barriers to scale in price‑sensitive channels but opening niches for differentiation.
- Société BIC S.A. — Leverages unmatched global scale and brand recognition. Their strengths are mass distribution, cost leadership on high‑volume SKUs and compliance engineering for child‑resistant requirements. Strategic questions for BIC include expanding into higher‑margin utility products and accelerating sustainability programs to defend retail shelf space as regulations tighten.
- Tokai Corporation — A major OEM with a strong orientation toward safety and cost engineering. Tokai is well‑positioned to capture private label demand and serve firms seeking rapid compliance redesigns; their roadmap should prioritize flexible production cells to support both flint and electronic alternatives.
- Flamagas S.A. (Clipper) — Known for robust ignition systems and multi‑use utility features. Flamagas’ brand equity in repeat‑use designs suggests an opportunity to monetize refill ecosystems and accessory markets.
- Swedish Match (Cricket) — A global retail staple; its strengths lie in reliability and retail penetration. Strategic focus for Cricket will be balancing unit economics under EPR regimes while preserving availability in mass channels.
- Zippo Manufacturing Company — Commands the premium, lifestyle and EDC segment where margins are attractive and brand loyalty reduces price sensitivity; Zippo’s playbook should emphasize limited‑edition runs, serviceability and cross‑category brand extensions.
- NingBo Xinhai Electric Co., Ltd. — A Chinese volume manufacturer with scale benefits and design flexibility across both flint and electronic types. Their strategic value resides in cost competitiveness and quick turnarounds for global customers.
- Calico Brands, Inc. — A wholesale specialist that can exploit value channels and institutional purchases; margin pressure may require consolidation or vertical integration into upstream plastics and component supply.
- S.T. Dupont — Serves the luxury niche with high ASPs and craftsmanship; regulatory and material shifts are less disruptive to this segment, but sustainability credentials are increasingly important to high‑end consumers.
Collectively, these archetypes define strategic axes for competition: scale and cost, engineering and compliance, brand and premium differentiation, and OEM speed for private‑label partners.
Regulatory and supply‑side dynamics that will drive 2026 strategies
- Child‑resistant standards: Regulatory frameworks (for example, those enforced by consumer safety regulators) are now a de facto design requirement in many major markets — compliance timelines must be embedded in 2026 product roadmaps.
- Single‑use plastics and EPR: Expanded producer responsibility and single‑use restrictions are increasing compliance costs and shifting value toward refillable or recyclable designs; companies will need lifecycle cost models to defend price increases.
- Trade controls and import restrictions: Increasing scrutiny and tariffs in key markets are altering landed cost calculations and favouring diversified sourcing and local assembly options.
- Raw materials and labour volatility: While scale remains an advantage, capacity expansions in some manufacturing hubs have exposed manufacturers to labour and input cost swings that can erode low‑margin volumes; hedging and longer supplier contracts reduce exposure.
- Environmental externalities: With more than ten billion units produced annually, plastic waste is a structural reputational and policy risk; responsible companies will accelerate material substitution and take‑back programs.
A practical 2026 strategic playbook (eight decisive moves)
- Embed compliance into product design now: Convert regulatory timelines into product development milestones and test prototypes under expected standards.
- Segment your portfolio: Allocate R&D and capex to premium, refillable and compliant value SKUs based on margin and channel return expectations.
- Secure input cost and logistics: Negotiate multi‑year contracts for key plastics, metals and fuel components; evaluate nearshoring to mitigate trade and labour risk.
- Invest selectively in sustainability: Pilot bioplastic blends and recyclable hybrid structures where payback is demonstrated or where regulation mandates change.
- Use M&A to buy capability: Prioritize targets that add compliance engineering, patented ignition systems, or direct access to high‑growth channels.
- Revise commercial models: Rebalance channel incentives toward high‑margin e‑commerce and convenience formats; realign trade spend to SKU profitability.
- Activate scenario planning: Stress test 2026 budgets under higher‑cost, high‑regulation and trade‑restricted scenarios using the report’s integrated model.
- Communicate proactively: Prepare investor and retailer messaging on compliance, sustainability and total cost of ownership to protect price and reduce churn.
Our full report provides the quantitative backing, playbooks and model access needed to operationalize the moves above. This preview deliberately omits granular segment and regional allocations — those detailed splits, supplier lists, and the interactive forecast model are available only in the complete PW Consulting report and licensed deliverables.
Next steps
For boards, strategy teams and private investors preparing 2026 capital and M&A decisions, the Disposable Lighters Market study is designed to be the single source of truth: validated historical data, forward scenarios, competitive playbooks and an executable roadmap for product, supply chain and commercial transformation. To obtain full access to the report, the interactive model and tailored advisory services, please visit PW Consulting’s market research portal or contact your PW Consulting account lead for a demo and licensing options.
For detailed analysis of this topic, please visit the official page: Disposable Lighters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refrigerated Display Cases Market to Reach USD 16,140M by 2032 at 7.4% CAGR
By pmarketresearch, 2026-07-08
Refrigerated Display Cases Market: Strategic Outlook for 2026 Decision-Makers
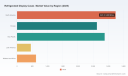
As clients recalibrate capital plans and product roadmaps for 2026, PW Consulting’s latest Refrigerated Display Cases Market study delivers the operational and strategic intelligence required to act with conviction. Built on a 2025 base year and detailed historical analysis from 2020–2025, our forecast through 2032 is grounded in rigorous bottom-up modeling and scenario stress tests. The headline: the market has expanded materially over the past five years and, at a compound annual growth rate of 7.4% through the forecast window, is on a path from roughly USD 9.8 billion in 2025 to an expected USD 16.1 billion by 2032. That trajectory reframes product, regulatory and go-to-market trade-offs for vendors, retailers and service providers entering 2026.
Refrigerated Display Cases Market
Why this study matters for 2026 decisions
-
Regulatory-driven product changes are no longer hypothetical. New rules around refrigerants and energy classes are compressing innovation timelines and creating retrofit markets that can be monetized if you move early.
Refrigerated Display Cases Market -
Procurement and manufacturing choices made this year will determine cost competitiveness for the next product cycle. Raw-material volatility and concentrated component supply chains mean lead times and margin pressure will vary by architecture and configuration.
Refrigerated Display Cases Market -
Channel economics are shifting: service and after-sales contracts (retrofits, refrigerant conversions, remote monitoring) are becoming strategic revenue streams rather than aftermarket niceties.
-
Consolidation dynamics and competitive positioning are clear enough to identify targets for partnerships or tuck-ins—but fine-grained share data and due-diligence metrics are essential before making M&A commitments.
What the report delivers (practical, executable content)
This study is designed as a decision-support tool for revenue, R&D, regulatory and M&A leaders. It combines:
-
Market sizing and unit/price triangulation across the historical (2020–2025) and forecast (2026–2032) windows—allowing scenario-level revenue and volume projections tied to product classes and installation types.
-
Regulatory impact modeling that translates refrigerant and energy-efficiency rules into retrofit demand curves, compliance timelines and incremental cost estimates for new builds versus replacements.
-
Technology and product roadmaps that benchmark plug-in, remote and semi plug-in architectures against operational metrics (energy, serviceability, footprint), with a prioritization matrix for R&D investment.
-
Supply-chain and cost-to-serve heat maps identifying single-source exposures, material cost sensitivities, and near-term supplier prioritization options.
-
Commercial playbooks: pricing strategies, warranty design, bundled service offerings, and channel segmentation to accelerate penetration while protecting margin.
-
Competitive dossiers and consolidation scenarios—including concentration metrics—that support target screening and valuation calibrations for potential acquisitions.
Competitive landscape: how the leader set is shaping strategy
The industry exhibits moderate concentration, with the top three and top five players controlling a meaningful share of global revenue—an arrangement that supports scale-driven investments in low-GWP refrigeration, digital controls and multicountry service networks. This structural backdrop favors firms that can combine product innovation with distribution reach and service execution.
-
Hussmann Corporation has doubled down on retail and foodservice merchandisers, emphasizing natural refrigerants and energy-efficient lighting; recent product introductions highlight thermal control advances that improve in-case shelf life and shrinkage economics.
-
Carrier Commercial Refrigeration leverages integrated store systems and smart controls, positioning itself for large format retail rollouts that value total-store energy optimization over unit price.
-
Zero Zone is a product-focused innovator with narrow-footprint and hybrid architectures that optimize space and energy—though regulatory pressures on hybrid solutions are forcing a short-term rethink of its installed-base playbook.
-
True Manufacturing continues to be recognized for durable reach-in and glass-door merchandisers, with a value proposition tailored to foodservice customers emphasizing uptime and serviceability.
-
Epta, Hillphoenix and Arneg (European manufacturers) are demonstrating how compliance-driven energy advances (and PFAS-free materials) can be turned into competitive differentiation for customers sensitive to sustainability credentials.
-
AHT, Kysor Warren, Hoshizaki and Frigoglass round out a diversified competitive set with strengths in specific channels—convenience stores, beverage retail, and international distribution—that make them attractive partners or acquisition targets depending on strategic aims.
Recent product-level moves illustrate the pace of innovation: Hussmann’s late-2025 reach-in merchandisers introduced air-cooled microblock technology to reduce temperature variance; Epta showcased a double-sided multideck at a prominent trade event highlighting floor-space efficiencies for independent retailers; Hillphoenix launched a CO2 system claiming dramatically lower amperage draw versus conventional units. These examples reflect the dual themes of energy efficiency and serviceability that will dominate buyer selection in 2026.
Market dynamics and risk map
-
Regulatory shifts: effective 2026 rules are accelerating retirements and conversions. Restrictions on certain hybrid architectures and low-GWP charge limits force design and installation trade-offs that materially affect BOM composition and service models.
-
Refrigerant transition: adoption of alternatives such as R‑290 and CO2 is increasing—designers must reconcile flammability, charge size, and transcritical performance with store-level constraints and safety codes.
-
Material and component risk: while 2025 saw moderated price volatility for steel, aluminum and glass, supply chain fragility remains. Decisions on localization, component standardization and inventory strategy should be prioritized this year.
-
Aftermarket opportunity: replacement cycles and mandated conversions create a multi-year revenue stream for retrofit services, parts and remote-monitoring subscriptions; firms that can scale field operations will convert regulatory headwinds into recurring income.
Strategic implications and recommended actions for 2026
Executives should treat 2026 as a decisive year to shift from defensive compliance to offensive growth. Recommended actions:
-
Immediate (0–6 months): conduct a portfolio compliance audit to identify non-compliant SKU lines and define a prioritized conversion map; implement a price/cost reset that reflects refrigerant replacement and servicing economics.
-
Near-term (6–18 months): launch retrofit pilot programs with performance guarantees and service-subscription models; accelerate low-GWP product launches with modular architectures to enable faster field conversions.
-
Medium-term (12–36 months): pursue targeted M&A to acquire regional service networks or component capabilities that shorten time-to-market for compliant products; invest in digital controls and remote diagnostics to reduce service costs and generate subscription revenue.
-
Supply-chain resilience: diversify component sourcing, lock long-lead contracts for critical materials, and qualify alternate glazing and insulation suppliers that meet energy and sustainability rules.
-
Organizational: establish a cross-functional regulatory task force combining engineering, procurement and sales to manage product lifecycles and customer communications through transitions.
How PW Consulting supports execution
PW Consulting’s Refrigerated Display Cases Market study is intentionally structured as an implementation reference. Beyond headline forecasting, the full deliverable includes downloadable financial models, retrofit demand calculators, supplier heat maps, and granular competitive dossiers—tools designed for CFOs, heads of product, and corporate development teams who need to quantify trade-offs and prioritize investments for 2026.
We intentionally maintain critical segment-level granularity and pricing matrices in the full report to preserve analytic integrity for clients conducting procurement negotiations, benchmarking, or M&A diligence. If you need the full dataset (regional/type/application splits, unit-level pricing curves, and channel share matrices) or a bespoke briefing aligned to your product and geographic footprint, request the complete report and modeling package on PW Consulting’s report page.
In short: the refrigerated display cases market is entering a phase in which regulatory timing, refrigerant strategy, and service capability determine winners. Organizations that align product design, supply chain and commercial models in 2026 will convert compliance pressures into sustainable growth—our study shows how to make those choices with data-backed confidence.
For detailed analysis of this topic, please visit the official page: Refrigerated Display Cases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Basmati Rice Market to Reach USD 315.1 Million by 2032 (CAGR 6.98% 2026–32)
By pmarketresearch, 2026-07-08
Basmati Rice Market 2026: Strategic Imperatives for Growth and Resilience
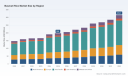
As PW Consulting’s Senior Strategic Advisor and Head of Industry Analysis, I present this forward-looking introduction to our Basmati Rice Market study. Grounded on a 2025 base year and a comprehensive historical review (2020–2025), the study projects the sector through 2032. At the consolidated level the market grows from an estimated USD 147.5 million in 2020 to roughly USD 198.0 million in 2025 and is forecast to reach about USD 315.1 million by 2032 — an implied compound annual growth rate (CAGR) of approximately 6.98% across the forecast horizon. These headline metrics frame material opportunities and risks that will shape corporate decisions in 2026 and beyond.
Basmati Rice Market
Why this report matters for 2026 decision cycles
-
Policy volatility is now a primary commercial variable. Recent regulatory shifts — including the lifting and reconfiguration of export controls in major supplying countries, and trade interventions that materially alter tariff landscapes — have already changed landed-cost calculus for key destinations. These moves have immediate implications for sourcing, inventory strategy and pricing tactics in 2026 procurement cycles.
Basmati Rice Market -
Market fragmentation and differentiated consumer demand are accelerating premiumization. Although headline growth is attractive, the market remains relatively unconsolidated, creating runway for brand-building, private-label growth, and regional champions. Strategic choices around channel positioning and product variants will determine margin capture as demand for both value and premium aromatics expands.
Basmati Rice Market -
Operational and reputational risk has risen. Recent product-safety events at large retailers and high-profile recalls underline the need for tightened quality systems, end-to-end traceability and rapid-response recall playbooks — all of which must be reflected in 2026 CAPEX and supplier-auditing plans.
-
Climate and input-side innovations are creating structural shifts in cost and supply. Advances in seed technology and cultivation practices designed to lower water intensity and input costs are no longer experimental: some varieties optimized for direct-seeded rice (DSR) cultivation are entering commercial use, influencing long-run supply curves and sustainability credentials.
Key market dynamics to inform strategy
-
Demand drivers: Growing global middle classes and continued diasporic consumption underpin steady retail and foodservice demand for aromatic rice. Premium segments (convenience-ready formats, value-added pack sizes, and certified sustainability labels) are expanding faster than aggregate volume, demanding differentiated commercial approaches.
-
Supply constraints and adaptations: Water scarcity, land-use competition and input inflation are pushing producers to adopt higher-yield, water-efficient varieties and to rethink crop rotations. Institutional supports — export registration systems, allocation certificates and targeted seed programs — are shaping who can scale reliably and who remains exposed to seasonality risks.
-
Trade and tariff environment: Tariff actions and export policy adjustments have meaningfully reshuffled near-term competitiveness among origin countries in major import markets. Firms must incorporate scenario-based landed-cost models that reflect asymmetric tariff treatments and the possibility of sudden policy reversals.
-
Quality, safety and traceability: The commercial fallout from retail recalls highlights two imperatives — (1) rigorous supplier qualification and in-market quality assurance, and (2) investment in traceability systems that enable rapid consumer and regulator responses. These are non-negotiable elements of market access in developed retail environments.
Competitive landscape — structure and strategic posture
The Basmati rice sector remains fragmented: the three- and five-firm concentration ratios are modest, a structural signal that no single incumbent dominates. This creates three strategic implications for 2026:
-
Opportunity for consolidation and scale-driven cost playbooks — buyers with M&A mandates can find value in roll-up strategies focused on supply-chain integration and compliance capability.
-
Room for differentiated brand and route-to-market plays — agile suppliers can protect margin by building premium positioning tied to origin stories, sustainability credentials and differentiated packaging.
-
Persistent arbitrage and price competition — fragmentation keeps procurement competition intense, so margin protection requires operational efficiency and tighter collaboration with growers.
Representative players and ecosystem actors highlighted in our study include a mix of private producers and industry associations. For example, a U.S.-headquartered firm known for its hybrid aromatic long-grain offerings has pursued non-GMO, kosher and sustainable lines that position it well in premium retail channels. Meanwhile, national exporter federations and trade associations play decisive roles in market access, policy advocacy and export facilitation for their members. Their activities materially affect trade flows, compliance timelines and market-entry costs.
Recent developments underscore these dynamics: a major U.S. retailer initiated a voluntary recall tied to insect contamination, demonstrating the practical consequences of gaps in cold-chain and storage hygiene; leading agricultural research institutes have commercialized DSR-optimized basmati varieties to lower water use; and exporters from key origins have been actively engaging U.S. distributors as tariff and policy shifts rewrite competitive economics. Our study synthesizes these events into quantified impact scenarios for revenue, margin and inventory risk.
What the PW Consulting report delivers — practical, transaction-ready tools
The full study is built to support commercial decisions in 2026 and includes:
-
Proprietary market-sizing and multi-scenario forecasts (2026–2032) anchored to 2025 baseline data, with sensitivity analyses for demand elasticity, tariff shocks and yield improvements.
-
Channel-specific demand maps for retail, foodservice and industrial customers, together with SKU-level profitability templates and shelf-space optimization models.
-
Supply-chain deep dives: origin cost curves, input-risk matrices, cold storage and logistics bottleneck maps, plus supplier scorecards that operational teams can implement immediately.
-
Regulatory and trade-playbook: a calendar of likely policy triggers, compliance checklists for prioritized markets and tariff-mitigation pathways (including alternative routing and tariff-smoothing mechanisms).
-
Commercial playbooks and go-to-market blueprints: private-label vs. branded launch scenarios, pricing ladders, promotion cadences and retailer negotiation scripts tailored to 2026 buying cycles.
-
M&A and partnership screening: a shortlist framework and valuation-sensitivity model designed to identify accretive targets that deliver immediate procurement synergies or route-to-market access.
-
Operational risk tools: a contamination-prevention checklist, recall-response templates and a traceability-technology selection guide mapped to cost and time-to-implement targets.
To respect strategic confidentiality and to maintain the "trailer" principle of this communication, the report’s granular segmentation tables, origin-by-destination trade flows, and SKU-level revenue forecasts are intentionally summarized here. These detailed matrices and interactive models are available in the full downloadable study.
How to apply these insights in 2026 — a short action agenda
-
Re-balance sourcing portfolios: introduce origin diversification targets tied to tariff and logistical scenarios; lock minimal coverage for critical SKUs while piloting alternative origins for non-core assortments.
-
Invest in upstream traceability and vendor development: prioritize digital traceability pilots with high-volume suppliers and mandate third-party audits for all strategic suppliers within 12 months.
-
Accelerate product tiering: launch a two-track portfolio — value-focused SKUs for cost-sensitive channels and premium, certified lines leveraging origin and sustainability claims for differentiated margins.
-
Embed scenario-based pricing: adopt dynamic landed cost models that update for tariff shifts, freight volatility and yield outcomes; build contractual flex in supplier agreements to share upside/ downside.
-
Prepare for rapid recall scenarios: pre-define roles, supplier isolation procedures and customer communication templates; test the playbook with tabletop exercises in Q3 2026.
-
Explore strategic consolidation opportunities: use our M&A screening tool to evaluate whether bolt-on acquisitions unlock scale benefits in procurement or fill capability gaps in traceability and quality assurance.
Conclusion — why PW Consulting’s study is a 2026 must-read
The Basmati rice market is maturing into a strategically important, moderately growing segment with asymmetrical risks and clear arbitrage opportunities. Our analysis combines macro-calibration (2020–2025 historicals and a 2026–2032 forecast anchored at a ~6.98% CAGR) with transaction-ready tools to help commercial, procurement and corporate development teams make decisive choices in 2026. Because high-value decisions require granular, validated inputs, we have intentionally withheld detailed segmental tables and SKU-level forecasts from this summary. For the complete dataset, interactive models and the full suite of implementation playbooks, access the PW Consulting report download page.
Contact PW Consulting to schedule a briefing where we’ll walk your team through the report’s scenario models and tailor a 90-day action plan aligned to your commercial priorities for 2026.
For detailed analysis of this topic, please visit the official page: Basmati Rice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Electrodes Market to hit USD 1,922.4M by 2032 at 5.2% CAGR
By pmarketresearch, 2026-07-08
Medical Electrodes Market 2026: Strategic Briefing for Decision-Makers
Executive snapshot
As PW Consulting’s lead industry analyst, I present a concise strategic briefing to orient executive teams, product leaders, and investors ahead of planning cycles in 2026. The global medical electrodes market has expanded steadily through the first half of the decade and is projected to continue growing at a mid-single-digit pace. This briefing highlights the macro trajectory, regulatory and reimbursement inflections, competitive dynamics, and the practical, decision-ready insights embedded in our full market study — while intentionally reserving the granular segment matrices that underpin deal-level and product-level plays (available in the full report).
Medical Electrodes Market
Market trajectory: 2020–2032 at a glance
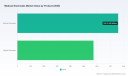
The market moved from just over USD 1.07 billion in 2020 to approximately USD 1.33 billion by the 2025 base year, tracking an aggregate uplift that reflects both durable clinical demand and episodic product refresh cycles. Our forecast through 2032 projects continued expansion, with the market following a compound annual growth rate (CAGR) of approximately 5.2% over the forecast window. By 2032, the topline approaches the USD 1.9–2.0 billion range under the base forecast scenario, driven by a mix of device upgrades, broader adoption of monitoring in ambulatory settings, and incremental neuromodulation use cases.
Medical Electrodes Market
Importantly, the growth path is not perfectly linear — the model captures near-term acceleration tied to product launches and reimbursement clarity, as well as short-term volatility from raw-material inflation and episodic capital spending cycles. These non-linearities create tactical windows for market entry, premiumization, and M&A that are time-sensitive for 2026 planners.
Medical Electrodes Market
Why this matters for 2026 decisions
- Procurement & cost management: Hospitals and OEMs faced rising consumables costs through 2020–2025 (average annual increases in medical and surgical supplies were material), altering total cost of care calculations. Buyers and suppliers must align contracts and price-index clauses to mitigate pass-throughs of material inflation into 2026.
- Regulatory timing is a gating factor: ISO 10993 biocompatibility expectations and FDA pathways (including 510(k) requirements for novel electrode designs and MR-conditional claims) remain material to time-to-market. Recent guidance tightens testing expectations for long-term adhesion and signal fidelity — a critical design constraint for neuromonitoring and implantable-adjacent applications.
- Reimbursement enables new use cases: 2026 updates to procedural and HCPCS coding have clarified billing pathways for several advanced electrode arrays. These code changes convert previously unfunded pilot programs into viable commercialization targets, particularly in outpatient and device-assisted stimulation settings.
- Portfolio and R&D prioritization: With mid-single-digit market growth, incremental share gains come more from product differentiation and channel optimization than from category expansion alone. R&D allocation should prioritize demonstrable clinical outcomes (signal accuracy, adhesion, skin tolerability) and economic value (longer wear, lower replacement frequency).
- M&A and partnerships: The market concentration metrics indicate a moderately consolidated supplier base at the top. Strategic roll-ups of adjacent technologies (thin-film intracranial electrodes, smart reusable electrodes, disposables optimized for home-monitoring) are credible routes to fast-track access to new clinical segments.
What PW Consulting’s full report delivers (practical content)
Our full market study is designed as an operational toolkit for executives committing resources in 2026. Key deliverables include:
- Dynamic market model with annualized topline and scenario runs (base, downside, upside) for 2026–2032, allowing users to test assumptions such as reimbursement shifts, material-cost shocks, and adoption curves.
- Go-to-market playbooks for hospital procurement, commercial-scale OEM partnerships, and direct-to-consumer monitoring channels — each with margin and volume thresholds for profitable scale.
- Regulatory and clinical pathway maps, including testing protocols aligned to ISO 10993 and the current FDA expectations for MR-conditional and long-wear adhesives.
- Competitive positioning matrices and qualitative vendor scorecards based on product breadth, innovation cadence, geographic strength, and channel control — optimized for rapid target screening.
- Unit-cost and pricing models built from primary supplier interviews and cost-buildup analysis, enabling negotiation benchmarks and SKU rationalization.
- Actionable M&A shortlist with flags for strategic fit, integration complexity, and time-to-revenue for bolt-on acquisitions or licensing deals (data room-ready dossiers for prioritized targets).
- Supplier risk heat maps that correlate single-sourced raw materials, contract manufacturer dependency, and geography-specific supply-chain exposure.
To preserve the competitive value of this intelligence we present segment-level forecasts, channel shares, and price ladders only within the full report — a deliberate packaging choice to support client decision confidentiality and to prevent tactical leakage.
Competitive landscape — strategic reads on leading players
The supplier ecosystem ranges from diversified medical device majors to specialized electrode technology firms. Below are high-level strategic interpretations of select players included in our competitive analysis:
- Ambu A/S: Positioned as an innovation-focused supplier of disposable electrodes, Ambu’s recent launches underscore an emphasis on signal clarity and patient comfort. Their execution model — combining product refresh cadence with broad distribution — makes them a logical partner for hospital trials and OEM co-development.
- 3M Company: A category stalwart with strong brand trust in monitoring electrodes. Recent product introductions aim at vulnerable cohorts (paediatric and geriatric), opening channels in specialty care and home-health kits. Their scale enables aggressive commercial programs but also invites scrutiny on margin resilience in pricing negotiations.
- Medtronic plc: Leverages deep neurology and cardiac franchises to bundle electrodes with higher-value systems (EEG, DBS, electrosurgery). Their product roadmap emphasizes incremental performance gains that justify premium positioning in procedural segments.
- Nihon Kohden Corporation: Strong in reusable and “smart” electrode systems, with a focus on integrating diagnostics and telemetry. Their advantage is clinical trust in neurodiagnostic settings and an R&D pipeline targeting long-term monitoring solutions.
- CONMED, ZOLL, B. Braun, Cardinal Health: These players emphasize breadth across monitoring and electrosurgical neutral electrodes, leveraging channel relationships with hospitals and ambulatory surgery centers. Their strategies balance private-label volume plays with branded innovation in subcategories.
- Specialists & innovators (Natus, Rhythmlink, NeuroOne, Ad-Tech, Nissha, KLS Martin): A set of smaller, often highly technical firms compete on niche performance attributes — thin-film intracranial electrodes, SEEG, subdermal disposables, and high-fidelity EEG/EMG sensors. These companies are frequent acquisition targets for larger OEMs seeking specialty capabilities.
Market concentration is meaningful but not prohibitive for new entrants: the top-tier vendors control a substantial share of the market but leave clear white space for differentiated technologies and service models, particularly those that reduce total cost of ownership or unlock new reimbursement pathways.
Near-term industry dynamics to incorporate into 2026 plans
- Regulatory constraint and opportunity: FDA 510(k) clearance remains the common path for many electrode innovations, with increasing scrutiny on MR-conditional claims and long-term adhesion testing; aligning product development milestones to these requirements shortens commercialization timelines.
- Reimbursement shifts: Updated CPT and HCPCS codes in 2026 create explicit billing pathways for certain electrode arrays used in nerve stimulation procedures, improving return-on-investment for targeted clinical pilots.
- Input-cost inflation: Rising raw-material and supply-chain costs materially affect unit economics for disposables; cost-optimization and alternate sourcing strategies are essential to sustaining margin targets.
- Clinical demand drivers: Aging populations, expanded ambulatory monitoring, and growth in neuromodulation therapies are sustaining demand, but commercial success requires demonstrating both clinical differentiation and economic value.
Recommended 90–180 day moves for 2026
- Finalize regulatory gap analysis for any product slated for 2026–2027 launch; prioritize submission paths that align with the new FDA testing expectations.
- Lock preferred-supplier agreements with indexed pricing clauses to mitigate further material-cost shocks.
- Initiate 2–3 focused clinical pilots in reimbursement-favorable settings to generate the HTA and cost-effectiveness evidence required by payors.
- Screen the M&A shortlist in our annex and commence confidential outreach for at least one strategic bolt-on that accelerates access to intracranial or thin-film electrode capabilities.
- Rebalance R&D portfolios toward features that enable clear reimbursement capture (e.g., wear-time extensions, integration with remote monitoring platforms, and validated signal-accuracy claims).
Accessing the full intelligence
This briefing is intentionally high-level to catalyze strategic alignment in 2026 planning cycles. The full PW Consulting Medical Electrodes Market report contains the granular segment economics, channel shares, pricing ladders, and vendor-level scorecards necessary for live commercial decisions and transaction due diligence. For teams preparing budgets, negotiating supplier agreements, or evaluating bolt-on acquisitions, that level of granularity is mission-critical — and available through our official distribution channels.
PW Consulting remains available to support bespoke scenario modeling, M&A diligence, and regulatory readiness planning derived from our proprietary dataset and primary interviews. In a market growing at roughly 5.2% annually with meaningful near-term regulatory and reimbursement inflections, disciplined, data-driven moves in 2026 will materially shape competitive position through the next business cycle.
For detailed analysis of this topic, please visit the official page: Medical Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vegan & Processed Cheese Market to Reach $28.89M by 2032 at 7.26% CAGR
By pmarketresearch, 2026-07-08
Vegan Cheese and Processed Cheeses Market: Strategic Imperatives for 2026
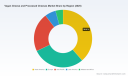
As companies position for growth in a market that bridges traditional dairy processing and rapidly evolving plant-based innovation, PW Consulting’s latest Vegan Cheese and Processed Cheeses Market study (base year 2025; historical 2020–2025; forecast 2026–2032) provides a pragmatic roadmap for corporate decision‑makers in 2026. The sector is expanding at a mid‑single‑digit to high‑single‑digit compound annual growth rate (CAGR 7.26%), reflecting steady demand and continued product innovation. Our bottom‑up sizing shows the market recovering and expanding from the mid‑2020s and approaching the upper‑twenty millions (USD, revenue unit: Million) by the end of the forecast window—an environment that rewards clarity on product positioning, channel economics and manufacturing scale.
Vegan Cheese and Processed Cheeses Market
Why this study matters for 2026 corporate strategy
- Decision clarity under margin pressure: Retail indicators and our channel models show pricing pressure on plant‑based SKUs even as new niches emerge. The study quantifies how a modest downward shift in average retail price interacts with unit volumes to compress gross margins—essential when allocating R&D, marketing and capex in 2026.
- Portfolio prioritization and SKU rationalization: With household penetration still constrained and evolving taste trade‑offs, companies must prioritize SKUs that deliver differentiated consumer utility (melt, spreadability, artisanal profile) rather than broad SKU proliferation. The research contains a prioritization framework and ROI thresholds tuned to the market’s growth and cost structure.
- Channel economics and go‑to‑market playbooks: The report maps profitable routes to market across retail, foodservice and industrial ingredient channels and offers retailer negotiation scripts and trade promotion models that preserve margin while supporting distribution expansion.
- Manufacturing and scale decisions: Our cost benchmarking highlights break‑even thresholds for co‑packing versus owned capacity across plant‑based bases (nut/bean/oil matrices) and conventional processed cheese lines—insight critical to 2026 capex and footprint choices.
What the full report contains (practical, operational outputs)
- Actionable market sizing and near‑term scenario forecasts (base 2025; forecast 2026–2032) with sensitivity to price, penetration and commodity input swings.
- Segment definitions and a commercialization matrix that ties product attributes (melt, flavor profile, dairy‑free claims, certifications) to channel demand and willingness to pay—plus playbooks for premiumization vs cost leadership.
- A modular financial model (Excel) enabling rapid assessment of SKU launches, private label bids, co‑packing arrangements and M&A valuations under multiple scenarios.
- Supply chain and input cost analysis, including emulsifiers, protein analogues and packaging pathways, with vendor scorecards and a supplier negotiation toolkit.
- Regulatory and labeling risk matrix, including trade‑policy and food‑safety triggers that materially affect go‑to‑market timing and consumer communications.
- Commercial templates: retailer negotiation decks, foodservice menu concepts, and industrial ingredient sales packages.
- Competitive playbooks and a screened M&A target list (by strategic fit and execution complexity), supported by integration risk checklists.
Competitive landscape — what to watch in 2026
The market shows moderate concentration—indicative of space for challengers and niche specialists. Across the competitive set, there is a clear divide between artisan, branded vegan specialists and large processed‑cheese incumbents pursuing scale and distribution advantages.
Vegan Cheese and Processed Cheeses Market
- Miyoko’s Creamery (Sonoma, CA): Artisanal positioning and fermentation‑led taste differentiation give Miyoko’s a premium play. For rivals, the implication is twofold: premium consumers tolerate higher price points and seek provenance; meanwhile, artisanal scalability is constrained without targeted investments in manufacturing automation.
- Violife (Netherlands): Global reach and a broad SKU range make Violife a defensive, wide‑spectrum player in mainstream retail. Competitive responses should factor in rapid SKU turnover and shelf space dynamics when negotiating category resets.
- Daiya Foods (California, USA): Known for melt‑capable formulations, Daiya’s recent flavor innovations illustrate the continuing role of technology in maintaining relevance—especially in foodservice and consumer segments demanding functional parity with dairy.
- Kite Hill (California, USA): Nut‑milk bases and premium positioning reinforce the bifurcation of the market between indulgence and value propositions. Partners and acquirers should evaluate the scale‑up path to meet retail listing minimums without diluting brand equity.
- Hochland SE (Germany), Groupe Bel (France), Kraft Heinz (USA): These incumbents bring manufacturing scale, established distribution and category management heft. Their plays—whether defensive on price, selective on plant‑based offerings, or opportunistic M&A—will define competitive thresholds for margin and shelf access.
Recent corporate moves illustrate this dynamic: a major European player discontinued a plant‑based brand and closed a production site in 2025, signaling the risk of non‑performing assets and the need for rigorous portfolio review. Conversely, acquisitive activity and new product launches among niche players emphasize continued innovation and the enduring attractiveness of premium artisanal formats.
Vegan Cheese and Processed Cheeses Market
Market dynamics and consumer context
- Demand signals: Retail data show a decline in plant‑based cheese dollar and unit sales in 2025, while average retail prices decreased modestly. At the same time, household penetration remains low—underscoring that category expansion is still an active, not mature, growth opportunity.
- Price and value tension: The drop in average retail price in 2025 has amplified the importance of cost control and value engineering for producers and private label manufacturers. The report quantifies the impact of small price movements on EBITDA across typical operating models.
- Consolidation runway: A fragmented supplier base and differentiated product archetypes create fertile ground for targeted acquisitions—particularly to acquire branded innovation or regional manufacturing capacity at attractive multiples.
Implications & recommended strategic moves for 2026
- For incumbents in processed cheese: Use 2026 to pilot plant‑based SKUs that leverage existing production lines where feasible, but maintain financial discipline—only scale SKUs that meet defined margin and distribution thresholds.
- For pure‑play vegan brands: Prioritize channel mix optimization (strengthen foodservice and DTC where functional advantages play best) and secure flexible manufacturing partnerships to manage seasonality and promotional volatility.
- For retailers and foodservice operators: Re‑segment assortment by consumer occasion and value tier; deploy localized merchandising to lift household penetration without eroding price architecture.
- For investors and M&A strategists: Target bolt‑on artisanal brands with strong IP in formulation or fermentation and clear scale pathways; avoid assets with unsustainable trade promotion burdens unless there is a credible cost transformation plan.
- For ingredient and equipment suppliers: Focus on melt/emulsion technologies and cost‑down solutions; co‑development partnerships can accelerate adoption and create stickier customer relationships.
Methodology & credibility
The study’s base year is 2025, with historical trends reviewed across 2020–2025 and a forecast horizon of 2026–2032. PW Consulting triangulated retail scanner data, manufacturer interviews, company filings, trade statistics and on‑the‑ground channel checks. Forecasts are produced via a bottom‑up model, validated with top‑down market checks and scenario sensitivity analyses. Deliverables include the underlying financial model and executive playbooks to move from insight to commercial execution.
Next steps — how to extract full strategic value
This executive overview is designed to establish the strategic contours and high‑value implications for decision‑making in 2026. The full report contains the detailed segmentation, granular regional and application breakdowns, SKU‑level economics, and downloadable models you need to execute on the strategies sketched here. Access the complete study to view the tables, company profiles, and transaction screening outputs that will enable prioritized action in the coming 12–18 months.
For detailed analysis of this topic, please visit the official page: Vegan Cheese and Processed Cheeses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fireworks Market Poised for 6.5% CAGR — Strategic Outlook
By pmarketresearch, 2026-07-08
Fireworks Market 2026: Strategic Intelligence for Decisions that Spark Value
As enterprises, investors and public-sector planners prepare strategies in 2026, the global fireworks market presents a distinct blend of resilient growth dynamics, legacy manufacturing concentration, emergent safety and regulatory pressures, and accelerating demand-side innovation. PW Consulting’s new Fireworks Market study (base year 2025, historical period 2020–2025, forecast 2026–2032) synthesizes quantitative market-size trajectories with qualitative scenario analysis so leaders can make informed, time-sensitive choices. This article highlights the report’s strategic value for 2026 decision cycles while purposefully omitting detailed sub-segment tables to encourage direct access to the full intelligence product.
Fireworks Market
Macro picture: a compact market with steady momentum
The fireworks market is characterized by modest absolute scale but steady expansion. Between 2020 and the 2025 base year, the market moved from a lower base through consistent year-on-year growth. With a compound annual growth rate (CAGR) of 6.5% projected for the forecast period, the market is expected to continue expanding from the 2025 base into the early 2030s. By 2026 the market is poised to register a notable uplift as pent-up event demand, product innovations and geographic recovery converge; projections in our study extend through 2032 to map longer-tail scenarios and sensitivity to regulatory shocks.
Fireworks Market
Why this matters for 2026 decisions
- Timing of investment and capacity decisions. The market’s steady CAGR means that incremental capacity additions and targeted capital expenditure can still yield attractive returns—provided they are timed to avoid short-term regulatory or production interruptions. Our report provides validated demand curves and scenario-based timing recommendations so procurement and operations leaders can phase investments rather than overcommit to cyclical peaks.
- Supply-chain and sourcing risk management. A concentrated manufacturing geography remains central to global supply. Disruptions in key clusters have outsized system effects—making dual-sourcing strategies and near-shoring analyses high-priority items for 2026 supply agendas. The report models supplier interruption scenarios and quantifies inventory strategies tied to different risk tolerances.
- Regulatory and reputational risk calibration. 2026 will be a pivotal year for compliance-led decisions: recent safety incidents have prompted intensified scrutiny and temporary enforcement actions. Our dynamics chapter maps likely regulatory trajectories across major jurisdictions and translates them into compliance cost bands and timeline impacts for product certification, testing and transport protocols.
- Portfolio and go-to-market optimization. Manufacturers and event producers must reconcile traditional product lines with experiential offerings—large-scale displays, indoor pyrotechnics, hybrid live-digital spectacles, and in some markets non-pyrotechnic alternatives. The study offers playbooks for portfolio rationalization, channel prioritization, and pricing tactics that reflect seasonality and event-driven demand.
What the report contains (practical, executable assets)
- Market-sizing model (2020–2032) with baseline and three stress-case scenarios, delivered in spreadsheet-friendly format for board-level what-if analysis.
- Segment and application-level growth drivers with qualitative overlays on seasonality, festival calendars and B2B event pipelines—presented as decision-ready narratives rather than raw tables.
- Supply-chain risk maps that identify single-point-of-failure suppliers, critical raw-material dependencies and logistics chokepoints, with mitigation playbooks and inventory heuristics for each risk tier.
- Regulatory-impact framework that translates safety incidents, probable policy responses and certification trajectories into quantitative margin pressure and time-to-market estimates.
- Competitive landscaping and capability heatmaps for leading manufacturers and display houses, including IP, certification footprints, product breadth and route-to-market strengths.
- M&A and partnership opportunity screening, with quantified valuation levers, integration risks and proposed deal structures tailored to strategic buyers, private-equity sponsors and strategic alliances.
- Scenario-based tactical recommendations for commercial teams—pricing strategies, channel incentives, and event-centric product bundles optimized for 12–24 month horizons.
- Executive dashboards and investor-ready slide templates that distill the analysis into concise decision materials for board meetings and capital committees.
Competitive landscape: mature crafts, rising modernizers
The market remains a mix of heritage family-owned manufacturers—many operating in long-standing production clusters—and smaller professional display firms with deep event expertise. Our competitive analysis assesses capability differentiation across production scale, certifications, export networks, and services for professional displays.
Fireworks Market
- Established manufacturing clusters in traditional production centers continue to supply the majority of consumer and display-grade product lines. Many of these manufacturers have expanded export capabilities, achieved international certifications and maintain extensive cooperative factory networks to manage seasonal demand.
- Professional display houses in major end markets retain strong positions in large-scale events and custom shows through in-house technical teams, logistics capabilities, and legacy client relationships. Their value lies less in volume manufacturing and more in end-to-end event orchestration and safety governance.
- Across both groups, differentiation increasingly depends on demonstrable compliance (international safety standards), product innovation (effects, reliability, environmentally conscious formulations), and the ability to execute cross-border logistics under tightened regulatory regimes.
PW Consulting’s profiles of leading players examine how certification credentials, cooperative production models, joint-venture footprints, and century-spanning reputations translate into strategic advantages or vulnerabilities. The study also assesses how trade-show activity, product launches and on-site demonstrations signal evolving market positioning in 2026.
Regulatory shock and the Liuyang inflection
2026 introduced a notable regulatory inflection point following a major safety incident at a manufacturing facility in a primary production cluster. Authorities ordered temporary production halts across local manufacturers, demonstrating how single-site events can cascade into global supply interruptions and compliance reassessments. Simultaneously, that production cluster remains the historic heart of fireworks manufacturing, hosting hundreds of specialized operations and dense supplier ecosystems.
Our Dynamics chapter places this event in context: we quantify immediate output loss scenarios, model the transmission of shortages to major consuming regions, and outline pragmatic remedial measures—ranging from accelerated alternative sourcing and inventory strategies to supplier audits and third-party certification acceleration. We also model the potential medium-term policy responses, from heightened factory inspections to revised storage and transport regulations, and estimate the operational cost impact under each policy scenario.
Opportunities and threats mapped for 2026
- Opportunities: Specialized display services, safety-as-a-service offerings (certification, on-site QA), premium event packages, and product lines emphasizing reduced-noise and lower-smoke formulations. Strategic entrants can capture premium margins by pairing validated safety credentials with event-management competencies.
- Threats: Heightened regulatory enforcement, concentration risk tied to production clusters, raw-material price volatility, and the competitive pressure of non-pyrotechnic experiential technologies (drones, AR/VR spectacles) in high-profile events.
- Consolidation potential: Low-to-moderate market concentration among top players leaves room for roll-up strategies that prioritize compliance, distribution control, and service bundling. The study identifies acquisition archetypes that can both reduce compliance exposure and unlock cross-border sales synergies.
How executives should act in 2026
- Prioritize short-term resilience: implement dual-sourcing, increase critical-safety inventories selectively, and accelerate third-party compliance checks for key suppliers to mitigate stoppage risk.
- Invest in certification and traceability: buyers and brands that can prove higher compliance will secure premium event contracts and reduce insurance costs.
- Rebalance portfolios: consider shifting capital toward experiential event services and hybrid offerings that combine pyrotechnics with digital augmentation.
- Prepare for policy tightening: integrate regulatory scenario planning into capital allocation and pricing models; update contractual clauses to reflect force majeure and extended lead-time realities.
- Scan M&A selectively: target assets that provide distribution control in key consuming markets or that bring differentiated safety and testing capabilities.
Why PW Consulting’s report is a strategic asset
The study is designed as a decision-enabler for 2026. It combines a rigorously validated market-size model (with transparent assumptions and sensitivity tests), actionable playbooks for supply-chain and regulatory risk mitigation, and competitive profiles that identify concrete pathways to strengthen market position. Importantly, the analysis is calibrated to preserve confidentiality of sensitive sub-segment economics in this preview—enabling clients to use the report as a practical playbook while we retain the granular segmentation and proprietary data for direct subscribers.
Next steps
For corporate strategy teams, procurement leaders, event producers, and private-equity investors considering deals in or adjacent to the fireworks ecosystem, the full PW Consulting Fireworks Market study provides the operational detail and scenario-level diagnostics required to act with confidence in 2026. Visit our report page to access the full dataset, downloadable models, and bespoke advisory options that translate study insights into executable 12–36 month plans.
For detailed analysis of this topic, please visit the official page: Fireworks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cheese Powder Market Poised for 6.72% CAGR Through 2032 — PW Consulting
By pmarketresearch, 2026-07-08
Cheese Powder Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a strategic primer on the global cheese powder market designed to orient leadership teams preparing critical 2026 plans. This briefing synthesizes the study’s macro forecasts, competitive architecture, regulatory inflection points and real-world playbooks — deliberately revealing the depth of our analysis while reserving granular subsegment figures for the full report. Think of this piece as a high-fidelity trailer: enough insight to prioritize choices today, but not the playbook you’ll execute tomorrow. For that, access to the full study is required.
Cheese Powder Market
Market snapshot: size, trajectory, and concentration
The cheese powder market is on a clear multi-year expansion path. On an aggregated basis, the market grew from a lower-single-digit billion-dollar scale in 2020 to an estimated USD 5.29 Billion in the base year 2025, and is forecast to reach roughly USD 8.34 Billion by 2032. The expected compound annual growth rate over the forecast horizon is approximately 6.72% — a rate that signals steady demand expansion driven by structural changes across food manufacturing, retail convenience offerings and ingredient innovation.
Cheese Powder Market
Market structure is neither atomized nor monopolistic: the top three players account for a meaningful majority share, and the top five expand that position further. This concentration dynamic (CR3 and CR5 levels that indicate a moderately consolidated industry) creates both competitive barriers and predictable partnership opportunities for suppliers, co-manufacturers and brand owners.
Cheese Powder Market
Why 2026 is a pivotal planning year
- Transition from recovery to expansion: After the recent stabilization of supply chains and raw-material availability, 2026 is the first year where companies can meaningfully scale new formulations, channel pilots and cross-border projects without one-off pandemic risk premiums.
- Regulatory and trade inflection points crystallize: Several regulatory shifts and tariff actions enacted through 2025 change the economics of export sourcing and label claims — making 2026 the operational year to adapt ingredients, processes and distribution footprints.
- Consumer expectations and formulation innovation align: Nutrition-focused claims (clean label, organic, allergen management) and culinary trends (snacking, ready-to-eat meal platforms) converge to create commercially viable premiumization and cost-optimization product tiers.
Demand and supply dynamics shaping strategy
Demand drivers are broad-based: ingredient input into ready-to-cook/ready-to-eat offerings, bakery and snack innovation, on-trend flavor extensions, and foodservice reformulation are all contributing to steady uptake. Supply-side dynamics are equally influential — dairy milk supply, processing capacity, dehydration technology improvements and logistics costs are core determinants of margin for both manufacturers and ingredient buyers.
Two concrete policy shifts observed in 2025 require immediate board-level attention:
- India: Draft FSSAI standards for cheese powder (2025) — The Food Safety and Standards Authority of India released draft amendments that define composition, additive limits, hygienic production criteria and labeling requirements for cheese powder. For firms engaged in South Asia — whether via exports, toll-manufacturing or local JV structures — these standards change permissible formulations and disclosure obligations, and will influence product design, certification pathways and market entry timetables.
- China: Import tariff adjustments (March 2025) — In response to trade measures, certain grated or powdered cheese products faced an additional tariff layer. This alters landed cost math for exporters and increases the commercial attractiveness of regional sourcing or tariff engineering solutions (e.g., tariff classification, bonded storage, nearshoring).
Strategically, these dynamics mean teams must re-evaluate three levers in 2026: product architecture (what to sell and how to label it), sourcing footprint (where to manufacture or buy key milk/cheese intermediates), and route-to-market (direct exports vs. local co-manufacture vs. tolling).
Competitive landscape: what leaders are doing
The competitive field combines global dairy ingredient specialists and regional innovators. Key firms we profile in the full research are known for differentiated value propositions:
- Lactosan A/S (Denmark) — Focuses on premium, diverse cheese powder portfolios tailored to food producers seeking specialty varieties and refined flavor systems.
- Land O’Lakes Ingredients (United States) — Leverages scale in cheddar variants and formulation know-how across mild-to-bold flavor spectrums for large industrial customers.
- Commercial Creamery Company (United States) — Niche player with emphasis on white cheddar and organic-certified variants appealing to health-oriented and specialty channels.
- Bluegrass Ingredients (United States) — Known for creative product breadth and color/flavor blends that enable new application development in snacks and savory innovation.
- DFA Ingredient Solutions (United States) — Offers capacity for certified production lines (Organic, Halal) and positions itself as a regulatory-compliant supply partner.
- All American Foods, Inc. (United States) — Specializes in bulk Pro Mix® solutions and custom formulations serving large-scale food processors.
Across these profiles, three strategic themes recur: (1) portfolio breadth combined with technical application support, (2) certification and traceability as commercial differentiators, and (3) partnerships that embed suppliers into co-development of finished goods. Competitive plays in 2026 will likely focus on deepening application engineering, expanding certification footprints and creating locked-in channel agreements with high-growth snack and meal platforms.
Actionable strategic plays for 2026
Based on the market trajectory and competitive context, here are priority moves for executive teams preparing 2026 budgets and roadmaps:
- Re-evaluate sourcing strategy through scenario modeling: Build scenarios that quantify the P&L impact of tariffs, local-regulation compliance costs and logistics volatility. Identify two alternate supply footprints (e.g., regional hubs vs. centralized production) and run stress tests against raw milk price swings.
- Invest selectively in certification and documentation: Where incremental revenue from organic, Halal or compliant labeling exceeds certification costs within a three-year payback, accelerate conversion. Certifications are now purchase prerequisites for many foodservice and retail chains.
- Prioritize application-engineering partnerships: Allocate R&D capacity to fast-follow application pilots with major food manufacturers — small co-funded pilots can unlock long-term off-take contracts and enable premium pricing.
- Design an adaptive product taxonomy: Implement a two-track portfolio: (A) standardized cost-optimized base powders for volume channels; (B) value-added, differentiated powders for premium and clean-label segments. Keep SKU proliferation controlled by modular flavor and functional concentrates.
- Evaluate M&A and contract-manufacturing opportunities: Use market concentration to identify bolt-ons that provide either geographic access, certification capability or specialized dehydration technology. Tolling agreements can be a low-capex pathway to regional presence.
- Embed regulatory monitoring into commercial cadence: Make regulatory change a formal decision trigger in product roadmaps — especially in high-growth regional markets where draft standards are rapidly evolving.
What the full PW Consulting report provides (practical content)
The full study is built for commercial teams and investment committees who need executable intelligence. It includes:
- Market sizing and forecasting methodology with base-year reconciliation (2025) and scenario outputs across the 2026–2032 horizon.
- Demand-driver analysis by end-application and product-type, with elasticity estimates and TAM/SAM frameworks for prioritized use cases.
- Supply-chain mapping covering milk origin, dehydration capacity, key input cost drivers and transport/logistics nodes.
- Regulatory and tariff impact models (including sensitivity to the FSSAI draft standards and recent tariff actions) and suggested compliance pathways.
- Competitor heatmaps, capability matrices and vendor win-loss examinations — including playbooks from the leading ingredient suppliers profiled above.
- Commercial playbooks: channel-entry strategies, pricing scenarios, promotional experiments and sample KPIs to operationalize trials.
- M&A screening tools and diligence checklists tailored to the cheese-powder value chain.
- Risk register and decision triggers for near-term shocks (tariff shocks, raw milk shortages, regulatory adoption timelines).
How to use this analysis in boardroom decisions
For 2026 planning cycles, treat the report as a decisioning toolkit rather than a static market brief. Recommended sequence:
- Shortlist three strategic hypotheses (e.g., nearshoring, premium certification, channel partnership) and map required investments and KPIs.
- Run sensitivity models on the most impactful variables highlighted in our research (cost of goods, tariff exposure, adoption velocity in target channels).
- Execute a 6–9 month pilot for the highest-probability hypothesis with explicit success criteria defined up front; use our commercial playbooks to accelerate test design.
- Trigger irreversible investments (capacity, M&A) only after pilots validate demand, margin and operational readiness under the report’s defined stress scenarios.
Closing: why now, and next steps
The cheese powder market’s steady CAGR and predictable commercial use cases create a fertile environment for disciplined growth plays in 2026. The near-term regulatory and trade shifts introduce both cost risk and competitive opportunity — winners will be those who combine rigorous scenario planning with quick, low-cost experimentation and selective investment in certification and application engineering.
PW Consulting’s full Cheese Powder Market study contains the segmented market analytics, supplier scorecards, regulatory impact models and step-by-step playbooks necessary to convert the trends summarized here into executable initiatives. Access to the complete dataset and appendices will be essential if your team intends to commit capital, redesign supply chains or launch new product architectures in 2026. Contact our market team to schedule a briefing and obtain the full report.
For detailed analysis of this topic, please visit the official page: Cheese Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com