

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Foot Care Market to Reach $5.48B by 2032 at 6.84% CAGR — PW Consulting

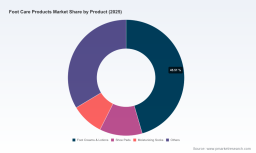
Foot Care Products Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies set priorities for 2026, the foot care products market presents a compelling mix of steady growth, technical fragmentation and regulatory inflection points. Our PW Consulting study — anchored on a 2025 base year with historical coverage from 2020–2025 and forward-looking forecasts to 2032 — finds the global market expanding from roughly USD 2.7 Billion in 2020 to an estimated USD 3.45 Billion in 2025, with projections to exceed USD 5.4 Billion by 2032 at a compound annual growth rate (CAGR) of approximately 6.84% over the 2026–2032 forecast window.
Foot Care Products Market
This briefing is designed as a strategic “teaser”: it surfaces the actionable trends and decision levers that will matter most to executives in 2026 while deliberately withholding detailed segment-level datapoints so that commercial, product and M&A teams will consult the full report for the granular inputs required to execute.
Foot Care Products Market
Why this matters for 2026 planning
- Predictable scale with room for differentiation: The market’s mid-single-digit CAGR and sustained increase in absolute market size create breathing space for new products, channel experiments and targeted M&A without requiring hyper-aggressive share-snatching plays.
- Fragmentation drives specialization opportunities: Low concentration among top players signals that focused plays — premium therapeutic formulations, clinically-oriented solutions for high-risk cohorts, or digitally enabled orthotic services — can scale commercially without immediate head-to-head confrontation with dominant incumbents.
- Regulation and reimbursement are fast-moving levers: 2026 is the year reimbursement pathways and certification frameworks materially affect provider behavior and payer access. Companies that align product design and go-to-market to these evolving rules will secure advantaged distribution into clinical channels.
Market trajectory and implications
From a sizing perspective, the market’s expansion is both organic and structural: consumer wellness habits, aging populations, and greater attention to preventive podiatric care underpin baseline growth, while medical reimbursement shifts and technical improvements in materials and sterilization protocols are unlocking higher-value clinical use cases.
Foot Care Products Market
For strategy teams, the arithmetic is straightforward. A market growing at roughly 6.8% annually across the forecast horizon favors measurable, staged investments: pilot launches and controlled geography rollouts in 2026–2027; scale-up and vertical integration (manufacturing, sterilization, clinical partnerships) in 2028–2030; and consolidation or strategic exits post-2030 as higher-margin niches solidify.
Competitive landscape — who to watch
The market is populated by a mix of consumer-focused brands, specialty device and formulation players, and regionally dominant clinical suppliers. Below are strategic profiles of several notable competitors that our clients frequently benchmark against:
- Aetrex Worldwide, Inc. (Princeton, NJ; https://www.aetrex.com) — Aetrex’s strength lies in blending hardware (orthotics, insoles) with digital diagnostics (foot-scanning and fit technologies). For 2026 strategies, they represent a benchmark for integrating technology-driven differentiation into retail and clinical channels.
- PediFix Inc. (Hauppauge, NY; https://www.pedifix.com) — Known for practical, consumer-oriented protection and comfort solutions (pads, wraps, blisters), PediFix exemplifies a playbook focused on wide retail distribution, low-cost manufacturing and brand trust in everyday-use categories.
- Alva-Amco Pharmacal Companies, Inc. (Sterling, VA; https://www.alvaamco.com) — With heritage in topical OTC formulations and private-label manufacturing, Alva-Amco is a case study in leveraging contract manufacturing and formulation know-how to serve both mass retail and professional dermatology/podiatry segments.
- Blistex Inc. (Oak Brook, IL; https://www.blistex.com) — Traditionally a consumer lip-care player, Blistex’s corporate capabilities in brand marketing and OTC product development illustrate how consumer healthcare firms can credibly diversify into adjacent foot-care balms and barrier formulations.
- Footlogix (Sammamish, WA; https://www.footlogix.com) — Positioned as a professional “pediceutical” brand, Footlogix shows how salon and clinic-first distribution can command premium pricing and professional endorsement — important for targeting higher-margin clinical channels and establishing therapy-backed claims.
- Diabetik Foot Care India Private Limited (Chennai, TN; https://www.diabetikfootcare.com) — An example of a geographically focused specialist targeting diabetic foot care and related high-risk cohorts. Their model highlights the commercial potential of tailored solutions in large emerging markets with growing chronic disease burdens.
Across the competitive set, success factors converge on three themes: clinical credibility, scalable manufacturing/sterilization capability, and omnichannel access (retail + clinical + e-commerce). Our full report maps capability matrices and channel economics for each player.
Regulatory, reimbursement and operational dynamics
Two regulatory/reimbursement developments in 2026 are particularly consequential:
- Regulatory approval landscape: Recent approvals for OTC foot care formulations underscore an easing pathway for novel topical products when supported by robust safety data and appropriate labeling. Companies investing in clinical evidence generation can accelerate market entry.
- Reimbursement & certification shifts: Changes to local coverage determinations and Medicare coding mean that certified nurses holding recognized foot-care credentials may deliver certain at‑risk foot care services under physician supervision. This broadens institutional access for products validated for clinical use and creates a new buyer segment within health systems and home health networks.
Operational standards are tightening too. Best-practice device reprocessing per Spaulding classification and manufacturer-specified sterilization cycles are now routine expectations in clinical purchasing decisions. Single-use accessoryization (e.g., disposable emery bands) and clear manufacturer sterilization protocols materially influence procurement choices and total cost of ownership calculations.
What the full PW Consulting report delivers (actionable contents)
We design the full study to be execution-ready for commercial, product and corporate development teams. Key deliverables include:
- Validated market-size models (2020–2032) and scenario analyses calibrated to alternative macroeconomic and reimbursement outcomes.
- Segmentation matrices by product, category and region with interactive sensitivity sliders for custom planning (note: detailed segment tables are available in the paid report).
- Channel and route-to-market economics: retailer margins, clinical procurement dynamics, and DTC/e‑commerce unit economics.
- Regulatory and reimbursement playbooks: required certifications, coding strategies, and payer engagement templates tied to the latest CMS and professional association guidelines.
- Manufacturing & sterilization benchmarking: supplier directories, quality checklists, CAPEX/OPEX models for in-house vs contract reprocessing, and compliance checklists aligned to Spaulding protocols.
- Competitive capability maps and M&A target shortlists, including valuations and integration risk assessments for tuck-in vs platform deals.
- Practical go-to-market plans and 18–36 month pilots for three strategic archetypes: consumer scale, clinical premium, and diagnostic-enabled orthotic platforms.
Decision playbook for 2026
- Prioritize clinical validation now: invest in limited clinical trials or real‑world evidence projects tied to reimbursement pathways. This accelerates access to institutional channels unlocked by 2026 credentialing shifts.
- Secure sterilization-certainty: ensure manufacturing and packaging are aligned with required sterilization cycles and single-use accessory standards; this reduces friction in clinical procurement.
- Test adjunct digital services: pilots of foot-scanning or tele-podiatry tied to product bundles can unlock higher lifetime value and stronger differentiation without heavy initial CAPEX.
- Balance channel focus: pursue a hybrid model where consumer retail fuels volume while higher-margin clinical products and professional partnerships protect profitability and limit commoditization.
Frequently asked technical & compliance questions
- What sterilization and reprocessing standards should product teams design for?
Design to meet Spaulding-classification reprocessing where applicable. For components intended as single-use (e.g., emery bands), reflect that in packaging and master-case economics. Where reprocessing is required, specify manufacturer-recommended steam sterilization cycles and validate via biological indicators to satisfy institutional procurement policies.
- Which certifications materially affect clinical adoption?
Recognition by professional bodies and alignment with clinically recognized certifications for providers increases product uptake. Also consider seals or endorsements that demonstrate impact on normal foot function and clinical utility when targeting podiatry or orthotics buyers.
- How should firms approach reimbursement engagement?
Map product use-cases to specific payer rules and local coverage determinations. If products address at-risk cohorts, ensure provider credentialing requirements and documentation templates are embedded into sales materials to minimize denials and administrative friction.
Conclusion and next steps
The foot care products market is attractive for 2026 investment: large enough to matter, fragmented enough to permit targeted wins, and dynamic enough that regulatory and clinical trends can be leveraged for disproportionate advantage. The path to outsized returns runs through clinical credibility, sterilization and supply-chain certainty, and intelligent channel orchestration.
PW Consulting’s full Foot Care Products Market report contains the detailed segmentation tables, competitive financials, vendor scorecards and executable playbooks that teams need to convert this strategic preview into 2026 deals and launches. To access the comprehensive dataset, model files, and bespoke advisory options, please follow the link on our website to request the complete report and schedule a strategy briefing.
For detailed analysis of this topic, please visit the official page: Foot Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com