

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Refrigerated Display Cases Market to Reach USD 16,140M by 2032 at 7.4% CAGR

Refrigerated Display Cases Market: Strategic Outlook for 2026 Decision-Makers
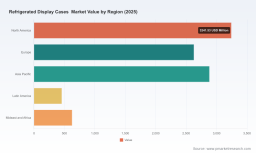
As clients recalibrate capital plans and product roadmaps for 2026, PW Consulting’s latest Refrigerated Display Cases Market study delivers the operational and strategic intelligence required to act with conviction. Built on a 2025 base year and detailed historical analysis from 2020–2025, our forecast through 2032 is grounded in rigorous bottom-up modeling and scenario stress tests. The headline: the market has expanded materially over the past five years and, at a compound annual growth rate of 7.4% through the forecast window, is on a path from roughly USD 9.8 billion in 2025 to an expected USD 16.1 billion by 2032. That trajectory reframes product, regulatory and go-to-market trade-offs for vendors, retailers and service providers entering 2026.
Refrigerated Display Cases Market
Why this study matters for 2026 decisions
-
Regulatory-driven product changes are no longer hypothetical. New rules around refrigerants and energy classes are compressing innovation timelines and creating retrofit markets that can be monetized if you move early.
Refrigerated Display Cases Market -
Procurement and manufacturing choices made this year will determine cost competitiveness for the next product cycle. Raw-material volatility and concentrated component supply chains mean lead times and margin pressure will vary by architecture and configuration.
Refrigerated Display Cases Market -
Channel economics are shifting: service and after-sales contracts (retrofits, refrigerant conversions, remote monitoring) are becoming strategic revenue streams rather than aftermarket niceties.
-
Consolidation dynamics and competitive positioning are clear enough to identify targets for partnerships or tuck-ins—but fine-grained share data and due-diligence metrics are essential before making M&A commitments.
What the report delivers (practical, executable content)
This study is designed as a decision-support tool for revenue, R&D, regulatory and M&A leaders. It combines:
-
Market sizing and unit/price triangulation across the historical (2020–2025) and forecast (2026–2032) windows—allowing scenario-level revenue and volume projections tied to product classes and installation types.
-
Regulatory impact modeling that translates refrigerant and energy-efficiency rules into retrofit demand curves, compliance timelines and incremental cost estimates for new builds versus replacements.
-
Technology and product roadmaps that benchmark plug-in, remote and semi plug-in architectures against operational metrics (energy, serviceability, footprint), with a prioritization matrix for R&D investment.
-
Supply-chain and cost-to-serve heat maps identifying single-source exposures, material cost sensitivities, and near-term supplier prioritization options.
-
Commercial playbooks: pricing strategies, warranty design, bundled service offerings, and channel segmentation to accelerate penetration while protecting margin.
-
Competitive dossiers and consolidation scenarios—including concentration metrics—that support target screening and valuation calibrations for potential acquisitions.
Competitive landscape: how the leader set is shaping strategy
The industry exhibits moderate concentration, with the top three and top five players controlling a meaningful share of global revenue—an arrangement that supports scale-driven investments in low-GWP refrigeration, digital controls and multicountry service networks. This structural backdrop favors firms that can combine product innovation with distribution reach and service execution.
-
Hussmann Corporation has doubled down on retail and foodservice merchandisers, emphasizing natural refrigerants and energy-efficient lighting; recent product introductions highlight thermal control advances that improve in-case shelf life and shrinkage economics.
-
Carrier Commercial Refrigeration leverages integrated store systems and smart controls, positioning itself for large format retail rollouts that value total-store energy optimization over unit price.
-
Zero Zone is a product-focused innovator with narrow-footprint and hybrid architectures that optimize space and energy—though regulatory pressures on hybrid solutions are forcing a short-term rethink of its installed-base playbook.
-
True Manufacturing continues to be recognized for durable reach-in and glass-door merchandisers, with a value proposition tailored to foodservice customers emphasizing uptime and serviceability.
-
Epta, Hillphoenix and Arneg (European manufacturers) are demonstrating how compliance-driven energy advances (and PFAS-free materials) can be turned into competitive differentiation for customers sensitive to sustainability credentials.
-
AHT, Kysor Warren, Hoshizaki and Frigoglass round out a diversified competitive set with strengths in specific channels—convenience stores, beverage retail, and international distribution—that make them attractive partners or acquisition targets depending on strategic aims.
Recent product-level moves illustrate the pace of innovation: Hussmann’s late-2025 reach-in merchandisers introduced air-cooled microblock technology to reduce temperature variance; Epta showcased a double-sided multideck at a prominent trade event highlighting floor-space efficiencies for independent retailers; Hillphoenix launched a CO2 system claiming dramatically lower amperage draw versus conventional units. These examples reflect the dual themes of energy efficiency and serviceability that will dominate buyer selection in 2026.
Market dynamics and risk map
-
Regulatory shifts: effective 2026 rules are accelerating retirements and conversions. Restrictions on certain hybrid architectures and low-GWP charge limits force design and installation trade-offs that materially affect BOM composition and service models.
-
Refrigerant transition: adoption of alternatives such as R‑290 and CO2 is increasing—designers must reconcile flammability, charge size, and transcritical performance with store-level constraints and safety codes.
-
Material and component risk: while 2025 saw moderated price volatility for steel, aluminum and glass, supply chain fragility remains. Decisions on localization, component standardization and inventory strategy should be prioritized this year.
-
Aftermarket opportunity: replacement cycles and mandated conversions create a multi-year revenue stream for retrofit services, parts and remote-monitoring subscriptions; firms that can scale field operations will convert regulatory headwinds into recurring income.
Strategic implications and recommended actions for 2026
Executives should treat 2026 as a decisive year to shift from defensive compliance to offensive growth. Recommended actions:
-
Immediate (0–6 months): conduct a portfolio compliance audit to identify non-compliant SKU lines and define a prioritized conversion map; implement a price/cost reset that reflects refrigerant replacement and servicing economics.
-
Near-term (6–18 months): launch retrofit pilot programs with performance guarantees and service-subscription models; accelerate low-GWP product launches with modular architectures to enable faster field conversions.
-
Medium-term (12–36 months): pursue targeted M&A to acquire regional service networks or component capabilities that shorten time-to-market for compliant products; invest in digital controls and remote diagnostics to reduce service costs and generate subscription revenue.
-
Supply-chain resilience: diversify component sourcing, lock long-lead contracts for critical materials, and qualify alternate glazing and insulation suppliers that meet energy and sustainability rules.
-
Organizational: establish a cross-functional regulatory task force combining engineering, procurement and sales to manage product lifecycles and customer communications through transitions.
How PW Consulting supports execution
PW Consulting’s Refrigerated Display Cases Market study is intentionally structured as an implementation reference. Beyond headline forecasting, the full deliverable includes downloadable financial models, retrofit demand calculators, supplier heat maps, and granular competitive dossiers—tools designed for CFOs, heads of product, and corporate development teams who need to quantify trade-offs and prioritize investments for 2026.
We intentionally maintain critical segment-level granularity and pricing matrices in the full report to preserve analytic integrity for clients conducting procurement negotiations, benchmarking, or M&A diligence. If you need the full dataset (regional/type/application splits, unit-level pricing curves, and channel share matrices) or a bespoke briefing aligned to your product and geographic footprint, request the complete report and modeling package on PW Consulting’s report page.
In short: the refrigerated display cases market is entering a phase in which regulatory timing, refrigerant strategy, and service capability determine winners. Organizations that align product design, supply chain and commercial models in 2026 will convert compliance pressures into sustainable growth—our study shows how to make those choices with data-backed confidence.
For detailed analysis of this topic, please visit the official page: Refrigerated Display Cases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com