

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Disposable Lighters Market to Hit USD 344.8M by 2032 at 4.0% CAGR

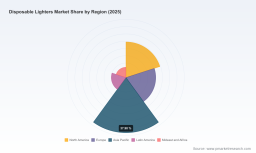
Disposable Lighters Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our new Disposable Lighters Market study. This article is written as a high-impact trailer: it demonstrates the analytical depth and the decision-ready perspectives contained in the full study while intentionally withholding granular segment-level figures to encourage executive teams to consult the complete report for transaction-grade details.
Disposable Lighters Market
Market snapshot: trajectory you cannot ignore
Using 2025 as the base year, the disposable lighters market has demonstrably recovered and expanded from its early‑decade base. Between 2020 and 2025 the market moved from the low‑hundreds to a materially larger base, and our forecasting framework projects continued growth through 2032. The model embedded in the report shows the market expanding at a steady compound annual growth rate of 4.0% across the 2026–2032 forecast window, with an implied acceleration in certain channels and product tiers driven by lifestyle trends, regulatory responses and supply‑side optimization.
Disposable Lighters Market
These headline dynamics translate into a predictable but strategically challenging environment for manufacturers, private labelers, distributors and investors: steady top‑line growth coupled with rising compliance costs, evolving consumer preferences and concentrated competitive forces that favour scale, design capability and regulatory agility.
Disposable Lighters Market
Why this report matters for 2026 corporate decisions
- Investment prioritization: Our integrated financial and regulatory scenarios let CFOs and strategy teams size the ROI for capital investment — from tooling and automation to new product lines — under multiple policy outcomes.
- Portfolio optimization: Operators must choose where to balance premiumization, value SKUs and refillable alternatives. The study maps margin profiles, SKU profitability and channel elasticity to guide SKU rationalization and NPD timing.
- Regulatory compliance as a competitive moat: With child‑resistant standards and single‑use restrictions rising globally, early movers in compliant design and EPR systems can reduce total cost of ownership and create barriers to late entrants.
- M&A and partnership playbooks: The report surfaces target archetypes and screening metrics for bolt‑on acquisitions, OEM partnerships and upstream supplier investments that accelerate scale and lower unit economics.
- Supply‑chain risk management: Sourcing strategies that trade off labour and input cost volatility against lead‑time and compliance risk are modelled and stress‑tested for 2026 capital plans.
What the full report contains (executive summary of deliverables)
- Comprehensive market sizing and validated historical series (2020–2025) with an audited baseline for 2025 and granular forecasts to 2032, including scenario variants reflecting regulatory stringency and material‑cost shocks.
- Market concentration analysis and competitive positioning maps that identify capability gaps and consolidation opportunities; our CR3 and CR5 concentration metrics are included to show market structure implications for strategy.
- Practical go‑to‑market playbooks for OEMs, branded players and private label distributors — covering distribution levers, pricing tactics, trade promotion ROI and assortment strategies for retail, e‑commerce and B2B channels.
- Regulatory impact models covering child‑resistant standards, single‑use plastics policies, trade restrictions and anticipated producer responsibility obligations — with cost pass‑through and margin impact scenarios.
- Supply‑chain diagnostic and sourcing playbook: cost‑curve modelling, supplier risk scoring, reshoring vs. nearshoring tradeoffs, and recommended contracting templates for component and fuel suppliers.
- Product and material transition roadmap that translates compliance imperatives into engineering requirements, prototype timelines and unit‑cost implications for bioplastics, metal hybrids and refillable architectures.
- Transaction support materials including target screening matrices, indicative valuation multipliers by archetype, and integration checklist items tailored to M&A in this sector.
- Model access: an interactive financial model used to generate the published scenarios (available to clients under license).
Competitive landscape: what incumbents and challengers are doing
The disposable lighters industry is marked by a mix of global branded giants, regional specialists, OEM heavyweights and niche luxury houses. Market concentration metrics indicate that the top three and top five players control a substantial portion of the market, creating high barriers to scale in price‑sensitive channels but opening niches for differentiation.
- Société BIC S.A. — Leverages unmatched global scale and brand recognition. Their strengths are mass distribution, cost leadership on high‑volume SKUs and compliance engineering for child‑resistant requirements. Strategic questions for BIC include expanding into higher‑margin utility products and accelerating sustainability programs to defend retail shelf space as regulations tighten.
- Tokai Corporation — A major OEM with a strong orientation toward safety and cost engineering. Tokai is well‑positioned to capture private label demand and serve firms seeking rapid compliance redesigns; their roadmap should prioritize flexible production cells to support both flint and electronic alternatives.
- Flamagas S.A. (Clipper) — Known for robust ignition systems and multi‑use utility features. Flamagas’ brand equity in repeat‑use designs suggests an opportunity to monetize refill ecosystems and accessory markets.
- Swedish Match (Cricket) — A global retail staple; its strengths lie in reliability and retail penetration. Strategic focus for Cricket will be balancing unit economics under EPR regimes while preserving availability in mass channels.
- Zippo Manufacturing Company — Commands the premium, lifestyle and EDC segment where margins are attractive and brand loyalty reduces price sensitivity; Zippo’s playbook should emphasize limited‑edition runs, serviceability and cross‑category brand extensions.
- NingBo Xinhai Electric Co., Ltd. — A Chinese volume manufacturer with scale benefits and design flexibility across both flint and electronic types. Their strategic value resides in cost competitiveness and quick turnarounds for global customers.
- Calico Brands, Inc. — A wholesale specialist that can exploit value channels and institutional purchases; margin pressure may require consolidation or vertical integration into upstream plastics and component supply.
- S.T. Dupont — Serves the luxury niche with high ASPs and craftsmanship; regulatory and material shifts are less disruptive to this segment, but sustainability credentials are increasingly important to high‑end consumers.
Collectively, these archetypes define strategic axes for competition: scale and cost, engineering and compliance, brand and premium differentiation, and OEM speed for private‑label partners.
Regulatory and supply‑side dynamics that will drive 2026 strategies
- Child‑resistant standards: Regulatory frameworks (for example, those enforced by consumer safety regulators) are now a de facto design requirement in many major markets — compliance timelines must be embedded in 2026 product roadmaps.
- Single‑use plastics and EPR: Expanded producer responsibility and single‑use restrictions are increasing compliance costs and shifting value toward refillable or recyclable designs; companies will need lifecycle cost models to defend price increases.
- Trade controls and import restrictions: Increasing scrutiny and tariffs in key markets are altering landed cost calculations and favouring diversified sourcing and local assembly options.
- Raw materials and labour volatility: While scale remains an advantage, capacity expansions in some manufacturing hubs have exposed manufacturers to labour and input cost swings that can erode low‑margin volumes; hedging and longer supplier contracts reduce exposure.
- Environmental externalities: With more than ten billion units produced annually, plastic waste is a structural reputational and policy risk; responsible companies will accelerate material substitution and take‑back programs.
A practical 2026 strategic playbook (eight decisive moves)
- Embed compliance into product design now: Convert regulatory timelines into product development milestones and test prototypes under expected standards.
- Segment your portfolio: Allocate R&D and capex to premium, refillable and compliant value SKUs based on margin and channel return expectations.
- Secure input cost and logistics: Negotiate multi‑year contracts for key plastics, metals and fuel components; evaluate nearshoring to mitigate trade and labour risk.
- Invest selectively in sustainability: Pilot bioplastic blends and recyclable hybrid structures where payback is demonstrated or where regulation mandates change.
- Use M&A to buy capability: Prioritize targets that add compliance engineering, patented ignition systems, or direct access to high‑growth channels.
- Revise commercial models: Rebalance channel incentives toward high‑margin e‑commerce and convenience formats; realign trade spend to SKU profitability.
- Activate scenario planning: Stress test 2026 budgets under higher‑cost, high‑regulation and trade‑restricted scenarios using the report’s integrated model.
- Communicate proactively: Prepare investor and retailer messaging on compliance, sustainability and total cost of ownership to protect price and reduce churn.
Our full report provides the quantitative backing, playbooks and model access needed to operationalize the moves above. This preview deliberately omits granular segment and regional allocations — those detailed splits, supplier lists, and the interactive forecast model are available only in the complete PW Consulting report and licensed deliverables.
Next steps
For boards, strategy teams and private investors preparing 2026 capital and M&A decisions, the Disposable Lighters Market study is designed to be the single source of truth: validated historical data, forward scenarios, competitive playbooks and an executable roadmap for product, supply chain and commercial transformation. To obtain full access to the report, the interactive model and tailored advisory services, please visit PW Consulting’s market research portal or contact your PW Consulting account lead for a demo and licensing options.
For detailed analysis of this topic, please visit the official page: Disposable Lighters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com