

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Medical Electrodes Market to hit USD 1,922.4M by 2032 at 5.2% CAGR

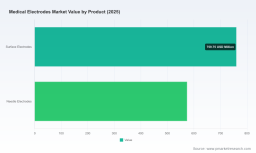
Medical Electrodes Market 2026: Strategic Briefing for Decision-Makers
Executive snapshot
As PW Consulting’s lead industry analyst, I present a concise strategic briefing to orient executive teams, product leaders, and investors ahead of planning cycles in 2026. The global medical electrodes market has expanded steadily through the first half of the decade and is projected to continue growing at a mid-single-digit pace. This briefing highlights the macro trajectory, regulatory and reimbursement inflections, competitive dynamics, and the practical, decision-ready insights embedded in our full market study — while intentionally reserving the granular segment matrices that underpin deal-level and product-level plays (available in the full report).
Medical Electrodes Market
Market trajectory: 2020–2032 at a glance
The market moved from just over USD 1.07 billion in 2020 to approximately USD 1.33 billion by the 2025 base year, tracking an aggregate uplift that reflects both durable clinical demand and episodic product refresh cycles. Our forecast through 2032 projects continued expansion, with the market following a compound annual growth rate (CAGR) of approximately 5.2% over the forecast window. By 2032, the topline approaches the USD 1.9–2.0 billion range under the base forecast scenario, driven by a mix of device upgrades, broader adoption of monitoring in ambulatory settings, and incremental neuromodulation use cases.
Medical Electrodes Market
Importantly, the growth path is not perfectly linear — the model captures near-term acceleration tied to product launches and reimbursement clarity, as well as short-term volatility from raw-material inflation and episodic capital spending cycles. These non-linearities create tactical windows for market entry, premiumization, and M&A that are time-sensitive for 2026 planners.
Medical Electrodes Market
Why this matters for 2026 decisions
- Procurement & cost management: Hospitals and OEMs faced rising consumables costs through 2020–2025 (average annual increases in medical and surgical supplies were material), altering total cost of care calculations. Buyers and suppliers must align contracts and price-index clauses to mitigate pass-throughs of material inflation into 2026.
- Regulatory timing is a gating factor: ISO 10993 biocompatibility expectations and FDA pathways (including 510(k) requirements for novel electrode designs and MR-conditional claims) remain material to time-to-market. Recent guidance tightens testing expectations for long-term adhesion and signal fidelity — a critical design constraint for neuromonitoring and implantable-adjacent applications.
- Reimbursement enables new use cases: 2026 updates to procedural and HCPCS coding have clarified billing pathways for several advanced electrode arrays. These code changes convert previously unfunded pilot programs into viable commercialization targets, particularly in outpatient and device-assisted stimulation settings.
- Portfolio and R&D prioritization: With mid-single-digit market growth, incremental share gains come more from product differentiation and channel optimization than from category expansion alone. R&D allocation should prioritize demonstrable clinical outcomes (signal accuracy, adhesion, skin tolerability) and economic value (longer wear, lower replacement frequency).
- M&A and partnerships: The market concentration metrics indicate a moderately consolidated supplier base at the top. Strategic roll-ups of adjacent technologies (thin-film intracranial electrodes, smart reusable electrodes, disposables optimized for home-monitoring) are credible routes to fast-track access to new clinical segments.
What PW Consulting’s full report delivers (practical content)
Our full market study is designed as an operational toolkit for executives committing resources in 2026. Key deliverables include:
- Dynamic market model with annualized topline and scenario runs (base, downside, upside) for 2026–2032, allowing users to test assumptions such as reimbursement shifts, material-cost shocks, and adoption curves.
- Go-to-market playbooks for hospital procurement, commercial-scale OEM partnerships, and direct-to-consumer monitoring channels — each with margin and volume thresholds for profitable scale.
- Regulatory and clinical pathway maps, including testing protocols aligned to ISO 10993 and the current FDA expectations for MR-conditional and long-wear adhesives.
- Competitive positioning matrices and qualitative vendor scorecards based on product breadth, innovation cadence, geographic strength, and channel control — optimized for rapid target screening.
- Unit-cost and pricing models built from primary supplier interviews and cost-buildup analysis, enabling negotiation benchmarks and SKU rationalization.
- Actionable M&A shortlist with flags for strategic fit, integration complexity, and time-to-revenue for bolt-on acquisitions or licensing deals (data room-ready dossiers for prioritized targets).
- Supplier risk heat maps that correlate single-sourced raw materials, contract manufacturer dependency, and geography-specific supply-chain exposure.
To preserve the competitive value of this intelligence we present segment-level forecasts, channel shares, and price ladders only within the full report — a deliberate packaging choice to support client decision confidentiality and to prevent tactical leakage.
Competitive landscape — strategic reads on leading players
The supplier ecosystem ranges from diversified medical device majors to specialized electrode technology firms. Below are high-level strategic interpretations of select players included in our competitive analysis:
- Ambu A/S: Positioned as an innovation-focused supplier of disposable electrodes, Ambu’s recent launches underscore an emphasis on signal clarity and patient comfort. Their execution model — combining product refresh cadence with broad distribution — makes them a logical partner for hospital trials and OEM co-development.
- 3M Company: A category stalwart with strong brand trust in monitoring electrodes. Recent product introductions aim at vulnerable cohorts (paediatric and geriatric), opening channels in specialty care and home-health kits. Their scale enables aggressive commercial programs but also invites scrutiny on margin resilience in pricing negotiations.
- Medtronic plc: Leverages deep neurology and cardiac franchises to bundle electrodes with higher-value systems (EEG, DBS, electrosurgery). Their product roadmap emphasizes incremental performance gains that justify premium positioning in procedural segments.
- Nihon Kohden Corporation: Strong in reusable and “smart” electrode systems, with a focus on integrating diagnostics and telemetry. Their advantage is clinical trust in neurodiagnostic settings and an R&D pipeline targeting long-term monitoring solutions.
- CONMED, ZOLL, B. Braun, Cardinal Health: These players emphasize breadth across monitoring and electrosurgical neutral electrodes, leveraging channel relationships with hospitals and ambulatory surgery centers. Their strategies balance private-label volume plays with branded innovation in subcategories.
- Specialists & innovators (Natus, Rhythmlink, NeuroOne, Ad-Tech, Nissha, KLS Martin): A set of smaller, often highly technical firms compete on niche performance attributes — thin-film intracranial electrodes, SEEG, subdermal disposables, and high-fidelity EEG/EMG sensors. These companies are frequent acquisition targets for larger OEMs seeking specialty capabilities.
Market concentration is meaningful but not prohibitive for new entrants: the top-tier vendors control a substantial share of the market but leave clear white space for differentiated technologies and service models, particularly those that reduce total cost of ownership or unlock new reimbursement pathways.
Near-term industry dynamics to incorporate into 2026 plans
- Regulatory constraint and opportunity: FDA 510(k) clearance remains the common path for many electrode innovations, with increasing scrutiny on MR-conditional claims and long-term adhesion testing; aligning product development milestones to these requirements shortens commercialization timelines.
- Reimbursement shifts: Updated CPT and HCPCS codes in 2026 create explicit billing pathways for certain electrode arrays used in nerve stimulation procedures, improving return-on-investment for targeted clinical pilots.
- Input-cost inflation: Rising raw-material and supply-chain costs materially affect unit economics for disposables; cost-optimization and alternate sourcing strategies are essential to sustaining margin targets.
- Clinical demand drivers: Aging populations, expanded ambulatory monitoring, and growth in neuromodulation therapies are sustaining demand, but commercial success requires demonstrating both clinical differentiation and economic value.
Recommended 90–180 day moves for 2026
- Finalize regulatory gap analysis for any product slated for 2026–2027 launch; prioritize submission paths that align with the new FDA testing expectations.
- Lock preferred-supplier agreements with indexed pricing clauses to mitigate further material-cost shocks.
- Initiate 2–3 focused clinical pilots in reimbursement-favorable settings to generate the HTA and cost-effectiveness evidence required by payors.
- Screen the M&A shortlist in our annex and commence confidential outreach for at least one strategic bolt-on that accelerates access to intracranial or thin-film electrode capabilities.
- Rebalance R&D portfolios toward features that enable clear reimbursement capture (e.g., wear-time extensions, integration with remote monitoring platforms, and validated signal-accuracy claims).
Accessing the full intelligence
This briefing is intentionally high-level to catalyze strategic alignment in 2026 planning cycles. The full PW Consulting Medical Electrodes Market report contains the granular segment economics, channel shares, pricing ladders, and vendor-level scorecards necessary for live commercial decisions and transaction due diligence. For teams preparing budgets, negotiating supplier agreements, or evaluating bolt-on acquisitions, that level of granularity is mission-critical — and available through our official distribution channels.
PW Consulting remains available to support bespoke scenario modeling, M&A diligence, and regulatory readiness planning derived from our proprietary dataset and primary interviews. In a market growing at roughly 5.2% annually with meaningful near-term regulatory and reimbursement inflections, disciplined, data-driven moves in 2026 will materially shape competitive position through the next business cycle.
For detailed analysis of this topic, please visit the official page: Medical Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com