

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vegan & Processed Cheese Market to Reach $28.89M by 2032 at 7.26% CAGR

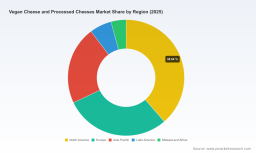
Vegan Cheese and Processed Cheeses Market: Strategic Imperatives for 2026
As companies position for growth in a market that bridges traditional dairy processing and rapidly evolving plant-based innovation, PW Consulting’s latest Vegan Cheese and Processed Cheeses Market study (base year 2025; historical 2020–2025; forecast 2026–2032) provides a pragmatic roadmap for corporate decision‑makers in 2026. The sector is expanding at a mid‑single‑digit to high‑single‑digit compound annual growth rate (CAGR 7.26%), reflecting steady demand and continued product innovation. Our bottom‑up sizing shows the market recovering and expanding from the mid‑2020s and approaching the upper‑twenty millions (USD, revenue unit: Million) by the end of the forecast window—an environment that rewards clarity on product positioning, channel economics and manufacturing scale.
Vegan Cheese and Processed Cheeses Market
Why this study matters for 2026 corporate strategy
- Decision clarity under margin pressure: Retail indicators and our channel models show pricing pressure on plant‑based SKUs even as new niches emerge. The study quantifies how a modest downward shift in average retail price interacts with unit volumes to compress gross margins—essential when allocating R&D, marketing and capex in 2026.
- Portfolio prioritization and SKU rationalization: With household penetration still constrained and evolving taste trade‑offs, companies must prioritize SKUs that deliver differentiated consumer utility (melt, spreadability, artisanal profile) rather than broad SKU proliferation. The research contains a prioritization framework and ROI thresholds tuned to the market’s growth and cost structure.
- Channel economics and go‑to‑market playbooks: The report maps profitable routes to market across retail, foodservice and industrial ingredient channels and offers retailer negotiation scripts and trade promotion models that preserve margin while supporting distribution expansion.
- Manufacturing and scale decisions: Our cost benchmarking highlights break‑even thresholds for co‑packing versus owned capacity across plant‑based bases (nut/bean/oil matrices) and conventional processed cheese lines—insight critical to 2026 capex and footprint choices.
What the full report contains (practical, operational outputs)
- Actionable market sizing and near‑term scenario forecasts (base 2025; forecast 2026–2032) with sensitivity to price, penetration and commodity input swings.
- Segment definitions and a commercialization matrix that ties product attributes (melt, flavor profile, dairy‑free claims, certifications) to channel demand and willingness to pay—plus playbooks for premiumization vs cost leadership.
- A modular financial model (Excel) enabling rapid assessment of SKU launches, private label bids, co‑packing arrangements and M&A valuations under multiple scenarios.
- Supply chain and input cost analysis, including emulsifiers, protein analogues and packaging pathways, with vendor scorecards and a supplier negotiation toolkit.
- Regulatory and labeling risk matrix, including trade‑policy and food‑safety triggers that materially affect go‑to‑market timing and consumer communications.
- Commercial templates: retailer negotiation decks, foodservice menu concepts, and industrial ingredient sales packages.
- Competitive playbooks and a screened M&A target list (by strategic fit and execution complexity), supported by integration risk checklists.
Competitive landscape — what to watch in 2026
The market shows moderate concentration—indicative of space for challengers and niche specialists. Across the competitive set, there is a clear divide between artisan, branded vegan specialists and large processed‑cheese incumbents pursuing scale and distribution advantages.
Vegan Cheese and Processed Cheeses Market
- Miyoko’s Creamery (Sonoma, CA): Artisanal positioning and fermentation‑led taste differentiation give Miyoko’s a premium play. For rivals, the implication is twofold: premium consumers tolerate higher price points and seek provenance; meanwhile, artisanal scalability is constrained without targeted investments in manufacturing automation.
- Violife (Netherlands): Global reach and a broad SKU range make Violife a defensive, wide‑spectrum player in mainstream retail. Competitive responses should factor in rapid SKU turnover and shelf space dynamics when negotiating category resets.
- Daiya Foods (California, USA): Known for melt‑capable formulations, Daiya’s recent flavor innovations illustrate the continuing role of technology in maintaining relevance—especially in foodservice and consumer segments demanding functional parity with dairy.
- Kite Hill (California, USA): Nut‑milk bases and premium positioning reinforce the bifurcation of the market between indulgence and value propositions. Partners and acquirers should evaluate the scale‑up path to meet retail listing minimums without diluting brand equity.
- Hochland SE (Germany), Groupe Bel (France), Kraft Heinz (USA): These incumbents bring manufacturing scale, established distribution and category management heft. Their plays—whether defensive on price, selective on plant‑based offerings, or opportunistic M&A—will define competitive thresholds for margin and shelf access.
Recent corporate moves illustrate this dynamic: a major European player discontinued a plant‑based brand and closed a production site in 2025, signaling the risk of non‑performing assets and the need for rigorous portfolio review. Conversely, acquisitive activity and new product launches among niche players emphasize continued innovation and the enduring attractiveness of premium artisanal formats.
Vegan Cheese and Processed Cheeses Market
Market dynamics and consumer context
- Demand signals: Retail data show a decline in plant‑based cheese dollar and unit sales in 2025, while average retail prices decreased modestly. At the same time, household penetration remains low—underscoring that category expansion is still an active, not mature, growth opportunity.
- Price and value tension: The drop in average retail price in 2025 has amplified the importance of cost control and value engineering for producers and private label manufacturers. The report quantifies the impact of small price movements on EBITDA across typical operating models.
- Consolidation runway: A fragmented supplier base and differentiated product archetypes create fertile ground for targeted acquisitions—particularly to acquire branded innovation or regional manufacturing capacity at attractive multiples.
Implications & recommended strategic moves for 2026
- For incumbents in processed cheese: Use 2026 to pilot plant‑based SKUs that leverage existing production lines where feasible, but maintain financial discipline—only scale SKUs that meet defined margin and distribution thresholds.
- For pure‑play vegan brands: Prioritize channel mix optimization (strengthen foodservice and DTC where functional advantages play best) and secure flexible manufacturing partnerships to manage seasonality and promotional volatility.
- For retailers and foodservice operators: Re‑segment assortment by consumer occasion and value tier; deploy localized merchandising to lift household penetration without eroding price architecture.
- For investors and M&A strategists: Target bolt‑on artisanal brands with strong IP in formulation or fermentation and clear scale pathways; avoid assets with unsustainable trade promotion burdens unless there is a credible cost transformation plan.
- For ingredient and equipment suppliers: Focus on melt/emulsion technologies and cost‑down solutions; co‑development partnerships can accelerate adoption and create stickier customer relationships.
Methodology & credibility
The study’s base year is 2025, with historical trends reviewed across 2020–2025 and a forecast horizon of 2026–2032. PW Consulting triangulated retail scanner data, manufacturer interviews, company filings, trade statistics and on‑the‑ground channel checks. Forecasts are produced via a bottom‑up model, validated with top‑down market checks and scenario sensitivity analyses. Deliverables include the underlying financial model and executive playbooks to move from insight to commercial execution.
Next steps — how to extract full strategic value
This executive overview is designed to establish the strategic contours and high‑value implications for decision‑making in 2026. The full report contains the detailed segmentation, granular regional and application breakdowns, SKU‑level economics, and downloadable models you need to execute on the strategies sketched here. Access the complete study to view the tables, company profiles, and transaction screening outputs that will enable prioritized action in the coming 12–18 months.
For detailed analysis of this topic, please visit the official page: Vegan Cheese and Processed Cheeses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com