

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Sulfonated Polyethersulfone Market to Hit $1,036.42M by 2032, 8.51% CAGR
By pmarketresearch, 2026-09-16
Unlocking Strategic Value in the Sulfonated Polyethersulfone Market: A 2026 Outlook
Executive Summary: The Imperative for Data-Driven Decision Making
As industries across the globe pivot toward sustainable materials and advanced membrane technologies, the strategic landscape for specialty polymers is undergoing a profound transformation. For senior executives, procurement leaders, and R&D directors, the question is no longer whether to engage with sulfonated polyethersulfone (S-PES) supply chains, but how to navigate the accelerating demand with precision. PW Consulting presents a comprehensive market intelligence briefing designed to equip decision-makers with the analytical depth required for 2026 and beyond.
The sulfonated polyethersulfone market represents a critical intersection of water infrastructure, energy transition, and medical innovation. Organizations that attempt to forecast capacity planning, pricing strategies, or partnership opportunities without granular visibility into market dynamics risk suboptimal capital allocation. Our latest research publication delivers the structured intelligence necessary to turn uncertainty into competitive advantage.
Macro Trajectory: Growth Patterns and Historical Momentum
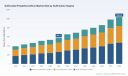
Understanding the market's velocity requires more than isolated snapshots. Our analysis anchors decision-making in a robust historical dataset spanning 2020 through 2025, establishing the baseline performance that informs forward-looking projections. Over this five-year window, the market demonstrated sustained expansion, climbing from approximately 390.45 million USD to 585.5 million USD. This upward trajectory reflects compounding demand across multiple end-use sectors and the gradual maturation of sulfonation technologies.
Looking ahead, the forecast period extends through 2032, offering a sufficiently long horizon to accommodate multi-year product development cycles, regulatory implementation timelines, and capital investment returns. Our projections indicate the market will advance to roughly 655.69 million USD in 2026, continuing its expansion to reach 1,036.42 million USD by the terminal forecast year. This path reflects a compound annual growth rate of 8.51 percent, a figure that signals a healthy, structurally supported expansion rather than a temporary cyclical spike. Such a CAGR demands that organizations institutionalize monitoring mechanisms and build strategic flexibility into their operational roadmaps.
For enterprises evaluating market entry, capacity expansion, or supply agreements, these figures provide an essential north star. Yet the macro view is only the beginning. The real strategic value lies in dissecting the drivers, constraints, and competitive variables that shape this growth curve.
Why 2026 Demands a Refined Analytical Lens
The year 2026 marks a pivotal inflection point for several reasons. Production technologies are transitioning from pilot and early-commercial stages into more scalable operations, particularly in Asia, where manufacturing capacity and process innovation are accelerating. At the same time, regulatory frameworks concerning polymer disposal and manufacturing processes are tightening globally, altering cost structures and influencing material selection decisions. Organizations that rely on legacy assumptions about feedstock availability, pricing stability, or application adoption rates will find themselves misaligned with the emerging reality.
Furthermore, the positioning of sulfonated polyethersulfone as a hydrocarbon-based alternative to perfluorocarbon sulfonic acid polymers introduces both opportunity and complexity. Cost considerations, environmental compliance expectations, and end-user preferences are simultaneously reshaping procurement criteria. Decision-makers need to understand not just where the market is heading, but how the underlying substitution dynamics will play out across specific application verticals and geographic corridors.
Inside the Report: Actionable Intelligence for Strategic Planning
Our publication is engineered for practical application. It is not merely a data repository; it is a structured analytical toolkit designed to support scenario planning, competitive positioning, and risk assessment. The report delivers a multi-layered examination of the market environment, integrating quantitative forecasting with qualitative interpretation of industry forces.
- Demand and Supply Integration: The analysis maps how production volumes, pricing benchmarks, and capacity expansions interact across the value chain. We examine the role of key intermediates and monomer precursors, including the contribution of diphenyl sulfone to sulfone polymer production, to illuminate cost drivers and supply sensitivity.
- Production Context and Unit Economics: Detailed context is provided on recent production milestones, including global output volumes and average selling price indicators, giving readers a grounded sense of the commercial landscape surrounding specialized sulfonated grades.
- Application and Technology Segmentation: The report breaks down market structures by sulfonation degree and by application, allowing executives to evaluate where value creation is concentrated and how technical specifications influence purchasing decisions. The inclusion of controlled sulfonation degrees and molecular weight considerations reflects the reality that performance requirements vary sharply across membrane blends, ion exchange systems, and separation processes.
- Regulatory and Environmental Dynamics: A dedicated examination of how stricter environmental regulations concerning polymer manufacturing and disposal shape market behavior ensures that compliance risk is treated as a strategic variable rather than a peripheral concern.
Competitive Landscape and Regional Dynamics
The market structure reflects a notable degree of concentration, yet one that still leaves substantial room for specialized players and regional innovators. Our competitive assessment addresses the interplay between established suppliers and emerging entities, highlighting how proprietary sulfonation technologies, molecular weight retention strategies, and process efficiencies differentiate participants in a technically demanding field.
The competitive environment is not monolithic. Companies are pursuing distinct technical pathways, from direct polymerization approaches that seek precise control over sulfonation degree and molecular weight to novel sulfonation methods that prioritize high molecular weight retention through multiple international patents. Some participants focus on pilot-stage offerings and specialized grades such as light brown powder formulations with targeted sulfonation levels, while others supply materials tailored for antibacterial blend composite membranes, dye separation applications, or nonfluorinated membrane solutions. This fragmentation of technical strategy creates both partnership opportunities and competitive friction points that executives must navigate with care.
Application Value Chains and Sulfonation Technology Spectrum
One of the most decision-relevant dimensions of this market lies in the relationship between sulfonation intensity and end-use suitability. Different applications impose different requirements for ion conductivity, membrane morphology, fouling resistance, and chemical stability. As a result, the market naturally segments into tiers defined by sulfonation degree, each with its own supply-demand equilibrium and technological trajectory.
Higher sulfonation ranges are often aligned with applications demanding elevated ion exchange capacity, while medium and lower ranges serve contexts where balance between hydrophilicity, mechanical integrity, and cost is critical. The report explores how these ranges map to real-world usage, including the development of antifouling blends for water treatment membranes, ion exchange membranes for redox flow batteries, and nonfluorinated alternatives for electrodialysis and cation exchange systems.
Sulfonated Polyethersulfone Market
Polysulfone Resin Market
On the application side, water and wastewater treatment stands as a primary demand pillar, reflecting ongoing infrastructure investment and the search for high-performance membrane materials. Proton exchange membrane applications represent another major axis of growth, tied to energy conversion and storage technologies. Medical and biotechnology uses add a performance-sensitive layer to the demand profile, while industrial gas separation and other specialized applications contribute additional pockets of differentiated demand. The report dissects these streams without overgeneralizing, ensuring that readers can identify which segments offer the most promising alignment with their product portfolios, capabilities, and strategic ambitions.
Strategic Implications for Market Entry, Expansion, and Partnership
For organizations evaluating 2026 planning cycles, the strategic implications of this market extend well beyond headline growth figures. The combination of an 8.51 percent CAGR, evolving production technologies, and a shifting regulatory backdrop means that static business cases can quickly become outdated. Executives need dynamic frameworks that can accommodate changes in feedstock availability, regional demand shifts, and the commercial readiness of competing material classes.
Success in this environment depends on several interconnected capabilities. First, it requires a clear understanding of where technical differentiation truly matters, whether through sulfonation process innovation, molecular weight control, or application-specific blend formulation. Second, it demands disciplined assessment of regional demand patterns and supply chain resilience, given the concentration and distribution of market activity across major geographic areas. Third, it calls for proactive scenario planning around substitution risk, especially as cost and environmental considerations continue to elevate the appeal of hydrocarbon-based membrane alternatives relative to perfluorocarbon options.
The report supports these needs by integrating market structure, competitive behavior, and technology development into a unified analytical narrative. Decision-makers can use the output to evaluate supplier qualification strategies, refine product roadmap priorities, and assess M&A or partnership targets with a more complete picture of market momentum and technical differentiation.
Conclusion: Converting Intelligence into Advantage
The sulfonated polyethersulfone market is entering a phase in which informed strategy will separate value creators from passive participants. Growth is real, technology is advancing, and competitive differentiation is increasingly tied to process innovation and application engineering. Yet the full strategic picture cannot be captured through summaries alone. The granularity required to make high-confidence decisions—down to the interaction of sulfonation degrees, application demand, regulatory responses, and competitive positioning—is contained within the full research analysis.
PW Consulting's market study offers the depth, structure, and forward-looking rigor that executive teams need to navigate 2026 with confidence. For organizations ready to move from general awareness to actionable intelligence, the complete report provides the detailed segmentation, competitive profiling, and scenario-based interpretation necessary to translate market momentum into measurable strategic outcomes.
For detailed analysis of this topic, please visit the official page: Sulfonated Polyethersulfone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cephalosporin Intermediates Market Projected to Reach USD 567 Million by 2032 at 5.4% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence Report: Navigating the 2026-2032 Cephalosporin Intermediates GCLE Market
The global pharmaceutical supply chain stands at a critical inflection point. As we move beyond the volatility of the early 2020s, the demand for essential antibiotic intermediates has stabilized into a trajectory of steady, calculated growth. For stakeholders in the pharmaceutical manufacturing sector, understanding the nuances of the Cephalosporin Intermediates GCLE Market is no longer optional; it is a prerequisite for resilient strategic planning. This article serves as an executive preview of our latest comprehensive market research, designed to equip leadership teams with the foresight needed to navigate the forecasting period of 2026 through 2032.
Our analysis indicates that the market is poised for expansion, driven by persistent healthcare demands and evolving manufacturing dynamics. However, surface-level growth figures often mask the complex interplay of raw material dependencies, regional concentration risks, and competitive maneuvering that define actual profitability. This report dissects those layers, offering a granular view of where value is created and where vulnerabilities lie.
Market Trajectory and Historical Context
The foundation of any strategic forecast lies in a robust understanding of historical performance. Our research tracks the market revenue from 2020 through the base year of 2025, providing a five-year historical lens against which future projections are calibrated. The data reveals a market that has demonstrated resilience despite global logistical disruptions. Starting from a valuation of approximately 312.45 Million USD in 2020, the sector climbed to 392.36 Million USD by 2025. This upward trend underscores the inelastic demand for cephalosporin antibiotics, which remain a cornerstone of global infectious disease treatment protocols.
Cephalosporin Market
Looking forward, our forecast models project a consistent Compound Annual Growth Rate (CAGR) of 5.4 percent over the forecast period. By 2032, the market is expected to reach a valuation of 566.97 Million USD. While these macro figures suggest a healthy environment, the strategic value for decision-makers lies in understanding the velocity and sustainability of this growth. A 5.4 percent CAGR implies a maturing market where share gain becomes increasingly difficult, shifting the focus from pure volume expansion to efficiency, quality differentiation, and supply chain security. The transition from the historical period to the forecast period marks a shift from recovery to optimization, requiring firms to adapt their capital allocation strategies accordingly.
Cephalosporin Intermediates GCLE Market
Operational Deep Dive: Report Contents and Methodology
To support high-stakes decision-making, this research report moves beyond top-line estimates. It is structured to provide actionable intelligence across several critical dimensions. The methodology integrates primary interviews with industry participants and secondary research from regulatory filings, trade analyses, and technical literature. The following components define the scope of our operational analysis:
- Segmentation by Product Grade: The market is bifurcated into High Purity Grade, defined as above 99 percent, and Standard Grade, typically at 98 percent. The report analyzes the revenue contribution and strategic importance of each grade, highlighting how purity specifications influence downstream API manufacturing costs and regulatory compliance.
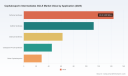
- Application-Specific Demand: We examine the consumption patterns across key synthesis pathways, including Cefixime, Cefdinir, Cefprozil, and Cefcapene Pivoxil. Understanding the specific demand drivers for each antibiotic synthesis route allows manufacturers to align production capacities with the most lucrative therapeutic segments.
- Regional Distribution Analysis: The study maps revenue flows across major geographical zones. While Asia Pacific remains a dominant force in volume, the report details the strategic nuances of Europe, North America, Latin America, and the Mideast and Africa, focusing on import dependencies and local manufacturing capabilities.
- Supply Chain Risk Assessment: A dedicated section evaluates the vulnerabilities in the raw material supply chain, specifically focusing on the procurement of key precursors and the impact of logistical factors on export expenses.
This structure ensures that readers do not merely see the size of the pie, but understand the ingredients, the bakers, and the distribution channels. For procurement officers and supply chain managers, the segmentation data offers a blueprint for negotiating contracts and securing supply lines. For strategic planners, the regional analysis highlights where capacity expansion might yield the highest return on investment relative to regulatory environments.
Competitive Landscape and Key Players
Market concentration is a vital indicator of competitive intensity and pricing power. Our analysis identifies a moderately concentrated market structure, where the top three players hold a significant portion of the revenue share, and the top five entities command a majority of the market. This concentration suggests that while there is room for new entrants, established players benefit from economies of scale and established supply chain relationships, particularly regarding critical raw materials.
The competitive field is characterized by specialized manufacturers who have invested heavily in the specific chemical synthesis routes required for GCLE production. Key companies shaping the landscape include:
- Otsuka Chemical Co., Ltd.: Headquartered in Osaka, Japan, this firm is a primary developer and manufacturer of GCLE. They operate dedicated production facilities, including a plant in India, positioning them as a critical link in the β-lactam intermediate supply chain. Their long-standing expertise makes them a benchmark for quality and technical capability.
- CSPC Cenway Tianjin Pharmaceuticals Co., Ltd. and Tianjin Gencom Pharmaceutical Co., Ltd.: Based in Tianjin, China, these entities are active suppliers of GCLE intermediates for cephalosporin API production. Their presence underscores the significance of the Tianjin region as a hub for pharmaceutical intermediates.
- Tianjin Jinkang, Ningbo Renjian Pharmaceuticals, Shandong Ruiying Pharmaceutical Group, Jiangsu Haici Biopharmaceuticals, and Xindi Bio: These listed global manufacturers represent a broad swath of production capacity across China. Their involvement in the GCLE market highlights the competitive pressure on pricing and the importance of scale in securing raw material contracts.
- Virchow Group / Virchow Petrochemicals Private Limited: Operating out of Telangana, India, this group manufactures and supplies GCLE for cephalosporin intermediates. Their presence adds a layer of diversification to the supply base outside of China, which is strategically relevant for buyers seeking to mitigate geographic concentration risk.
- Otsuka Chemical (India) Private Limited: Located in Haryana, this entity serves as a manufacturing plant focused on GCLE production, extending the Japanese parent company's reach into the Indian market, which is a key production base for export-oriented cefixime.
The presence of both Japanese technology leaders and large-scale Chinese manufacturers creates a dynamic competitive environment. Buyers must navigate the trade-offs between technical precision, cost efficiency, and supply security. The report provides detailed profiles on these entities, analyzing their production capacities, strategic positioning, and potential vulnerabilities.
Critical Market Dynamics and Constraints
Strategic decisions cannot be made in a vacuum. The GCLE market is subject to specific structural constraints and regulatory dynamics that significantly influence margin potential and supply reliability. Our research highlights several critical factors that industry leaders must monitor closely during the 2026-2032 period.
Raw Material Dependency and Penicillin-G: A fundamental constraint in GCLE production is the reliance on Penicillin-G as the key raw material. Industry data indicates that this precursor is entirely procured from China with no alternative sources currently available at scale. This creates a single-point-of-failure risk in the supply chain. Historical technical literature notes that domestic Chinese processes have faced challenges regarding high costs and quality issues in the past, leading to periods of continued reliance on imports in certain contexts. This dependency means that any disruption in the Penicillin-G supply chain directly impacts GCLE availability and pricing.
Regulatory Schemes and Export Orientation: Regulatory frameworks play a pivotal role in shaping market flows, particularly in India. Advanced authorization schemes have been implemented that allow GCLE suppliers to import Penicillin-G without minimum import price restrictions for export-oriented cefixime production. This regulatory nuance is crucial for manufacturers operating in India, as it affects the landed cost of raw materials and the competitiveness of the final exported product. Understanding these regulatory levers is essential for cost modeling and margin protection.
Logistical Factors and Regional Dominance: China dominates the export of cephalosporin API and intermediates. However, this dominance is not without friction. Logistical factors such as high international shipping costs and container shortages have historically affected export expenses. While supply chains have adapted, the potential for renewed logistical volatility remains a risk factor that must be priced into long-term contracts. The report analyzes how these logistical realities interact with regional market sizes to determine true net revenue potential for exporters versus domestic consumers.
Strategic Implications for 2026 and Beyond
As we enter the forecast period, the strategic imperative shifts from navigating crisis to managing growth amidst constraints. The projected growth from 397.57 Million USD in 2026 to nearly 567 Million USD by 2032 offers opportunity, but realizing this value requires sophisticated management of the underlying dynamics.
For procurement leaders, the concentration of raw material sourcing in China necessitates dual-sourcing strategies where possible, or stronger contractual safeguards with existing suppliers. For production planners, the distinction between High Purity and Standard Grade segments offers a pathway to margin improvement, as high-purity grades often command premium pricing in regulated markets. For executives evaluating market entry or expansion, the regional concentration suggests that proximity to key API manufacturing hubs in Asia Pacific may offer logistical advantages, though regulatory access in North America and Europe remains a key value driver.
Furthermore, the competitive landscape indicates that consolidation may continue as larger players leverage their scale to secure raw material advantages. Smaller players may need to find niches in specific application segments, such as Cefcapene Pivoxil Synthesis, where volume requirements are lower but specialization is higher. The interplay between the top five companies and the broader field of listed manufacturers will define price stability and innovation rates in the coming years.
Conclusion: The Value of Precision Intelligence
In a market defined by specific technical requirements, raw material dependencies, and regional regulatory nuances, general market intelligence is insufficient. Success in the Cephalosporin Intermediates GCLE Market during the 2026-2032 period will belong to those who understand the granular details of supply chain vulnerabilities, competitive capabilities, and segmentation dynamics.
This report provides the framework for that understanding. It bridges the gap between high-level market sizing and the operational realities of manufacturing and procurement. However, the full depth of the data, including precise revenue splits by region and application, detailed company profiles, and specific risk mitigation strategies, is contained within the full research document. For organizations committed to securing their supply chains and optimizing their market position, accessing the complete intelligence is the next logical step.
We invite stakeholders to review the full report to leverage these insights for their 2026 strategic planning cycles. The data presented here is the foundation; the complete analysis is the tool required to build a resilient future in the global pharmaceutical intermediates market.
For detailed analysis of this topic, please visit the official page: Cephalosporin Intermediates GCLE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Borated Polyethylene Market Hits USD 217.04M in 2025, Projected 5.18% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in Industrial Grade Borated Polyethylene Materials: A 2026 Market Intelligence Preview
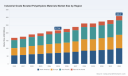
The industrial grade borated polyethylene market stands at a critical inflection point as of 2026. With global revenue projections indicating steady expansion from approximately 217 million USD in the base year of 2025 toward over 309 million USD by the end of the forecast window in 2032, the sector demonstrates a compound annual growth rate that underscores sustained demand for neutron shielding solutions across nuclear, medical, and defense verticals. For strategic planners, procurement leaders, and competitive intelligence teams, navigating this landscape requires more than top-line figures. It demands a granular understanding of material formulations, regulatory compliance pathways, regional supply dynamics, and the evolving positioning of key manufacturers. This preview outlines the strategic architecture of our newly released market research study and explains why access to its full analytical framework will be indispensable for enterprise decision-making throughout 2026 and beyond.
Worldwide Industrial Grade Ammonium Pentaborate Market
The Macro Trajectory: Reading Growth Beyond the Headline
Historical revenue patterns from 2020 through 2025 reveal a market that has consistently navigated raw material volatility, shifting nuclear energy policies, and evolving medical radiation protection standards. The transition into the 2026-2032 forecast period suggests that growth will not be linear. Instead, it will be shaped by uneven adoption cycles across applications, divergent regional procurement rhythms, and material substitution pressures that reward manufacturers capable of balancing cost efficiency with certified shielding performance. The study maps these inflection points without relying on surface-level percentage breakdowns. Instead, it contextualizes how revenue concentration, formulation preferences, and application-specific procurement behaviors interact to create pockets of margin expansion and competitive vulnerability. Readers who engage with the complete report will gain a structured view of where volume growth converges with pricing resilience, and where commoditization risks threaten undifferentiated producers.
Segmentation Dynamics: Boron Loading, Applications, and Regional Realities
The commercial architecture of borated polyethylene is fundamentally defined by boron concentration, application criticality, and geographic supply chain maturity. Formulations ranging from lighter boron loadings to high-concentration variants serve distinct shielding requirements, with procurement decisions often dictated by neutron flux profiles, spatial constraints, and regulatory specifications. Similarly, end-use environments span from nuclear power reactors and medical radiotherapy facilities to research accelerators, nuclear propulsion systems, and radioactive waste containment. Each vertical imposes unique certification demands, thickness tolerances, and fabrication expectations that directly influence supplier selection.
Regional supply and demand patterns further complicate the competitive picture. Manufacturing footprints, logistics infrastructure, and local regulatory frameworks create divergent cost structures and delivery timelines. The study disentangles these regional dynamics by examining how procurement hubs interface with production clusters, how import-export flows respond to certification bottlenecks, and how localized content requirements shape sourcing strategies. Rather than presenting static regional revenue splits, the analysis focuses on the operational mechanisms that determine which suppliers can reliably serve which markets, under what compliance conditions, and at what total cost of ownership.
Competitive Landscape: Strategic Positioning Among Core Players
The industry features a concentrated but differentiated supplier base, with leading manufacturers distinguished by proprietary processing methods, certification portfolios, customization capabilities, and vertical market focus. Several organizations have built recognizable identities around specific product architectures and application specializations, creating defensible niches within a market that increasingly rewards technical reliability and supply chain consistency.
-
King Plastic Corporation has reinforced its market presence through targeted exhibition participation, including appearances at the International Sign Expo and the NRPA Annual Conference, signaling continued engagement with both industrial and specialized material buyers. Its product positioning emphasizes trademarked shielding formulations and proprietary processing techniques designed to deliver flatness and dimensional consistency in large-format sheets and custom configurations.
Industrial Grade Borated Polyethylene Materials Market -
MarShield Custom Radiation Products has expanded its strategic alignment with nuclear energy initiatives by joining Canadians for CANDU, while maintaining a broad offering of borated polyethylene sheets, pellets, and custom shapes. Its certification ratings and fabrication services position it as a solutions-oriented supplier for nuclear, medical, and industrial neutron shielding requirements.
-
Emco Plastics maintains a strong compliance-oriented profile, offering borated HDPE sheets with multiple boron content options and adherence to military and ASTM specifications. Its ITAR registration and thickness/size versatility support demand from nuclear power plants, medical facilities, aerospace, and radioactive material storage and transport applications.
-
A&L Shielding focuses on cost-effective, lightweight neutron and gamma shielding solutions, emphasizing standard large-format sheet configurations for medical and industrial environments where installation efficiency and material economy are priorities.
-
Radiation Protection Products, Inc. supplies a recognizable purple-hued borated polyethylene line in standard and custom formats, serving nuclear reactors, medical vaults, linear accelerators, and research facilities with an emphasis on accessible standard inventory and custom fabrication flexibility.
-
NELCO Worldwide addresses security and propulsion-adjacent applications with both standard and higher boron content options, supporting cargo screening, border protection, and nuclear submarine-related shielding needs through configurable sheet formats and machining services.
-
Shandong Yasu New Material Co., Ltd. stands out for its highly customizable boron content range and broad product formats, including sheets, rods, and pellets, targeting nuclear power, medical therapy rooms, particle accelerators, and aerospace/defense applications. Its formulation flexibility positions it as a responsive supplier in markets where shielding specifications vary significantly across projects.
The full study evaluates these players through a structured competitive assessment framework, examining product differentiation, certification coverage, regional service reach, fabrication capabilities, and recent strategic moves. Rather than simply cataloging company profiles, the analysis identifies where competitive advantages are likely to persist, where price competition may intensify, and how recent partnerships and trade show engagements signal shifting commercial priorities.
Market Dynamics and Strategic Variables
Several operational and regulatory forces continue to shape procurement behavior and supplier competitiveness. Material pricing illustrates the premium associated with higher boron loadings, with standard 5% boron sheets carrying materially different cost profiles than 30% boron variants. This pricing gradient influences application selection, especially in projects where shielding performance requirements can be met through formulation optimization rather than blanket upsizing. Understanding these cost-performance tradeoffs is essential for buyers seeking to balance compliance, weight, spatial constraints, and budget.
Regulatory compliance remains a decisive filter in competitive access. Military specifications such as MIL-P-23536A and EB2562E continue to govern neutron shielding expectations for naval and defense-related deployments, while nuclear sector standards impose additional requirements on hydrogen density, aging effects, and spent fuel storage system compositions. Suppliers that can demonstrate consistent certification adherence, documentation rigor, and test-backed performance claims gain preferential access to high-assurance procurement channels. The study examines how these regulatory layers affect market entry barriers, customer retention, and the economics of qualification-led selling.
Supply chain resilience also warrants close attention. Fabrication services, custom machining, stocking strategies, and cut-to-size capabilities increasingly differentiate suppliers in contexts where end users prioritize project-ready materials over commodity sheet purchases. Companies that combine certified material supply with CNC or waterjet cutting, custom block and slab production, and responsive inventory positioning are better equipped to capture value in complex procurement environments. These capabilities are not merely service add-ons; they are increasingly central to supplier selection in medical, nuclear, and defense applications where installation precision and lead-time reliability carry substantial operational weight.
What the Study Delivers: Operational Intelligence for Decision-Makers
This market research is structured to translate market complexity into actionable strategic guidance. Beyond baseline sizing and trend mapping, the report provides a working view of how material technology, regulatory expectations, and procurement behavior intersect across the forecast period. It is designed for teams that need to evaluate supplier risk, prioritize market entry or expansion, calibrate product development roadmaps, and align sourcing strategies with evolving shielding requirements.
Key components of the study include:
-
A detailed segment architecture that explains how boron loading choices, application criticality, and regional procurement habits shape demand trajectories and margin dynamics.
-
A competitive positioning map that evaluates core manufacturers on formulation range, certification coverage, fabrication capabilities, and strategic signaling through partnerships and exhibition activity.
-
An analysis of pricing structure logic, showing how standard and high-concentration formulations create differentiated procurement economics across use cases.
-
A regulatory and compliance overlay that clarifies the role of military specifications, nuclear standards, and documentation requirements in shaping buyer preference and supplier eligibility.
-
Forward-looking scenario framing for the 2026-2032 period, highlighting where volume growth, application diversification, and supply chain maturity are likely to reshape competitive access.
The full report is built to support both strategic planning and execution-level decisions. It provides the contextual depth needed to interpret market movements, assess supplier capabilities, and anticipate where procurement standards and material specifications will tighten or evolve.
Why Strategic Access Matters in 2026
As enterprises navigate a market defined by steady growth, concentrated competition, and rising technical expectations, the cost of incomplete intelligence is increasingly measurable. Procurement teams that lack visibility into formulation economics may overspend on over-specified materials or under-specify shielding performance. Market expansion teams that rely on generic segmentation may misjudge regional readiness or overestimate the transferability of product offerings. Competitive analysts who overlook certification pathways and fabrication capabilities may misread which suppliers are truly positioned to win high-assurance contracts.
The study addresses these blind spots by connecting market structure to decision quality. It offers a disciplined framework for interpreting growth signals, assessing supplier reliability, and anticipating where regulatory or application-specific demands will alter purchasing behavior. For organizations operating in nuclear energy, medical radiation protection, research infrastructure, defense, or radioactive material handling, this intelligence provides a practical foundation for sourcing strategy, product planning, and competitive positioning.
Conclusion: Moving from Market Awareness to Strategic Action
The industrial grade borated polyethylene market is not simply expanding; it is maturing in ways that reward technical precision, compliance readiness, and supply chain flexibility. The trajectory through 2032 suggests continued demand growth, but the distribution of that growth will favor participants who can align formulation choices, certification strength, fabrication capability, and regional service capacity with the specific requirements of each application. Our full market research unpacks these dynamics with the depth required for confident strategic action. For decision-makers who need more than headline sizing and broad trend statements, the complete study offers the structured intelligence necessary to convert market momentum into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Industrial Grade Borated Polyethylene Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Single Mode Fiber Bundle Market to Hit $558.44M by 2032, Growing at 7.8% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Connected Decade: Navigating the Single Mode Fiber Bundle Market 2026–2032
An Executive Introduction to PW Consulting's Latest Market Research
The global telecommunications infrastructure is undergoing a structural transformation where bandwidth density, latency imperatives, and physical layer reliability are no longer engineering constraints but strategic differentiators. Single mode fiber bundles have become the connective tissue for enterprise backbones, hyperscale data centers, terrestrial and submarine networks, and increasingly specialized photonic applications. For decision-makers planning capital allocation, supplier partnerships, or product roadmaps through the end of the decade, the Single Mode Fiber Bundle Market represents both an infrastructure enabler and a competitive battleground. This article introduces PW Consulting's latest market research, outlines the analytical architecture of the study, and explains why its findings are designed to support executive decisions during the 2026 planning cycle and beyond.
The research is built on a structured quantitative foundation and enriched by qualitative intelligence on competitive positioning, regulatory shifts, raw material dynamics, and product innovation. The objective is not merely to chart historical movement, but to translate observable market signals into actionable strategic guidance. Readers who require granular volume splits, region-by-region revenue breakdowns, or detailed application-level monetization figures will find those specifics reserved for the full report and its accompanying data modules; this introduction is designed to demonstrate methodological rigor and market relevance while directing procurement and strategy teams toward the complete intelligence package.
From Historical Trajectory to 2032 Outlook: Why the Market Narrative Matters
Market intelligence is most valuable when it connects backward-looking evidence with forward-looking scenarios. The study synthesizes a consistent historical series and extends the analysis through a twelve-year forecast window, allowing executives to evaluate growth durability rather than short-term volatility. The dataset anchors its base year at 2025 and carries a forecast period from 2026 through 2032. During the historical window, revenue progression reflects a market that has matured its product standards, expanded deployment templates, and absorbed cycles of supply and demand adjustment. By the base year, the overall market is positioned at a materially higher revenue level than earlier in the decade, and the forward trajectory indicates continued expansion. The projected compound annual growth rate over the forecast horizon is 7.8%, expressed in USD millions, signaling a market that remains structurally attractive even as competitive intensity, input cost variability, and regional trade dynamics evolve.
Why does this trajectory carry strategic weight? Because single mode fiber bundles are no longer a homogeneous commodity category. They are deployed across dense aggregation points, high-performance sensing environments, biomedical imaging systems, aerospace sensing architectures, and industrial laser delivery platforms. Each deployment context imposes distinct requirements for attenuation stability, bend response, polarization behavior, connectorization, and mechanical robustness. The growth outlook therefore reflects not just volume accumulation, but a compounding shift in how fiber bundles are specified, integrated, and valued across end-use environments. For strategists, the message is clear: revenue growth is real, but the growth is unevenly distributed across technology variants and use cases, which makes segmentation intelligence essential for sourcing, pricing, and channel strategy decisions.
Research Architecture: What the Study Contains and How It Supports Decision-Making
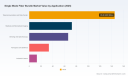
The report is organized to move from macro market framing to operational detail, allowing different internal audiences to extract value without losing sight of the overall market story. At the top level, the research establishes market sizing and forecast logic, with a consistent base year and forecast period and a clear currency and revenue unit convention. That foundation is supplemented by segmentation frameworks that organize the market by region, by type, and by application. These frameworks are constructed to show relative scale and structural importance rather than to reduce the market to simplistic share tables. Decision-makers can use the resulting structure to assess where demand concentration exists, how regional deployment patterns diverge, and which product families are gaining relevance as networks move toward higher density and specialized photonic integration.
Beyond sizing and segmentation, the study maps the competitive landscape with company-level profiles, product-technology orientation, headquarters locations, and digital references for primary verification. This section is designed for procurement leadership, mergers and acquisitions screening, channel partnership evaluation, and competitive response planning. The report also includes an ongoing developments tracker that captures product showcases, trade-show introductions, and architectural shifts relevant to bundled single mode fiber. Regulatory and trade context is integrated where it affects market dynamics, including technology transition policy, broadband classification rulings, raw material cost movements, and tariff actions that influence import exposure for fiber optic components. Together, these elements form a decision-support platform rather than a static market snapshot.
To help readers understand the qualitative depth of the study, the following categories outline the practical intelligence available in the full report:
- Macro market sizing and forecast logic, including the base year, historical window, forecast horizon, growth rate, and revenue unit conventions, structured to support scenario planning and investment timing.
- Segmentation frameworks by region, by type, and by application, built to reveal structural demand concentration, deployment preferences, and product-family relevance without reducing the analysis to isolated share statistics.
- Company profiles and competitive positioning for major participants across North America, Europe, Asia Pacific, and broader global supply chains, with indications of product focus, technology orientation, and deployment contexts.
- Industry dynamics coverage that integrates regulatory developments, broadband policy shifts, raw material pricing behavior, and trade actions, enabling risk assessment for sourcing and import-dependent procurement.
- Recent innovation and product showcase intelligence, including multi-core fiber platforms, fiber array units, and hybrid architecture demonstrations that illustrate where bundle architectures may interface with next-generation optical systems.
The Competitive Landscape: Structures, Specialization, and Strategic Posture
The single mode fiber bundle market is shaped by a set of globally active manufacturers and technology providers whose portfolios span telecom and data center backbones, bend-insensitive cable designs, air-blown fiber infrastructure, specialty photonics, and high-density interconnect assemblies. Market concentration indicates a meaningful degree of consolidation at the top of the field, with the largest participants collectively holding a substantial share of revenue. That concentration matters for buyers because it influences lead-time reliability, specification flexibility, regional service coverage, and the pace at which new product architectures move from lab to commercial bundle configurations.
Among the most visible participants, Corning maintains a prominent position through single mode fiber families used in high-density bundle configurations, including cable designs that place multiple fibers within a bundle for telecom and data center deployments. Sumitomo Electric Lightwave provides OS2 single-mode fiber bundles engineered for air-blown fiber infrastructure, with color coding aligned to common industry standards and ribbon variants intended for high-density network installations. Prysmian Group focuses on bend-insensitive single-mode fiber cables suited to bundled high-density applications in telecom backbone and fiber-to-the-home networks. CommScope supplies single-mode fiber solutions for backbone bundles in enterprise and telecommunications networks, while Nexans produces fiber optic cables for bundled configurations in terrestrial and submarine telecom projects. Furukawa Electric and Fujikura contribute single mode fiber and cable assemblies oriented toward long-haul and data center applications as well as telecom and specialty network integrations. Yangtze Optical Fibre and Cable represents a large-scale producer active in bundled cable infrastructures for broadband and backhaul deployments.
The market also includes participants whose relevance extends beyond mainstream telecom bundles into sensing, imaging, and specialty delivery. LEONI supplies specialty single-mode fiber bundles for industrial, medical, and aerospace applications that require precise signal transmission. Molex offers single-mode fiber optic interconnects and bundled assemblies for high-density telecom and data communications. Thorlabs manufactures custom and standard single-mode fiber bundles for spectroscopy, sensing, and instrumentation applications. CeramOptec specializes in fused silica single-mode fiber bundles for high-power laser delivery, medical, and industrial uses. OFS Fitel develops single-mode optical fibers and connectivity solutions adaptable to bundled configurations for telecom networks. IDIL Fibres Optiques produces custom single-mode fiber bundles with various connectors for scientific and industrial photonics.
What distinguishes this competitive set is the coexistence of broad infrastructure scale and deep application specialization. Some participants compete primarily on volume, deployment scale, and network-grade reliability. Others compete on custom engineering, polarization behavior, high-power handling, or metrology-grade signal integrity. For corporate strategists, the implication is that supplier selection cannot be reduced to a single cost benchmark. Sourcing strategy must account for the required performance envelope, the importance of regional supply continuity, and the risk that tariff or raw material pressures may affect import-dependent procurement. The report's company-level coverage supports this evaluation by aligning each participant's product orientation with the deployment contexts most relevant to its core offerings.
Loose Buffered Fiber Market
Market Dynamics in 2026: Policy, Trade, and Input Cost Pressure
The market does not unfold in a vacuum. During the recent planning window, several external forces have begun to influence how single mode fiber bundles are specified, produced, and deployed. Regulatory developments in the United States have reshaped the framework around legacy service transitions and broadband classification. In March 2026, the FCC adopted a Report and Order overhauling technology transition discontinuance rules, granting blanket section 214(a) authority for grandfathering legacy voice and lower-speed data services over copper while ensuring 911 connectivity in fiber transitions. Earlier policy actions, including the FCC's 2025 initiative to eliminate the Restore Net Neutrality proceeding, have been accompanied by court-level developments such as the US Court of Appeals for the Sixth Circuit decision in January 2025 that struck down the FCC's 2024 net neutrality reclassification order and returned broadband classification to Title I information services. For fiber deployment strategy, these shifts matter because they alter the regulatory backdrop against which legacy copper retirement, fiber build-out, and service continuity decisions are made.
Trade and input cost dynamics are equally relevant. Global fiber optic prices rose again in early 2026 due to ongoing supply chain dynamics affecting raw materials and production for single-mode fiber components. At the same time, the United States imposed 104% tariffs on certain Chinese-origin fiber optic products effective April 2025, impacting import costs for single-mode fiber components. These pressures create a dual challenge for procurement and strategic sourcing: cost visibility becomes more volatile, and regional sourcing exposure must be examined with greater care. Executive teams evaluating multi-year build plans need to consider whether cost assumptions remain durable under continuing raw material pressure and tariff-induced price adjustments, especially where import-dependent supply chains are involved.
On the innovation side, recent developments point to the expanding intersection between bundle architectures and next-generation optical systems. In March 2026, a trade show product showcase highlighted multi-core fiber portfolio elements alongside bundle and space optics platforms, including high-precision fiber array units for co-packaged optics systems featuring hybrid polarization-maintaining and single-mode fiber architecture. Product introductions of this kind do not merely signal laboratory interest; they indicate where fiber bundle engineering is beginning to interface with CPO, high-density interconnect, and advanced photonics integration pathways. For strategists, these developments are early indicators of how specification requirements and supplier capabilities may evolve over the forecast horizon.
Why This Research Is Strategically Valuable for 2026 Decisions
In a market defined by regional variation, product specialization, and policy sensitivity, high-level market totals are necessary but insufficient. Decision-makers need a framework that connects revenue scale to segmentation structure, competitive posture to sourcing risk, and macroeconomic signals to deployment timing. PW Consulting's Single Mode Fiber Bundle Market research is designed to provide that linkage. The study enables executives to assess whether their demand assumptions align with the broader growth trajectory, to identify which product families and deployment contexts are most likely to influence future revenue concentration, and to evaluate supplier landscapes in terms of technology fit rather than price alone.
The report's added value lies in its ability to translate complex signals into operating decisions. Procurement teams can use the segmentation and competitive coverage to refine vendor shortlists and assess import exposure under current tariff and raw material conditions. Strategy and corporate development teams can use the concentration data and innovation tracker to anticipate where specialty bundles may create differentiated value beyond conventional telecom deployments. Leadership teams planning infrastructure investments can use the forecast framework to test scenario assumptions against a consistent base year and forward growth path, then decide where timing, specification, and supplier diversification should be prioritized.
Importantly, the research balances transparency with restraint. The introduction makes the market narrative legible and the methodology credible, while reserving the most granular breakdowns for the full study. This design reflects the reality that senior decisions often depend on precise regional demand posture, detailed application-level scale, and specific supplier-by-supplier positioning that cannot be responsibly compressed into an overview. Readers who need those specifics are guided toward the complete report, where the segmentation splits, revenue detail, and company profiles can be inspected, compared, and incorporated into internal planning models.
Single Mode Fiber Bundle Market
How to Use This Study in Practice
The most effective use of the report begins with alignment. Strategy, procurement, engineering, and finance teams should first agree on the decision context: are they evaluating market entry, supplier diversification, capacity timing, pricing strategy, or long-term infrastructure investment? Once the decision question is defined, the market sizing and forecast sections provide the top-level context, while the segmentation frameworks help test whether planned assumptions are consistent with the structural distribution of demand across regions, product families, and application environments. The competitive profiles then support supplier assessment, and the dynamics section equips teams to incorporate policy, trade, and input cost variables into risk-adjusted plans.
For leaders who need to move quickly, the report's architecture allows targeted extraction without sacrificing strategic coherence. A sourcing review may focus on company profiles, regional supply considerations, and recent cost and tariff developments. A product strategy review may emphasize type segmentation, application deployment relevance, and the innovation tracker. A corporate development review may focus on concentration signals, competitive positioning, and product-family momentum. In each case, the study is designed to support decisions with evidence rather than anecdote, while still directing the reader to the full intelligence package for the precise figures and breakdowns that underpin internal modeling and negotiation strategy.
Conclusion: From Market Visibility to Decision Advantage
The Single Mode Fiber Bundle Market is entering a phase in which growth, specialization, and external pressure will all shape competitive outcomes during the 2026 planning cycle and through the forecast horizon. Revenue scale and trajectory provide the backdrop, but the decisive questions lie in how demand is distributed across regions and applications, how suppliers differentiate across telecom, sensing, imaging, and specialty delivery, and how policy and trade developments alter cost exposure and deployment timing. PW Consulting's market research is built to answer those questions with disciplined structure, company-level depth, and integrated industry context. For executives seeking a credible basis for investment, sourcing, and product strategy, the study offers a practical bridge between market intelligence and operational decision-making. Those who require the full segmentation detail, precise regional and application-level scale, and complete supplier coverage are encouraged to access the complete report to secure the data necessary for rigorous planning and confident execution.
For detailed analysis of this topic, please visit the official page: Single Mode Fiber Bundle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Used Cooking Oil for SAF Market Hits $2.87B in 2025, Projected 20.31% CAGR to $10.45B by 2032
By pmarketresearch, 2026-09-16
The UCO-to-SAF Imperative: Navigating a $10 Billion Transition by 2032
The aviation industry stands at a critical decarbonization inflection point, and used cooking oil has emerged as one of the most strategically vital feedstock vectors in the sustainable aviation fuel value chain. Our latest market research on the Used Cooking Oil for Sustainable Aviation Fuel market translates a rapidly compounding revenue trajectory into an actionable decision framework for executives, procurement leaders, and energy investors. Drawing on historical performance from 2020 through 2025 and a forward-looking forecast extending to 2032, the analysis captures how feedstock logistics, regulatory mandates, and refining pathway economics are converging to reshape competitive positioning across the global SAF ecosystem.
The headline trajectory is unmistakable. Revenue associated with UCO directed toward sustainable aviation fuel applications expanded from roughly $840 million in 2020 to approximately $2.87 billion in 2025, and the forecast arc accelerates sharply thereafter, reaching an estimated $3.49 billion in 2026 and climbing toward $10.45 billion by 2032. This expansion is anchored by a projected compound annual growth rate of 20.31 percent across the 2026–2032 forecast period. For strategy teams, the implication is straightforward: UCO is no longer a peripheral waste-stream story. It is becoming a structurally constrained, policy-driven commodity whose availability, pricing power, and geographic routing will determine which refiners, aggregators, and airline-affiliated fuel buyers can reliably meet blending obligations without incurring margin erosion.
Executing in this environment requires more than top-line forecasting. It demands a clear line of sight into collection-channel economics, conversion-pathway competitiveness, regional supply-chain resilience, and the contractual architectures that major processors are already locking in. The research is designed to deliver that precision without overwhelming decision-makers with undifferentiated data density. Instead, it surfaces the operational and strategic variables that actually move the needle when boards are allocating capital, negotiating offtake terms, or evaluating entry into the HEFA and co-processing value chains.
Why This Research Matters for 2026 Decision-Making
2026 is a pivot year for sustainable aviation fuel procurement and feedstock strategy. Regulatory clocks have already started ticking in key markets, and the earliest compliance cycles are exposing the operational realities of scaling UCO-dependent production. The European Union’s ReFuelEU Aviation mandate requires a 2 percent SAF blending baseline from January 2025, climbing toward 6 percent by 2030, with UCO-based HEFA positioned as the dominant compliant pathway in the near term. In the United Kingdom, the SAF mandate took effect in January 2025 with a 2 percent target, and provisional data from the first ten months of 2025 indicated that 1.63 percent was achieved, entirely from UCO feedstock. These early compliance readings matter because they reveal both the speed at which demand can materialize and the dependency that emerges when a single feedstock category carries the bulk of early blending requirements.
On the incentive side, the United States Section 45Z clean fuel production credit provides up to $1 per gallon for SAF through 2029 under updated legislation, with eligibility restricted to North American feedstocks. That restriction changes the strategic calculus for anyone modelling U.S. production economics or planning feedstock sourcing across borders. Meanwhile, trade dynamics are reshaping physical supply routes: U.S. imports of UCO from China declined significantly in 2025 due to tariff pressure, pushing sourcing activity toward Australia, South Korea, and Malaysia even as total import volumes remained robust at approximately 2 million metric tons through November 2025. These are exactly the kinds of structural shifts that can undermine a supply plan if they are treated as background noise rather than core inputs to scenario design.
Used Cooking Oil for Sustainable Aviation Fuel Market
The research therefore treats feedstock availability as a strategic risk variable, not a static assumption. It maps how collection infrastructure, pre-processing capacity, and long-term supply commitments interact with policy timelines, so that executives can stress-test their SAF sourcing strategies against realistic constraints instead of optimistic averages.
What the Report Covers: An Operational Roadmap, Not Just a Forecast
The study is built around practical decision support. Beyond the macro revenue trajectory and multi-year forecast, the report examines the structural segmentation that determines where value accrues and where bottlenecks form. It analyzes collection and supply channels including food service collection, industrial food processing, and household collection, with attention to how each channel’s logistics profile affects scalability, contamination risk, and feedstock consistency. It also evaluates application pathways, particularly the HEFA production pathway and refinery co-processing, explaining how capital intensity, conversion yields, and integration with existing refining assets shape competitiveness across different operator profiles.
Worldwide Kenaf Seed Oil Market
Regional analysis is presented to help teams understand where supply depth, processing infrastructure, and policy momentum are most aligned. Rather than forcing a single narrative, the research disaggregates market behavior so that strategy leaders can identify which geographies offer the most reliable feedstock aggregation, where co-processing assets are best positioned to absorb waste oils, and where import dependency may create vulnerability under shifting trade or tariff regimes.
Equally important, the report connects quantitative structure to real-world industry movement. It incorporates recent developments that illustrate how the market is actually behaving as procurement contracts, production ramp-ups, and partnership agreements begin to lock in supply for the 2026–2030 window. These activity signals are essential for interpreting whether observed price behavior reflects temporary tightness or a more durable re-rating of UCO as a premium SAF feedstock.
Competitive Positioning in a Concentrated but Fragmented Value Chain
The competitive landscape reveals a market that is consolidated at the top yet highly dependent on a broad network of collectors, processors, and integrators. Market concentration data indicates a CR3 of approximately 38.4 percent and a CR5 of about 52.15 percent, suggesting that while leading players hold meaningful share, a substantial portion of supply and conversion capacity remains distributed across specialized operators. For entrants and incumbents alike, the strategic question is less about aggregate share than about securing dependable feedstock flow, differentiating by conversion route, and building long-term contractual insulation against price volatility.
Among the most prominent players, Neste stands out as a global leader in renewable fuels with extensive UCO collection and processing networks, including assets acquired in the United States, feeding HEFA-based SAF production across multiple refineries through dedicated UCO-to-SAF pathways. Darling Ingredients operates through its Diamond Green Diesel joint venture, supplying UCO and other waste feedstocks and delivering neat SAF produced from UCO, animal fats, and other renewables. Greenergy International functions as a major collector and supplier of UCO for biofuel and SAF production, supported by established European and international aggregation networks that reinforce HEFA pathway supply. In the UK, Olleco specializes in UCO collection and pre-processing for conversion into biodiesel and SAF feedstocks, while Brocklesby Ltd collects and processes UCO into refined feedstock specifically for sustainable aviation fuel production. Argent Energy focuses on waste-based feedstocks including UCO for advanced biofuels and SAF.
Across the Atlantic, Baker Commodities Inc. provides UCO collection and recycling services that supply feedstock for renewable diesel and SAF facilities, and Mahoney Environmental Inc. operates as a UCO collection specialist delivering feedstock directly into Neste’s SAF production. Quatra supplies large volumes of European UCO under long-term agreements for processing into SAF at biorefineries. Sanimax collects and processes animal fats and UCO for renewable fuel and SAF applications across Canada and the United States. Münzer Bioindustrie GmbH processes UCO and waste oils into biofuels with SAF feedstock capabilities. World Energy operates biorefineries converting UCO into high volumes of SAF. EcoCeres converts UCO and agricultural waste into SAF and other fuels using proprietary technology. In Asia, PT Pertamina has completed its first SAF shipment from UCO and is developing co-processing capabilities for UCO-based SAF, while Sinopec operates UCO-based bio-aviation fuel plants using proprietary SRJET technology. TotalEnergies receives UCO supplies for biorefineries producing SAF and operates co-processing units using waste oils. XCF Global Inc., through its New Rise Renewables operations, runs HEFA SAF facilities using waste- and residue-based feedstocks including UCO.
What makes this competitive set strategically interesting is not simply the roster of names, but the pattern of recent commitments and operational milestones. In August 2025, PT Pertamina completed its first shipment of aviation fuel produced from used cooking oil, signaling state-backed momentum in UCO-based SAF adoption. In July 2025, Quatra signed a 15-year agreement to supply TotalEnergies with 60,000 tons of European used cooking oil annually starting in 2026 for biodiesel and SAF processing, illustrating how long-duration contracts are being used to stabilize feedstock access. In December 2024, Darling Ingredients delivered its first batch of neat SAF produced using UCO and other renewable feedstocks via Diamond Green Diesel to Avfuel Corporation, marking a concrete step in distributed neat-SAF supply. In February 2025, XCF Global’s New Rise Reno facility began ramp-up with HEFA technology using waste feedstocks, with SAF production expected to resume in early 2026. In March 2025, Cosmo Oil partnered with SAFFAIRE SKY ENERGY, Suita City, JGC Holdings, and REVO International to promote domestic UCO collection for Japan’s first large-scale locally-made SAF production targeting 30,000 kiloliters per year.
These moves matter because they show the market hardening around long-term supply architecture. A collector secures a 15-year off-take commitment; a refiner brings a HEFA line back into ramp-up; a state-owned energy company executes its first UCO-based SAF shipment; a domestic consortium organizes around localized collection to reduce import dependency. Each event is a data point in a broader pattern: the companies that can combine reliable collection, credible processing credentials, and policy-aligned conversion pathways are positioning themselves to capture the most durable margins as mandates intensify.
Feedstock Economics, Regulatory Tailwinds, and the 2026–2032 Window
Pricing behavior in the UCO market has become an integral part of SAF project economics. Indicative bulk UCO prices in 2025–2026 reached the $750–$1,250 per ton range in Europe and North America, with spikes above $1,400 per ton in tight markets, driven by rising SAF and biodiesel demand. For procurement and finance teams, this range is not just a commodity note; it is a margin sensitivity variable that interacts directly with blending mandates, incentive eligibility, and the competitiveness of alternative feedstocks. When UCO prices spike, the economic advantage of co-processing configurations, regional sourcing diversification, and long-term fixed-price or indexed contracts becomes more pronounced.
Regulatory alignment is amplifying that sensitivity. The EU ReFuelEU Aviation mandate’s progressive ramp from 2 percent to 6 percent by 2030 establishes a multi-year demand floor that favors feedstocks capable of meeting compliance requirements at scale. UCO-based HEFA has emerged as the dominant compliant pathway in the early years, which means that near-term policy implementation is disproportionately channeling demand toward the very feedstock category this research analyzes. In parallel, the UK mandate’s early attainment figures, entirely from UCO feedstock, underscore how quickly a market can become concentrated around a single supply base when compliance timelines are immediate and alternatives are limited.
In the United States, the Section 45Z credit creates a different kind of strategic filter. Because eligibility is restricted to North American feedstocks, the incentive architecture favors domestic and regionally sourced supply chains over imported alternatives, reinforcing the importance of collection networks, preprocessing capacity, and feedstock traceability within the eligible geography. This is one of the reasons the report pays close attention to how trade flow changes, such as the 2025 decline in U.S. UCO imports from China and the corresponding pivot toward Australia, South Korea, and Malaysia, can alter both cost structures and compliance positioning.
From Intelligence to Action
The broader takeaway for 2026 planning is that UCO for sustainable aviation fuel is evolving from an opportunistic sustainability narrative into a tightly contested supply-chain business. The revenue outlook suggests a market moving toward the $10.45 billion range by 2032, but the strategic prize will not go to organizations that simply recognize the growth trend. It will go to those who can map their feedstock access, conversion strategy, and regulatory exposure onto a coherent plan before mandates, incentives, and competitor contracts reshape the landscape.
This research is designed to support that planning with granular segmentation, competitive profiling, and market-dynamic analysis that can be translated directly into sourcing strategy, capacity evaluation, and risk management. The full study provides the detailed regional and segment breakouts, company-level analysis, and scenario-ready context that executives need to move from awareness to execution. For teams responsible for SAF procurement, renewable fuel investment, or feedstock portfolio strategy, the complete report offers the depth required to make 2026 decisions with confidence rather than conjecture.
For detailed analysis of this topic, please visit the official page: Used Cooking Oil for Sustainable Aviation Fuel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
BaBr2 Market Reaches $47.6M in 2025, Projects 4.3% CAGR to $63.91M by 2032: PW Consulting
By pmarketresearch, 2026-09-16
Strategic Intelligence in the BaBr2 Market: Navigating Growth and Volatility Through 2032
The global Barium Bromide (BaBr2) market stands at a critical inflection point, shaped by evolving industrial applications, raw material dynamics, and tightening regulatory frameworks. For executives, procurement leaders, and R&D directors operating in specialty chemicals, advanced materials, and imaging technologies, timely and granular market intelligence is no longer optional. PW Consulting's latest BaBr2 Market Research report delivers a comprehensive, data-driven foundation for strategic planning across the 2026-2032 horizon.
This analysis synthesizes historical performance, forward-looking projections, and structural market shifts to equip decision-makers with actionable clarity. Rather than presenting static figures, the report is engineered to support scenario modeling, supply chain optimization, and competitive positioning in a market characterized by moderate but consistent growth, regional imbalances, and concentration-driven pricing dynamics.
Market Trajectory and Macro Performance
The BaBr2 market has demonstrated resilient expansion over the past half-decade, reflecting steady demand from advanced materials, optical manufacturing, and specialized chemical synthesis. Based on our baseline assessments, global revenue reached approximately 47.6 million USD in the base year of 2025, building on a trajectory that traced 38.5 million USD in 2020, 41.5 million USD in 2021, 41.4 million USD in 2022, 43.8 million USD in 2023, and 46.6 million USD in 2024. The slight normalization observed in 2022 gave way to renewed momentum as downstream industrial activity accelerated and high-purity grades gained broader adoption.
Looking ahead, our forecast models project steady annual valuation gains, with the market expected to reach approximately 63.9 million USD by 2032. This translates to a compound annual growth rate (CAGR) of 4.3 percent over the forecast window. While the growth rate may appear measured, it conceals significant variation across applications and regional demand centers, as well as pockets of elevated premium pricing for high-purity or certified grades. Strategic planners should therefore interpret headline growth figures as a baseline rather than a substitute for segment-level and supply-side analysis.
Segmentation Architecture and Demand Drivers
The BaBr2 value chain is structured around two primary dimensions: chemical form and end-use application. Understanding how these segments interact is essential for identifying margin opportunities, forecasting capacity requirements, and aligning product roadmaps.
From a chemical form perspective, the market is divided between anhydrous barium bromide and barium bromide dihydrate. The anhydrous variant commands the larger share, driven by its stability profile and suitability for high-purity industrial and laboratory applications. The dihydrate form, while smaller in aggregate value, maintains steady relevance in specific downstream processes where hydrated chemistry is preferred or where supply chain logistics favor its handling characteristics. Our report dissects the pricing differentials, purity thresholds, and application suitability between these two forms, providing buyers and suppliers with a clear framework for product positioning.
On the application side, demand is anchored by several high-value use cases. Scintillator crystal production represents a major consumption node, leveraging barium bromide's optical and radiation-detection properties in specialized imaging and scientific instrumentation. Chemical synthesis and reagents constitute another substantial demand pillar, with BaBr2 serving as a precursor or intermediate in fine chemical pathways. Optical glass manufacturing absorbs a meaningful portion of supply, particularly where refractive index control and thermal stability are critical. A smaller but niche segment relates to specialty imaging and photography, where refined chemical grades support historically persistent demand in precision media applications.
Importantly, the relative weight of each application and region is not static. Regulatory shifts, feedstock pricing, and technological substitution can quickly reshape demand allocations. The report provides forward-looking segmentation scenarios that map how these drivers may redistribute market value across the forecast period, without relying on oversimplified proportional assumptions.
Supply-Side Dynamics and Raw Material Exposure
Barium bromide is predominantly produced by reacting barium carbonate or barium sulfide with hydrobromic acid. This fundamental synthesis route means that BaBr2 pricing and availability are tightly coupled to the cost structure of barium feedstocks and acid inputs. Recent industry data underscore this sensitivity: in the second quarter of 2025, barium carbonate prices in Italy climbed to approximately 678 USD per metric ton, propelled by rising barite and sodium carbonate costs alongside elevated energy and freight expenditures. Moving into the third quarter of 2025, UK barium carbonate pricing reached roughly 687 USD per metric ton, supported by stable demand from glass, ceramics, and chemical processing but pressured by higher energy tariffs and freight costs.
These feedstock trends are not isolated regional anecdotes. They reflect a broader pattern in which energy intensity, logistics congestion, and upstream mineral availability converge to influence downstream specialty chemical economics. Our BaBr2 Market Research report integrates these supply-side variables into a cohesive pricing and margin framework, helping procurement and finance teams anticipate cost volatility, negotiate contracts with informed benchmarks, and evaluate supplier diversification strategies.
Regulatory Landscape and Compliance Risk
Market participants must also navigate a shifting regulatory environment. Barium bromide is classified under transport regulations as UN1564, Barium compound, n.o.s., Hazard Class 6.1, Packing Group III, with corresponding documentation, labeling, and handling requirements that affect warehousing, shipping, and cross-border trade. In parallel, the substance is listed under EU REACH restrictions and appears in marine environmental policy frameworks as a hazardous substance, as reflected in ECHA listings. These designations influence import/export feasibility, customer qualification timelines, and the cost of compliance documentation.
For multinational operators, regulatory exposure is not uniform across geographies. The report maps jurisdictional nuances, identifies coverage gaps, and provides guidance on aligning sourcing and distribution strategies with evolving compliance expectations. This dimension is particularly valuable for organizations expanding into Europe or managing supply chains that traverse multiple regulatory regimes.
Competitive Landscape and Strategic Positioning
The BaBr2 market exhibits meaningful concentration, but also a diverse set of participants spanning commodity-scale producers, specialty-grade suppliers, and laboratory-focused distributors. Our analysis indicates that the top three firms command a combined share of approximately 42.5 percent, while the top five collectively represent around 58.8 percent of market value. This concentration pattern suggests that scale, distribution reach, and certification capabilities confer competitive advantage, but also leaves room for differentiated niche players who serve high-purity, high-compliance, or region-specific demand.
Among the entities profiled in the report, several stand out for their positioning and operational profile:
- AB Enterprises , headquartered in Mumbai, supplies and exports high-purity Barium Bromide across a broad application set spanning pharmaceuticals, textiles, plastics, dyes, food coloring, paints, and chemical refineries, with an emphasis on meeting international standards through superior purity chemicals.
- Vizag Chemical , based in Visakhapatnam, operates as a manufacturer, supplier, and distributor of industrial-grade Barium Bromide at 99 percent purity or higher, supported by ISO 9001:2015 certification, serving diverse industries within India and export markets.
- Axiom Chemicals Pvt Ltd , located in Vadodara, Gujarat, manufactures and exports both Barium Bromide Anhydrous and Dihydrate, aligned to CAS 10553-31-8 and 7791-28-8, targeting industrial chemical applications.
- Powder Pack Chem , also operating from Mumbai, offers Barium Bromide in powder form with 98 percent purity at LR grade, catering to laboratory and industrial use cases that prioritize accessible specifications.
- Sincere Chemical , a China-based producer, integrates R&D, production, and sales for Barium Bromide (CAS 10553-31-8), offering factory pricing and sample availability to support downstream evaluation and scaling.
- Stanford Advanced Materials (SAM) , in the United States, supplies high-quality BaBr2 at 99 percent purity in white bead form, positioned for advanced materials and chemical synthesis applications where form factor and purity consistency matter.
- Sigma-Aldrich (Merck KGaA) , with presence across the United States and Germany, provides anhydrous Barium Bromide beads in -10 mesh at 99.999 percent trace metals basis, targeting laboratory, research, and high-purity applications that require stringent material certification.
While recent public developments among these companies are not extensively highlighted in the current reporting cycle, the structural signals are clear: pricing power tends to accrue to suppliers with certified high-purity grades, reliable logistics, and credible compliance credentials. Conversely, buyers benefit from supplier diversification, total-cost-of-ownership modeling, and early alignment on purity and packaging requirements. The report's competitive intelligence section goes beyond company descriptions to evaluate relative positioning, supply reliability indicators, and the strategic implications of concentration for negotiation leverage and risk distribution.
Operational Content and Decision Support
Beyond macro trends and company profiles, the BaBr2 Market Research report is structured as a practical decision-support toolkit. It delivers actionable content across multiple analytical dimensions, enabling users to translate market intelligence into operational plans.
Key components include:
BaBr2 Market
- Supply-demand balance analysis that disaggregates production, consumption, and inventory dynamics to identify periods of tightness or slack, as well as the structural factors likely to drive future imbalances.
- Price trajectory modeling that correlates feedstock movements, energy inputs, freight costs, and demand elasticity to produce forward-looking price scenarios rather than single-point estimates.
- Regulatory and compliance mapping that clarifies classification, transport, and environmental restrictions relevant to sourcing, storage, and international shipment.
- Purity and grade benchmarking that compares specifications across suppliers and application types, helping technical and procurement teams match material requirements with cost-effective sourcing options.
- Competitive benchmarking that positions major players by scale, certification, geographic reach, and product form, supporting supplier selection and market entry evaluations.
- Scenario planning modules that test how shifts in regional demand, raw material availability, and regulatory actions could alter market outcomes across the 2026-2032 horizon.
This operational depth is designed for cross-functional use. R&D teams can align material specifications with realistic availability and pricing. Procurement can structure contracts around informed cost benchmarks and supplier risk profiles. Strategy and finance can incorporate segment and scenario insights into investment appraisals, capacity planning, and market entry assessments.
Why This Report Matters for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the BaBr2 market face a convergence of incremental growth, feedstock volatility, and regulatory complexity. The headline CAGR of 4.3 percent provides a useful directional signal, but the strategic opportunities and risks are distributed unevenly across forms, applications, and geographies. Companies that rely solely on broad market averages risk misjudging regional demand intensity, underestimating compliance costs, or overpaying for specifications that exceed actual application requirements.
PW Consulting's BaBr2 Market Research addresses these blind spots by combining verified historical data, forward-looking modeling, and grounded supply-side analysis. The report does not simply recount what has happened; it provides the analytical scaffolding required to evaluate what should happen next. For buyers, that means better contract timing, more accurate budget planning, and stronger supplier negotiation positions. For suppliers, it means clearer product roadmaps, targeted certification investments, and more precise capacity allocation. For investors and strategic planners, it means a defensible basis for scenario analysis and risk assessment.
Accessing Full Intelligence
The insights summarized here reflect the report's analytical framework and directional findings, but the full intelligence payload extends well beyond this overview. Detailed segmentation analyses, granular demand and pricing scenarios, supplier benchmarking matrices, and regulatory coverage maps are structured to support immediate operational use. Because market conditions and input costs can shift rapidly, decision-makers benefit from accessing the complete dataset and scenario tools directly.
To obtain the full BaBr2 Market Research report and integrate its comprehensive data, models, and strategic guidance into your 2026 planning cycle, visit the source page for complete access and detailed methodology.
Lithium Bromide Market
For detailed analysis of this topic, please visit the official page: BaBr2 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PVP for Lithium Ion Battery Market Hits $342.15M in 2025, Forecasts 11.24% CAGR to $721.18M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Energy Transition: The Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market 2026-2032
The global transition toward electrified mobility and stationary energy storage has fundamentally altered the demand dynamics for specialty chemicals used in battery manufacturing. Among these materials, Polyvinylpyrrolidone (PVP) has emerged as a critical enabler for performance optimization in lithium-ion battery production. As manufacturers scale capacity to meet the projected demand through the end of the decade, understanding the nuanced market structure of battery-grade PVP is no longer optional—it is a strategic imperative. PW Consulting is pleased to introduce our latest comprehensive market study, designed to equip industry stakeholders with the actionable intelligence required to navigate the complexities of the 2026-2032 forecast period.
This analysis serves as a prelude to our full report, offering a high-level perspective on market direction while underscoring the depth of granular data available to clients who require precision for supply chain planning, R&D allocation, and competitive positioning.
Macro Market Trajectory and Revenue Outlook
The financial trajectory of the PVP market for lithium-ion batteries indicates robust expansion, driven by the dual engines of electric vehicle (EV) adoption and energy storage system (ESS) deployment. Analysis of historical performance from 2020 through the base year of 2025 reveals a consistent upward trend in revenue generation, reflecting the materialization of demand forecasts that were previously considered ambitious.
Binders for Lithium Ion Batteries Market
In 2020, the global market revenue stood at approximately 164.2 million USD. By 2025, this figure had climbed to 342.15 million USD, demonstrating a compound growth pattern that outpaces many traditional industrial chemical segments. The report projects that this momentum will accelerate into the forecast period. Revenue is expected to reach 376.25 million USD in 2026 and continue its ascent to 721.18 million USD by 2032. This growth path implies a significant increase in consumption volume as battery factories operationalize gigafactory-scale production lines worldwide.
Our modeling indicates a robust compound annual growth rate (CAGR) of 11.24 percent throughout the forecast horizon. This rate suggests that PVP will maintain its criticality in battery chemistries, resisting substitution by alternative binders or dispersants in the near term. For strategists, this CAGR is not merely a percentage; it represents the velocity at which market share can be captured or lost depending on supply chain resilience and product specification alignment.
Segmentation Dynamics: Type, Application, and Regional Distribution
While the aggregate numbers signal growth, the strategic value of this report lies in its dissection of the market into actionable segments. The study provides a detailed breakdown of the market by product type, application, and region, revealing where value is being created and where supply bottlenecks may emerge.
Product Type Dynamics
The market is bifurcated into Powder PVP and Solution PVP. Powder PVP continues to command a significant share of the market revenue, driven by its logistical advantages in bulk transport to battery manufacturing hubs and its versatility in dry mixing processes. However, Solution PVP is carving out a distinct niche, particularly in facilities where immediate slurry preparation is prioritized over long-term storage stability. Our analysis details the revenue contribution and volume trends of each type, highlighting the specific technical requirements that drive purchasing decisions in automated mixing lines versus manual formulation setups. Clients will gain insight into which form factor aligns best with their processing logistics and cost structures.
Application Criticality
In terms of application, the report segments demand across Carbon Nanotube Dispersant, Electrode Binder Additive, and Ceramic Coating for Separators. Historically, the use of PVP as a dispersant for conductive additives, such as carbon nanotubes and carbon black, has been a primary driver of volume. The ability of PVP to stabilize these conductive networks in the electrode slurry directly impacts the electrical performance and cycle life of the final cell.
Concurrently, the role of PVP in ceramic coating for separators is gaining traction. As battery safety requirements tighten with higher energy densities, the use of PVP-based binders in separator coatings offers adhesion and thermal stability benefits. The Electrode Binder Additive segment also remains substantial, particularly for specific anode and cathode chemistries where adhesion to the current collector is paramount. The full report quantifies the revenue splits across these applications, revealing which function is acting as the primary volume driver in different production environments and how the mix is expected to shift as battery architectures evolve.
Regional Landscape
Geographically, the Asia Pacific region stands as the dominant consumer and producer of battery-grade PVP, reflecting the concentration of global battery cell manufacturing capacity. The market data reflects substantial revenue generation within this region, supported by the presence of major battery manufacturers and downstream EV assembly plants. Europe and North America represent mature but growing markets, driven by local content requirements and the establishment of new gigafactories in Western economies. The Rest of World segment, while smaller in absolute terms, shows potential for incremental growth as battery adoption expands in emerging markets.
The full report provides detailed regional revenue figures and forecasts, allowing companies to assess market attractiveness by territory. It examines the interplay between local production capabilities and import reliance, identifying where tariff structures or logistics costs may influence the final landed cost of PVP materials.
Competitive Landscape and Industry Dynamics
The market structure for battery-grade PVP is characterized by a mix of global specialty chemical giants and agile regional manufacturers. Our analysis of the competitive landscape reveals a moderately concentrated market, with the top three companies holding a combined market share of approximately 64.25 percent, while the top five firms account for roughly 79.1 percent of total revenue. This concentration suggests that while incumbents hold significant sway, there is room for specialized players to capture niche segments through performance differentiation.
Key Market Participants
Ashland Inc. (Wilmington, Delaware, USA) remains a prominent supplier of PVP K-Series polymers used as binders and additives. Their portfolio includes specialty binders like Soteras CCS-V for separators, emphasizing performance polymers for enhanced coating and electrochemical properties. Ashland's focus on high-performance solutions positions them as a preferred supplier for premium-tier battery applications where performance margins are narrow.
BASF SE (Ludwigshafen, Germany) provides PVP for lithium-ion battery applications primarily as dispersants and processing aids in electrode formulations. Their extensive portfolio of additives for cathode, anode, and separator coatings allows them to offer integrated solutions for slurry stability. BASF leverages its global scale to maintain consistent supply chains across major production regions.
In China, the competitive field is diverse and includes several specialized producers. Boai NKY Pharmaceuticals Ltd (NKY Medical) in Jiaozuo, Henan, is a major producer offering battery-grade PVP K30 powder specifically developed for lithium battery applications, supplying high-purity grades for dispersant use. NIPPON SHOKUBAI Co., Ltd. (Osaka, Japan) manufactures PVP used as dispersants for metal oxides and carbon materials, supporting electrode slurry formulation and performance enhancement.
Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Synvent Materials Corporation (Ningxia, China) offers Syno® PVP Battery Grade (e.g., K30 Battery with K-value 27-32.4, >98% solids, <100 ppm NVP) manufactured under cGMP standards. This focus on high purity and certification makes them relevant for applications where impurity control is critical. Henan Pengfei New Materials Co., Ltd. produces PVP series for lithium battery cathode slurries and nano materials, emphasizing dispersant roles. Their recent technical updates in 2025 have highlighted performance data on PVP as nonionic dispersants, showcasing improved stability and processing efficiency. Huzhou Sunflower Specialty Polymer Co., Ltd. in Zhejiang is another leading manufacturer of PVP K-series, supplying PVP as dispersant for lithium battery cathode materials.
While these companies represent the core competitive set, the full report profiles additional entities and analyzes their specific revenue contributions, capacity expansions, and strategic partnerships. It dissects the moves made by these players, such as technical application updates and product launches, to reveal the direction of innovation in the sector.
Critical Market Drivers and Headwinds
Understanding the market trajectory requires a clear view of the forces shaping supply and demand. The report integrates several dynamic factors that influence pricing, availability, and margin structures.
Raw Material Constraints and Costs
The upstream feedstock for PVP, N-vinylpyrrolidone (NVP), relies on commodities such as calcium carbide and acetylene. The cost of these raw materials forms a significant portion of the total production cost for battery-grade PVP. Demand for PVP in lithium batteries and photovoltaic silver paste has risen sharply in recent years, contributing to price premiums for high-purity grades. There is an industry expectation that demand will continue to escalate, putting upward pressure on feedstock availability. Furthermore, environmental restrictions on chemical industrial parks in China have occasionally led to imbalances in NVP supply, impacting the availability of high-purity battery-grade PVP. These supply-side frictions can lead to volatility in pricing and require proactive supply chain management.
Price Volatility and Cost Structures
Historical price data indicates that PVP prices have fluctuated within a notable range over recent periods, influenced by raw material costs and demand from the new energy sector. For procurement teams, this volatility underscores the need for long-term contracts, hedging strategies, or vertical integration considerations. The report examines price trends and correlates them with capacity utilization rates and feedstock index movements to help clients anticipate cost cycles.
Usage Intensity and Specification Trends
The intensity of PVP usage per unit of battery capacity is a key metric for forecasting demand. Industry benchmarks suggest specific usage rates for PVP in lithium battery applications, primarily involving industrial-grade PVP K30 and K90 as dispersants for cathode materials. As cathode chemistries evolve toward higher nickel contents or silicon blends, the specification requirements for binders and dispersants may shift, potentially altering the consumption rate or driving demand for higher purity grades. Our study analyzes these technical trends to project how usage intensity might evolve over the forecast period.
Report Architecture and Analytical Depth
The "Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market" report is structured to guide decision-makers from macro trends to micro-level execution details. Beyond the market sizing and segmentation discussed above, the full document includes:
- Historical Reconstruction (2020-2025): A detailed year-by-year breakdown of market performance, allowing for validation of internal models against external data and identification of anomaly periods caused by supply disruptions or demand shocks.
- Forecast Methodology (2026-2032): Transparent modeling assumptions regarding capacity additions, technology adoption curves, and regional growth drivers. The forecast accounts for known pipeline projects and policy interventions that may alter market equilibrium.
- Competitive Benchmarking: In-depth profiles of key companies, including their product portfolios, production capacities, geographic footprint, and recent strategic developments. The report assesses the relative positioning of each player in terms of price, quality, and service.
- Segment Revenue and Volume Analysis: Granular data splits for region, type, and application. These splits are essential for companies to identify high-growth pockets and allocate resources accordingly.
- Supply Chain and Raw Material Analysis: An examination of the NVP supply chain, cost structures, and the impact of environmental regulations. This section helps stakeholders assess risk exposure in their upstream dependencies.
- Strategic Recommendations: Actionable insights for suppliers, buyers, and investors. This includes guidance on market entry strategies, partnership opportunities, and risk mitigation tactics.
Our research team has synthesized data from public filings, industry surveys, technical literature, and primary interviews to construct a cohesive narrative. The result is a document that not only tells you what the market is doing but explains why it is doing it and what it means for your specific business context.
The 2026 Strategic Imperative
As the industry enters 2026, the window for aligning strategy with market realities is narrowing. The projected growth to 2032 indicates a market that will be significantly larger and potentially more complex than it is today. Companies that rely on aggregate data alone may miss the nuances of regional shifts, application-specific demand surges, or competitive moves by niche players.
For suppliers, the opportunity lies in capturing share in high-growth segments by differentiating on purity, consistency, or technical support. For battery manufacturers, the focus must be on securing reliable supply of grade-specific materials while managing cost volatility through strategic sourcing. For investors, understanding the concentration dynamics and the emergence of new capacity is vital for evaluating the risk-return profile of assets in this value chain.
The full report provides the data backbone required to make these decisions with confidence. It quantifies the revenue opportunities in each segment, maps the competitive threats, and highlights the supply chain vulnerabilities that could disrupt operations. By accessing this intelligence, organizations can move beyond reactive planning to proactive strategy execution.
Conclusion
The Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market is at a pivotal juncture. The convergence of electrification mandates, battery chemistry innovation, and raw material dynamics creates a landscape rich with opportunity but fraught with complexity. PW Consulting's comprehensive study offers the clarity needed to navigate this environment.
While this overview highlights the macro trajectory and structural dynamics, the precise segmentation data, detailed competitive rankings, and scenario-based forecasting remain within the full report. We invite industry leaders, procurement directors, and strategy teams to access the complete intelligence package to ensure their 2026 planning is built on a foundation of rigorous, up-to-date analysis.
Request the Full Report and Detailed Segmentation Data
For detailed analysis of this topic, please visit the official page: Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Difurfuryldisulfide Market Hits $24.8M in 2025, Driven by F&B Flavoring and Asia Pacific
By pmarketresearch, 2026-09-16
Navigating the Difurfuryldisulfide Market: Strategic Intelligence for 2026 and Beyond
The specialty chemicals sector continues to reward organizations that pair operational precision with forward-looking market intelligence. As industrial formulators, flavor houses, and supply chain leaders finalize their 2026 procurement and capacity strategies, the difurfuryldisulfide market presents a compelling case for disciplined evaluation. In this landscape, our latest research deliverable arrives not as a static snapshot, but as a decision-enabling framework designed to align procurement, R&D, and competitive positioning with the realistic trajectory of a maturing, value-driven niche.
Built on a rigorous five-year historical baseline spanning 2020 through 2025 and extending through a seven-year forecast window to 2032, this analysis translates longitudinal demand signals, pricing behaviors, and structural shifts into actionable intelligence. The narrative that follows is deliberately curated: it demonstrates the depth of our methodology and the relevance of our findings while preserving the granular segmentation required for precise planning. For executives who require exact regional breakdowns, purity-tier valuations, and application-level market shares, the full report remains the definitive source.
A Measured Expansion Trajectory Anchored in Value-Tier Demand
The difurfuryldisulfide market has followed a disciplined growth curve, expanding from a baseline of USD 20.12 million in 2020 to a projected USD 26.26 million in 2026. This progression is not the result of volatile speculation but rather reflects steady consolidation across flavor, fragrance, and industrial applications where sulfur-linked furan derivatives serve distinct functional roles. Over the forecast horizon through 2032, the market is expected to reach USD 33.52 million, translating to a compound annual growth rate of 4.4 percent.
For strategic planners, that trajectory carries two immediate implications. First, growth is structural rather than cyclical, suggesting that demand is anchored in recurring formulation requirements rather than one-off sourcing events. Second, the pace of expansion is moderate enough to reward careful supplier evaluation and contract structuring, yet fast enough to penalize organizations that treat this category as a commoditized afterthought. Companies that treat difurfuryldisulfide as a strategic input, rather than a back-pocket ingredient, will be better positioned to manage continuity, specification compliance, and total cost of ownership.
The research also situates this trajectory within a broader feedstock and regulatory context. Furfural, the primary upstream material for furfuryl derivatives, is derived substantially from agricultural residues such as corn cobs, and its downstream pathways influence both availability and cost stability for difurfuryl disulfide producers. In parallel, evolving environmental frameworks, including European emission restrictions on formaldehyde that favor furfuryl alcohol-based resins over phenolic alternatives, are reshaping demand patterns in adjacent furan-chemistry applications. These dynamics do not merely color the headline numbers; they define the operating environment in which suppliers and buyers must make long-term commitments.
Competitive Architecture and the New Relevance of Compliance
The competitive landscape for difurfuryldisulfide is concentrated but diversified by function, geography, and certification posture. With the top three players holding approximately 42.5 percent of the market and the top five extending that share to 58.8 percent, the industry exhibits enough fragmentation to preserve sourcing flexibility while maintaining enough concentration to reward supplier relationship management. Organizations that understand who controls which grade, which certifications, and which distribution channels will move faster when specifications tighten or lead times compress.
Several established participants illustrate how the market is bifurcating between natural-identity positioning, synthetic-grade utility, and research-grade precision. In North America, Advanced Biotech Inc. continues to supply difurfuryl disulfide natural and synthetic grades for food, beverage, and aroma applications, with kosher and other certifications maintained through 2026. Its recent renewal of kosher certification for DIFURFURYL DISULFIDE 10% ETOH NATURAL, valid through November 2026, underscores how compliance continuity has become a differentiator in food and beverage supply chains. Axxence Aromatic GmbH, operating from Germany, provides a natural-grade offering recognized under EU natural and FEMA 3146 standards, and its December 2025 halal certification renewal reflects a broader trend: identity-preserved and certification-backed materials are increasingly tying up market share in sensitive applications.
Beyond these Western and European players, the competitive field extends across East Asia and specialized distribution networks. TCI America, through Tokyo Chemical Industry Co., Ltd., manufactures and distributes difurfuryl disulfide at 95.0+ percent purity for research, synthesis, and industrial use, often routed through established laboratory distributors. Spectrum Chemical Mfg. Corp. and Scimplify serve parallel but distinct roles in the U.S. market by offering laboratory-scale and bulk industrial supply, respectively, with regulatory documentation and COA/SDS support. Alfa Chemistry positions itself as an ISO 9001:2015 certified supplier of furan derivatives with 98+ percent purity options, while Aurochemicals addresses the natural flavor enhancement segment with diluted formats such as 1 percent in ethanol or propylene glycol. On the manufacturing side, Nanjing MSN Chemical Co., Ltd. and Beijing Lys Chemicals Co., Ltd. emphasize global distribution of fine chemicals and gram-to-ton scale production, respectively, while Tengzhou Runlong Fragrance Co., Ltd., operating since 2004, focuses on meat flavor agent applications with FEMA 3146 and CAS 4437-20-1 specifications.
This roster is not merely a directory; it is a map of capability, risk, and negotiation leverage. Some participants compete primarily on purity thresholds and documentation readiness, others on natural identity and certification portability, and still others on scale, logistics, and price architecture. The report’s competitive assessment section explains how these postures interact with buyer requirements across food and beverage, fragrance and cosmetics, and animal feed applications, helping procurement teams match specification needs with supplier strengths rather than defaulting to price alone.
Natural Sulforaphane Market
From Headline Numbers to Operating Decisions
A realistic market study must do more than describe demand; it must help teams convert context into commercial decisions. Our research is structured to support that translation through practical, cross-functional modules that move beyond the aggregate market size and CAGR. The report examines how upstream cost differentials and feedstock geography influence derivative pricing, how regulatory shifts alter preferred resin and polymer pathways and, by extension, downstream furan demand, and how certification renewals and safety data sheet updates affect sourcing continuity.
Readers will find detailed attention to the interplay between purity requirements and application suitability, a critical dimension in a category where 98+ percent purity often commands a premium but where certain formulations may be optimized at lower thresholds. The analysis also explores how regional manufacturing costs and logistics friction shape supply options, noting for example that furfural production economics can differ materially between China and North America due to labor and logistics variables, and that furfuryl alcohol pricing has moved within defined bands over recent years depending on purity and grade. These factors do not operate in isolation; they help explain why some buyers prioritize certified natural identity while others emphasize bulk pricing and documentation speed.
Equally important, the report assesses supply continuity risk through the lens of certification lifecycles, regulatory documentation, and distributor networks. With recent events ranging from Advanced Biotech’s SDS update in mid-2025 to Axxence’s halal certification in late 2025 and Advanced Biotech’s kosher renewal in early 2026, the evidence points to a market where compliance is not a static checkbox but an ongoing operational commitment. Organizations that track these milestones and incorporate them into supplier scorecards will face fewer surprises during qualification cycles and audits.
Difurfuryldisulfide Market
Where the Report Goes Further: Executive Intelligence Designed for Action
To support execution across procurement, R&D, and strategy, the full report delivers operational content that extends well beyond the macro summary. Decision-makers can expect:
- A structured view of market size evolution from the 2020 base through the 2026 forecast and the full projection period to 2032, framed in U.S. dollars and millions of dollars, with analysis of inflection points rather than isolated figures.
- A competitive mapping that aligns each key company’s product grades, purity ranges, certification posture, and distribution channels with the applications and geographies where they matter most.
- An examination of how upstream feedstock dynamics, including furfural availability and furfuryl alcohol pricing trends, influence derivative supply chains and downstream cost structures.
- A regulatory and compliance narrative that connects emission directives, certification renewals, and documentation practices to sourcing decisions and audit readiness.
- Practical guidance on evaluating natural versus synthetic identity, purity thresholds, and dilution formats across food, beverage, fragrance, cosmetics, and animal feed applications.
This structure is intentional. Rather than overwhelming readers with static tables, the report connects each insight to a decision point: which supplier to qualify, which purity tier to target, how to structure multi-period contracts, and where to place R&D emphasis as feedstock economics and regulatory frameworks evolve.
Why 2026 Decisions Depend on Precision, Not Just Direction
The difurfuryldisulfide market in 2026 is best understood as a category where the cost of ambiguity is rising. Moderate but steady growth, a moderately concentrated supplier base, and certification-sensitive end uses all point to the same conclusion: organizations that operate on generic assumptions will pay for it in qualification delays, specification mismatches, or avoidable premium pricing. By contrast, teams that integrate feedstock context, competitive capability, and compliance continuity into a single planning framework can protect continuity while improving unit economics.
That is precisely where the full research earns its place in the decision cycle. The executive overview presented here has outlined the strategic contours and demonstrated the analytical rigor behind the study. What it cannot do, by design, is replace the detailed regional, purity, and application segmentation that purchasing directors and formulation leads need before committing capital. Those specifics, including precise market values and split-level intelligence, are preserved in the complete report so that each organization can align the data with its own specification thresholds, volume profiles, and compliance requirements.
Accessing the Full Intelligence
A market of this shape rewards early clarity. The full Difurfuryldisulfide Market research report provides the granular segmentation, company-by-company capability mapping, regulatory timeline, and forecast detail required to convert strategy into procurement and product decisions with confidence. For leaders planning 2026 sourcing, R&D prioritization, and supplier qualification, the complete study is the optimal reference point. Detailed segmentation data, company profiles, and forecast tables are available through our research portal, where the full dataset can be aligned to your internal volume assumptions and compliance standards.
For detailed analysis of this topic, please visit the official page: Difurfuryldisulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Strength Steel Market Hits $130M in 2025, Forecast 7.8% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the High Strength Steel Market: A 2026 Executive Briefing
The global high strength steel market stands at a critical inflection point as industrial demand converges with stringent regulatory frameworks and accelerated technological innovation. For corporate strategists, procurement leaders, and capital allocators, navigating this landscape requires more than top-line projections. It demands granular, actionable intelligence that maps macroeconomic momentum to on-the-ground competitive shifts. PW Consulting’s latest High Strength Steel Market research delivers precisely that intelligence, offering a decision-ready architecture designed to de-risk strategic planning and unlock structural advantages across the 2026 to 2032 horizon.
A Market Defined by Resilient Growth and Structural Rebalancing
Tracing the market’s trajectory from 2020 through 2025 establishes a clear baseline of steady expansion, with revenue compounding at a pace that outpaces broader industrial metal benchmarks. The transition from historical performance into the forecast window reveals an acceleration pattern that demands immediate strategic attention. By 2026, the market has crossed a significant revenue threshold, and the forward projection indicates sustained upward momentum through the end of the decade. The implied compound annual growth rate across the full forecast period underscores a structurally healthy demand environment rather than a cyclical spike. This trajectory is not uniform across all vectors, which is exactly why executives must look beyond aggregate figures. The reallocation of investment, shifting end-user priorities, and evolving material specifications are reshaping where value accrues and which product architectures capture premium positioning.
Leadership teams operating in capital-intensive sectors cannot afford to treat high strength steel as a commoditized input. The market’s expansion is increasingly tied to performance-critical applications, weight-reduction mandates, and infrastructure modernization cycles. Understanding how these drivers fragment across product architectures and end-use ecosystems is the difference between capturing margin expansion and being squeezed by price volatility. Our research isolates these dynamics without diluting them into vague trend summaries, providing a clear line of sight from macro momentum to segment-level execution pathways.
Decoding the Competitive Architecture
The industry’s leadership cohort reflects a deliberate concentration of technological capability, geographic footprint, and application-specific expertise. A handful of entrenched players command the majority of realized market value, yet the competitive field remains highly active as incumbents recalibrate portfolios and challengers target niche performance tiers. The market structure exhibits moderate oligopolistic characteristics, meaning that while scale players set pricing anchors and technology benchmarks, there remains meaningful room for differentiated positioning through grade specialization, regional supply chain optimization, and application engineering.
High Strength Steel Market
Several globally recognized producers anchor the landscape, each pursuing distinct strategic vectors. A Swedish leader has cemented its reputation through premium structural and automotive grades engineered for extreme load conditions and lightweighting targets. A Luxembourg-headquartered multinational continues to scale its high-yield and advanced-grade offerings, particularly where construction durability and automotive crash performance intersect. A South Korean manufacturer has extended its global sales architecture around premium structural steels and automotive high-strength lines, leveraging integrated production advantages to compete in export-driven markets. A Japanese enterprise maintains a strong presence in ultra-high-tensile and offshore-grade plates, serving infrastructure and heavy industrial buyers who prioritize certification depth and metallurgical consistency. In North America, the largest domestic supplier of advanced high-strength steels is pushing third-generation grades that directly address vehicle lightweighting requirements, while a major U.S. integrated producer has introduced proprietary advanced grades designed for electric vehicle platforms and transformer applications. European and Indian counterparts round out the competitive matrix, with one German firm supplying high-strength flat-rolled products for automotive and industrial use, an Austrian manufacturer emphasizing premium grades for machinery and automotive segments, and an Indian producer focusing on corrosion-resistant high-tensile offerings for offshore and maritime environments.
This is not a static hierarchy. Recent corporate movements demonstrate how quickly product launches, capacity decisions, and industry consortium studies can reshape sourcing preferences. A major European producer recently introduced a new line of ultra-high-strength steels engineered specifically for electric vehicle chassis, positioning the release around lightweighting efficiency and updated safety compliance thresholds. A leading U.S. integrated manufacturer simultaneously expanded its portfolio to include proprietary advanced high-strength formulations and ultra-thin lightweight grades tailored for EV and transformer applications. Meanwhile, a North American capacity expansion initiative committed substantial capital toward increasing quenched-and-tempered steel output, extending the availability of flagship high-strength brands for demanding industrial and transportation users. Complementing these corporate moves, an industry-wide research body published a new parts consolidation study that quantifies how advanced high-strength steels can simplify vehicle architecture while maintaining structural integrity. These developments are not isolated headlines; they signal where R&D capital is flowing, where downstream buyers are being encouraged to re-evaluate material selections, and which performance benchmarks are becoming table stakes rather than differentiators.
Forces Reshaping Market Dynamics
Executive decision-making in this sector is being compressed by a convergence of policy shifts, input cost volatility, and standardization updates that directly alter procurement economics and specification strategies. Trade policy remains one of the most immediate variables. The reinstatement and subsequent escalation of import tariffs in the United States through mid-2025 fundamentally altered the cost baseline for imported high strength steel, forcing regional buyers to reconsider sourcing geography, inventory positioning, and contract structuring. Across the Atlantic, parallel moves by the European Union to reduce duty-free quotas and impose steep duties beyond those thresholds have recalibrated the cost landscape for European manufacturers and their supply chain partners. These policy adjustments do not merely affect landed cost; they influence capacity utilization patterns, redirect trade flows, and elevate the strategic importance of regional supply security.
Input cost dynamics add another layer of complexity. Recent price adjustments by major domestic producers in response to rising prime scrap costs illustrate how raw material inflation transmits rapidly into finished high-strength-grade economics. When base material costs move sharply, the margin sensitivity of advanced grades becomes a board-level concern, particularly for automotive and construction programs that operate on tightly negotiated multi-year agreements. Simultaneously, updated welding electrode classification standards have introduced new specification considerations for fabrication and construction workflows, requiring engineering teams to align procurement choices with revised compatibility and certification requirements. These are not peripheral compliance items; they are operational variables that influence total cost of ownership, lead-time reliability, and vendor qualification timelines.
What ties these forces together is their compounding effect. Tariff exposure changes sourcing logic, raw material inflation compresses margin tolerance, and specification updates alter fabrication readiness. Companies that treat these as independent risks often overcorrect in one area while under-hedging another. Our research integrates these variables into a unified operational framework, enabling leaders to model how policy, input costs, and technical standards interact across procurement cycles and capital planning horizons.
Inside the Research: Actionable Architecture for 2026 Decision-Making
This study is constructed for executives who need precision over generality. Rather than presenting a static market snapshot, the report maps the decision environment across product architecture, application demand, regional positioning, and competitive behavior, with explicit guidance on where and how to act. The analytical core is built around a multi-layered segmentation framework that dissects the market by type, application, and geography, while deliberately avoiding the trap of superficial share arithmetic. Each segmentation layer is evaluated for growth durability, price sensitivity, specification trajectory, and substitution risk so that sourcing and product-strategy teams can identify where to protect exposure and where to pursue premium positioning.
The competitive section goes beyond corporate profiling to assess strategic posture, capacity intent, and portfolio direction. Readers gain a structured view of how leading producers are aligning R&D investments with end-user requirements, which product families are being prioritized, and how recent launches and capacity decisions signal the next phase of market competition. This enables procurement and product-development teams to anticipate supplier positioning, evaluate alternative grade pathways, and construct negotiation strategies grounded in forward-looking supplier behavior rather than historical pricing alone.
Regulatory and cost-environment analysis is embedded throughout the report, not isolated in a compliance appendix. Trade-policy escalations, duty-quota adjustments, raw material price movements, and updated technical standards are mapped to their operational consequences, giving strategy and supply-chain leaders a practical reference for scenario planning. The forecast architecture extends across the full outlook window, providing a coherent growth narrative that supports capacity decisions, long-term contract structuring, and product-mix optimization. Crucially, the report maintains a tight focus on decision utility: it highlights where growth is structurally supported, where volatility is likely to intensify, and which strategic levers deliver the highest return on analytical investment.
To preserve the depth required for real-world application, certain granular breakdowns are reserved for the full intelligence package. The complete report provides the detailed regional and application-level decompositions, type-specific revenue architecture, concentration measurements, and company-by-company strategic assessments that turn high-level direction into executable planning inputs. This deliberate structure ensures that the executive summary establishes credibility and directional clarity while the full dataset delivers the specificity needed for budgeting, sourcing, and product-roadmap decisions.
Why This Intelligence Matters Now
Market leadership in high strength steel is increasingly defined by the speed and accuracy with which organizations integrate demand signals, policy reality, and supplier strategy into their capital and procurement plans. The growth trajectory through the end of the decade is robust, but the path to capturing it is uneven. Winners will be those who align material specifications with downstream performance mandates, manage exposure to trade and input-cost volatility, and position their product or sourcing strategies ahead of competitor portfolio shifts. Delaying that alignment until quarterly reviews or spot-market disruptions force action is a structural disadvantage.
PW Consulting’s High Strength Steel Market research provides the analytical foundation to move from reactive monitoring to proactive positioning. It equips leadership teams with a consolidated view of where value is concentrating, how competitive intentions are evolving, and which operational variables deserve immediate attention in 2026. The full report is designed to be read by strategists, commercial directors, procurement executives, and engineering leaders who need to translate market momentum into measurable advantage. Accessing the complete dataset will reveal the detailed segmentation architectures, competitive granularities, and scenario-ready breakdowns necessary to convert insight into execution.
High-strength Polyester Thread Market
For organizations preparing for the next phase of industrial demand, the question is no longer whether high strength steel will remain central to lightweighting, durability, and infrastructure performance, but how precisely to navigate the opportunities and risks embedded in its growth path. This research is built to answer that question with the clarity, rigor, and operational relevance that 2026 decision-making demands.
For detailed analysis of this topic, please visit the official page: High Strength Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hexagonal BN Market Hits $954.4M in 2025, Forecast CAGR 4.71% to 2032
By pmarketresearch, 2026-09-15
Hexagonal Boron Nitride Market 2026: Strategic Imperatives for Industrial Leadership
The hexagonal boron nitride market stands at the intersection of advanced materials, thermal management, and critical mineral policy. As enterprises navigate a decade of geopolitical recalibration, energy transition acceleration, and semiconductor supply chain restructuring, the ability to read material market signals with precision has shifted from procurement advantage to strategic necessity. Our latest research on the Hexagonal BN market delivers exactly that capability, translating multi-year historical performance, forward-looking macroeconomic trajectories, and competitive positioning into an operative decision framework for 2026.
This article serves as a strategic preview of the full research release. It outlines the analytical architecture, contextual forces shaping procurement and capacity decisions, and the competitive dynamics that executives must monitor. Core segmentation figures, regional revenue breakdowns, and detailed application-level allocation data remain reserved for the complete report, ensuring that subscribers receive unfiltered intelligence calibrated for capital allocation, product roadmapping, and vendor strategy.
Market Trajectory and the 2026 Decision Horizon
Historical trajectories and forward projections converge on a market characterized by steady expansion and evolving structural drivers. The Hexagonal BN market reached approximately $954.4 million in 2025, building on a consistent growth arc from $765.86 million in 2020. The base year reflects a market that has absorbed cyclical disruptions, raw material volatility, and regional reconfiguration while maintaining an unbroken upward path. Looking forward, the forecast window extends through 2032, with 2026 projected at nearly $968 million and the trajectory climbing toward roughly $1.34 billion by the close of the forecast period. These headline figures frame a compound annual growth rate of 4.71 percent across the forecast horizon.
For leadership teams planning 2026 initiatives, the message is not merely that growth persists, but that the growth is becoming more structurally embedded. Thermal management requirements in power electronics, semiconductor packaging, and high-performance coatings are pushing marginal applications into core demand channels. At the same time, feedstock dynamics are being reshaped by raw material cost movements and policy designations that alter the strategic calculus around sourcing resilience.
Several contextual shifts reinforce this interpretation. Average unit values for combined US boron imports declined from $574 per metric ton in 2024 to $540 per metric ton in 2025, providing feedstock relief to producers operating along global supply chains. Concurrently, refined borax and boric acid import volumes have remained stable, supporting consistent boron availability for downstream materials manufacturers. On the regulatory front, boron was designated a critical mineral in 2025, with the designation formalized in November and acknowledged as part of the broader critical minerals list. This policy milestone intensifies government focus on domestic sourcing, supply-chain resilience, and incentives for onshore production, directly affecting how multinational buyers evaluate long-term procurement commitments and regional channel partnerships.
These dynamics are not peripheral. They alter the cost-to-serve equation, reshape the risk profile of single-region sourcing, and influence the attractiveness of vertically integrated versus distributed production models. The full research dissects how these forces propagate through pricing, inventory strategy, and contract structuring across the value chain.
Report Architecture and Operational Utility
The Hexagonal BN market research was designed to function as a working document for strategy, procurement, R&D, and corporate development teams. Rather than stopping at aggregate sizing, the study maps the operational terrain that executives must navigate. It integrates historical performance from 2020 through 2025, a forecast structure spanning 2026 to 2032, and a series of analytical layers that translate market data into action-oriented insight.
The report’s analytical content includes:
- A baseline market evaluation covering total revenue scale, growth momentum, and structural inflection points relevant to capacity planning and demand forecasting.
- Segment-level analysis across material formats, application categories, and regional footprints, enabling teams to pressure-test product mix assumptions and channel strategies without relying on top-down generalizations.
- Competitor profiling that connects company positioning, product portfolios, and value-chain roles to broader market structure, helping buyers and suppliers benchmark influence, differentiation, and strategic vulnerabilities.
- Regulatory and raw-material context integration, including critical mineral designations and import-value trends, mapped to sourcing resilience, pricing sensitivity, and supply continuity scenarios.
- Strategic considerations for M&A screening, partnership selection, capacity investment, and product commercialization, aligned with decision cycles relevant to 2026 planning.
Importantly, the report is built to support comparative analysis without exposing readers to a shallow aggregation of metrics. Instead, it evaluates the relative weight of demand vectors, the distribution of competitive influence, and the interaction between regulatory signals and commercial execution. Readers seeking granular regional percentages, detailed application monetization splits, and material-type revenue breakdowns will find those elements in the complete research, where they are presented in a format designed for scenario modeling and investment justification.
Hexagonal BN Market
Competitive Landscape: Influence, Specialization, and Strategic Positioning
The Hexagonal BN market exhibits concentrated influence alongside a diverse field of specialists. The research evaluates how leading participants shape demand expectations, differentiate through technical capability, and position themselves relative to end-use requirements such as thermal management, lubrication, insulation, coatings, and advanced electronic applications. Market concentration metrics indicate that a relatively small group of firms captures a disproportionate share of industry revenue, while the remaining field competes through specialization, regional responsiveness, and niche technical performance.
This structure matters for 2026 strategy because concentration and specialization create different types of strategic risk and opportunity. Concentrated players can influence pricing norms, standards adoption, and supply expectations in mature application channels. At the same time, specialized manufacturers and regional producers can offer differentiated attributes in high-purity powders, monolayer and thin-film formats, ceramic components, and application-tailored formulations. For buyers, the strategic challenge is to distinguish between price competition and performance competition, and to understand where switching costs are genuinely structural rather than merely contractual.
The report profiles the core companies that define this competitive architecture, examining how each positions itself within the broader value chain. Profiles span established multinational producers as well as focused specialists and regional manufacturers. The analysis explores how these participants compete across thermal management, lubrication, insulation, composites, coatings, and semiconductor-oriented formats. Rather than listing company attributes in isolation, the report situates each player within market structure, highlighting where scale, technical differentiation, feedstock access, or application expertise creates durable positioning.
Several participant categories emerge from this competitive mapping:
- Large, broadly positioned manufacturers with multi-application portfolios spanning thermal management, composites, lubricants, and industrial end uses. These firms often anchor supply expectations in electronics, advanced ceramics, and high-temperature industrial applications.
- High-purity and research-oriented suppliers that serve demanding thermal, electrical, and laboratory applications, where specification control and material consistency are primary purchase drivers.
- Specialists in monolayer, thin-film, and advanced material formats oriented toward semiconductor and two-dimensional materials applications, where processing capability and format precision differentiate offerings.
- Regional producers and ceramic-component manufacturers that compete on industrial reliability, cost, and supply proximity, particularly in applications where volume and repeatability matter more than laboratory-grade specification performance.
The research does not treat these categories as static. It examines how participants may expand into adjacent formats, deepen application-specific offerings, or reposition relative to one another as demand vectors mature. Where relevant, the study addresses how regulatory developments and feedstock cost trends influence competitive advantages in sourcing, regional production, and supply assurance. Executives evaluating vendor consolidation, partnership strategy, or dual-sourcing requirements will find the full report’s company-level profiles and concentration analysis especially relevant for quantifying relative influence.
Strategic Implications for 2026 Decision-Making
Translating market intelligence into 2026 action requires more than trend recognition. It requires mapping growth drivers to business-specific exposure, identifying where supply resilience matters most, and determining whether the competitive environment favors consolidation, specialization, or regional diversification. The Hexagonal BN market research is structured to support exactly this kind of strategic translation.
Several implications stand out for enterprise planning:
- Demand signals are broadening beyond traditional insulation and lubrication use cases into thermal management and advanced application formats. This evolution changes which capabilities, specifications, and supply relationships become strategically important over the forecast period.
- Feedstock relief, reflected in lower average import unit values and stable refined boron volumes, can reduce near-term cost pressure for producers, but it does not eliminate structural sourcing risk. Critical mineral designation and supply-chain resilience expectations continue to shape procurement strategy, especially for organizations exposed to policy-sensitive regions or single-source dependencies.
- Market concentration creates both pricing discipline and competitive constraint. Buyers must understand whether concentration translates into supply security, margin pressure, or opportunities for differentiation through application-specific partnerships and format specialization.
- Competitive positioning is increasingly defined by technical format capability, application readiness, and regional supply assurance rather than by volume alone. This favors organizations that can align product roadmaps with the material attributes most valued in thermal, electronic, and high-temperature industrial contexts.
For companies planning capacity additions, product introductions, or vendor negotiations in 2026, the full report provides the necessary scaffolding to move from directional confidence to evidence-backed justification. Instead of relying on generalized market commentary, decision-makers can reference scenario-ready data, company-level competitive context, and regulatory-material linkages that shape real-world operating conditions.
CBN Abrasives Market
What the Complete Research Unlocks
The preview above establishes the strategic logic behind the research and the types of decisions it is designed to support. The complete Hexagonal BN market report extends this foundation into detailed segmentation analysis, comprehensive company profiles, concentration assessment, and integrated context on raw material trends and policy developments. It offers the granularity needed to evaluate regional demand concentration, application-level revenue logic, and material-format dynamics without exposing readers to high-level approximations.
Organizations that use this research effectively typically do so by linking macro trajectory to internal exposure. That means aligning procurement strategy with feedstock and regulatory signals, calibrating capacity or inventory assumptions against demand growth without over-indexing to headline figures, and using competitive structure to identify where supplier leverage, differentiation, or substitution risk is most material. The full report is built for these applications, providing a coherent reference point for strategy sessions, investment reviews, and long-range planning cycles extending through 2032.
The Hexagonal BN market will not be defined by growth alone. It will be defined by who can interpret the interaction of thermal demand, material specification, feedstock economics, and critical mineral policy with discipline. For leaders preparing for 2026, this research is intended to turn that challenge into a structured advantage. The complete dataset, segmentation detail, and competitive intelligence are available through the source report, where they can be deployed directly into enterprise decision-making with the precision that material market strategy demands.
For detailed analysis of this topic, please visit the official page: Hexagonal BN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com