

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PVP for Lithium Ion Battery Market Hits $342.15M in 2025, Forecasts 11.24% CAGR to $721.18M by 2032

Strategic Intelligence for the Energy Transition: The Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market 2026-2032
The global transition toward electrified mobility and stationary energy storage has fundamentally altered the demand dynamics for specialty chemicals used in battery manufacturing. Among these materials, Polyvinylpyrrolidone (PVP) has emerged as a critical enabler for performance optimization in lithium-ion battery production. As manufacturers scale capacity to meet the projected demand through the end of the decade, understanding the nuanced market structure of battery-grade PVP is no longer optional—it is a strategic imperative. PW Consulting is pleased to introduce our latest comprehensive market study, designed to equip industry stakeholders with the actionable intelligence required to navigate the complexities of the 2026-2032 forecast period.
This analysis serves as a prelude to our full report, offering a high-level perspective on market direction while underscoring the depth of granular data available to clients who require precision for supply chain planning, R&D allocation, and competitive positioning.
Macro Market Trajectory and Revenue Outlook
The financial trajectory of the PVP market for lithium-ion batteries indicates robust expansion, driven by the dual engines of electric vehicle (EV) adoption and energy storage system (ESS) deployment. Analysis of historical performance from 2020 through the base year of 2025 reveals a consistent upward trend in revenue generation, reflecting the materialization of demand forecasts that were previously considered ambitious.
Binders for Lithium Ion Batteries Market
In 2020, the global market revenue stood at approximately 164.2 million USD. By 2025, this figure had climbed to 342.15 million USD, demonstrating a compound growth pattern that outpaces many traditional industrial chemical segments. The report projects that this momentum will accelerate into the forecast period. Revenue is expected to reach 376.25 million USD in 2026 and continue its ascent to 721.18 million USD by 2032. This growth path implies a significant increase in consumption volume as battery factories operationalize gigafactory-scale production lines worldwide.
Our modeling indicates a robust compound annual growth rate (CAGR) of 11.24 percent throughout the forecast horizon. This rate suggests that PVP will maintain its criticality in battery chemistries, resisting substitution by alternative binders or dispersants in the near term. For strategists, this CAGR is not merely a percentage; it represents the velocity at which market share can be captured or lost depending on supply chain resilience and product specification alignment.
Segmentation Dynamics: Type, Application, and Regional Distribution
While the aggregate numbers signal growth, the strategic value of this report lies in its dissection of the market into actionable segments. The study provides a detailed breakdown of the market by product type, application, and region, revealing where value is being created and where supply bottlenecks may emerge.
Product Type Dynamics
The market is bifurcated into Powder PVP and Solution PVP. Powder PVP continues to command a significant share of the market revenue, driven by its logistical advantages in bulk transport to battery manufacturing hubs and its versatility in dry mixing processes. However, Solution PVP is carving out a distinct niche, particularly in facilities where immediate slurry preparation is prioritized over long-term storage stability. Our analysis details the revenue contribution and volume trends of each type, highlighting the specific technical requirements that drive purchasing decisions in automated mixing lines versus manual formulation setups. Clients will gain insight into which form factor aligns best with their processing logistics and cost structures.
Application Criticality
In terms of application, the report segments demand across Carbon Nanotube Dispersant, Electrode Binder Additive, and Ceramic Coating for Separators. Historically, the use of PVP as a dispersant for conductive additives, such as carbon nanotubes and carbon black, has been a primary driver of volume. The ability of PVP to stabilize these conductive networks in the electrode slurry directly impacts the electrical performance and cycle life of the final cell.
Concurrently, the role of PVP in ceramic coating for separators is gaining traction. As battery safety requirements tighten with higher energy densities, the use of PVP-based binders in separator coatings offers adhesion and thermal stability benefits. The Electrode Binder Additive segment also remains substantial, particularly for specific anode and cathode chemistries where adhesion to the current collector is paramount. The full report quantifies the revenue splits across these applications, revealing which function is acting as the primary volume driver in different production environments and how the mix is expected to shift as battery architectures evolve.
Regional Landscape
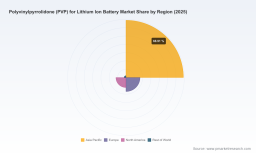
Geographically, the Asia Pacific region stands as the dominant consumer and producer of battery-grade PVP, reflecting the concentration of global battery cell manufacturing capacity. The market data reflects substantial revenue generation within this region, supported by the presence of major battery manufacturers and downstream EV assembly plants. Europe and North America represent mature but growing markets, driven by local content requirements and the establishment of new gigafactories in Western economies. The Rest of World segment, while smaller in absolute terms, shows potential for incremental growth as battery adoption expands in emerging markets.
The full report provides detailed regional revenue figures and forecasts, allowing companies to assess market attractiveness by territory. It examines the interplay between local production capabilities and import reliance, identifying where tariff structures or logistics costs may influence the final landed cost of PVP materials.
Competitive Landscape and Industry Dynamics
The market structure for battery-grade PVP is characterized by a mix of global specialty chemical giants and agile regional manufacturers. Our analysis of the competitive landscape reveals a moderately concentrated market, with the top three companies holding a combined market share of approximately 64.25 percent, while the top five firms account for roughly 79.1 percent of total revenue. This concentration suggests that while incumbents hold significant sway, there is room for specialized players to capture niche segments through performance differentiation.
Key Market Participants
Ashland Inc. (Wilmington, Delaware, USA) remains a prominent supplier of PVP K-Series polymers used as binders and additives. Their portfolio includes specialty binders like Soteras CCS-V for separators, emphasizing performance polymers for enhanced coating and electrochemical properties. Ashland's focus on high-performance solutions positions them as a preferred supplier for premium-tier battery applications where performance margins are narrow.
BASF SE (Ludwigshafen, Germany) provides PVP for lithium-ion battery applications primarily as dispersants and processing aids in electrode formulations. Their extensive portfolio of additives for cathode, anode, and separator coatings allows them to offer integrated solutions for slurry stability. BASF leverages its global scale to maintain consistent supply chains across major production regions.
In China, the competitive field is diverse and includes several specialized producers. Boai NKY Pharmaceuticals Ltd (NKY Medical) in Jiaozuo, Henan, is a major producer offering battery-grade PVP K30 powder specifically developed for lithium battery applications, supplying high-purity grades for dispersant use. NIPPON SHOKUBAI Co., Ltd. (Osaka, Japan) manufactures PVP used as dispersants for metal oxides and carbon materials, supporting electrode slurry formulation and performance enhancement.
Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Synvent Materials Corporation (Ningxia, China) offers Syno® PVP Battery Grade (e.g., K30 Battery with K-value 27-32.4, >98% solids, <100 ppm NVP) manufactured under cGMP standards. This focus on high purity and certification makes them relevant for applications where impurity control is critical. Henan Pengfei New Materials Co., Ltd. produces PVP series for lithium battery cathode slurries and nano materials, emphasizing dispersant roles. Their recent technical updates in 2025 have highlighted performance data on PVP as nonionic dispersants, showcasing improved stability and processing efficiency. Huzhou Sunflower Specialty Polymer Co., Ltd. in Zhejiang is another leading manufacturer of PVP K-series, supplying PVP as dispersant for lithium battery cathode materials.
While these companies represent the core competitive set, the full report profiles additional entities and analyzes their specific revenue contributions, capacity expansions, and strategic partnerships. It dissects the moves made by these players, such as technical application updates and product launches, to reveal the direction of innovation in the sector.
Critical Market Drivers and Headwinds
Understanding the market trajectory requires a clear view of the forces shaping supply and demand. The report integrates several dynamic factors that influence pricing, availability, and margin structures.
Raw Material Constraints and Costs
The upstream feedstock for PVP, N-vinylpyrrolidone (NVP), relies on commodities such as calcium carbide and acetylene. The cost of these raw materials forms a significant portion of the total production cost for battery-grade PVP. Demand for PVP in lithium batteries and photovoltaic silver paste has risen sharply in recent years, contributing to price premiums for high-purity grades. There is an industry expectation that demand will continue to escalate, putting upward pressure on feedstock availability. Furthermore, environmental restrictions on chemical industrial parks in China have occasionally led to imbalances in NVP supply, impacting the availability of high-purity battery-grade PVP. These supply-side frictions can lead to volatility in pricing and require proactive supply chain management.
Price Volatility and Cost Structures
Historical price data indicates that PVP prices have fluctuated within a notable range over recent periods, influenced by raw material costs and demand from the new energy sector. For procurement teams, this volatility underscores the need for long-term contracts, hedging strategies, or vertical integration considerations. The report examines price trends and correlates them with capacity utilization rates and feedstock index movements to help clients anticipate cost cycles.
Usage Intensity and Specification Trends
The intensity of PVP usage per unit of battery capacity is a key metric for forecasting demand. Industry benchmarks suggest specific usage rates for PVP in lithium battery applications, primarily involving industrial-grade PVP K30 and K90 as dispersants for cathode materials. As cathode chemistries evolve toward higher nickel contents or silicon blends, the specification requirements for binders and dispersants may shift, potentially altering the consumption rate or driving demand for higher purity grades. Our study analyzes these technical trends to project how usage intensity might evolve over the forecast period.
Report Architecture and Analytical Depth
The "Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market" report is structured to guide decision-makers from macro trends to micro-level execution details. Beyond the market sizing and segmentation discussed above, the full document includes:
- Historical Reconstruction (2020-2025): A detailed year-by-year breakdown of market performance, allowing for validation of internal models against external data and identification of anomaly periods caused by supply disruptions or demand shocks.
- Forecast Methodology (2026-2032): Transparent modeling assumptions regarding capacity additions, technology adoption curves, and regional growth drivers. The forecast accounts for known pipeline projects and policy interventions that may alter market equilibrium.
- Competitive Benchmarking: In-depth profiles of key companies, including their product portfolios, production capacities, geographic footprint, and recent strategic developments. The report assesses the relative positioning of each player in terms of price, quality, and service.
- Segment Revenue and Volume Analysis: Granular data splits for region, type, and application. These splits are essential for companies to identify high-growth pockets and allocate resources accordingly.
- Supply Chain and Raw Material Analysis: An examination of the NVP supply chain, cost structures, and the impact of environmental regulations. This section helps stakeholders assess risk exposure in their upstream dependencies.
- Strategic Recommendations: Actionable insights for suppliers, buyers, and investors. This includes guidance on market entry strategies, partnership opportunities, and risk mitigation tactics.
Our research team has synthesized data from public filings, industry surveys, technical literature, and primary interviews to construct a cohesive narrative. The result is a document that not only tells you what the market is doing but explains why it is doing it and what it means for your specific business context.
The 2026 Strategic Imperative
As the industry enters 2026, the window for aligning strategy with market realities is narrowing. The projected growth to 2032 indicates a market that will be significantly larger and potentially more complex than it is today. Companies that rely on aggregate data alone may miss the nuances of regional shifts, application-specific demand surges, or competitive moves by niche players.
For suppliers, the opportunity lies in capturing share in high-growth segments by differentiating on purity, consistency, or technical support. For battery manufacturers, the focus must be on securing reliable supply of grade-specific materials while managing cost volatility through strategic sourcing. For investors, understanding the concentration dynamics and the emergence of new capacity is vital for evaluating the risk-return profile of assets in this value chain.
The full report provides the data backbone required to make these decisions with confidence. It quantifies the revenue opportunities in each segment, maps the competitive threats, and highlights the supply chain vulnerabilities that could disrupt operations. By accessing this intelligence, organizations can move beyond reactive planning to proactive strategy execution.
Conclusion
The Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market is at a pivotal juncture. The convergence of electrification mandates, battery chemistry innovation, and raw material dynamics creates a landscape rich with opportunity but fraught with complexity. PW Consulting's comprehensive study offers the clarity needed to navigate this environment.
While this overview highlights the macro trajectory and structural dynamics, the precise segmentation data, detailed competitive rankings, and scenario-based forecasting remain within the full report. We invite industry leaders, procurement directors, and strategy teams to access the complete intelligence package to ensure their 2026 planning is built on a foundation of rigorous, up-to-date analysis.
Request the Full Report and Detailed Segmentation Data
For detailed analysis of this topic, please visit the official page: Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com