

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: General Bio‑Based Polyamide Market Poised for Breakout, Growing at 15.02% CAGR Through 2032
By pmarketresearch, 2026-07-01
General Bio-Based Polyamide Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting today releases a forward-looking briefing derived from our full market research report on the General Bio-Based Polyamide Market. The briefing synthesizes why 2026 will be a pivotal year for procurement, product development, and capital allocation decisions across automotive, textiles, consumer goods, electronics, and industrial manufacturing. It highlights the macro trajectory—built on our modeled market build from historical data (2020–2025) into a 2026–2032 forecast—and explains the practical, decision-ready content executives will find in the complete report.
General Bio Based Polyamide Market
Why 2026 Is a Strategic Inflection Point
Our modeling shows the global bio-based polyamide market expanding rapidly from its 2025 base to a materially larger market by the end of the 2026–2032 forecast window. The forecast period delivers a compound annual growth rate of 15.02%, driven by accelerating adoption in technical applications, regulatory incentives in key jurisdictions, and tangible downstream decarbonization commitments. By anchoring on the 2025 baseline and stress-testing plausible 2026 business scenarios, the full study equips leaders to prioritize investments, hedge supply-chain risk, and capture share in fast-moving adjacencies.
General Bio Based Polyamide Market
What Senior Executives Need to Know—At a Glance
- Market momentum: The market has grown consistently through the 2020–2025 period and enters 2026 with strong demand signals across multiple end-use sectors.
- Acceleration factors: Regulatory pressure (notably in European markets), corporate net-zero commitments, and product performance parity in many applications are accelerating commercial uptake.
- Concentration and competition: The market exhibits a moderate degree of supplier concentration—enough to reward strategic partnerships but still leave space for innovative entrants and niche specialists.
- Raw material dynamics: Renewable feedstocks—particularly castor oil derivatives—remain central to cost and availability dynamics, with feedstock supply volatility capable of producing short-term price spikes that affect feedstock-linked intermediates.
Market Dynamics and Near-Term Risks
Two structural dynamics will shape board-level choices in 2026. First, regulatory frameworks and procurement policies are rapidly moving from aspirational language to concrete procurement incentives and technical acceptance criteria. For companies operating in jurisdictions aligning incentives with circularity and carbon intensity reduction, bio-based polyamides are becoming a default option for new programs in automotive, consumer electronics, and select industrial applications.
General Bio Based Polyamide Market
Second, feedstock and intermediate-price volatility remains a tactical risk. Castor-derived intermediates and downstream sebacic acid have exhibited significant month-to-month price fluctuations in recent historical windows—an operational challenge for midstream processors and converters. Firms that align procurement strategies with forward contracting, offtake arrangements, and alternative feedstock options will have a measurable cost-of-goods advantage in 2026.
Competitive Landscape—Where Leaders Are Placing Bets
The competitive map is composed of legacy chemical majors and specialist bio-based players. Several strategic moves in 2024–2026 illustrate how incumbents are scaling and differentiating:
- Arkema has pursued integration and transparent-grade capacity expansion, bringing into production a high-transparency bio-based polyamide unit in Singapore that substantially scales supply for high-value niches such as medical devices and eyewear. Arkema’s carbon-footprint improvements—validated to a low-kilogram CO2e per kilogram production figure—signal how renewable electricity and process efficiency can create a class-leading sustainability claim.
- Evonik continues to position high-performance partially bio-based grades and powders for technical applications and additive manufacturing, targeting engineering customers that require predictable material properties and supply security.
- DSM-Firmenich (Envalior) and RadiciGroup have concentrated on automotive-grade polymers with demonstrated in-service performance, while Asian innovators such as Cathay Biotech are introducing novel monomer pathways (e.g., cadaverine-derived chemistries) that broaden feedstock optionality and fiber applications.
- Mass-balance and bio-attributed strategies are being adopted by producers such as DOMO and BASF, with ISCC-certified offerings enabling customers to credibly claim reduced lifecycle impacts without immediate upstream overhaul.
- Smaller specialists and technology developers—Toray, Mitsubishi Gas Chemical, and Avient among them—are targeting biodegradation, specialty cosmetic applications, and formulation-led replacement opportunities.
These moves together create a layered competitive field in which scale, certification, feedstock integration, and targeted application expertise determine which firms capture growth pockets. The market concentration metrics in our study confirm that a handful of suppliers command meaningful share, but there is clear room for differentiated entrants and regional champions.
Practical Capabilities in the Full Report (What We Don’t Publish Here)
Following the “trailer” principle, we present the strategic architecture of the full report without disclosing sensitive segment tables and supplier-level volumes. The comprehensive study, however, contains a suite of practical tools designed for immediate application in 2026 planning cycles:
- Scenario-driven demand model: A dynamic model that supports “what-if” runs for regulatory shifts, feedstock shocks, and premium adoption curves, calibrated to historical 2020–2025 data and our 2026–2032 forecast.
- Supply-risk heatmap: Granular assessment of feedstock risk, supplier concentration at sub-regional level, and contingency options that materially affect sourcing strategies and working-capital planning.
- Commercial playbooks: Tailored approaches for OEMs, converters, and polymer producers that translate sustainability claims into product specifications, cost-impact pathways, and phased adoption milestones.
- Capex and plant-siting decision frameworks: Investment appraisal templates that quantify payback under different incentive regimes and access to renewable power or integrated feedstock sources.
- Procurement and contracting templates: Best-practice terms for long-term offtake, indexation clauses for feedstock volatility, and certification verification workflows.
Strategic Recommendations for 2026 Planning
- Prioritize hybrid sourcing strategies: Combine contracted offtake from integrated suppliers with spot access to alternative feedstock-based grades to mediate price spikes and secure innovation premiums.
- Lock in sustainability credentials early: Work with ISCC and bio-attribution providers to set up traceable claims; mass-balanced offerings can bridge near-term carbon goals while dedicated bio-feedstock volumes scale.
- Target application-first substitution: Identify high-value, low-volume applications (connectors, tubing, selective consumer goods) where bio-based grades already match performance and command higher margin capture.
- Invest in co-development with material providers: Co-funded trials, joint validation, and shared technical roadmaps reduce time-to-adoption and align material roadmaps with OEM qualification cycles.
- Stress-test supply chains for feedstock shocks: Build buffers, diversify suppliers geographically, and model financial contingencies for the type of midstream price volatility observed historically.
Risk-Reward and the Executive Checklist
The risk-reward trade-off in 2026 favors organizations that take an active, structured approach to adoption. Risks include feedstock price volatility, qualification timelines for critical applications, and potential policy reversals or uneven regulatory alignment between markets. Rewards include accelerated compliance with decarbonization goals, access to premium product positioning, and first-mover advantage in emerging application clusters.
Executives evaluating engagement should consider this short checklist:
- Have you validated total-cost-of-ownership for bio-based alternatives at the product level, not just resin price?
- Do your suppliers have credible certification and transparent chain-of-custody mechanisms?
- Can your R&D and procurement functions run concurrent qualification and contractual negotiation tracks?
- Are capital and supply contingencies in place to manage feedstock-driven mid-cycle price shocks?
What the Full PW Consulting Report Delivers
The complete General Bio-Based Polyamide Market report is designed as an operational toolkit for 2026 boardrooms and commercial teams. It combines our proprietary demand-supply modeling, supplier benchmarking, certification and policy analysis, and executable playbooks into a single deliverable that supports strategy, procurement, and engineering stakeholders. The report also documents recent industry developments and supplier moves that matter for 2026 sourcing decisions—capacity ramp-ups, ISCC and low-carbon product launches, and measured carbon-footprint disclosures that materially affect procurement criteria.
Next Steps
PW Consulting invites corporate leaders, investors, and procurement teams to review the executive summary and access the full dataset and models via the report landing page. The full report includes source-level data, scenario models, and an annex of supplier profiles and validated performance claims that are essential for executable 2026 plans.
For teams seeking immediate support, PW Consulting offers bespoke briefings and rapid-turn validation workshops to align technical, commercial, and procurement stakeholders around a pragmatic adoption roadmap.
For detailed analysis of this topic, please visit the official page: General Bio Based Polyamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rubidium-83 Market Poised for 6.18% CAGR Through 2026–2032 Forecast
By pmarketresearch, 2026-07-01
Rubidium-83 Market — 2026 Strategic Briefing
PW Consulting’s latest Rubidium-83 Market report provides the actionable intelligence senior leaders need to make high-confidence choices in 2026 — from sourcing and supply resilience to R&D investment prioritization and M&A screening. This briefing explains why Rubidium-83 has moved from a niche laboratory input to a strategic material in specific research and imaging ecosystems, summarizes the report’s high-level findings, and highlights the practical deliverables executives can use immediately. For practitioners, this is a “trailer” of our full study: we show the analytical depth and decision frameworks while reserving full segment-level tables and proprietary model outputs for the complete report on our site.
Rubidium-83 Market
Market Snapshot: Growth, Scale and Concentration
Rubidium-83 is a small but fast-growing specialty isotope market. Our base-year sizing places the global market at a modest yet steadily rising level in 2025, following a consistent expansion since 2020. Forward-looking projections embedded in the report forecast a compound annual growth rate (CAGR) of 6.18% across the 2026–2032 forecast window, reflecting growing research demand, constrained primary supply dynamics, and rising downstream activity in tracer and calibration applications.
Rubidium-83 Market
Two structural characteristics are critical for strategy: first, the total market dollar size is compact relative to mainstream commodity metals, which underscores the importance of supplier access and cost control for key end-users; second, market concentration is high — the combined share of the largest three suppliers materially dominates the market, and the top five account for virtually the entire commercialized trade. These concentration metrics drive the competitive and risk profile and are central to the playbooks we recommend for buyers, investors, and policy stakeholders.
Rubidium-83 Market
Why 2026 Is a Decision Point
- Demand inflection: Several scientific and medical research programs that use rubidium isotopes for calibration, detector testing, and tracer development are moving from pilots into larger-scale experimental campaigns in the next 12–24 months. This creates discrete procurement events that can strain the currently compact supply network.
- Supply friction: Primary rubidium supply remains a byproduct of other mineral mining and refined chemical supply chains, and the effective capacity to produce accelerator-derived isotopes is limited. That structural supply tightness means that procurement timing, qualification, and long-term agreements will determine access and pricing for research organizations.
- Concentration risk: High CR3/CR5 concentration means single-supplier events — technical, regulatory, or geopolitical — can quickly propagate through downstream programs. Mitigating this requires deliberate supplier diversification, contingency inventory policies, and, where relevant, vertical partnership strategies.
Supply Chain & Production Dynamics
Rubidium-83 supply is shaped by two linked realities. First, primary rubidium feedstock is not mined as a dedicated large-scale product; it generally appears as a byproduct in cesium and lithium mining circuits. As a result, primary availability is closely coupled to the economics of other commodity value chains. Second, the isotope used for research-grade Rubidium-83 is produced predominantly in accelerator environments via proton bombardment of RbCl targets — a production route that yields very specific radionuclidic purity requirements and that is not readily rampable without specialized capital and regulatory clearance.
For decision-makers this translates into three tactical actions: (1) treat long-lead-time production slots at accelerator facilities as strategic capacity — securing them early under contract is often cheaper than paying spot premiums later; (2) qualify substitute chemistries and delivery forms to increase purchasing optionality; and (3) invest in upstream relationship mapping — understanding the mining-to-refining pathways for rubidium feedstock will be critical to negotiating effective supply terms.
Price and Cost Trends
Observed market behavior in recent years shows clear upward pressure on pricing for high-purity rubidium metal and refined compounds. The price trajectory accelerated in 2022–2023, driven by tighter feedstock availability and increased buying from research programs. Our report quantifies the cost drivers and models scenarios for marginal price movement under alternative supply/demand shocks — including a short, sharp accelerator outage versus steady demand ramp. Executives will find a practical pricing playbook in the full report: recommended hedging approaches, contract structures, and negotiation levers tailored to both single-use research consumers and institutional procurement groups.
Regulatory and Quality Constraints
Rubidium-83 is supplied under strict radionuclidic purity specifications and is designated for research applications. Compliance with radionuclidic impurity thresholds and solvent/formulation controls is non-negotiable for end-users, particularly in regulated medical and biological research settings. The report includes a compliance matrix that aligns supplier capabilities to the most commonly enforced specification buckets and maps certification, testing frequency, and custody transfer practices that materially impact program timelines and reproducibility.
Competitive Landscape — Who Matters
The market is composed of a small set of specialized suppliers and distributors, each occupying distinct roles along the value chain. PW Consulting’s competitive analysis synthesizes company capabilities, supply modalities, and go-to-market models, and highlights where strategic partnerships or acquisitions would yield the highest operational leverage. Key archetypes identified in the report include:
- Government-backed production and stewardship: National isotope programs act as a stabilizing supplier for specialized isotopes and often maintain non-commercial production channels for research-grade material. Their offer model typically emphasizes compliance and traceability.
- Global specialty chemicals suppliers: Established materials companies supply both stable rubidium compounds and tailored isotopic products for advanced materials and electronics markets. These firms excel in volume handling and distribution networks.
- Specialist isotope vendors and distributors: Market-focused firms supply high-purity and research-grade isotopes, with capabilities in packaging, short-run production, and regulatory handling specific to radioactive materials.
Our full report provides an operational comparator for the leading participants, detailing manufacturing footprints, accreditation status, lead-time profiles, and distribution channels. This enables procurement teams to run supplier-by-supplier risk assessments and to model the sourcing implications of a switch or of adding secondary providers.
Geopolitics and Sourcing Risk
Primary rubidium production is concentrated geographically and closely associated with the mining footprints of a few countries. That geographic concentration, combined with the lack of large-scale primary mining outside core producer jurisdictions, elevates supply vulnerability to trade policy shifts and export controls. The report maps these geopolitical exposures against customer demand clusters and offers mitigation strategies — from dual-sourcing and nearshoring pilots to in-market inventory pooling and strategic reserves for mission-critical programs.
Practical Deliverables: What the Report Contains
- Market sizing and validated growth scenarios (2020–2032), with sensitivity analyses designed for procurement planning horizons of 12–36 months.
- Supply chain map and supplier capability profiles, including production modalities (accelerator vs reactor routes), qualification timelines, and cost-to-serve breakdowns.
- Regulatory compliance matrix and quality-assurance playbook — including radionuclidic purity bands, testing protocols, and recommended contract clauses to manage liability and chain-of-custody.
- Commercial strategy toolkit: template RFQ clauses, sample long-term supply agreement structures, and negotiation levers mapped to supplier archetypes.
- Risk heatmaps and contingency models — rapid-impact scenarios and recommended operational responses (e.g., how to prioritize orders or substitute materials under supply stress).
- M&A and partnership scouting: a prioritized shortlist of technology and distribution targets, with acquisition rationale and integration risk assessment.
Use Cases: How Buyers and Investors Can Apply the Report in 2026
- Procurement teams — convert forecast uncertainty into procurement certainty by using our timing model to lock production slots and to size safety stock in a way that ties directly to research program milestones.
- R&D and scientific organizations — leverage the compliance playbook to shorten qualification cycles and to structure purchase orders that preserve experimental reproducibility.
- Strategic investors — use the concentration and scenario modules to identify consolidation targets where scale can reduce lead times and lower unit costs across customer segments.
- Public policy and national labs — adopt the supply-resilience checklist to design contingency capacity and to evaluate the case for targeted domestic capability investments.
Why PW Consulting’s Intelligence Is Distinctive
Our approach combines granular supply-chain interrogation with program-level demand mapping. We triangulate supplier disclosures, laboratory procurement behavior, and upstream mineral dynamics to produce a decision-grade view rather than an academic forecast. The analysis is deliberately practice-oriented: each chapter ends with a "what to do next" checklist and an eight-step implementation timeline managers can apply within 90 days.
Next Steps & How to Access the Full Report
This briefing intentionally highlights the frameworks and strategic implications without reproducing our full segmentation tables, supplier scorecards, and proprietary scenario outputs. Those core data assets — including supplier-specific lead times, contract language templates, and the complete demand-by-application model — are available in the full PW Consulting Rubidium-83 Market report on our website. Organizations planning procurement cycles or portfolio moves in 2026 should review the full study before finalizing capital allocation or long-term contracts.
For customized briefings, supplier stress-testing, or a private workshop to translate these insights into a one-year action plan, contact PW Consulting’s Isotopes and Specialty Materials practice. Our on-demand advisory services include bespoke scenario runs using client-specific demand curves and tailored supplier negotiation support.
For detailed analysis of this topic, please visit the official page: Rubidium-83 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cochloroether Rubber Eco Market to grow at 4.51% CAGR, hitting USD 874.95 million by 2032 as Asia Pacific leads with USD 297.96M in 2025
By pmarketresearch, 2026-07-01
PW Consulting Preview: Cochloroether (ECO) Rubber Market — Strategic Intelligence for 2026 Decision-Making
PW Consulting today releases a preview of its forthcoming Cochloroether (ECO) Rubber Eco Market report, offering senior executives and strategy teams a synthesis of the market forces that will shape commercial outcomes in 2026 and beyond. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study projects continued expansion at a compound annual growth rate (CAGR) of 4.51%. The total market expanded from approximately USD 515 million in 2020 to about USD 643 million in 2025 and is modeled to approach USD 875 million by 2032 — an investment case that invites active portfolio positioning and supply-chain decisions in the coming 12–18 months.
Cochloroether Rubber Eco Market
Why this report matters for 2026 planning
-
High-impact, near-term choices: 2026 will be a year when procurement contracts renew, capital allocation debates are settled, and regulatory-compliance roadmaps firm up — all under a market context of steady mid-single-digit growth.
Cochloroether Rubber Eco Market -
Supply-side complexity: upstream epichlorohydrin dynamics, including new capacity additions and evolving bio-based production routes, are already re-shaping feedstock sourcing economics and margin profiles across the value chain.
Cochloroether Rubber Eco Market -
Concentration and counterparty risk: the ECO rubber ecosystem exhibits oligopolistic features that alter negotiation leverage, partner selection, and competitive response strategies.
-
Regulatory and product-risk bifurcation: material formulations that avoid hazardous curing systems and enable automotive OEM compliance present differentiated commercial opportunities.
What the PW Consulting report delivers — practitioner-focused, execution-ready content
-
Proprietary market model & scenario toolkit — a fully transparent forecast engine (2026–2032) with sensitivity levers for feedstock prices, capacity additions, and end-market demand shocks.
-
Actionable supplier scorecards — qualitative and quantitative assessments of incumbent manufacturers and compounders that support supplier rationalization or qualification plans.
-
Commercial playbooks — tailored go-to-market and pricing strategies for suppliers, OEMs, and distributors across differing risk appetites and time horizons.
-
Supply-chain mapping and sourcing options — downstream exposure mapping, alternative feedstock sourcing, and recommendations for hedge structures and long-term agreements.
-
Regulatory & sustainability matrix — compliance impact assessment, product substitution risk rankings, and a roadmap for integrating bio-based feedstocks and lead/ETU-free curing technologies.
-
M&A and partnership screening — a shortlist of archetypal targets and the due-diligence checklist our practitioners use to validate accretive acquisitions or joint ventures.
-
Primary intelligence — interviews with industry leaders, plant-level capacity checks, and market testing feedback to validate modeled outcomes.
Market dynamics and feedstock context
Two supply-side realities deserve immediate attention. First, epichlorohydrin remains the primary upstream feedstock for ECO rubber. Global epichlorohydrin production capacity and utilization trends materially affect industry margins and pricing behavior. Recent industry monitoring shows global production capacity in the multi-million-tonne range and a sizable gap between nameplate capacity and actual output, with significant capacity additions announced in consecutive years. Those additions — many tied to glycerol-based, lower-carbon production routes — are shifting the cost curve and creating differentiated supply pools for companies willing to qualify bio-based inputs.
Second, price signalling from major producers has amplified procurement risk. Public pricing actions and periodic increases are a reminder that integrated producers retain the option to pass through feedstock-driven cost shocks. For buyers and compounders, this translates to a need for dynamic contracting, blended sourcing, and contingency inventory strategies. PW Consulting’s report models a range of epichlorohydrin price and availability scenarios and traces their impact on margins, product viability, and total cost of ownership for OEMs and tier suppliers.
Competitive landscape — who matters and why
The ECO rubber industry is concentrated. The top three manufacturers account for a meaningful majority of market supply, and the top five widen that hold further — a structural feature that shapes capacity access, contract terms, and innovation pathways.
-
Osaka Soda Co., Ltd. — A fully integrated producer with monomer-to-polymer capabilities and a long track record in EPICHLOMER™ and related grades. Integration gives it margin and supply stability advantages and the ability to manage upstream disruptions internally.
-
Mitsui Plastics, Inc. — A legacy supplier with high-purity ECO lines and deep experience in customizable formulations. Its long production history and modular grade portfolio make it a go-to partner for OEMs requiring proven performance and tailored properties.
-
Zeon Corporation — Known for the Hydrin® family, Zeon emphasizes thermal, fuel, and ozone resistance with production footprints that include U.S.-based capacity for select grades. This geographic stance is relevant for buyers seeking regional supply security or localized content.
-
BRP Manufacturing — A U.S.-based compounder focused on application-specific, ASTM-compliant grades. Its strengths are speed-to-sample, customization for automotive components, and proximity to North American OEMs.
-
RADO Gummi GmbH — A European specialist delivering ETU-/lead-free curing systems and formulations optimized for compliance and low permeability. Its product positioning addresses tightening regulatory expectations and OEM risk programs.
These firms differentiate by integration (monomer production vs. compounding), regional footprint, and product/curing chemistries. For potential entrants or investors, the implication is clear: compete on either technology (bio-based, ETU-free chemistries), service (localized compounding and rapid qualification), or cost (scale-driven, integrated production).
Regulatory and sustainability vectors to watch
Regulatory attention on curing systems and hazardous additives has created measurable demand for ETU-free and lead-free formulations. At the same time, sustainability pushes — including OEM targets for low-carbon materials — are accelerating interest in glycerol-derived and other bio-based epichlorohydrin routes. These shifts are not merely compliance items; they are value-creation levers for suppliers that can demonstrate lower life-cycle emissions and simplified regulatory risk profiles.
Strategic recommendations for 2026
-
Adopt a two-tier procurement strategy: secure a baseline of capacity with integrated producers while qualifying alternative compounders and bio-based feedstock suppliers to preserve optionality.
-
Invest in product differentiation where regulation meets performance — ETU-/lead-free curing and low-permeability grades are becoming table stakes for automotive and regulated industrial applications.
-
Recalibrate pricing models: build contract clauses that include transparent pass-through mechanics for feedstock inflation and capacity constraint premiums.
-
Prioritize regionalization for critical applications: localized production reduces lead times and mitigates supply-chain shocks for mission-critical OEM platforms.
-
Evaluate M&A and capacity partnerships selectively: focus on targets that fill functional gaps (e.g., bio-feedstock access, ETU-free curing IP, or compounding scale in priority markets).
-
Run scenario-based product roadmaps: use the PW Consulting forecast toolkit to stress-test R&D pipelines against low-, mid-, and high-growth outcomes through 2032.
How PW Consulting converts insight into execution
We build market intelligence with the explicit goal of enabling decisions. The full report provides the editable financial model, a supplier heatmap, and playbooks that translate analysis into boardroom-ready actions. Clients receive: the primary-data foundation (supplier interviews and plant checks), a validated forecast engine with scenario toggles, and prioritized strategic initiatives mapped to investment size, time-to-benefit, and execution risk.
Where this preview is intentionally high-level, the full report contains the granular segmentation, company scorecards, and modeling assumptions that commercial teams and M&A committees require to commit capital or amend sourcing contracts. For organizations preparing budgets, negotiating supplier agreements, or planning product launches into 2026, that level of detail is material and actionable.
Next steps
PW Consulting’s Cochloroether (ECO) Rubber Eco Market report is designed to be the decision-support asset for the next wave of strategic moves across suppliers, OEMs, and investors. To access the full dataset, proprietary segmentation, and our scenario-ready financial model, visit the report page or contact PW Consulting to schedule a briefing with our sector practice. In a market with concentrated supply, evolving feedstock pathways, and tightening regulatory expectations, early access to validated intelligence will be a competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Cochloroether Rubber Eco Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cosmetic-Grade Sorbitan Esters Market Set to Grow at a 5.45% CAGR, Fueling Skincare Innovation
By pmarketresearch, 2026-07-01
Cosmetic Grade Sorbitan Esters Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases its authoritative market study on Cosmetic Grade Sorbitan Esters, built to serve as an operational playbook for leaders in chemicals, personal care formulation, procurement, and private equity. The report synthesizes five years of historical performance with a forward-looking forecast through 2032 to convert market signals into actionable strategies for 2026. In short: the market has moved from a mid‑single‑hundred million-dollar base in 2020 to a stronger industry in 2025, and is projected to continue growing at a steady mid‑single‑digit CAGR through the forecast horizon.
Cosmetic Grade Sorbitan Esters Market
Why this report matters for 2026 strategic planning
-
Decision-ready macrotrend clarity: Our analysis shows the market expanding from its 2025 baseline and tracking to meaningful scale by 2032 under the central forecast (5.45% CAGR). This trajectory matters if your 2026 priorities include capacity planning, price setting, or portfolio rationalization.
Cosmetic Grade Sorbitan Esters Market -
Concentration and competitive tension: Market concentration is material but not monopolistic—our benchmarking reveals a top‑three share that signifies strong incumbents and a top‑five structure that leaves room for mid‑tier challengers and specialized niche entrants. That balance creates differentiated playbooks depending on scale and capabilities.
Cosmetic Grade Sorbitan Esters Market -
Regulatory and reputational guardrails: Recent regulatory activity and public-health reporting reinforce that sorbitan esters remain a cleared, stable ingredient under current cosmetic frameworks—nonetheless, adjacent regulatory movements and PFAS scrutiny require governance in 2026 product approvals and supplier attestations.
-
Upstream vulnerability: Raw material dynamics and feedstock routing continue to be the primary near‑term margin lever. Our scenario work models procurement stress and relief pathways so teams can plan for both disruptive price swings and prolonged cost declines in certain sourcing corridors.
Highlights from the dataset (what we disclose here)
-
Market scale and pace: The report documents the market’s growth from the early 2020s through a 2025 market base and projects a path to the end of the decade; the global market is forecast on a consistent USD basis with an annualized growth rate of 5.45% across the forecast window.
-
Competitive concentration: The top three and top five players hold a meaningful share of the market, signaling both the power of established ingredient houses and the potential for differentiated strategies by specialized suppliers.
-
Regulatory context: We track recent public assessments and agency outputs that affect ingredient acceptability and supplier due diligence, including a mid‑2025 scientific opinion that maintained established safety profiles relevant to cosmetic use and late‑2025 agency reporting that did not implicate sorbitan esters in broader contaminant discussions.
What’s in the full report — practical, executable content
-
Integrated market model (historical 2020–2025, forecast 2026–2032): downloadable Excel with sensitivity toggles for price, demand elasticity, and substitution rates.
-
Segment playbooks: go-to-market and product development guidance tailored to ingredient manufacturers, contract formulators, and brand owners (including recommended KPIs and go/no‑go thresholds).
-
Price and margin scenarios: three distinct procurement scenarios with hedging and sourcing strategies tied to feedstock risk indicators.
-
Competitive benchmarking: strategic profiles, technological differentiators, route‑to‑market strengths, and M&A posture for leading and emerging suppliers.
-
Regulatory tracker and compliance checklist: a living annex mapping agency actions, labeling obligations, and documentation best practices for 2026 submissions.
-
Supplier map and risk matrix: mapped supply chains, single‑sourced nodes, and an operational risk scorecard to prioritize supplier audits and redundancy investments.
-
Commercial diligence pack for investors: valuation sensitivities, earnout structures suitable for ingredient targets, and integration playbooks for bolt‑on acquisitions.
Competitive landscape — implications for 2026
The market’s incumbent set includes established specialty chemistry houses and a cohort of regional producers. Global specialty manufacturers bring broad formulation expertise, GMP and pharmaceutical‑grade offerings, and deep customer relationships; regional manufacturers provide agility on cost and localized supply. Key commercial archetypes and implications are:
-
Large specialty players (example archetypes include established multinational suppliers): strength lies in registered cosmetic grades, global distribution, and formulation support services. These players will continue to compete on technical service, integrated product systems (emulsifier blends), and sustainability certifications.
-
Mid‑tier European and Asian suppliers: these firms often compete on customization and shorter lead times; for 2026 we expect consolidation pressure as global brands seek harmonized specifications and single‑source procurement efficiency.
-
Cost‑competitive regional suppliers (notably in high‑capacity manufacturing hubs): their relevance increases as formulators seek to optimize blended sourcing strategies, but quality assurance and regulatory documentation will determine market access.
Recent industry moves underscore these dynamics. A 2025 scientific opinion maintained the established safety profile for a key sorbitan derivative in adjacent applications—this preserves regulatory continuity for cosmetic formulators. Separately, ingredient launches showcased at industry forums highlight the ongoing pivot toward natural‑aligned and wellness‑oriented emulsifier systems; such product innovation drives cross‑category demand for sorbitan esters as co‑emulsifiers and stabilizers.
Strategic playbook: recommended actions for stakeholders in 2026
-
For ingredient producers: invest in formulation support and supply‑chain transparency. Differentiate through certified purity grades, documented supply chains, and customer co‑development services to defend margins against commoditization.
-
For brand owners and formulators: adopt multimodal sourcing and lock in dual suppliers for critical grades. Use our scenario model to stress‑test formulations against feedstock cost swings and regulatory shifts.
-
For distributors and traders: build value‑added services (regulatory paperwork, shelf‑life testing, bespoke blending) to capture spreads as raw material arbitrage compresses.
-
For M&A investors: prioritize targets with documented quality systems, long‑term supply agreements with blue‑chip cosmetics customers, and proprietary formulations that enhance integration value.
-
Cross‑industry resilience: implement an ingredient governance framework that maps raw‑material origin to finished‑product claims to withstand heightened scrutiny on traceability and safety.
How clients are using this report operationally
-
Procurement teams are running cost‑of‑goods scenarios to decide whether to forward‑buy certain grades or expand regional warehousing capacity.
-
R&D and product teams are leveraging the formulation matrix to substitute blending ratios and reduce reliance on single‑source co‑emulsifiers without sacrificing stability or sensory attributes.
-
Corporate development groups use our competitive scorecards and deal models to screen acquisition targets and to calibrate earnouts tied to supply continuity and revenue retention.
Next steps — obtain the full intelligence
The public briefing above is designed as a strategic “trailer”: it demonstrates the depth and practical orientation of our analysis while withholding core segmented matrices and precise regional and application breakdowns that are central to transaction and sourcing decisions. The full PW Consulting report includes those proprietary segmentations, supplier scorecards with audited documentation status, and a live financial model you can adapt to your specific assumptions.
To access the complete market study and the interactive tools that translate insights into 2026 actions, visit the PW Consulting report page or contact our advisory team to schedule a tailored briefing. For clients who require immediate implementation support, we also offer a facilitated 48‑hour workshop to convert the report’s scenarios into a one‑page operational plan.
PW Consulting — helping chemical and personal‑care leaders convert market intelligence into defensible, executable strategy for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Cosmetic Grade Sorbitan Esters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyurethane Adhesive for Shoes Market to Reach USD 2,672.73 Million by 2032 at 5.85% CAGR; Asia Pacific Dominates with USD 1,025.57 Million
By pmarketresearch, 2026-07-01
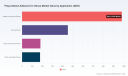
Polyurethane Adhesive For Shoes Market — Strategic Outlook for 2026
As global footwear manufacturers recalibrate post-pandemic supply chains and accelerate sustainability roadmaps, polyurethane (PU) adhesives have become a strategic input rather than a commoditized purchase. PW Consulting’s latest market study — released with a strong forecast horizon — positions senior leaders to make fact-based decisions in 2026 that protect margins, de-risk supply, and capture share in higher-value segments of the footwear value chain.
Polyurethane Adhesive For Shoes Market
High-level market context
Our analysis shows the market expanding steadily from the early 2020s into the mid-2020s: the industry moved from an approximate market base in 2020 to roughly USD 1.8 billion in 2025. Under our base-case assumptions, the polyurethane adhesive for shoes market is projected to grow at a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast window, reaching a multi-billion-dollar opportunity by 2032. Market concentration is material: the top three suppliers account for a meaningful share of industry revenues and the top five control just over half of the market, creating both competitive pressure and consolidation opportunity for mid-market players and innovators.
Polyurethane Adhesive For Shoes Market
Why this report matters for 2026 decisions
-
Procurement and margin protection: With feedstock volatility (notably MDI/TDI prices tied to crude oil) and recent tariff changes affecting landed costs, procurement strategy is now a core margin lever. The report provides procurement scenarios and contract structures tailored to footwear adhesive formulations.
Polyurethane Adhesive For Shoes Market -
Product and process roadmap: Environmental regulations—REACH and regional Green Deal-style frameworks—are accelerating the shift away from solvent-based chemistries. Manufacturers must prioritise technology choices (waterborne PU, hot-melt PUR, bio-based polyols) that meet both regulatory and brand sustainability requirements without sacrificing performance.
-
Supply chain resilience: Tariff adjustments and regional manufacturing incentives are altering landed-cost calculus. The study equips executives to decide on near-shore vs. global sourcing, inventory hedging, and strategic supplier partnerships.
-
M&A and partnerships: Given the moderate-to-high concentration in the market, acquisitive moves or co-development partnerships can accelerate access to differentiated chemistries and customer contracts. The study identifies capability gaps where targeted M&A can create outsized returns.
What’s included — practical, decision-ready deliverables
This report was designed for operators and executives who need executable guidance, not academic summaries. Key operational components include:
-
Five strategic playbooks: procurement hedging, formulation migration (solvent → waterborne/PUR), manufacturing conversion (adhesive application and curing optimization), sustainability compliance, and channel go-to-market for adhesive formulators.
-
Supplier scorecards and heat maps capturing technology readiness, scale, geographic footprint, and commercial terms—built to accelerate vendor selection and pilot programs.
-
Scenario modelling with sensitivity to raw material swings (MDI/TDI), tariff shocks, and accelerated regulatory timelines—allowing finance and strategy teams to stress-test capex and pricing strategies.
-
A regulatory impact matrix mapping REACH/Green Deal-related timelines to formulation decisions, enabling product managers to prioritize reformulation efforts that will be most material to brand customers.
-
Commercial benchmarks and pricing guidance in USD (per market unit and aggregated revenue scale), plus suggested margin-preserving contract structures for long lead-time raw materials.
-
Implementation timelines and cost-to-convert estimates for switching application technology (for example, moving to polyurethane hot-melt systems to reduce steps and energy usage in athletic shoe lines).
Competitive landscape — what leading suppliers are doing
The market is populated by a mix of global chemical majors, specialized formulators, and regional innovators. Public and private players have distinct playbooks:
-
Global adhesives leaders are commercializing polyurethane hot-melt (PURHM) and waterborne systems that emphasize reduced production steps, lower energy consumption, and compatibility with multi-material uppers. They are positioning these products directly to major athletic brands and contract manufacturers as labour- and energy-saving solutions.
-
Polymer producers and raw-material suppliers are moving upstream into application-ready dispersions and thermoplastic polyurethane (TPU) powders to capture value beyond commodities. Their strategy centers on tighter integration with formulators and co-development with footwear OEMs.
-
Regional specialists from Asia and Taiwan are competing on hydrolysis-resistant grades and waterborne chemistries, offering rapid local service and certification pathways for regional brand manufacturers.
Recent industry moves underscore these themes: several major players refreshed portfolios for sports shoe bonding and low-VOC formulations in 2024–2025; new thermoplastic TPU lines for solvent-based and hot-melt applications were launched; and bio-based TPU introductions are entering the market palette, signaling a clear premium for lower-carbon options.
Market dynamics and risk factors
-
Raw material volatility: MDI and TDI price swings remain a critical margin risk. Our models show that short-term spikes materially compress formulators’ margins unless procurement and pricing are aligned with indexation or hedging mechanisms.
-
Regulatory pressure: Tightening VOC and hazardous substance limits are accelerating the adoption of water-based dispersions and low-VOC chemistry across major footwear producing regions. Non-compliant suppliers will face restricted access to key customers in Europe and other regulated markets.
-
Tariff and trade policy: Recent changes to tariffs on key polyols and isocyanates have already raised landed costs in some markets. Manufacturers that rely on imported intermediates should re-evaluate total landed cost and consider localizing critical upstream capabilities.
-
Sustainability premium: Brands are increasingly willing to pay for adhesives that demonstrably lower lifecycle emissions or use bio-sourced inputs—creating a differentiated price band for certified formulations.
Strategic imperatives for 2026 — recommended actions
-
Lock in multi-year feedstock agreements with protective clauses. Combine volume commitments with indexation and force majeure provisions to stabilize unit costs without forfeiting upside flexibility.
-
Prioritise migration pathways to water-based dispersions and bio-based polyols for product lines that supply regulated markets or sustainability-focused brands. Use pilot programs with tier-1 brands to accelerate adoption and share reformulation risk.
-
Invest selectively in hot-melt PUR capability where labour reduction and energy efficiency deliver short payback; quantify the operational savings across targeted production lines before committing to wholesale conversion.
-
Evaluate M&A or JV opportunities to acquire localized capacity for critical intermediates or proprietary PU grades. Given market concentration dynamics, disciplined inorganic moves can be accretive to both margin and time-to-market.
-
Establish a regulatory early-warning system and a reformulation playbook tied to compliance milestones—this reduces surprise capital requirements and protects customer contracts.
PW Consulting’s role and how to use this study
Our report is built to be operational: it includes executable templates, supplier selection matrices, and a worked example of a 24-month migration plan from solvent-based adhesive to a low-VOC, waterborne system in a mass-production footwear line. We combine primary interviews with formulators, manufacturers, and brand procurement leads, plus proprietary pricing and concentration analysis that highlights competitive opportunities without disclosing commercially sensitive split data in this release.
For leadership teams planning 2026 budgets, the study serves three immediate uses: (1) aligning R&D and procurement spend with the most probable regulatory and raw material scenarios, (2) prioritizing capital expenditure to convert lines with the fastest return on invested capital, and (3) defining partnering or M&A criteria that close capability gaps quickly.
Next steps — where to get the full intelligence
This press summary highlights the strategic framing and operational implications. The full report contains the granular segmentation, supplier-level economics, and downloadable modelling tools required to execute decisions in 2026. To access the complete dataset, scenario models, and supplier scorecards, please visit the PW Consulting report page or contact our advisory team to schedule a briefing tailored to your priorities.
PW Consulting remains available to support implementation— from pilot design and supplier negotiations to CAPEX prioritisation and regulatory compliance programs—enabling manufacturers and formulators to convert market insight into defensible advantage during 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Polyurethane Adhesive For Shoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 3D Weaving Fabrics Market to Hit USD 266.5 Million by 2032
By pmarketresearch, 2026-06-30
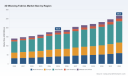
3D Weaving Fabrics Market 2026 Strategic Outlook — PW Consulting Intelligence Brief
As manufacturers, OEMs, and investors prepare strategic plans for 2026, the PW Consulting 3D Weaving Fabrics Market report offers a focused, executable intelligence package to guide high-stakes decisions. Grounded in a 2020–2025 historical dataset and an explicit 2026–2032 forecast horizon, the study quantifies a steady expansion trajectory (5.55% CAGR across the forecast window) and traces the structural forces shaping demand, supply, technology adoption, and regulatory risk. The market reached approximately USD 183.8 Million in our base year (2025) and is projected to grow to roughly USD 266.5 Million by 2032 — a profile consistent with a maturing, innovation-led materials subsector that is becoming mission-critical across mobility, protective, and performance applications.
3D Weaving Fabrics Market
Why this report matters for 2026 decision cycles
- Capital allocation: validates near- and medium-term ROI expectations for capacity expansion, machine investment, and automation projects against a credible CAGR and scenario set.
- Supply chain strategy: informs raw material contracting (notably carbon fiber and engineered polymers), geographic sourcing, and inventory hedging in light of regulatory and export-control dynamics.
- Product and technology roadmaps: helps prioritize R&D bets (near-net shaping, integrated reinforcements, hybrid knit-weave hybrids) by mapping technology readiness to addressable end markets.
- M&A and partnerships: identifies strategic windows for bolt-on acquisitions and co-development agreements where market concentration and capability gaps align with corporate objectives.
What PW Consulting’s 3D Weaving Fabrics Market report contains
- Full historical time series (2020–2025) and a granular forecast model (2026–2032) — inclusive of base-case, upside, and downside scenarios.
- Demand-side segmentation by geography, fabric architecture, and end-use application, with trend narratives and market sizing at the aggregate level. (Note: the press summary intentionally omits granular segment-level figures to preserve the report’s data value.)
- Comprehensive supply-side mapping: manufacturers, machine vendors, converter networks, and component suppliers, with capacity maps and utilization stress tests.
- Technology assessment and TRL-style positioning for 3D weaving variants, spacers, and hybrid constructions, including manufacturability and scale-up risk matrices.
- Raw-material and price sensitivity analysis, supplier risk indices, and contract negotiation playbooks for carbon fiber and specialty polymer inputs.
- Regulatory, standards, and trade policy impact assessment — with country-level implementation scenarios and compliance mitigation strategies.
- Competitive benchmarking: revenue-agnostic capability profiles, commercialization roadmaps, and potential M&A candidate scoring.
- Executive 90/180/365-day action plans tailored to buyers, suppliers, and investors.
Data-driven strategic takeaways for 2026
Growth will be steady rather than meteoric. The mid-single-digit CAGR we model reflects expanding use of 3D woven architectures where performance and integration advantages justify premium pricing — notably in structural composites, protective systems, and integrated apparel. That said, growth will be uneven by application and region as OEM adoption, regulatory shifts, and raw-material dynamics reorient supplier economics.
3D Weaving Fabrics Market
- Demand katalysts: system-level benefits (weight reduction, through-thickness reinforcement, fewer secondary bonding steps) are accelerating adoption in composites-heavy segments. Expect sustained traction in automotive lightweighting, performance sports equipment, and industrial protective gear, with new use-cases emerging around multifunctional wearables and protective apparel.
- Supply and concentration: market concentration remains modest — our concentration metrics point to a fragmented supplier base with room for consolidation. This creates arbitrage for strategic acquirers and risks for firms that rely on a narrow supplier set.
- Raw-material posture: carbon-fiber pricing has shown relative stability into 2025–2026 at key grades, but supply and lead-time volatility persists for specialty formulations. Buyers should adopt staged volume commitments and explore material substitution pathways where technical requirements permit.
- Regulatory and trade friction: recent policy moves — such as India’s expanded certification requirements for weaving equipment and updates to the U.S. Commerce Control List classifying multidirectional weaving machines — materially affect where capital can be deployed, what equipment can be imported, and how IP-protected machine architectures are traded. These constraints argue for diversified manufacturing footprints, local partnership arrangements, and proactive compliance planning.
Competitive landscape: reading the players and their strategic plays
The ecosystem is populated by specialized innovators, regional champions, and converters who combine design know-how with composite systems integration. Key strategic archetypes observed include pure-play technology licensors, vertically integrated producers, converter-specialists, and machine vendors enabling on-site capability expansion.
3D Weaving Fabrics Market
- Technology-first developers — firms like the Belgium-based developer known for its 3D weaving technology are positioned as technology originators targeting composites and technical-application niches. For alliances, these players are attractive R&D and OEM partners.
- Performance-material specialists — manufacturers from East Asia producing engineered 3D carbon, fiberglass, and UHMWPE constructions address ballistic, industrial, and hybrid-composite markets. Their strengths are cost-competitive scale and engineered fiber expertise; their strategic moves typically emphasize vertical integration and export-led growth.
- Converter and composite systems players — industry converters focused on carbon-fibre 3D textiles serve aerospace, wind, marine, and automotive customers. These firms compete on end-to-end qualification capability and supply security rather than raw price alone.
- Innovative knitted/woven hybrid players — companies introducing knitted 3D solutions (including spacer and seamless functional platforms) are pushing into apparel and protective gear, leveraging textile design to embed functionality (reinforcements, pockets, thermal control) without heavy secondary assembly.
- Regional production specialists — midsized firms with adjacent capabilities (spacer fabrics, woven composites) serve local OEM clusters. They are preferred partners for localized programs and rapid prototyping.
Recent industry moves provide a window into strategic direction. Notable examples include the commercial introduction of a 3D weaving platform enabling seamless performance apparel with integrated reinforcements, trade-show-led product demonstrations of film-infused near-net shapes and thermal protection systems, and machine vendors showcasing 3D weaving capability at regional technical textile shows. These signals emphasize two persistent themes: (1) manufacturers are prioritizing manufacturable integration (near-net shaping, in-line joining) and (2) visibility at technical venues is being used to accelerate OEM qualification cycles.
Regulatory and operational risk matrix
- Machine and technology export controls: the classification of multidirectional, multidimensional weaving machines under expanded export control regimes increases the complexity of cross-border equipment procurement and licensed manufacturing relationships. This elevates the value of domestic machine capability and local partnerships in sensitive jurisdictions.
- Standards and certification: new certification regimes for weaving and embroidery machinery in select markets introduce lead-time and documentation burdens for equipment OEMs and end users — companies will need to front-load compliance tasks into 2026 CAPEX planning.
- Input volatility: while average selling prices for chosen carbon-fibre grades have been stable, supply concentration for high-modulus and specialty grades can create tight windows for qualification-linked sourcing; strategic stocks or multi-sourcing agreements mitigate production risk.
Practical 90/180/365-day playbook for executives
- Next 90 days — perform a rapid supply-security audit (raw materials + machine vendors), initiate compliance reviews for anticipated export or import constraints, and launch two pilot co-development tests with candidate 3D weaving partners to validate performance claims and lead times.
- Next 180 days — commit to at least one scaling path: either secure long-lead time equipment with staged commissioning, or finalize a localized contract manufacturing agreement. Begin formal due diligence on acquisition targets that close capability gaps (converter capacity, machine know-how, or regional presence).
- Next 365 days — operationalize a productization pipeline for 3D-woven-enabled offerings (from design to qualification), lock multi-year strategic supply contracts with tiered pricing, and roll out a blended sourcing strategy that hedges both material and regulatory risk.
How PW Consulting’s report unlocks value
This report is designed as an execution toolkit: not only does it provide verified historical and forecasted market sizing (2020–2032) and a clear CAGR for planning, it maps the practical levers that move margin and time-to-market. For corporate strategists, procurement leads, and private-equity teams, the intelligence enables confident allocation of capital and prioritization of integration vs. partnership models — while preserving flexibility around equipment strategy and IP exposure.
Next steps
PW Consulting’s full report contains the proprietary segment-level breakdowns, detailed company capability matrices, supplier scorecards, and interactive forecasting models that executives need to finalize 2026 plans. The summary above intentionally omits those granular figures to preserve the actionable intelligence contained in the full deliverable. For access to the complete dataset, scenario workbooks, and bespoke advisory engagements tailored to your portfolio or operations, please visit our report page or contact PW Consulting’s advisory desk to arrange a briefing and data license.
For detailed analysis of this topic, please visit the official page: 3D Weaving Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fishmeal & Fish Oil Market Poised for a 6.53% CAGR During 2026–2032
By pmarketresearch, 2026-06-30
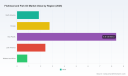
Fishmeal and Fish Oil Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
PW Consulting’s latest Fishmeal and Fish Oil Market report (base year 2025, forecast 2026–2032) delivers a compact, actionable intelligence package designed to inform high-stakes commercial and policy decisions through 2026. The market’s macro trajectory is unequivocal: after a steady recovery through the early 2020s our modelling shows the market expanding from roughly USD 12.4 Billion in 2020 to USD 16.3 Billion in 2025, and continuing at a compound annual growth rate (CAGR) of 6.53% to reach approximately USD 25.3 Billion by 2032. These headline dynamics create both immediate risks and multi-year opportunities for producers, feed companies, traders, and strategic investors.
Fishmeal and Fish Oil Market
Why this report matters for 2026 decision-making
- Timing of exposure to supply shocks: The industry is entering 2026 with pronounced supply-side uncertainty. Recent quota adjustments and early-year production declines have already tightened raw material availability. Executives need a prioritized, near-term playbook to manage procurement, pricing, and customer commitments.
- Structural growth with pockets of premiumisation: Long-term demand drivers — aquaculture expansion, pet nutrition upgrades, and human-grade omega-3 applications — underpin the forecast CAGR and justify selective capacity and capability investments. However, the path to value increasingly favors processors that can deliver certified, traceable, and refined product streams.
- Sustainability and data-driven differentiation: Environmental benchmarking and certifications are shifting from “nice-to-have” to commercial requirements in many global feed and nutrition value chains. Companies that demonstrate verified life-cycle performance will access premium channels and lower market friction.
- Consolidation pressure and strategic positioning: Market concentration metrics show a moderately fragmented landscape with meaningful room for M&A and alliances—opportunities that can materially alter regional supply footprints if executed effectively in 2026–2027.
What’s inside the report (Practical, operational components)
- Market sizing and forecast model (2020–2032) with scenario variants reflecting quota and stock recovery scenarios, plus sensitivity analyses tied to raw material availability and energy costs.
- Price volatility framework and a procurement heatmap that prioritizes actions by risk exposure and contract flexibility.
- Supply-chain risk register and mitigation playbook, including upstream sourcing alternatives, logistics contingency plans, and a checklist for short-term offtake negotiations.
- Sustainability benchmarking toolkit: how to operationalize Life Cycle Assessment (LCA) data, accelerate MarinTrust and equivalent certifications, and convert environmental credentials into commercial terms.
- Commercial playbooks for value-added products (concentrates, refined oils) that map product specs to buyer segments and margin profiles.
- Competitive landscaping with executive profiles, recent strategic moves, and an M&A opportunity matrix tailored to different acquisition budgets.
- Regulatory scenario planning: modelling outcomes of quota changes, trade measures, and certification uptake on supply/demand balances.
- Investor brief: ROIC and payback scenarios for select capex options — decarbonization retrofits, hydrolysis/upgrading lines, and downstream purification capacity.
Industry dynamics and near-term flashpoints
The sector is operating under three overlapping dynamics that will shape corporate outcomes through 2026.
Fishmeal and Fish Oil Market
- Acute supply-side tightening: Policy shifts and quota changes in major sourcing jurisdictions have reduced available raw material in early 2026, contributing to lower global output in the first quarter versus the prior year. For buyers and traders this translates into elevated spot volatility and an increased premium on secure, certified supply chains.
- Acceleration of sustainability credentialing: Leading processors are investing not just in certifications but in data transparency—registering branded LCA datasets and extending third-party certificates to preserve market access. These investments are already influencing commercial negotiations and will become de facto entry requirements in premium channels.
- Upgrading and product differentiation: Technical routes such as enzymatic concentration and molecular distillation are enabling processors to move up the value chain, selling high-purity oils and protein concentrates into pharmaceutical, aquafeed, and human nutrition segments. This is reshaping where margin pools will be found over the medium term.
Competitive landscape — who to watch
The market contains a set of established, globally-active processors and traders that together shape trading flows and certification norms. Our report provides strategic profiles of each, assessing capacity types, technical capabilities, certification status, and recent strategic moves that matter to buyers and partners.
Fishmeal and Fish Oil Market
- TASA (Lima, Peru): Continuous investments in fuel switching and processing upgrades signal a dual strategy — reduce operating costs and upgrade product quality. Recent plant conversions to cleaner fuel sources and hydrolysis investments underscore this push.
- Omega Protein Corporation (Reedville, Virginia, USA): As a primary regional processor, Omega Protein remains central to North American supply chain dynamics, especially for menhaden-derived products used across feed and supplement markets.
- TripleNine Group A/S and FF Skagen A/S (Denmark): European players that combine high-purity processing technologies with broad export networks — well-positioned to capture pharmaceutical and premium aquafeed demand.
- Pelagia AS (Norway): Focused on pelagic species and on-the-ground value-add, Pelagia’s product mix targets both animal feed and higher-margin protein concentrates.
- Austral Group S.A.A., Pesquera Diamante S.A., Pesquera Exalmar S.A.A., Colpex, and other Peruvian processors: Collectively influential on global raw-material availability. Recent milestones include LCA registration in branded databases and MarinTrust certification renewals — actions that materially affect buyer acceptance in international markets.
- Corpesca and Scoular Company: From global output to diversified trading, their activities influence logistics flows and pricing corridors for key buyer geographies.
Our concentration analysis highlights a market where top producers do not yet dominate to the point of being insurmountable — presenting strategic openings for well-funded entrants, alliances, or roll-up strategies that can accelerate market share shifts over a 24–36 month horizon.
Actionable recommendations for 2026
To convert the report’s insights into near-term advantage, PW Consulting recommends a set of prioritized actions for different executive roles.
- Procurement & Trading (0–90 days): Secure multi-sourced offtake agreements with staggered delivery windows, introduce flexible pricing collars, and build contingency inventory where margin economics permit. Short-term supply is likely to remain tight; liquidity-ready buyers will access incremental volumes.
- Operations & Capex (90–360 days): Fast-track energy transition projects (e.g., fuel switching) and modular upgrading lines (hydrolysis, fractionation) to capture premium demand. Prioritize retrofit capex that shortens time-to-market for higher-value concentrates.
- Commercial & Sustainability (6–12 months): Invest in LCA data collection and third-party certification. Build differentiated product specifications (e.g., certified traceable oils) and align sales teams to sell sustainability as a feature with premium pricing potential.
- M&A & Strategy (12–36 months): Target bolt-on acquisitions that broaden species input, geographic coverage, or add downstream refining capabilities. Use acquisitive moves to secure feedstock or vertically integrate into refinement and branded nutrition channels.
- Policy & Stakeholder Engagement: Proactively engage with regulators and regional fisheries authorities to anticipate quota scenarios and to advocate for predictable management frameworks that reduce price volatility and supply-side shocks.
What we are deliberately withholding — and why
To preserve the report’s commercial value as a decision-making tool, this public summary highlights strategic conclusions and operational recommendations while withholding detailed regional and application-level breakdowns, granular price curves, and full company revenue splits. These granular datasets and interactive models are included in the full PW Consulting report and are essential for transaction-grade due diligence, procurement re-negotiations, and capital planning.
Next steps: how to use this intelligence
- Request the full report to access the interactive forecast model, downloadable LCA templates, and company valuation ranges.
- Commission a tailored workshop with our team to convert the playbook recommendations into a 90-day execution plan aligned to your cost structure and market exposure.
- Engage our M&A advisory to review acquisition targets prioritized in our opportunity matrix and to run accelerated due diligence on certification liabilities and supply contracts.
PW Consulting’s Fishmeal and Fish Oil Market report is calibrated to drive decisions in an environment where near-term scarcity and long-term structural growth coexist. For executives who must make procurement, capital, or M&A choices in 2026, the report offers the scenario tools, competitive intelligence, and operational playbooks needed to convert volatility into advantage. Reach out to request the full dataset and to schedule a briefing with our senior industry team.
For detailed analysis of this topic, please visit the official page: Fishmeal and Fish Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tequila Market Poised for a Robust 8.97% CAGR Through 2032
By pmarketresearch, 2026-06-30
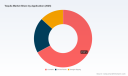
Tequila Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Study
PW Consulting’s latest Tequila Market research — anchored on a 2025 base year and projecting through 2032 — offers a focused, decision-grade view for corporations shaping 2026 strategies. Built on five years of historical granularity (2020–2025) and driven by proprietary scenario modeling, the study captures why tequila is no longer a niche spirits story but a structurally expanding beverage category. The headline: global market momentum remains robust, with an almost 9% compound annual growth rate (CAGR) underpinning a near-term climb from a 2025 baseline into a materially larger market by 2032. This briefing summarizes the strategic takeaways, competitive dynamics, supply-chain tensions and regulatory shifts that will matter most to executives in 2026 — while reserving the report’s full, actionable tables and segment-level forecasts for authorized subscribers.
Tequila Market
Why this report matters for 2026 decision-making
Senior leaders face three converging dynamics in 2026: accelerating consumer premiumization, an increasingly global trade environment, and structural input volatility tied to agave supply. Our research quantifies the market’s scale and trajectory across the forecast window and combines that macro view with scenario-driven business implications. For commercial leaders, this means the difference between tactical reactions (inventory buffering, spot buying) and strategic positioning (portfolio rebalancing, targeted market diversification, and supply-chain integration). The report provides the evidence base to prioritize capital allocation, M&A screening, and channel strategies for the coming 12–24 months.
Tequila Market
What the PW Consulting report contains (practical, implementable elements)
- Proprietary market-size model with historical validation (2020–2025) and a seven-year forecast (2026–2032) showing the baseline expansion path and upside/downside scenarios.
- Consolidation and concentration analysis highlighting market share dispersion among the largest producers and what that implies for pricing power and distribution leverage.
- Supply-chain risk mapping that integrates agave-production cycles, certification adoption, and labor/sustainability pressures — translated into procurement playbooks.
- Regulatory and trade scenarios — including tariff shocks and origin-recognition shifts — with decision trees for market-entry and pricing responses.
- Commercial playbooks by go-to-market channel (on-premise, off-premise, e-commerce, duty-free) and consumer occasion (cocktails, on-the-rocks, sipping), including SKU and price-tier strategies.
- M&A and partnership screening templates: valuation sensitivity matrices, synergy capture checklists, and post-deal integration risk heatmaps.
- Executive dashboards and downloadable appendices with granular forecasts, proprietary assumptions, and a library of primary-source citations.
Market trajectory and headline metrics
Our baseline projection — based on validated historical data and current market signals — shows the global tequila market expanding at an approximate 8.97% CAGR over the forecast horizon. From the 2025 base, the market is projected to grow significantly by 2032 under the baseline scenario, with alternative scenarios provided for faster premiumization or deeper trade disruption. The pace of expansion is driven by persistent consumer demand in established markets coupled with faster growth in newer geographies and premium segments.
Tequila Market
Concentration analysis reveals a moderately consolidated competitive set: the top-three and top-five players account for a significant portion of the market, creating both barriers for smaller independent brands and structural opportunities for scale-driven network effects in distribution and global marketing. The report’s competitive scorecards translate these concentration metrics into practical implications for pricing elasticity and channel negotiation power.
Competitive landscape: who matters and why
The Tequila Market’s competitive fabric combines legacy houses, multinational beverage groups, and artisan producers. Key company profiles included in the report dissect commercial models, brand architectures, and international strategies. Examples covered include:
- Jose Cuervo S.A. de C.V. — mass-market reach with a mix of 100% agave and mixto portfolios and broad export footprints.
- Patrón S.A. de C.V. — premium positioning with a focus on high-quality blanco, reposado and añejo expressions and luxury channel tactics.
- Don Julio (Diageo) — ultra-premium expressions and heritage-led branding driving high-margin opportunities.
- Casa 1800 / 1800 Tequila — premium reposado and añejo lines with global distribution strengths.
- El Jimador (Brown-Forman), Sauza (Constellation Brands), Casamigos (Diageo), Espolòn, Hornitos and other notable producers — each analyzed for portfolio segmentation, channel mix and international expansion strategies.
For each name, the report offers a succinct strategic read: competitive advantages, margin levers, distribution risks, and likely M&A or brand-extension behavior in 2026. That perspective is essential for partners, suppliers and potential acquirers assessing alignment or competitive threats.
Supply chain and raw-material dynamics
Tequila’s supply equation is uniquely tied to blue agave cycles. Our analysis incorporates recent production figures and price signaling: in the prior cycle, global tequila output and associated agave harvests led to a temporary oversupply, depressing spot prices and creating short-term cost relief. At the same time, the adoption of social and sustainability certifications among agave growers accelerated, reflecting industry-level pressure to formalize labor standards and traceability. These dynamics produce a two-fold strategic imperative for 2026: optimize procurement to capture lower-cost windows while securing certified, traceable supply for premium and regulated channels.
Practically, this means prioritizing long-term supply contracts, forward pricing instruments and direct investment in agave agriculture where scale allows. The report’s procurement playbook provides contract templates, hedging approaches and an ROI framework for vertical integration decisions.
Regulatory and trade environment — immediate risks and medium-term shifts
Trade policy proved a central disruptor in 2025 and into 2026. A tariff imposition in a major export market materially affected competitiveness and prompted diversification moves. Concurrently, new international recognition acts that protect designation of origin — including recent accession by an influential Gulf market — strengthen the global legal architecture that supports premium positioning for origin-authenticated products.
For companies active in 2026, the key questions are how to price through tariffs, where to pivot distribution, and how to leverage designation protections to defend premium SKUs. The report offers scenario-tested strategies: temporary market hedging, accelerated shelf-space buys in unaffected markets, and brand messaging that emphasizes origin-authenticated quality to preserve margin under tariff pressure.
Strategic implications and recommended actions for 2026
Our analysis points to five immediate strategic priorities for corporate leaders:
- Rebalance portfolios toward resilience: accelerate premium lines with strong provenance narratives while maintaining flexible value offerings in price-sensitive channels.
- Lock in supply and certify traceability: pursue medium-term contracts with certified growers, and where feasible, pursue equity stakes in agave production to stabilize input costs.
- Deploy a market-diversification playbook: prioritize growth in markets with favorable trade conditions and invest in digital channels to offset on-premise volatility.
- Use competitive position to capture distribution economics: scale players should negotiate exclusivity and promotional economics in key retail and travel-retail nodes.
- Stress-test pricing and promotional plans against tariff and currency stress scenarios: adopt dynamic pricing frameworks to maintain margin under different trade outcomes.
Each recommendation in the full report is accompanied by an implementation checklist, expected P&L impact ranges and a timeline aligned to 2026 planning cycles.
How PW Consulting supports implementation
Beyond the research, PW Consulting offers a suite of advisory services to operationalize the findings: strategy workshops, M&A diligence and target screens, supply-chain reengineering programs, procurement negotiation support, and consumer segmentation analysis tailored to spirits and luxury beverages. Our deliverables are calibrated to board-level decision timelines and to the operational tempo that beverage companies require ahead of a fiscal-year planning cycle.
Closing: a strategic invitation
Tequila is at an inflection point where premium demand, trade policy and agricultural cycles will shape winners and losers in 2026. PW Consulting’s Tequila Market study distills complex dynamics into executable intelligence for boards, commercial leaders and investors. The public summary above offers the strategic frame; the full report contains the models, segment-level forecasts, and operational templates your team will need to translate intent into outcomes.
Contact PW Consulting to request the full report, licensing terms, or to book a strat-off workshop with our lead industry analysts. Our advisory teams are prepared to convert the report’s insights into a 90-day action plan aligned to your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Tequila Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Scandium Metal Market Set to Expand at 8.55% CAGR, Reaching USD 93.29 Million by 2032
By pmarketresearch, 2026-06-30
Scandium Metal Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
As strategic planners and procurement leaders prepare budgets, capital decisions, and industrial partnerships for 2026, PW Consulting’s latest Scandium Metal Market report offers a focused, decision-centric view of an emergent specialty metals market. Our analysis combines a clarified demand forecast, supply‑side capacity mapping, and an executable playbook for near‑term action — providing exactly the strategic inputs executives need without revealing proprietary segment-level detail that must be validated on purchase.
Scandium Metal Market
Why scandium matters now — and next
Scandium has moved from a laboratory curiosity to a strategic component in a short list of high-value industrial pathways: high-performance aluminum alloys, solid‑oxide fuel cells (SOFCs), optical lasers, and specialty lighting among them. This transition is reflected in the market’s structural trajectory: from an estimated global market value of USD 52.0 Million in the base year (2025), the market is modeled to grow at a compound annual growth rate (CAGR) of 8.55% during our forecast window, reaching an anticipated USD 93.29 Million by 2032. That growth profile is not linear — it is punctuated by discrete capacity ramps, policy interventions, and technology adoption events that will create asymmetric value opportunities for early movers.
Scandium Metal Market
What distinguishes our report (practical, executable deliverables)
- Proprietary supply‑demand engine: A modular forecast tool calibrated to historical 2020–2025 market signals and 2026–2032 scenario variants. The engine supports scenario queries (policy shock, rapid SOFC uptake, alloy substitution) and produces outputs useful for CAPEX timing and procurement hedging.
- Supply pathway mapping: A geospatial view of primary and secondary feedstock sources (including industrial waste streams), commercial‑scale production assets, and announced expansions — annotated with commissioning timelines, technology readiness scores, and upstream permit/risk flags.
- Commercial pricing and cost‑curve sensibilities: Forward price bands under three adoption scenarios and an enterprise‑grade cost sensitivity matrix that shows where margins go under different feedstock and recovery‑efficiency assumptions.
- Supplier due diligence pack: Standardized scorecards for incumbent and emerging suppliers (technical capability, capacity optionality, counterparty risk, sourcing footprint) plus red‑flag checklists for supply contracts.
- M&A and JV playbook: Transaction triggers, valuation traffic lights, integration pitfalls (notably for operations relying on low‑grade secondary feedstocks), and model term sheets for offtake and tolling arrangements.
- Regulatory & defense procurement tracker: A living appendix summarizing recent government actions, grant programs, and defense offtake that materially affect supply security and investment risk.
Key market dynamics shaping 2026 decision-making
- Constrained, concentrated supply: A handful of established producers and vertically integrated accounts continue to dominate global supply. Market concentration leaves buyers exposed to sourcing disruptions during capacity transitions and geopolitical stressors.
- Secondary feedstocks gaining strategic importance: Recovery from industrial residues — notably oxide and red‑mud streams from TiO2 and aluminum processing — is moving from pilot to commercial reality at several operators. That pathway materially improves feedstock optionality but introduces variability in impurity profiles and processing cost.
- Policy and defense demand: North American defense procurement and near‑shoring initiatives are creating premium sub‑markets for certified, traceable supply. Public procurement commitments can accelerate commercialization and justify near‑term capacity expansions.
- Project cadence matters: A small number of announced expansions and greenfield projects will determine market tightness in the next 12–36 months. The timing of commissioning events is therefore a primary driver of short‑term price volatility and long‑term investment returns.
Competitive landscape — who matters and why
Our competitive assessment focuses on companies that currently shape commercial availability and investment sentiment.
Scandium Metal Market
- Rio Tinto — A commercial producer with industrialized recovery routes from TiO2 waste streams. Recent strategic moves include a financing/expansion transaction intended to raise output at its Quebec operation, reflecting a deliberate push to secure near‑market defense and specialty industrial demand.
- Scandium International Mining Corp. — Developer-stage asset owner advancing a primary scandium mine in New South Wales. A recent mining lease milestone materially improves project maturity and the potential for primary scandium to enter the market as a dedicated supply stream.
- RUSAL — A legacy aluminum giant that supplies scandium as a strategic byproduct from integrated aluminum operations. Its global footprint and refining scale make it a pivotal supplier for large offtake arrangements.
- China‑based producers and suppliers — Several mid‑to-large scale operations supply a broad range of scandium products, from metal forms to high‑purity oxides, often competing on scale and price; their strategic posture affects global price floors and inventory flows.
- Specialty suppliers — Smaller niche manufacturers and material houses provide high‑purity products for research and industrial application scaling. Their agility is critical for early adopter applications where tight impurity controls matter more than price.
Recent, verifiable developments that alter near‑term strategy include capacity expansion announcements at commercial producers and new mining lease approvals for primary projects. At the same time, public‑sector funding for recovery technologies and defense procurement commitments are creating alternative demand anchors that change risk calculus for investors and offtakers alike.
How to use the report to inform 2026 choices
Executives asking "what do we need to decide in 2026?" will find three immediate use cases:
- Procurement and contract structuring: Use our supplier scorecards and contract templates to lock in staggered offtake with embedded flexibility (tolling, quality‑differentiated pricing, and volume ramp clauses). This reduces exposure to short‑term supply shocks while preserving upside participation if prices soften as new capacity comes online.
- Capital allocation and timing: Investors and industrials can apply the scenario outputs to gate CAPEX — distinguishing between projects that require de‑risking via offtake versus those that can be justified on merchant price exposure. Our models highlight the inflection points where private investment becomes commercially viable.
- Strategic partnerships and vertical strategies: For OEMs and alloy manufacturers, forming upstream partnerships (with producers, waste‑stream owners, or toll processors) is, in many cases, the most efficient route to secure consistent specification materials while avoiding raw material price contagion.
Risk register and mitigation playbook
Key risks include feedstock supply volatility, regulatory shifts, and product specification heterogeneity. Our report presents a prioritized risk register and a set of mitigation templates, such as dynamic inventory policies keyed to commissioning dates, multi‑sourcing mandates for critical components, and switchable process designs that tolerate feedstock impurity variance.
Actionable takeaways for different stakeholders
- For procurement leaders: Begin structuring multi‑year offtake agreements with optionality clauses today; engage with specialty tollers to build buffer capacity without committing to heavy upstream capital.
- For investors and corporate development teams: Use milestone‑based investments tied to proven recovery yields and offtake commitments; prioritize projects with secondary feedstock optionality and accessible permitting pathways.
- For policy and defense planners: Recognize that strategic procurement commitments (especially in certified, traceable supply programs) substantially reduce investment risk and can accelerate localized supply creation.
Why PW Consulting’s analysis is uniquely fit for 2026 planning
Our approach blends granular operational intelligence with market economics and a practitioner’s playbook. We do not simply forecast; we provide the decision logic that turns forecast outputs into executable strategies: precise supplier diligence forms, CAPEX gating criteria, contract templates optimized for thin markets, and scenario stress‑tests tailored to clients’ risk appetites.
Importantly, the report is intentionally structured as a "preview" here: it demonstrates the methodological rigor and the strategic depth you need to act in 2026, while preserving the core segmentlevel forecasts, supplier scorecards, and model files for authenticated access. Executives who require the complete financial matrices, regional and application breakdowns, and downloadable Excel model can obtain them via the report distribution channel.
Next steps — how to access the full intelligence
If your decisions in 2026 include securing offtake, timing investment, or redesigning product roadmaps around scandium‑enabled materials, we recommend downloading the full Scandium Metal Market report and associated model pack. The full dossier contains the segment‑level forecasts, supplier profiles, and contract exemplars that are essential for detailed implementation. Contact PW Consulting via our website to arrange access and a tailored briefing with our lead analysts.
In a market where a few capacity moves and a single policy decision can reallocate value, clarity and timing matter. Our report delivers both — enabling you to convert market intelligence into defensible, actionable strategy for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Scandium Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insight: L‑Hydroxyproline (CAS 51‑35‑4) Market to Reach USD 384.15 Million by 2032
By pmarketresearch, 2026-06-30
L-Hydroxyproline (CAS 51-35-4) Market — 2026 Strategic Outlook: A PW Consulting Executive Brief
Executive summary
As PW Consulting’s lead industry analyst, I present an executive synthesis of our 2026-ready market intelligence on L-Hydroxyproline. Using 2025 as the base year, the market has demonstrated sustained expansion from an observed USD 186.2 Million in 2020 to USD 250.8 Million in 2025. Our forecast blends historical demand drivers with near-term supply-side developments to project the market growing at a compound annual growth rate (CAGR) of 6.4% across the 2026–2032 horizon, reaching approximately USD 384.15 Million by 2032. These macro trajectories frame a set of actionable decision levers for corporate leaders — from C-suite strategists to procurement heads and R&D directors — who must position for 2026 and beyond.
L-Hydroxyproline (CAS 51-35-4) Market
Why this matters in 2026 — high-conviction implications
-
Demand momentum is durable but heterogeneous. The market’s steady rise reflects a mix of pharmaceutical formulations, personal-care innovation and specialty food/nutraceutical uses. For decision-makers, this means predictable baseline demand combined with pockets of rapid premiumization in high-margin use cases. Planning horizons must therefore balance volume playbooks with selective capability investment in quality and regulatory compliance.
L-Hydroxyproline (CAS 51-35-4) Market -
Supply-side shifts are shaping bargaining power. Recent capacity investments by established Western producers and rapid scaling by Asian manufacturers have created a more elastic global supply curve. Buyers should anticipate episodic pricing pressure and execute diversified sourcing strategies that prioritize quality tiers and lead-time resilience over pure price optimization.
L-Hydroxyproline (CAS 51-35-4) Market -
Technology and process mix are strategic differentiators. Our market mapping shows that microbial fermentation and enzymatic biotransformation together represent the dominant production backbone. Firms that can align procurement and R&D with these processes — whether by co-developing tailored grades or by investing in downstream purification — will capture structural margins.
-
Regulatory and formulation innovation are fast followers. Recent product launches and capacity expansions underscore a two-track evolution: regulatory-grade, traceable supply for pharmaceutical/clinical channels, and application-specific grades for cosmetics and nutraceuticals. Corporate strategies in 2026 must include regulatory readiness and formulation partnerships as core go-to-market enablers.
What the PW Consulting report delivers — practical, decision-ready modules
The full report is designed as a tactical toolkit for 2026 planning cycles. It combines proprietary market-sizing, a robust forecasting engine, supply-chain heatmaps and a stratified competitor playbook. Key, actionable modules include:
-
Comprehensive market model (2020–2032) with scenario sensitivity to raw material shocks, regulatory shifts and demand elasticity assumptions — enabling iterative boardroom “what-if” simulations.
-
Supply-side atlas with supplier tiering, production route matrices and risk scores — built to inform multi-sourcing contracts and buffer-capacity decisions without exposing segment-level commercial terms in this summary.
-
Commercial playbook outlining pricing levers, margin-protection tactics and commercialization checklists for each buyer persona (pharma CPO, cosmetic formulators, nutraceutical brand teams).
-
Regulatory & compliance dossier mapping pathways for pharmaceutical-grade approvals, cosmetic-claim substantiation and food-grade certification — presented as stepwise timelines and CapEx/OpEx sensitivity tables.
-
M&A and partnership framework, including threshold criteria for bolt-on acquisitions, JV structuring options, and synergies matrices that quantify integration value drivers.
Competitive landscape — reading the room in 2026
The competitive topology of L-Hydroxyproline shows a mix of premium, technology-led incumbents and high-scale, cost-oriented manufacturers. Market concentration metrics indicate a moderately consolidated upper tier, leaving space for mid-sized players and specialized entrants to differentiate on quality and service.
-
Kyowa Hakko Bio (Japan) — Positioned at the premium end with fermentation-based, pharma-grade offerings. Their strengths are regulatory-track record, high-purity manufacturing and established clinical supply relationships. For partners seeking reliable quality and traceability, Kyowa Hakko remains a first-choice supplier, though typically at a price premium.
-
Evonik Industries (Germany) — Recent capacity expansion in Europe underscores a strategic move to secure pharmaceutical-grade volumes close to major pharma clusters. Evonik’s play is classic integrated-chemistry plus biotech — emphasizing consistent quality, European regulatory alignment and global distribution. Their expansion has immediate implications for regional supply balance and contract negotiation dynamics.
-
Chinese supply base — A broad set of manufacturers has focused on scale, cost-efficiency and rapid capacity additions. These players serve a wide spectrum of quality tiers from industrial to high-purity grades. Competitive pressure from this cohort is most pronounced on volume contracts and commodity-grade channels, and savvy buyers will extract value by mixing suppliers across quality bands.
-
Specialty and niche producers — Several mid-size firms concentrate on high-purity derivatives and intermediates tailored for research and formulation houses. Their agility in customized specifications and shorter lead times makes them preferred collaborators for innovative product development.
Supply dynamics and production routes — what to watch
Two production paradigms dominate: microbial fermentation and enzymatic biotransformation. These approaches collectively form the backbone of industrial output and account for the majority share of production globally. For purchasing and operations teams, this has three implications:
-
Cost structures are increasingly driven by bioprocess inputs and downstream purification rather than upstream raw-material scarcity alone.
-
Quality differentiation is feasible via tighter bioprocess control and investment in purification train enhancements, enabling producers to command premium pricing for pharmaceutical and high-margin cosmetic grades.
-
Securing intellectual property or co-development agreements around proprietary strains or enzymes can be a durable competitive moat for manufacturers and a supply-stability lever for large buyers.
Regulatory and market signal highlights (recent)
-
Evonik’s 2025 expansion of pharmaceutical-grade capacity in Europe signals supplier intent to be closer to major pharma customers and to shorten qualification cycles — a clear indicator for procurement teams to revisit regional sourcing strategies.
-
New product launches in 2025 from major ingredient houses targeting cosmetic-grade hydroxyproline reflect a trend toward targeted actives in anti-aging formulations. Brands should evaluate co-development opportunities early in the 2026 formulation pipeline.
Market concentration and strategic implications
Concentration metrics show a mid-level aggregation of market share among the largest producers. This structure creates a two-speed market: incumbents can leverage scale to protect margins in regulated, high-entry-barrier channels; meanwhile, medium-sized players can exploit niches through agility and customization. For decision-makers, recommended responses include calibrated M&A screening, targeted supplier partnerships, and differentiated procurement frameworks that align with grade-specific risk profiles.
2026 Strategic playbook — recommended actions
-
Near-term (0–12 months): Lock supply via staggered contracts across quality tiers, prioritize suppliers with demonstrated regulatory compliance for clinical programs, and institute dual-sourcing for critical SKUs.
-
Medium-term (12–36 months): Invest in formulation co-development with selective high-purity suppliers, evaluate toll-manufacturing or partial vertical integration for strategic grades, and pilot bioprocess innovations that lower total cost of ownership.
-
Long-term (36+ months): Pursue targeted acquisitions or JVs to secure technology/IP, expand into adjacent value pools (e.g., specialty amino-acid derivatives), and build predictive procurement analytics tied to the report’s scenario models.
How PW Consulting supports your 2026 decision cycle
Our report is not an academic exercise; it is an executable playbook. Clients receive the full model, supplier heatmaps, contract negotiation checklists, and a prioritized initiative road map calibrated to company size, risk appetite and product mix. The public executive brief intentionally omits granular segmentation disclosures so strategic buyers and investors consult the full dataset for transaction-grade intelligence and detailed regional/application split analytics.
Final note — where to focus in 2026
In 2026, L-Hydroxyproline will be a market characterized by steady top-line growth, selective premiumization and active supply-side repositioning. Companies that combine disciplined procurement, targeted technical partnerships and scenario-based planning will convert market growth into durable competitive advantage. PW Consulting’s full report equips leaders to make those decisions with confidence — from assessing which suppliers to qualify, to sizing strategic investments, to structuring M&A that captures synergy without overpaying for transient scale.
For access to the complete market model, granular segmentation, supplier scorecards and our proprietary scenario toolset, please consult the full PW Consulting L-Hydroxyproline Market report.
For detailed analysis of this topic, please visit the official page: L-Hydroxyproline (CAS 51-35-4) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com