

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cochloroether Rubber Eco Market to grow at 4.51% CAGR, hitting USD 874.95 million by 2032 as Asia Pacific leads with USD 297.96M in 2025

PW Consulting Preview: Cochloroether (ECO) Rubber Market — Strategic Intelligence for 2026 Decision-Making
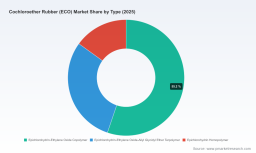
PW Consulting today releases a preview of its forthcoming Cochloroether (ECO) Rubber Eco Market report, offering senior executives and strategy teams a synthesis of the market forces that will shape commercial outcomes in 2026 and beyond. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study projects continued expansion at a compound annual growth rate (CAGR) of 4.51%. The total market expanded from approximately USD 515 million in 2020 to about USD 643 million in 2025 and is modeled to approach USD 875 million by 2032 — an investment case that invites active portfolio positioning and supply-chain decisions in the coming 12–18 months.
Cochloroether Rubber Eco Market
Why this report matters for 2026 planning
-
High-impact, near-term choices: 2026 will be a year when procurement contracts renew, capital allocation debates are settled, and regulatory-compliance roadmaps firm up — all under a market context of steady mid-single-digit growth.
Cochloroether Rubber Eco Market -
Supply-side complexity: upstream epichlorohydrin dynamics, including new capacity additions and evolving bio-based production routes, are already re-shaping feedstock sourcing economics and margin profiles across the value chain.
Cochloroether Rubber Eco Market -
Concentration and counterparty risk: the ECO rubber ecosystem exhibits oligopolistic features that alter negotiation leverage, partner selection, and competitive response strategies.
-
Regulatory and product-risk bifurcation: material formulations that avoid hazardous curing systems and enable automotive OEM compliance present differentiated commercial opportunities.
What the PW Consulting report delivers — practitioner-focused, execution-ready content
-
Proprietary market model & scenario toolkit — a fully transparent forecast engine (2026–2032) with sensitivity levers for feedstock prices, capacity additions, and end-market demand shocks.
-
Actionable supplier scorecards — qualitative and quantitative assessments of incumbent manufacturers and compounders that support supplier rationalization or qualification plans.
-
Commercial playbooks — tailored go-to-market and pricing strategies for suppliers, OEMs, and distributors across differing risk appetites and time horizons.
-
Supply-chain mapping and sourcing options — downstream exposure mapping, alternative feedstock sourcing, and recommendations for hedge structures and long-term agreements.
-
Regulatory & sustainability matrix — compliance impact assessment, product substitution risk rankings, and a roadmap for integrating bio-based feedstocks and lead/ETU-free curing technologies.
-
M&A and partnership screening — a shortlist of archetypal targets and the due-diligence checklist our practitioners use to validate accretive acquisitions or joint ventures.
-
Primary intelligence — interviews with industry leaders, plant-level capacity checks, and market testing feedback to validate modeled outcomes.
Market dynamics and feedstock context
Two supply-side realities deserve immediate attention. First, epichlorohydrin remains the primary upstream feedstock for ECO rubber. Global epichlorohydrin production capacity and utilization trends materially affect industry margins and pricing behavior. Recent industry monitoring shows global production capacity in the multi-million-tonne range and a sizable gap between nameplate capacity and actual output, with significant capacity additions announced in consecutive years. Those additions — many tied to glycerol-based, lower-carbon production routes — are shifting the cost curve and creating differentiated supply pools for companies willing to qualify bio-based inputs.
Second, price signalling from major producers has amplified procurement risk. Public pricing actions and periodic increases are a reminder that integrated producers retain the option to pass through feedstock-driven cost shocks. For buyers and compounders, this translates to a need for dynamic contracting, blended sourcing, and contingency inventory strategies. PW Consulting’s report models a range of epichlorohydrin price and availability scenarios and traces their impact on margins, product viability, and total cost of ownership for OEMs and tier suppliers.
Competitive landscape — who matters and why
The ECO rubber industry is concentrated. The top three manufacturers account for a meaningful majority of market supply, and the top five widen that hold further — a structural feature that shapes capacity access, contract terms, and innovation pathways.
-
Osaka Soda Co., Ltd. — A fully integrated producer with monomer-to-polymer capabilities and a long track record in EPICHLOMER™ and related grades. Integration gives it margin and supply stability advantages and the ability to manage upstream disruptions internally.
-
Mitsui Plastics, Inc. — A legacy supplier with high-purity ECO lines and deep experience in customizable formulations. Its long production history and modular grade portfolio make it a go-to partner for OEMs requiring proven performance and tailored properties.
-
Zeon Corporation — Known for the Hydrin® family, Zeon emphasizes thermal, fuel, and ozone resistance with production footprints that include U.S.-based capacity for select grades. This geographic stance is relevant for buyers seeking regional supply security or localized content.
-
BRP Manufacturing — A U.S.-based compounder focused on application-specific, ASTM-compliant grades. Its strengths are speed-to-sample, customization for automotive components, and proximity to North American OEMs.
-
RADO Gummi GmbH — A European specialist delivering ETU-/lead-free curing systems and formulations optimized for compliance and low permeability. Its product positioning addresses tightening regulatory expectations and OEM risk programs.
These firms differentiate by integration (monomer production vs. compounding), regional footprint, and product/curing chemistries. For potential entrants or investors, the implication is clear: compete on either technology (bio-based, ETU-free chemistries), service (localized compounding and rapid qualification), or cost (scale-driven, integrated production).
Regulatory and sustainability vectors to watch
Regulatory attention on curing systems and hazardous additives has created measurable demand for ETU-free and lead-free formulations. At the same time, sustainability pushes — including OEM targets for low-carbon materials — are accelerating interest in glycerol-derived and other bio-based epichlorohydrin routes. These shifts are not merely compliance items; they are value-creation levers for suppliers that can demonstrate lower life-cycle emissions and simplified regulatory risk profiles.
Strategic recommendations for 2026
-
Adopt a two-tier procurement strategy: secure a baseline of capacity with integrated producers while qualifying alternative compounders and bio-based feedstock suppliers to preserve optionality.
-
Invest in product differentiation where regulation meets performance — ETU-/lead-free curing and low-permeability grades are becoming table stakes for automotive and regulated industrial applications.
-
Recalibrate pricing models: build contract clauses that include transparent pass-through mechanics for feedstock inflation and capacity constraint premiums.
-
Prioritize regionalization for critical applications: localized production reduces lead times and mitigates supply-chain shocks for mission-critical OEM platforms.
-
Evaluate M&A and capacity partnerships selectively: focus on targets that fill functional gaps (e.g., bio-feedstock access, ETU-free curing IP, or compounding scale in priority markets).
-
Run scenario-based product roadmaps: use the PW Consulting forecast toolkit to stress-test R&D pipelines against low-, mid-, and high-growth outcomes through 2032.
How PW Consulting converts insight into execution
We build market intelligence with the explicit goal of enabling decisions. The full report provides the editable financial model, a supplier heatmap, and playbooks that translate analysis into boardroom-ready actions. Clients receive: the primary-data foundation (supplier interviews and plant checks), a validated forecast engine with scenario toggles, and prioritized strategic initiatives mapped to investment size, time-to-benefit, and execution risk.
Where this preview is intentionally high-level, the full report contains the granular segmentation, company scorecards, and modeling assumptions that commercial teams and M&A committees require to commit capital or amend sourcing contracts. For organizations preparing budgets, negotiating supplier agreements, or planning product launches into 2026, that level of detail is material and actionable.
Next steps
PW Consulting’s Cochloroether (ECO) Rubber Eco Market report is designed to be the decision-support asset for the next wave of strategic moves across suppliers, OEMs, and investors. To access the full dataset, proprietary segmentation, and our scenario-ready financial model, visit the report page or contact PW Consulting to schedule a briefing with our sector practice. In a market with concentrated supply, evolving feedstock pathways, and tightening regulatory expectations, early access to validated intelligence will be a competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Cochloroether Rubber Eco Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com