

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Scandium Metal Market Set to Expand at 8.55% CAGR, Reaching USD 93.29 Million by 2032

Scandium Metal Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
As strategic planners and procurement leaders prepare budgets, capital decisions, and industrial partnerships for 2026, PW Consulting’s latest Scandium Metal Market report offers a focused, decision-centric view of an emergent specialty metals market. Our analysis combines a clarified demand forecast, supply‑side capacity mapping, and an executable playbook for near‑term action — providing exactly the strategic inputs executives need without revealing proprietary segment-level detail that must be validated on purchase.
Scandium Metal Market
Why scandium matters now — and next
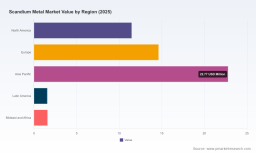
Scandium has moved from a laboratory curiosity to a strategic component in a short list of high-value industrial pathways: high-performance aluminum alloys, solid‑oxide fuel cells (SOFCs), optical lasers, and specialty lighting among them. This transition is reflected in the market’s structural trajectory: from an estimated global market value of USD 52.0 Million in the base year (2025), the market is modeled to grow at a compound annual growth rate (CAGR) of 8.55% during our forecast window, reaching an anticipated USD 93.29 Million by 2032. That growth profile is not linear — it is punctuated by discrete capacity ramps, policy interventions, and technology adoption events that will create asymmetric value opportunities for early movers.
Scandium Metal Market
What distinguishes our report (practical, executable deliverables)
- Proprietary supply‑demand engine: A modular forecast tool calibrated to historical 2020–2025 market signals and 2026–2032 scenario variants. The engine supports scenario queries (policy shock, rapid SOFC uptake, alloy substitution) and produces outputs useful for CAPEX timing and procurement hedging.
- Supply pathway mapping: A geospatial view of primary and secondary feedstock sources (including industrial waste streams), commercial‑scale production assets, and announced expansions — annotated with commissioning timelines, technology readiness scores, and upstream permit/risk flags.
- Commercial pricing and cost‑curve sensibilities: Forward price bands under three adoption scenarios and an enterprise‑grade cost sensitivity matrix that shows where margins go under different feedstock and recovery‑efficiency assumptions.
- Supplier due diligence pack: Standardized scorecards for incumbent and emerging suppliers (technical capability, capacity optionality, counterparty risk, sourcing footprint) plus red‑flag checklists for supply contracts.
- M&A and JV playbook: Transaction triggers, valuation traffic lights, integration pitfalls (notably for operations relying on low‑grade secondary feedstocks), and model term sheets for offtake and tolling arrangements.
- Regulatory & defense procurement tracker: A living appendix summarizing recent government actions, grant programs, and defense offtake that materially affect supply security and investment risk.
Key market dynamics shaping 2026 decision-making
- Constrained, concentrated supply: A handful of established producers and vertically integrated accounts continue to dominate global supply. Market concentration leaves buyers exposed to sourcing disruptions during capacity transitions and geopolitical stressors.
- Secondary feedstocks gaining strategic importance: Recovery from industrial residues — notably oxide and red‑mud streams from TiO2 and aluminum processing — is moving from pilot to commercial reality at several operators. That pathway materially improves feedstock optionality but introduces variability in impurity profiles and processing cost.
- Policy and defense demand: North American defense procurement and near‑shoring initiatives are creating premium sub‑markets for certified, traceable supply. Public procurement commitments can accelerate commercialization and justify near‑term capacity expansions.
- Project cadence matters: A small number of announced expansions and greenfield projects will determine market tightness in the next 12–36 months. The timing of commissioning events is therefore a primary driver of short‑term price volatility and long‑term investment returns.
Competitive landscape — who matters and why
Our competitive assessment focuses on companies that currently shape commercial availability and investment sentiment.
Scandium Metal Market
- Rio Tinto — A commercial producer with industrialized recovery routes from TiO2 waste streams. Recent strategic moves include a financing/expansion transaction intended to raise output at its Quebec operation, reflecting a deliberate push to secure near‑market defense and specialty industrial demand.
- Scandium International Mining Corp. — Developer-stage asset owner advancing a primary scandium mine in New South Wales. A recent mining lease milestone materially improves project maturity and the potential for primary scandium to enter the market as a dedicated supply stream.
- RUSAL — A legacy aluminum giant that supplies scandium as a strategic byproduct from integrated aluminum operations. Its global footprint and refining scale make it a pivotal supplier for large offtake arrangements.
- China‑based producers and suppliers — Several mid‑to-large scale operations supply a broad range of scandium products, from metal forms to high‑purity oxides, often competing on scale and price; their strategic posture affects global price floors and inventory flows.
- Specialty suppliers — Smaller niche manufacturers and material houses provide high‑purity products for research and industrial application scaling. Their agility is critical for early adopter applications where tight impurity controls matter more than price.
Recent, verifiable developments that alter near‑term strategy include capacity expansion announcements at commercial producers and new mining lease approvals for primary projects. At the same time, public‑sector funding for recovery technologies and defense procurement commitments are creating alternative demand anchors that change risk calculus for investors and offtakers alike.
How to use the report to inform 2026 choices
Executives asking "what do we need to decide in 2026?" will find three immediate use cases:
- Procurement and contract structuring: Use our supplier scorecards and contract templates to lock in staggered offtake with embedded flexibility (tolling, quality‑differentiated pricing, and volume ramp clauses). This reduces exposure to short‑term supply shocks while preserving upside participation if prices soften as new capacity comes online.
- Capital allocation and timing: Investors and industrials can apply the scenario outputs to gate CAPEX — distinguishing between projects that require de‑risking via offtake versus those that can be justified on merchant price exposure. Our models highlight the inflection points where private investment becomes commercially viable.
- Strategic partnerships and vertical strategies: For OEMs and alloy manufacturers, forming upstream partnerships (with producers, waste‑stream owners, or toll processors) is, in many cases, the most efficient route to secure consistent specification materials while avoiding raw material price contagion.
Risk register and mitigation playbook
Key risks include feedstock supply volatility, regulatory shifts, and product specification heterogeneity. Our report presents a prioritized risk register and a set of mitigation templates, such as dynamic inventory policies keyed to commissioning dates, multi‑sourcing mandates for critical components, and switchable process designs that tolerate feedstock impurity variance.
Actionable takeaways for different stakeholders
- For procurement leaders: Begin structuring multi‑year offtake agreements with optionality clauses today; engage with specialty tollers to build buffer capacity without committing to heavy upstream capital.
- For investors and corporate development teams: Use milestone‑based investments tied to proven recovery yields and offtake commitments; prioritize projects with secondary feedstock optionality and accessible permitting pathways.
- For policy and defense planners: Recognize that strategic procurement commitments (especially in certified, traceable supply programs) substantially reduce investment risk and can accelerate localized supply creation.
Why PW Consulting’s analysis is uniquely fit for 2026 planning
Our approach blends granular operational intelligence with market economics and a practitioner’s playbook. We do not simply forecast; we provide the decision logic that turns forecast outputs into executable strategies: precise supplier diligence forms, CAPEX gating criteria, contract templates optimized for thin markets, and scenario stress‑tests tailored to clients’ risk appetites.
Importantly, the report is intentionally structured as a "preview" here: it demonstrates the methodological rigor and the strategic depth you need to act in 2026, while preserving the core segmentlevel forecasts, supplier scorecards, and model files for authenticated access. Executives who require the complete financial matrices, regional and application breakdowns, and downloadable Excel model can obtain them via the report distribution channel.
Next steps — how to access the full intelligence
If your decisions in 2026 include securing offtake, timing investment, or redesigning product roadmaps around scandium‑enabled materials, we recommend downloading the full Scandium Metal Market report and associated model pack. The full dossier contains the segment‑level forecasts, supplier profiles, and contract exemplars that are essential for detailed implementation. Contact PW Consulting via our website to arrange access and a tailored briefing with our lead analysts.
In a market where a few capacity moves and a single policy decision can reallocate value, clarity and timing matter. Our report delivers both — enabling you to convert market intelligence into defensible, actionable strategy for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Scandium Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com