

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polyurethane Adhesive for Shoes Market to Reach USD 2,672.73 Million by 2032 at 5.85% CAGR; Asia Pacific Dominates with USD 1,025.57 Million

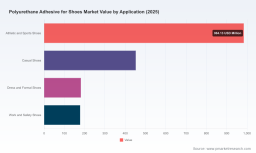
Polyurethane Adhesive For Shoes Market — Strategic Outlook for 2026
As global footwear manufacturers recalibrate post-pandemic supply chains and accelerate sustainability roadmaps, polyurethane (PU) adhesives have become a strategic input rather than a commoditized purchase. PW Consulting’s latest market study — released with a strong forecast horizon — positions senior leaders to make fact-based decisions in 2026 that protect margins, de-risk supply, and capture share in higher-value segments of the footwear value chain.
Polyurethane Adhesive For Shoes Market
High-level market context
Our analysis shows the market expanding steadily from the early 2020s into the mid-2020s: the industry moved from an approximate market base in 2020 to roughly USD 1.8 billion in 2025. Under our base-case assumptions, the polyurethane adhesive for shoes market is projected to grow at a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast window, reaching a multi-billion-dollar opportunity by 2032. Market concentration is material: the top three suppliers account for a meaningful share of industry revenues and the top five control just over half of the market, creating both competitive pressure and consolidation opportunity for mid-market players and innovators.
Polyurethane Adhesive For Shoes Market
Why this report matters for 2026 decisions
-
Procurement and margin protection: With feedstock volatility (notably MDI/TDI prices tied to crude oil) and recent tariff changes affecting landed costs, procurement strategy is now a core margin lever. The report provides procurement scenarios and contract structures tailored to footwear adhesive formulations.
Polyurethane Adhesive For Shoes Market -
Product and process roadmap: Environmental regulations—REACH and regional Green Deal-style frameworks—are accelerating the shift away from solvent-based chemistries. Manufacturers must prioritise technology choices (waterborne PU, hot-melt PUR, bio-based polyols) that meet both regulatory and brand sustainability requirements without sacrificing performance.
-
Supply chain resilience: Tariff adjustments and regional manufacturing incentives are altering landed-cost calculus. The study equips executives to decide on near-shore vs. global sourcing, inventory hedging, and strategic supplier partnerships.
-
M&A and partnerships: Given the moderate-to-high concentration in the market, acquisitive moves or co-development partnerships can accelerate access to differentiated chemistries and customer contracts. The study identifies capability gaps where targeted M&A can create outsized returns.
What’s included — practical, decision-ready deliverables
This report was designed for operators and executives who need executable guidance, not academic summaries. Key operational components include:
-
Five strategic playbooks: procurement hedging, formulation migration (solvent → waterborne/PUR), manufacturing conversion (adhesive application and curing optimization), sustainability compliance, and channel go-to-market for adhesive formulators.
-
Supplier scorecards and heat maps capturing technology readiness, scale, geographic footprint, and commercial terms—built to accelerate vendor selection and pilot programs.
-
Scenario modelling with sensitivity to raw material swings (MDI/TDI), tariff shocks, and accelerated regulatory timelines—allowing finance and strategy teams to stress-test capex and pricing strategies.
-
A regulatory impact matrix mapping REACH/Green Deal-related timelines to formulation decisions, enabling product managers to prioritize reformulation efforts that will be most material to brand customers.
-
Commercial benchmarks and pricing guidance in USD (per market unit and aggregated revenue scale), plus suggested margin-preserving contract structures for long lead-time raw materials.
-
Implementation timelines and cost-to-convert estimates for switching application technology (for example, moving to polyurethane hot-melt systems to reduce steps and energy usage in athletic shoe lines).
Competitive landscape — what leading suppliers are doing
The market is populated by a mix of global chemical majors, specialized formulators, and regional innovators. Public and private players have distinct playbooks:
-
Global adhesives leaders are commercializing polyurethane hot-melt (PURHM) and waterborne systems that emphasize reduced production steps, lower energy consumption, and compatibility with multi-material uppers. They are positioning these products directly to major athletic brands and contract manufacturers as labour- and energy-saving solutions.
-
Polymer producers and raw-material suppliers are moving upstream into application-ready dispersions and thermoplastic polyurethane (TPU) powders to capture value beyond commodities. Their strategy centers on tighter integration with formulators and co-development with footwear OEMs.
-
Regional specialists from Asia and Taiwan are competing on hydrolysis-resistant grades and waterborne chemistries, offering rapid local service and certification pathways for regional brand manufacturers.
Recent industry moves underscore these themes: several major players refreshed portfolios for sports shoe bonding and low-VOC formulations in 2024–2025; new thermoplastic TPU lines for solvent-based and hot-melt applications were launched; and bio-based TPU introductions are entering the market palette, signaling a clear premium for lower-carbon options.
Market dynamics and risk factors
-
Raw material volatility: MDI and TDI price swings remain a critical margin risk. Our models show that short-term spikes materially compress formulators’ margins unless procurement and pricing are aligned with indexation or hedging mechanisms.
-
Regulatory pressure: Tightening VOC and hazardous substance limits are accelerating the adoption of water-based dispersions and low-VOC chemistry across major footwear producing regions. Non-compliant suppliers will face restricted access to key customers in Europe and other regulated markets.
-
Tariff and trade policy: Recent changes to tariffs on key polyols and isocyanates have already raised landed costs in some markets. Manufacturers that rely on imported intermediates should re-evaluate total landed cost and consider localizing critical upstream capabilities.
-
Sustainability premium: Brands are increasingly willing to pay for adhesives that demonstrably lower lifecycle emissions or use bio-sourced inputs—creating a differentiated price band for certified formulations.
Strategic imperatives for 2026 — recommended actions
-
Lock in multi-year feedstock agreements with protective clauses. Combine volume commitments with indexation and force majeure provisions to stabilize unit costs without forfeiting upside flexibility.
-
Prioritise migration pathways to water-based dispersions and bio-based polyols for product lines that supply regulated markets or sustainability-focused brands. Use pilot programs with tier-1 brands to accelerate adoption and share reformulation risk.
-
Invest selectively in hot-melt PUR capability where labour reduction and energy efficiency deliver short payback; quantify the operational savings across targeted production lines before committing to wholesale conversion.
-
Evaluate M&A or JV opportunities to acquire localized capacity for critical intermediates or proprietary PU grades. Given market concentration dynamics, disciplined inorganic moves can be accretive to both margin and time-to-market.
-
Establish a regulatory early-warning system and a reformulation playbook tied to compliance milestones—this reduces surprise capital requirements and protects customer contracts.
PW Consulting’s role and how to use this study
Our report is built to be operational: it includes executable templates, supplier selection matrices, and a worked example of a 24-month migration plan from solvent-based adhesive to a low-VOC, waterborne system in a mass-production footwear line. We combine primary interviews with formulators, manufacturers, and brand procurement leads, plus proprietary pricing and concentration analysis that highlights competitive opportunities without disclosing commercially sensitive split data in this release.
For leadership teams planning 2026 budgets, the study serves three immediate uses: (1) aligning R&D and procurement spend with the most probable regulatory and raw material scenarios, (2) prioritizing capital expenditure to convert lines with the fastest return on invested capital, and (3) defining partnering or M&A criteria that close capability gaps quickly.
Next steps — where to get the full intelligence
This press summary highlights the strategic framing and operational implications. The full report contains the granular segmentation, supplier-level economics, and downloadable modelling tools required to execute decisions in 2026. To access the complete dataset, scenario models, and supplier scorecards, please visit the PW Consulting report page or contact our advisory team to schedule a briefing tailored to your priorities.
PW Consulting remains available to support implementation— from pilot design and supplier negotiations to CAPEX prioritisation and regulatory compliance programs—enabling manufacturers and formulators to convert market insight into defensible advantage during 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Polyurethane Adhesive For Shoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com