

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insight: L‑Hydroxyproline (CAS 51‑35‑4) Market to Reach USD 384.15 Million by 2032

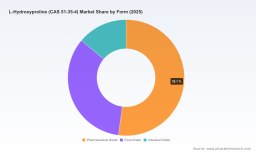
L-Hydroxyproline (CAS 51-35-4) Market — 2026 Strategic Outlook: A PW Consulting Executive Brief
Executive summary
As PW Consulting’s lead industry analyst, I present an executive synthesis of our 2026-ready market intelligence on L-Hydroxyproline. Using 2025 as the base year, the market has demonstrated sustained expansion from an observed USD 186.2 Million in 2020 to USD 250.8 Million in 2025. Our forecast blends historical demand drivers with near-term supply-side developments to project the market growing at a compound annual growth rate (CAGR) of 6.4% across the 2026–2032 horizon, reaching approximately USD 384.15 Million by 2032. These macro trajectories frame a set of actionable decision levers for corporate leaders — from C-suite strategists to procurement heads and R&D directors — who must position for 2026 and beyond.
L-Hydroxyproline (CAS 51-35-4) Market
Why this matters in 2026 — high-conviction implications
-
Demand momentum is durable but heterogeneous. The market’s steady rise reflects a mix of pharmaceutical formulations, personal-care innovation and specialty food/nutraceutical uses. For decision-makers, this means predictable baseline demand combined with pockets of rapid premiumization in high-margin use cases. Planning horizons must therefore balance volume playbooks with selective capability investment in quality and regulatory compliance.
L-Hydroxyproline (CAS 51-35-4) Market -
Supply-side shifts are shaping bargaining power. Recent capacity investments by established Western producers and rapid scaling by Asian manufacturers have created a more elastic global supply curve. Buyers should anticipate episodic pricing pressure and execute diversified sourcing strategies that prioritize quality tiers and lead-time resilience over pure price optimization.
L-Hydroxyproline (CAS 51-35-4) Market -
Technology and process mix are strategic differentiators. Our market mapping shows that microbial fermentation and enzymatic biotransformation together represent the dominant production backbone. Firms that can align procurement and R&D with these processes — whether by co-developing tailored grades or by investing in downstream purification — will capture structural margins.
-
Regulatory and formulation innovation are fast followers. Recent product launches and capacity expansions underscore a two-track evolution: regulatory-grade, traceable supply for pharmaceutical/clinical channels, and application-specific grades for cosmetics and nutraceuticals. Corporate strategies in 2026 must include regulatory readiness and formulation partnerships as core go-to-market enablers.
What the PW Consulting report delivers — practical, decision-ready modules
The full report is designed as a tactical toolkit for 2026 planning cycles. It combines proprietary market-sizing, a robust forecasting engine, supply-chain heatmaps and a stratified competitor playbook. Key, actionable modules include:
-
Comprehensive market model (2020–2032) with scenario sensitivity to raw material shocks, regulatory shifts and demand elasticity assumptions — enabling iterative boardroom “what-if” simulations.
-
Supply-side atlas with supplier tiering, production route matrices and risk scores — built to inform multi-sourcing contracts and buffer-capacity decisions without exposing segment-level commercial terms in this summary.
-
Commercial playbook outlining pricing levers, margin-protection tactics and commercialization checklists for each buyer persona (pharma CPO, cosmetic formulators, nutraceutical brand teams).
-
Regulatory & compliance dossier mapping pathways for pharmaceutical-grade approvals, cosmetic-claim substantiation and food-grade certification — presented as stepwise timelines and CapEx/OpEx sensitivity tables.
-
M&A and partnership framework, including threshold criteria for bolt-on acquisitions, JV structuring options, and synergies matrices that quantify integration value drivers.
Competitive landscape — reading the room in 2026
The competitive topology of L-Hydroxyproline shows a mix of premium, technology-led incumbents and high-scale, cost-oriented manufacturers. Market concentration metrics indicate a moderately consolidated upper tier, leaving space for mid-sized players and specialized entrants to differentiate on quality and service.
-
Kyowa Hakko Bio (Japan) — Positioned at the premium end with fermentation-based, pharma-grade offerings. Their strengths are regulatory-track record, high-purity manufacturing and established clinical supply relationships. For partners seeking reliable quality and traceability, Kyowa Hakko remains a first-choice supplier, though typically at a price premium.
-
Evonik Industries (Germany) — Recent capacity expansion in Europe underscores a strategic move to secure pharmaceutical-grade volumes close to major pharma clusters. Evonik’s play is classic integrated-chemistry plus biotech — emphasizing consistent quality, European regulatory alignment and global distribution. Their expansion has immediate implications for regional supply balance and contract negotiation dynamics.
-
Chinese supply base — A broad set of manufacturers has focused on scale, cost-efficiency and rapid capacity additions. These players serve a wide spectrum of quality tiers from industrial to high-purity grades. Competitive pressure from this cohort is most pronounced on volume contracts and commodity-grade channels, and savvy buyers will extract value by mixing suppliers across quality bands.
-
Specialty and niche producers — Several mid-size firms concentrate on high-purity derivatives and intermediates tailored for research and formulation houses. Their agility in customized specifications and shorter lead times makes them preferred collaborators for innovative product development.
Supply dynamics and production routes — what to watch
Two production paradigms dominate: microbial fermentation and enzymatic biotransformation. These approaches collectively form the backbone of industrial output and account for the majority share of production globally. For purchasing and operations teams, this has three implications:
-
Cost structures are increasingly driven by bioprocess inputs and downstream purification rather than upstream raw-material scarcity alone.
-
Quality differentiation is feasible via tighter bioprocess control and investment in purification train enhancements, enabling producers to command premium pricing for pharmaceutical and high-margin cosmetic grades.
-
Securing intellectual property or co-development agreements around proprietary strains or enzymes can be a durable competitive moat for manufacturers and a supply-stability lever for large buyers.
Regulatory and market signal highlights (recent)
-
Evonik’s 2025 expansion of pharmaceutical-grade capacity in Europe signals supplier intent to be closer to major pharma customers and to shorten qualification cycles — a clear indicator for procurement teams to revisit regional sourcing strategies.
-
New product launches in 2025 from major ingredient houses targeting cosmetic-grade hydroxyproline reflect a trend toward targeted actives in anti-aging formulations. Brands should evaluate co-development opportunities early in the 2026 formulation pipeline.
Market concentration and strategic implications
Concentration metrics show a mid-level aggregation of market share among the largest producers. This structure creates a two-speed market: incumbents can leverage scale to protect margins in regulated, high-entry-barrier channels; meanwhile, medium-sized players can exploit niches through agility and customization. For decision-makers, recommended responses include calibrated M&A screening, targeted supplier partnerships, and differentiated procurement frameworks that align with grade-specific risk profiles.
2026 Strategic playbook — recommended actions
-
Near-term (0–12 months): Lock supply via staggered contracts across quality tiers, prioritize suppliers with demonstrated regulatory compliance for clinical programs, and institute dual-sourcing for critical SKUs.
-
Medium-term (12–36 months): Invest in formulation co-development with selective high-purity suppliers, evaluate toll-manufacturing or partial vertical integration for strategic grades, and pilot bioprocess innovations that lower total cost of ownership.
-
Long-term (36+ months): Pursue targeted acquisitions or JVs to secure technology/IP, expand into adjacent value pools (e.g., specialty amino-acid derivatives), and build predictive procurement analytics tied to the report’s scenario models.
How PW Consulting supports your 2026 decision cycle
Our report is not an academic exercise; it is an executable playbook. Clients receive the full model, supplier heatmaps, contract negotiation checklists, and a prioritized initiative road map calibrated to company size, risk appetite and product mix. The public executive brief intentionally omits granular segmentation disclosures so strategic buyers and investors consult the full dataset for transaction-grade intelligence and detailed regional/application split analytics.
Final note — where to focus in 2026
In 2026, L-Hydroxyproline will be a market characterized by steady top-line growth, selective premiumization and active supply-side repositioning. Companies that combine disciplined procurement, targeted technical partnerships and scenario-based planning will convert market growth into durable competitive advantage. PW Consulting’s full report equips leaders to make those decisions with confidence — from assessing which suppliers to qualify, to sizing strategic investments, to structuring M&A that captures synergy without overpaying for transient scale.
For access to the complete market model, granular segmentation, supplier scorecards and our proprietary scenario toolset, please consult the full PW Consulting L-Hydroxyproline Market report.
For detailed analysis of this topic, please visit the official page: L-Hydroxyproline (CAS 51-35-4) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com