

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Carboxymethyl Tamarind Gum Market to Rise from USD 18.5 Million in 2025 to USD 28.74 Million by 2032 at a 6.49% CAGR, Led by Asia‑Pacific
By pmarketresearch, 2026-07-02
Carboxymethyl Tamarind Gum (CMT) Market — Strategic Briefing for 2026 Decision Makers
Executive preview
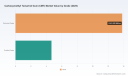
PW Consulting’s new market study on Carboxymethyl Tamarind Gum (CMT) consolidates five years of historical observation (2020–2025) and a seven‑year forecast (2026–2032) into a decision-grade intelligence package for commercial, procurement and corporate development leaders. The global market — tracked in USD Million — expanded from an estimated 13.5 in 2020 to 18.5 in our 2025 base year, and is projected to surpass 20.2 in 2026 on the way to approximately 28.7 by 2032. The forecast period carries a compound annual growth rate (CAGR) of 6.49% for 2026–2032. At a concentration level where the top three players account for roughly 38.4% of supply and the top five for about 52.2%, this is a market where mid‑sized incumbents and nimble newcomers can create outsized commercial returns if they move strategically.
Carboxymethyl Tamarind Gum (CMT) Market
Why this report matters in 2026
- Turn market momentum into commercial advantage: The growth trajectory shows stable demand expansion across legacy and adjacent applications; the question for 2026 is what moves will unlock margin expansion, not whether demand exists.
- Risk‑aware sourcing in a raw‑material‑centric supply base: India remains the primary origin of tamarind seed feedstock, and raw‑material dynamics (production, quality, logistics) are the single largest determinant of near‑term cost volatility.
- Concentration creates both opportunity and constraint: With moderate CR3/CR5 metrics, well‑timed M&A or offtake agreements can materially shift supplier economics — but they require granular supplier intelligence and scenario modelling to avoid overpaying for transient advantages.
- Regulatory and product‑grade stratification is decisive: Recognition of tamarind kernel powder in manufacturing contexts lowers a regulatory barrier for industrial uses, while higher‑value purified grades open doors to cosmetics, pharma and premium personal‑care segments.
What’s inside the report — operational modules that support 2026 programs
- Executive decision memo: concise scenarios (base, upside, downside) and recommended plays for procurement, product and M&A teams.
- Top‑level market model: annualized historical series and forecast to 2032 (USD Million), with driver decomposition (volume, price, grade mix) and sensitivity levers.
- Price and margin simulator: inputs for raw‑material cost, conversion yield and conversion economics by grade to stress‑test sourcing choices.
- Supply‑chain map and heat‑map: origin nodes, processing steps, logistics chokepoints and a risk index tied to seasonality and policy scenarios.
- Competitive scorecards: capability matrices for leading manufacturers, distributors and specialty processors (capex, grade portfolio, export footprint, technical service capability).
- Product & formulation playbook: application profiles for textile, paper, industrial and high‑purity segments, including formulation parameters, pilot protocols and scale‑up checklists.
- Commercial playbook: channel strategies, distributor economics, tender templates and win/loss playbooks for upstream and downstream commercial teams.
- M&A and partnership shortlist: validated targets and integration risk assessment with modeled synergies and payback horizons.
- Regulatory matrix and compliance checklist: mapped to food, industrial and cosmetic use cases, with incremental compliance steps for purified grades.
Note: The full dataset, vendor scorecards and line‑item segmentation detail are available in the complete report to support transaction execution and contract negotiation. This release is intentionally selective — a precise preview rather than exhaustive disclosure.
Carboxymethyl Tamarind Gum (CMT) Market
Market dynamics and strategic implications
Three structural forces drive the CMT market in 2026: raw‑material geography and seasonality; grade bifurcation between industrial and purified applications; and continuing demand resilience in textile printing alongside incremental uptake in technical industrial uses.
Carboxymethyl Tamarind Gum (CMT) Market
On raw materials: India remains the dominant source of tamarind kernel feedstock, producing on the order of several hundred thousand tonnes of tamarind annually. That concentration yields cost advantages for regionally integrated processors but introduces single‑country risk. Buyers and processors should plan for weather‑driven supply variability, upstream quality swings and logistics disruptions during peak harvest season. Practical mitigations include multi‑tier offtake agreements, inventory optimization calibrated to seasonality, and selective investment in on‑shore processing to shorten critical lead times.
On product grades: CMT is not a monolith. The industry differentiates between technical/industrial grades used as textile thickeners, paper sizing agents and drilling/binder additives, and higher‑purity grades that address cosmetics, personal‑care and pharmaceutical adjacencies. Achieving and certifying purified grades requires additional process steps (seed selection, coat removal, milling, sieving and controlled chemical modification), which create higher entry barriers but also wider margin pools for firms that can operationalize consistent quality and regulatory compliance.
On demand patterns: Textile printing continues to anchor demand, particularly where reactive and disperse dye systems require stable, high‑viscosity thickeners with excellent wash‑off and color‑fastness characteristics. Meanwhile, the product’s cold‑water solubility and rheology profile are opening new use cases in energy‑sensitive industrial processes and water‑sensitive paper applications. Buyers should quantify the uplift potential from specialty grades and consider product stewardship and sample support as differentiators in commercial negotiations.
Competitive landscape — tactical read on core suppliers
- Indian Hydrocolloids — A leading manufacturer and exporter with a clear focus on customizable grades and broad pH/temperature stability. Strategic posture: premium, service‑oriented supplier with the capacity to win technical partnerships for textile and oil‑field formulations.
- Adachi Group — Known for cost‑competitive textile‑grade thickeners, with emphasis on color fastness and wash‑off. Strategic posture: volume player that competes on consistency and pricing; attractive as a volume partner or OEM supply source.
- Sudev International — Focused on high‑viscosity grades and international quality standards. Strategic posture: niche supplier for customers requiring defined rheological windows and documented performance.
- Chhaya Industries — Specialist in high‑viscosity CMT grades for synthetic fiber printing; strong in technical service and filterability performance. Strategic posture: technology‑led supplier useful for pilot collaborations where processability matters.
- Other regional producers and distributors (including Premcem, Altrafine, Shivam, Mahesh Agro, Mysore Starch, Wego, Riverland, Allwyn, Creative Polymer and DHN International) form a competitive ecosystem of integrated manufacturers and merchant distributors. Strategic posture: diverse — from upstream agricultural integration to global distribution networks that can accelerate market entry for downstream formulators.
For buyers and investors, the immediate takeaway is clear: segment suppliers by capability (commodity vs specialty), then define sourcing and partnership strategies accordingly. A blended approach — strategic partnerships for specialty grades and competitive tenders for commodity volumes — typically minimizes total cost of ownership while preserving access to innovation.
2026 strategic playbook — prioritized actions
- Conduct an immediate 90‑day supply risk audit: map top‑tier suppliers, assess seasonality exposure, and secure 12–18 month conditional offtake terms to buffer near‑term volatility.
- Establish a product‑grade roadmap: identify a short list of high‑value purified grades that align with existing customers or attractive adjacent markets (cosmetics, pharma) and define pilot‑to‑scale timelines.
- Negotiate capability‑anchored partnerships: prioritize suppliers that offer technical service, customized grades and co‑development arrangements rather than purely transactional pricing.
- Model M&A and JV scenarios using concentration metrics: use CR3/CR5-informed valuations to identify targets where synergies are operationally credible (capacity expansion, raw‑material control, or entry into higher‑margin segments).
- Implement sustainability and traceability actions: build simple, auditable chain‑of‑custody mechanisms for tamarind feedstock to support customer sustainability commitments and de‑risk reputation exposure.
- Deploy KPIs and early‑warning indicators: raw‑material inventory days, conversion yield variance, grade‑specific rejection rates and net landed cost per functional kilo will highlight margin pressure before it erodes profitability.
Concluding guidance
The CMT market in 2026 is neither a niche curiosity nor a mature commodity with a single playbook. It is a mid‑growth specialty chemical market shaped by agricultural upstreams, process chemistry and application‑level differentiation. For organizations that pair disciplined supply‑chain tactics with a selective product innovation agenda, there is a clear path to premium returns.
PW Consulting’s full Carboxymethyl Tamarind Gum (CMT) Market Report contains the detailed models, supplier scorecards, playbooks and forensic risk scenarios required to execute these strategies. This briefing is a strategic trailer — it demonstrates the rigor and operational focus of our analysis while preserving the dataset and transaction playbooks that enable execution. To access the full report, proprietary vendor matrices and our consulting engagement options, please visit PW Consulting’s market reports portal or contact our strategy team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Carboxymethyl Tamarind Gum (CMT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Plastic Enclosure Market to Expand from USD 6.25B in 2025 to USD 9.4B by 2032 at a 6% CAGR — Asia‑Pacific Leads with USD 2.67B in 2025
By pmarketresearch, 2026-07-02
Electronic Plastic Enclosure Market 2026: Strategic Imperatives for Manufacturers, OEMs and Investors
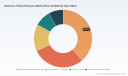
PW Consulting’s newest market briefing on Electronic Plastic Enclosures draws a clear line from data to decision for 2026. The global market — sized at USD 6,248.5 Million in our 2025 base year — is forecast to grow at a steady compound annual growth rate (CAGR) of 6.0% through our 2026–2032 horizon, reaching roughly USD 9.4 Billion by 2032. That macro trajectory masks a highly dynamic competitive and supply-side environment. This release summarizes the report’s strategic value, the practical intelligence inside, and the near-term plays companies should consider as they prepare budgets, product roadmaps, and M&A pipelines for 2026.
Electronic Plastic Enclosure Market
Why this report matters for 2026 decision cycles
-
Actionable market sizing to set realistic topline targets: Executive teams and corporate development groups gain a defensible baseline and growth runway for budgeting and valuation work.
Electronic Plastic Enclosure Market -
Supply-side risk mapping linked to pricing scenarios: Raw material volatility and trade policy are already shifting cost structures; the report translates those shifts into margin and capex planning implications.
Electronic Plastic Enclosure Market -
Regulatory and sustainability readiness: New reporting and chemical-content standards are not future hypotheticals — they are procurement and product-design constraints to be managed this year.
-
Competitive playbooks and M&A priority lists: We convert market structure and capability gaps into prioritized actions — product development, capacity moves, and bolt-on acquisition criteria.
What the report delivers (practical components)
-
Comprehensive market sizing and a seven-year forecast (2026–2032) with base-year 2025 alignment for reconciliation to internal plans.
-
Segmentation by material (ABS, polycarbonate, polyamide, PVC, and other high-performance polymers), by application (consumer, industrial, automotive, telecoms, medical), and by region — with methodology and sensitivity testing. Note: this press summary highlights strategic observations only; detailed subsegment tables and downloadable data packs are available in the full report.
-
Price and cost modeler: a scenario tool that converts raw material price moves and manufacturing mix into unit-cost and margin outcomes, including break-even curves for tooling vs. soft-tool/rapid-turn approaches.
-
Supply-chain resilience matrix: supplier concentration scores, nearshoring potential, dual-sourcing checklists, and actionable mitigation steps for tariff exposure and logistics disruption.
-
Regulatory and materials compliance playbook: templates for EHS engineering, materials declarations (to support compliance such as national registry requirements), and verification pathways for market claims (e.g., chemical-content limits).
-
Competitive benchmarks and capability heatmaps: product portfolios, manufacturing footprints, customization capabilities, and go-to-market models for leading players.
-
M&A and partnership thesis: prioritized target profiles, valuation logic, and integration checklists aligned to scale, margin, and IP objectives.
Market structure and competitive texture
The market exhibits moderate fragmentation: the three largest suppliers together account for roughly just under a third of global revenues, and the top five approach around two-fifths of the market. That structure creates both headroom for scale consolidation and defensibility for regional or specialized players who can leverage design, certification, or local-service advantages.
Across the competitive set, a few consistent strategic archetypes appear:
-
Volume-oriented, off-the-shelf specialists who compete on breadth of catalogue and fast availability.
-
Design-led firms that add ergonomic and aesthetic differentiation for handheld and customer-facing devices.
-
Custom and tooling-capable suppliers that capture higher ASPs in low-to-medium volume OEM programs (medical, industrial controls, lab automation).
-
Engineering partners focused on high-performance and environmental sealing for harsh environments (industrial, outdoor telecoms, and certain automotive segments).
Profiles and strategic implications for named competitors
-
Polycase (Avon, Ohio) — Strengths: US manufacturing, NEMA-rated enclosures, balanced off-the-shelf and custom capability. Strategic implication: momentum in domestically produced NEMA-rated lines positions Polycase well for nearshoring-led demand; scalability and raw-material cost management will be the near-term axes to protect margins.
-
Bud Industries (Willoughby, Ohio) — Strengths: broad general-purpose catalogue and industrial offerings. Strategic implication: catalogue breadth is a moat for distribution-led channels; further differentiation will require modularization and digital configuration tools.
-
Hammond Manufacturing (Guelph, Ontario) — Strengths: EMI/RFI shielding options, cross-material competence. Strategic implication: opportunity to capture higher-value industrial and communications niches that require shielding and hybrid material approaches, especially where performance trumps basic cost.
-
OKW Enclosures (Germany/US) — Strengths: ergonomic, design-forward solutions and customization. Strategic implication: premium positioning benefits from OEM relationships in handheld and medical classes; expansion in durable industrial solutions can broaden TAM.
-
New Age Enclosures — Strengths: off-the-shelf and injection-molding services for electronics. Strategic implication: vertical customers seeking single-source suppliers (design to injection) are prime targets — investments in shorter lead-time molding and digital quoting systems will pay back quickly.
-
Productive Plastics — Strengths: thermoforming and large custom enclosures for robotics and sensors. Strategic implication: as automation and robotics drive demand for bespoke housings, thermoforming and near-net shaping capabilities become attractive acquisition targets for firms wishing to enter large-format enclosures.
-
European specialists (Fibox, Bopla, Rolec) — Strengths: durable materials expertise and modern design language. Strategic implication: European players can exploit proximity advantages for industrial automation and utility markets subject to strong regulatory frameworks.
-
Allied Moulded Products, Integra, Toolless — Strengths: niche material mixes (fiberglass, stainless combinations), and no-tool or low-tool rapid customization. Strategic implication: these firms occupy defensible niches that become attractive targets for consolidators seeking to add specialty capabilities or to reduce time-to-market for regulated industries.
Recent market signals that should influence 2026 strategy
-
Raw-material swings: ABS feedstock tightening and producer-level price increases surfaced in early 2026, while polycarbonate softened materially in late 2025. Procurement roadmaps should incorporate both short-term pass-through scenarios and multi-year hedging strategies tied to polymer blends used across product families.
-
Regulatory tightening: national producer registries and international product-chemistry criteria (notably restrictions on certain brominated and chlorinated flame retardants) mean design teams must embed compliance earlier in the product lifecycle to avoid costly retrofits or market exclusion.
-
Trade policy friction: continued tariff adjustments on China-origin goods in strategic sectors increase the business case for diversified sourcing and regional production nodes.
-
Product innovation cadence: recent product launches and line extensions from leading players underscore a two-track innovation strategy—expand catalogue sizes for fast-moving SKUs while selectively developing ruggedized, certified products for high-growth verticals.
Practical strategic plays for 2026
-
Rebase product portfolios by margin contribution, not just revenue — rationalize low-margin SKUs where tooling and inventory drag ROI below company thresholds.
-
Optimize material mix: where polycarbonate pricing advantage exists, evaluate design swaps for equivalent performance; where ABS costs spike, pursue formulation blends or alternate polymer families for near-term relief.
-
Move to dual-source and geographically balanced supply footprints for critical resins and components; prioritize suppliers with validated compliance documentation to speed approvals.
-
Invest in compliance-as-a-service capabilities — materials declaration, test-lab partnerships, and documented chain-of-custody — as buyer requirements tighten in medical and enterprise tech markets.
-
Pursue bolt-on M&A to acquire specialty manufacturing (thermoforming, EMI-treated housings, or IP in sealed enclosures) that can boost realized ASPs and reduce dependence on commodity segments.
-
Deploy digital configurators and modular enclosure platforms to capture distribution revenue while reducing bespoke engineering costs; short lead-time, toolless product pathways can open medical and low-volume OEM opportunities.
How to use the full report
The full PW Consulting report contains the granular tables, regional and application breakouts, supplier scorecards and our scenario financial modeler that converts raw-material and tariff assumptions into P&L outcomes. This briefing purposefully omits detailed regional and application line-item disclosure to preserve the full dataset for buyers. For procurement teams, product leaders, and corporate development groups, the downloadable data pack and client workshop we provide turn findings into a 90–180 day execution roadmap.
Closing recommendation
With a projected rise from USD 6.25 Billion in 2025 toward the USD 9.4 Billion neighborhood by 2032 at a 6.0% CAGR, the electronic plastic enclosure market offers constructive growth backed by steady demand from consumer, industrial and automotive electronics. Yet the path to profitable growth in 2026 will be decided by three near-term capabilities: disciplined materials and cost management, demonstrable compliance and sustainability evidence, and operational agility to serve both catalogue and bespoke demand. PW Consulting’s full study equips leadership teams with the data, scenarios, and tactical playbooks needed to convert that market growth into durable margin expansion.
To obtain the complete report, regional and application breakouts, and the interactive scenario modeller, visit PW Consulting’s market reports page or contact our industry practice. The full package includes raw data downloads, supplier scorecards, and a tailored executive workshop to operationalize findings for 2026 planning.
For detailed analysis of this topic, please visit the official page: Electronic Plastic Enclosure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: BT Laminate Market Set to Expand at a 7.25% CAGR, Fueled by Asia‑Pacific Demand
By pmarketresearch, 2026-07-02
BT Laminate Market 2026 Strategic Brief: Navigating Cost Shock, Concentration, and Opportunity
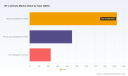
PW Consulting’s latest BT Laminate Market report (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes proprietary modeling, supplier-level intelligence, and scenario-based stress tests to give senior executives the decision-ready insights needed for 2026. Our analysis shows the global BT laminate market expanding from approximately USD 3,212.5 Million in 2025 to USD 5,243.5 Million by 2032, implying a compound annual growth rate (CAGR) of 7.25% over the forecast horizon. These headline figures underscore both resilience and structural change — but the near-term operating environment is where the most urgent strategic choices lie.
BT Laminate Market
Why this report matters for 2026 decision cycles
- Timesensitive procurement and pricing decisions: After an extended period of margin resilience, 2025–2026 has delivered sharp upstream cost shocks — from copper foil to electronic-grade glass cloth and specialty resins — that are forcing price pass-through decisions across the value chain. Our scenario models quantify the operating leverage and margin sensitivity for typical OEMs, substrate suppliers, and contract manufacturers.
- Concentrated supply base with strategic implications: The BT laminate market is highly concentrated. Our competitive analysis shows the top-tier players commanding the lion’s share of capacity and technology leadership. That concentration shapes negotiating dynamics, capacity allocation during cycles of tight supply, and the viability of near-term vertical integration moves.
- Regulatory and product-spec shifts: Accelerating adoption of halogen-free grades and lower-transmission-loss materials is creating bifurcated product roadmaps. Firms that can reconcile regulatory compliance with cost-effective process flows will capture disproportionate upside.
What executives will find actionable in the report
We designed this deliverable to be a playbook for 2026 strategy workstreams. The core assets include:
BT Laminate Market
- Demand-supply and price cascade models: Multi-scenario forecasts that map upstream input price moves to laminate cost curves and to downstream pricing elasticity. These models support three pricing-implementation templates: full pass-through, staged recovery, and margin protection via product mix optimization.
- Supplier risk heatmap and contingency plans: A weighted supplier-risk framework that combines concentration, geographic exposure, raw-material dependency, and technological differentiation. Each risk tier links to recommended tactical responses — from dual-sourcing playbooks to inventory buffering guidelines and JIT-to-JIC transition triggers.
- Technology and product readiness assessment: Comparative benchmarking of BT resin chemistries, low-warp formulations, and low-loss grades. The assessment includes manufacturing maturity scoring, retrofit cost estimates, and time-to-market roadmaps for process qualification cycles.
- Commercial playbooks: Negotiation templates and contracting structures (tiered pricing, indexation clauses, CPFR triggers) tailored to both buyers and producers to manage pass-through timing and protect margins during volatile input cycles.
- M&A and CapEx decision support: A prioritized list of capability and capacity gaps, complemented by valuation scenarios and synergies diagnostics for acquisition or greenfield investment. Our capital-allocation matrices help management prioritize capacity expansion, retrofits for low-loss grades, or investment in alternative substrate technologies.
- ESG and regulatory roadmaps: Compliance pathways for halogen-free adoption, supply-chain traceability templates, and product stewardship playbooks that align with global hazardous-substance regulations and customer procurement policies.
Competitive landscape — what our strategic read is
The BT laminate arena combines deep, technology-led incumbency with aggressive regional capacity investments. Our company dossiers synthesize technological strengths, geographic footprints, and product roadmaps for each major player. High-level takeaways:
BT Laminate Market
- Technology incumbency matters: Firms that pioneered BT chemistry and have continued materials R&D retain pricing power in advanced packaging and high-frequency applications. Their IP in low-warp and halogen-free grades serves as a barrier to low-cost entrants.
- Scale and product breadth are defensive moats: Large-scale copper-clad laminate producers with integrated upstream inputs have greater ability to smooth margin volatility and prioritize high-value customers during tight supply periods.
- Regional footprint is a competitive differentiator: Suppliers with multi-site manufacturing across Asia, North America, and Europe can manage logistics and regulatory variances more effectively and are preferred partners for global OEMs seeking supply resilience.
Representative strategic profiles (high level): Mitsubishi Gas Chemical retains deep technical leadership in BT resin technology and recently received industry recognition for next-generation low-warp grades — an advantage in high-density packaging. Major global material suppliers and laminate producers remain the primary capacity anchors, while several large Asian manufacturers are focusing on scale and cost competitiveness for high-volume segments. A subset of specialized suppliers competes on high-frequency and thermal-stability performance, addressing telecom, automotive, and semiconductor packaging niches.
Recent market shocks and what they signal
- Upstream cost inflation and an industry price response: In early 2026 a major supplier implemented a uniform price increase across several electronic-material product lines, citing raw-material and logistics cost pressures. This move crystallized margin compression risk across the supply chain and set a new bargaining baseline for pass-through negotiations.
- Supply constraints for key inputs: Glass-fabric availability tightened late in 2025 amid memory-sector strength and AI-driven demand. When raw-material tightness coincides with concentrated production, allocation risk rises rapidly and short-term spot premiums can spike.
- Regulatory-driven product migration: Demand for halogen-free and lower-transmission-loss BT formulations continues to grow, driven by both customer specifications and regulatory compliance. This creates a two-track market where premium, compliant grades command differentiated pricing and qualification timelines.
Strategic implications and recommended 90–180 day actions for 2026
For leadership teams planning 2026 budgets and operational priorities, the report translates market dynamics into a prioritized set of actions:
- Immediate (0–90 days): Run supplier exposure audits and implement short-term buy-side protections (indexation clauses, spot hedges for copper and glass cloth where economically justified). Activate contract-renegotiation templates and scenario-driven inventory thresholds.
- Near term (90–180 days): Accelerate qualification for alternative material grades and diversify sourcing across suppliers and geographies. Commission a cost-to-serve analysis to inform customer pricing strategies and margin preservation. Begin stress-testing planned CapEx against “high-cost” and “material-shortage” scenarios in our report.
- Medium term (6–18 months): Prioritize investments in low-loss BT variants and halogen-free process capabilities where ROI and customer funnel support. Consider strategic partnerships or bolt-on acquisitions to secure critical upstream inputs or to access differentiated resin chemistries.
Why PW Consulting’s dataset matters to you
The value of our report is the integration of market-level forecasting with supplier-level intelligence and executable templates. We combine a macro view — the market trajectory from roughly USD 3.21 Billion in 2025 to USD 5.24 Billion by 2032 at a 7.25% CAGR — with granular tools: cost-pass-through matrices, supplier-risk scores, technology-readiness assessments, and commercial contracting playbooks. That linkage from numbers to executable decisions is what makes this work actionable for 2026 planning cycles.
What we intentionally withhold here (and why)
Consistent with our “trailer” approach, this briefing demonstrates the analytical depth and strategic utility of the full report while intentionally omitting detailed subsegment splits, region-by-region revenue percentages, and proprietary supplier-level financials. Those datasets and the interactive models are included in the full report package and are best accessed directly to support confidential decision workflows and financial planning models.
Next steps — how to use this insight
- Download the full report and interactive workbooks to run supplier and price scenarios against your own demand profiles.
- Schedule a strategy workshop with our materials and procurement specialists to tailor the supplier heatmap and CapEx scenarios to your balance sheet.
- Engage our M&A advisory team to evaluate prioritized gap-filling targets or joint-venture structures that accelerate access to low-warp and halogen-free BT capabilities.
PW Consulting’s BT Laminate Market report is built for executive teams that need not just forecasts, but playbooks — tested, quantifiable, and ready for immediate deployment. For access to the full dataset, supplier dossiers, and customizable models that underpin these conclusions, please visit the report page and request the executive package.
For detailed analysis of this topic, please visit the official page: BT Laminate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 6.29% CAGR for Fiberglass Composite Rail Ties Market During 2026–2032
By pmarketresearch, 2026-07-02
Fiberglass Composite Rail Ties Market: Strategic Briefing for 2026 Decision-Makers
Executive summary
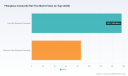
PW Consulting’s latest market study on Fiberglass Composite Rail Ties offers an operationally focused intelligence package tailored for executives, strategy teams, and procurement leaders planning 2026 initiatives. The market has shifted from niche specification to a scalable alternative for high‑decay zones and sustainability‑driven infrastructure programs. Our findings show a steady expansion in total market value — rising from approximately 178.5 Million USD in 2020 to 242.4 Million USD in the base year 2025 — and a projected compound annual growth rate (CAGR) of 6.29% across the 2026–2032 forecast window, taking the market toward roughly 371.8 Million USD by 2032. These macro dynamics create discrete windows for product development, supply chain repositioning, and commercial pilots; the report is designed to convert these windows into executable 2026 plans.
Fiberglass Composite Rail Ties Market
Why this matters for 2026 planning
-
Timing and scale: A mid‑single‑digit CAGR combined with accelerating replacement demand in certain geographies means that 2026 will be a year for capacity and commercial positioning, not merely R&D experimentation.
Fiberglass Composite Rail Ties Market -
Cost and risk profile: Raw material volatility — particularly in fiberglass and recycled plastics feedstocks — is material to unit economics. The sector will reward firms that pair technical differentiation with supply resilience and pricedown strategies.
Fiberglass Composite Rail Ties Market -
Standards and procurement gates: Compliance with rail authority standards (for example, widely recognized chapters that govern engineered composite ties) is a threshold requirement for mainstream procurement. Early alignment with testing protocols de‑risks pilot-to-scale transitions.
Market trajectory: what the numbers hide and reveal
The headline growth trajectory described above masks two important realities that frame 2026 choices. First, absolute market expansion is driven by a mix of replacement cycles in high‑decay zones, targeted transit projects, and bridge/tunnel applications where long life and environmental risk mitigation are prioritized. Second, growth is geographically and technically uneven: different tie constructions (e.g., long fiber versus continuous fiber systems) and application classes are evolving on distinct adoption curves. PW Consulting’s analysis identifies where early commercial traction is concentrated and where proof‑point investments are still required — we present directional momentum and scenario outcomes while intentionally reserving granular split data in this release to encourage direct engagement with the full study.
Dynamics shaping 2026 decision windows
-
Raw material supply and pricing: The fiberglass market experienced notable swings around late‑2025 and into 2026. After a period of moderation, upward pressure has resumed driven by raw material cost pass‑through, energy dynamics, and localized supply shortages. Procurement strategies that combine multi‑sourcing, indexed purchase agreements, and selective vertical integration will materially alter competitive cost curves.
-
Technical advances: Recent formulation work using recycled HDPE reinforced with high glass‑fiber loads and engineered fillers has improved flexural modulus and rigidity. These advances reduce barriers for mainline acceptance and open cost/performance tradeoffs that 2026 product roadmaps should exploit.
-
Regulatory and standards enforcement: Compliance with established design and performance frameworks is non‑negotiable for railroad buyers. Companies that institutionalize test rigs, third‑party validation, and variant documentation will shorten procurement cycles.
-
Sustainability and lifecycle economics: Composite ties made with recycled plastics and fiberglass offer end‑of‑life recyclability and eliminate creosote‑related hazards, enabling new procurement requirements tied to corporate ESG and public funding criteria. Lifecycle cost modeling, not simple upfront price comparisons, determines commercial viability in many tenders.
Competitive landscape: who to watch and why
The supplier base blends established composite specialists, plastics recyclers, and metal/wood incumbents adapting to new materials. Market concentration metrics indicate a sector that is neither fragmented nor tightly consolidated — there is room for national champions and specialist niche leaders alike. Key players we profile in the report exemplify the strategic archetypes buyers and investors should model:
-
Evertrak LLC — A North American player that emphasizes GFRP ties produced from recycled polyolefins and glass fiber, backed by product claims around 50‑year service life and standards alignment. A strategic investment by a major trading and manufacturing partner in early 2025 accelerated their production and distribution posture, signaling broader institutional capital interest in proven, recyclable GFRP systems.
-
EFG TieTek — An operational veteran focused on composite ties built from recycled plastics, rubber, and waste fiberglass with a diversified portfolio (cross ties, switch ties, bridge ties). Certification and longstanding production experience make them a reference point for technical maturity.
-
Triton Ties (Granite Peak Plastics affiliate) — Positions itself on extrusion technology and plastics recycling know‑how. Their strategy illustrates the value of marrying recycling scale with tie engineering to achieve competitive unit costs for mainline applications.
-
AGICO Rail and Pioonier — International entrants showing adoption pathways in metro systems and European markets, where processing patents and conformity to local standards facilitate municipal and transit procurement wins.
Recent supplier moves — strategic investment activity, refreshed technical messaging, and published formulation research — demonstrate how capital, branding, and R&D interact to accelerate readiness for larger tenders. PW Consulting’s supplier risk maps and partner suitability frameworks translate these dynamics into buy/partner/screen recommendations for 2026.
Strategic implications and prioritized actions for 2026
For executive teams building 2026 roadmaps, our analysis yields five prioritized decision areas that convert market growth into competitive advantage:
-
1) Launch targeted pilots aligned to replacement cycles: Prioritize pilot deployments in corridors where wood‑tie decay rates concentrate tie replacement volumes. Fast, well‑documented pilots shorten procurement lead times and create replicable case studies for network rollout.
-
2) Hedge raw material exposure: Implement layered procurement tactics — forward contracts where liquidity exists, indexed arrangements with major recyclers, and selective inventorying of critical glass fiber grades — to stabilize gross margins against 2026 price volatility.
-
3) Standardize testing and documentation: Invest in an in‑house or partner‑based testing regimen aligned with industry chapters that specify design, dimensional and performance equivalence to hardwood alternatives. This reduces technical objections during tender evaluation.
-
4) Prioritize lifecycle cost models over sticker price: Build TLCC (Total Lifecycle Cost and Carbon) models that incorporate maintenance intervals, expected service life, disposal or recycling credits, and environmental externalities to win tenders that weight sustainability metrics.
-
5) Pursue selective partnerships and M&A: Capital infusion and alliances — whether to expand capacity, secure feedstock, or acquire certification expertise — are becoming the faster route to scale than greenfield capacity alone. Monitor strategic moves by well‑capitalized buyers and engage with potential partners early.
What PW Consulting’s report delivers (practical components)
This study is built to be operationally useful in 2026. Among the deliverables:
-
Scenario models projecting demand and margin sensitivity across multiple raw‑material and adoption curves;
-
Supplier segmentation and suitability matrices, including production capacity, standards certification, and strategic fit;
-
Procurement playbook with contract structures, hedging options, and lead‑time mitigation tactics;
-
Pilot design templates and test protocols mapped to regulatory acceptance criteria;
-
Lifecycle cost calculators and ESG value capture frameworks for tender pricing and public funding submissions;
-
M&A and partnership scouting list with acquisition thesis and integration checklists targeted at 2026 consolidation scenarios.
To preserve commercial value for subscribers, the report presents detailed segmentation, regional and application revenue splits, and vendor share tables in the full document; this briefing intentionally focuses on strategic takeaways while directing practitioners to the full report for transaction‑grade numbers and supplier profiles.
How to use this briefing in 2026
-
Senior strategy teams: Use the scenario outputs to set capital allocation for 2026 R&D and capacity investments.
-
Procurement leaders: Adopt the playbook to design supplier panels and negotiate raw material supply terms keyed to expected demand curves.
-
Business development and product teams: Prioritize feature sets (mechanical performance, installability, recyclability) for pilot kits that can be validated under existing standards.
-
Investors and corporate development: Use supplier risk maps and concentration metrics to screen targets and co‑investment opportunities.
Closing perspective
Fiberglass composite rail ties are transitioning from an experimental substitute into a mainstream procurement option for segments of the rail network where longevity, environmental risk, and total lifecycle cost matter. Our market baseline and forecast quantify that transition, while the operational frameworks included in the full PW Consulting study translate those data into 2026‑ready actions. For decision‑makers aiming to move beyond pilots, the practical question for 2026 is not whether composites will matter — it is which organizations will have the contractual, technical, and supply‑chain scaffolding in place to capture that material demand growth. PW Consulting’s report is designed to be the scaffolding.
Download the full study and access vendor, regional and application level intelligence, as well as our proprietary supplier suitability tools, on the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Fiberglass Composite Rail Ties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ytterbium‑176 Market to Soar from USD 37.2 Million in 2025 to USD 175.95 Million by 2032 at a 24.85% CAGR — Top 3 Firms Command 88.42% Share
By pmarketresearch, 2026-07-02
Ytterbium-176 Market: Strategic Imperatives for 2026
PW Consulting’s latest Ytterbium-176 Market report (base year 2025; historical review 2020–2025; forecast 2026–2032) arrives at a pivotal moment for life‑science suppliers, radiopharmaceutical manufacturers, and strategic procurement teams. The market for enriched Yb‑176 has transitioned from niche research volumes to a commercially investable ecosystem—driven by the accelerating demand for no‑carrier‑added Lutetium‑177 production, advances in enrichment technologies, and deliberate policy shifts to diversify supply chains. Our analysis quantifies that transition and translates it into actionable options for executives planning investments, sourcing strategies, and regulatory engagement in 2026.
Ytterbium-176 Market
Why 2026 Is a Strategic Inflection Point
Between 2020 and 2025 the global Yb‑176 market expanded rapidly as capabilities matured and early commercial shipments began. PW Consulting’s baseline shows a multi‑fold increase in market size over that five‑year span, with continued momentum expected through 2032 under a compound annual growth rate of approximately 24.85%. The first forecast years (2026–2028) mark a shift from capacity demonstration to commercial scaling: producers that convert pilot output into repeatable, regulatory‑ready supply lines will define market leadership.
Ytterbium-176 Market
For corporate leaders, 2026 will not be a year to “wait and see.” It will be the year to convert strategic intent into operational positioning—securing long‑lead feedstock agreements, locking in manufacturing slots for Lu‑177 production, and embedding resilience in procurement contracts to mitigate geopolitical and regulatory risks.
Ytterbium-176 Market
What the Report Provides: Practical, Decision‑Ready Intelligence
- Market trajectory and scenario modeling. We present a base and alternative scenarios that reconcile historical shipments, announced capacity expansions, and plausible commercialization timelines—yielding forecast bands for planning and treasury modeling through 2032.
- Supply‑chain mapping and risk scoring. The report maps current producers, technology pathways (electromagnetic separation vs. laser‑based quantum enrichment), and bilateral dependencies. Each node is scored for capacity, ramp risk, export controls exposure, and time‑to‑certified supply.
- Procurement playbooks for buyers. Practical contracting templates and staging recommendations for the short (12 months), medium (12–36 months), and long (>36 months) horizons—covering MOQ strategies, quality acceptance criteria, and contingency clauses tied to irradiation cycles and Lu‑177 yield outcomes.
- Operational checklists for producers. Manufacturing readiness metrics (including feedstock sourcing, enrichment technology validation, impurity controls, and documentation needed for medical target manufacture) to accelerate regulatory acceptance by radiopharmacies and irradiation centers.
- Regulatory and compliance matrix. Consolidated guidance on nuclear safety standards, transport controls, export compliance considerations, and research‑use vs. commercial‑use distinctions that materially affect supply availability.
- M&A and strategic partner screening. A prioritized list of capability adjacencies—upstream enrichment, materials handling, irradiation capacity, and contract manufacturing—that create defensible value chains for entrants and incumbents alike.
Competitive Landscape: Technologies, Players, and Tactical Moves
The Yb‑176 marketplace is nascent but concentrated. A small set of specialized producers and government programs currently accounts for the vast majority of supply capacity; our competitive concentration metrics indicate a highly consolidated supply base. This concentration creates both a structural premium for secure supply and an opportunity for differentiated entrants to capture value through reliability, documentation, and service levels.
- Laser‑based entrants. Newer vendors deploying quantum enrichment laser systems have demonstrated faster theoretical enrichment pathways and lower footprint operations. These technology vendors are focused on demonstrating reproducible quality at commercial batches and translating lab results into certified supply chains.
- Electromagnetic‑separator incumbents. Established players using electromagnetic isotope separation have moved from proof‑of‑concept to commercial shipments, leveraging incremental capacity builds to serve initial customers with high‑purity material specifically tailored for medical target manufacture.
- Government and research suppliers. National isotope programs continue to play a role for R&D and capacity bridging, but their material is typically restricted to research quantities and not available as a full commercial supply solution. Nonetheless, their role in validating isotopic workflows and serving as strategic anchor providers cannot be understated.
Key industry movements in 2024–2025 already illustrate the reshaping of the ecosystem: commercial sample shipments by laser‑enrichment producers, capacity expansions by electromagnetic suppliers, and public announcements of commercial availability by established isotope firms. Taken together, these events signal a transition from scarcity to a more diversified commercial market—albeit one still dominated by a few players.
Risk and Opportunity: What to Watch in 2026
- Supply concentration risk. A small number of producers currently controls most commercial output. Buyers should prioritize multi‑sourcing strategies and contractual protections (e.g., supply assurance tiers and rollover options) to insulate irradiation schedules and downstream Lu‑177 production.
- Technology validation and quality parity. Not all enrichment methods are operationally equal when integrated into a medical‑grade production chain. Buyers and investors must evaluate not just isotopic purity claims but impurity profiles, material form (oxide vs. metal), documentation, and evidence of irradiation performance.
- Regulatory gating factors. Transport, handling, and export control regimes are evolving as governments aim to reduce single‑country dependencies. Firms should track policy shifts and align compliance roadmaps early to avoid operational delays.
- Commercialization cadence. Early entrants who demonstrated sample shipments in 2024–2025 still face the challenge of consistent, certified throughput. Monitoring production yields, lot reproducibility, and customer feedback will be essential to distinguish durable suppliers from one‑off producers.
How Investors and Strategic Buyers Should Use This Report in 2026
Executives can apply the report in three immediate ways:
- Portfolio prioritization. Use our scenario outputs to stress‑test capital projects and acquisition targets under different demand curves and supply ramp timelines. This is especially relevant for radiopharma firms planning to secure irradiation slots or for industrial players evaluating vertical integration into enriched targets.
- Procurement design. Implement layered sourcing frameworks: short‑term tactical purchases to maintain production runs; mid‑term contracts with capacity build options; and long‑term strategic partnerships to co‑finance upstream capacity expansions.
- Regulatory and stakeholder engagement. Allocate resources to documentation, safety case development, and export‑control compliance now—these investments reduce time‑to‑market advantages for new entrants and materially shorten commercial qualification periods for suppliers.
Case Illustrations (Non‑Exhaustive)
PW Consulting synthesizes public milestones and company disclosures into a practical set of lessons learned for 2026 planners. Examples include:
- Producers that paired technology demonstrations with early customer shipments built credibility faster; however, those that failed to publish qualification data struggled to convert pilots into recurring orders.
- Proactive buyers who negotiated conditional capacity options with multiple suppliers reduced their effective supply risk at marginal cost, compared with those relying on single‑source arrangements.
- Companies that integrated documentation and traceability into the handover from isotope supplier to irradiation facility significantly shortened regulatory review cycles for medical‑grade Lu‑177 synthesis.
What We Intentionally Omit (and Why)
In keeping with the “trailer” philosophy of this release, PW Consulting presents high‑confidence macro metrics and strategic guidance while reserving granular segmentation tables, region and end‑use breakdowns, and detailed price curves for subscribers of the full report. Readers seeking the complete data set—annualized market values by year, granular regional and application splits, supplier share tables, and facility‑level capacity schedules—should consult the full market study on our website.
Executive Recommendation: A 90‑Day Action Plan
- Supply assurance review: Map current and alternative suppliers; initiate contingency contracts for critical production slots.
- Technical validation: Commission independent analytical verification of isotopic and impurity profiles for any new supplier under consideration.
- Regulatory preparedness: Update transport and export‑control assessments and align quality documentation expectations with irradiation partners.
- Strategic scouting: Identify 2–3 potential M&A or JV targets—upstream enrichment or irradiation capacity—with the goal of securing optionality without bearing full build‑out risk.
Conclusion
The Ytterbium‑176 market is evolving from a constrained, research‑centric supply environment into a commercially viable segment with pronounced growth potential. PW Consulting’s report quantifies that pathway—with a strong historical growth trajectory and an aggressive forecast through 2032—while laying out the practical steps companies must take to translate market momentum into durable advantage. 2026 will reward organizations that combine technical due diligence, multi‑layered procurement, and regulatory foresight. For teams preparing capital allocations, vendor selection, or integration strategies this year, the full PW Consulting report delivers the underlying data and executable templates to move from strategic intent to operational certainty.
To access the full dataset, supplier profiles, and the detailed playbooks behind these insights, please visit the PW Consulting report page for the Ytterbium‑176 Market Study.
For detailed analysis of this topic, please visit the official page: Ytterbium-176 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modified Chlorinated Polyolefin Market to Rise from USD 345.5 Million in 2025 to USD 528.15 Million by 2032 at a 6.28% CAGR
By pmarketresearch, 2026-07-02
PW Consulting Releases Strategic Brief: Modified Chlorinated Polyolefin Market Outlook and Decision Framework for 2026
PW Consulting today publishes an executive-level briefing supporting our full research report on the Modified Chlorinated Polyolefin (MCPO) market — a focused, actionable intelligence package designed to inform boardroom decisions and commercial strategy heading into 2026. The MCPO market is exhibiting steady expansion: using 2025 as our base year, the global market is forecast to grow at a compound annual growth rate (CAGR) of 6.28% through our forecast horizon (2026–2032). Our scenario modelling projects clear upside for market participants that align product strategy, sourcing, and regulatory readiness with shifting end-market requirements.
Modified Chlorinated Polyolefin Market
Why this brief matters for 2026 decision cycles
-
Timing: 2026 will be a pivot year as OEMs and formulators accelerate adoption of low-VOC and waterborne adhesion promoters to comply with tightening environmental standards and corporate sustainability targets.
Modified Chlorinated Polyolefin Market -
Capital allocation: R&D, capacity expansions, and M&A decisions taken in 2026 will capture the compounding benefit of a predictable mid-single-digit market growth trajectory over the next six years.
Modified Chlorinated Polyolefin Market -
Risk management: Volatility in upstream polyolefin feedstocks and chlorine inputs is already exerting margin pressure — procurement hedging and supplier diversification are now strategic imperatives.
Market pulse — what the numbers tell us
Our market synthesis combines historical data (2020–2025), market interviews, and bottom‑up company intelligence to arrive at a high-confidence projection series for 2026–2032. The market demonstrates steady demand across coatings, inks, adhesives and specialty plastics applications, reflecting the continued need for adhesion promotion on low-surface-energy polyolefins. The growth profile and our scenario work provide a planning lens for executives preparing 3–5 year roadmaps:
-
Base-year anchoring: All recommendations are anchored to a 2025 base and reflect prevailing cost structures and regulatory baselines as of that year.
-
Mid-term trajectory: At a 6.28% CAGR to 2032, the market supports selective capacity additions and premium product launches but disfavors marginal investments in legacy solvent-heavy grades without clear differentiation.
-
Market structure: The market shows moderate concentration — the top three firms account for roughly 42.5% of industry supply, and the top five about 58.8% — leaving room for focused specialists and regional players to capture niche value.
Key dynamics shaping opportunity and risk
-
Regulatory push and product evolution: Global moves to restrict solvent emissions and certain chlorine‑related chemistries are accelerating reformulation. This trend is catalyzing investment into waterborne MCPO dispersions, acid‑modified variants, and low‑VOC co‑resins — a strategic pivot that incumbents and challengers must address.
-
Raw material volatility: Upstream exposure to polypropylene, polyethylene and chlorine makes feedstock procurement a primary margin lever. Firms with integrated sourcing, flexible feedstock options or long-term offtake agreements are better positioned to stabilize profitability.
-
End-use transitions: Automotive OEMs and industrial coatings buyers increasingly prioritize lifecycle and compliance metrics. Performance parity plus demonstrable environmental benefits will be required for premium positioning.
-
Geopolitical and logistics friction: Regional supply disruptions and freight cost variability are pushing customers to re-evaluate dual-source strategies and localize inventories for just-in-time manufacturers.
Competitive landscape — profiles and strategic implications
Our competitive chapter synthesizes corporate positioning, product portfolios, and route-to-market strengths of core market participants. Below are high-level strategic characterizations drawn from primary and secondary research:
-
Eastman Chemical Company — With broad capabilities in both solvent and waterborne CPO dispersions, Eastman is investing in low-VOC formulations and technical service to support OEM adoption. Their combination of application development expertise and portfolio depth creates a high barrier for new entrants targeting performance-sensitive segments.
-
Nippon Paper Group — Nippon Paper’s SUPERCHLON® platform demonstrates how legacy resin makers can translate polymer chemistry into differentiated adhesion promoters. Their strength lies in brand recognition for performance on polyolefins and established relationships with formulators in automotive and industrial coatings.
-
NAGASE America — As a distribution-led player with the Hardlen line, Nagase exemplifies the important role of channel partners in reaching specialty formulators and regional converters. Their value is in application know‑how and supply chain orchestration rather than high-volume manufacturing.
-
PhibroChem — Acting as a strategic partner and distributor for established technology owners, PhibroChem’s network accelerates market penetration for technology licensors and provides localized technical support for North American formulators.
-
Toyobo — Toyobo’s focus on maleic‑anhydride modified CPOs positions them to win in niche adhesive and lamination applications where bonding to polypropylene is mission‑critical. Their approach highlights the commercial value of chemically modified grades tailored to specific substrate challenges.
-
iSuoChem (Guangzhou Deco Chemical) — Representing agile manufacturing capability from China, iSuoChem competes on cost and rapid route-to-market for regional ink, coating, and laminating customers. They are a reminder that competitive pressure on price-performance will persist in commodity and semi‑specialty segments.
Collectively, these players demonstrate three winning strategic postures: (1) deep application expertise paired with advanced formulations, (2) channel and distribution orchestration, and (3) manufacturing-led cost competitiveness. Firms that blend two or more of these postures will be best positioned to capture profitable growth.
What the PW Consulting report contains — practical, board-ready outputs
Rather than an academic retelling of market history, our report is structured to support immediate commercial action. Highlights include:
-
A concise executive dashboard with scenario‑based forecasts (2026–2032) and downside/upside sensitivity tied to feedstock and regulatory shocks.
-
Actionable go-to-market playbooks for incumbent suppliers, specialty formulators, and distributors — including product migration roadmaps from solvent to waterborne platforms.
-
Procurement and hedging templates designed to translate volatile polypropylene, polyethylene, and chlorine markets into manageable procurement KPIs.
-
Pre-built M&A and JV screening matrices that align target attributes (technology, geography, customer access) to expected market value creation timelines.
-
Regulatory compliance pathways and reformulation checklists to accelerate approval and adoption of low‑VOC and waterborne solutions in automotive and industrial channels.
-
Competitor heatmaps and capability gap analyses mapping where new product introductions or service extensions would generate the most rapid ROI.
Note: Detailed regional and application segmentation tables, requested price benchmarks, and granular competitive share data are intentionally reserved for the full report to preserve strategic value and encourage direct engagement.
Strategic recommendations for executives planning in 2026
-
Prioritize waterborne and acid‑modified product development where regulatory pressure and customer sustainability mandates create a path to premiumization.
-
Embed feedstock risk management into commercial planning — secure multi‑year offtake or invest in vertical integration for critical polyolefin inputs where financially justified.
-
Evaluate concentrated M&A targets that provide application expertise or regional footholds rather than volume alone; accretive deals are more likely among specialists and channel partners.
-
Reconfigure commercial models to strengthen technical service capabilities — OEMs reward suppliers who reduce qualification cycles and lower total cost of ownership.
-
Build a phased reformulation playbook: pilot low‑VOC variants with strategic customers in 2026–2027, scale manufacturing in the 2028–2030 window as adoption matures.
How PW Consulting supports execution
We combine proprietary market modelling with hands‑on implementation support. Our full-service offering includes target screening for M&A, integration blueprints, and operational audits to reduce margin leakage across procurement and production. For firms planning product or geographic expansions, our market-entry packages include distributor selection, technical validation protocols, and local regulatory navigation.
Accessing the full intelligence
This release is a strategic preview designed to demonstrate the analytical depth of our MCPO research while reserving detailed segment-level data and tactical tools for clients and report purchasers. The full report (base year 2025, historical window 2020–2025, forecast 2026–2032) contains granular regional splits, application segmentation with price and volume trajectories, and downloadable decision-ready templates. Companies seeking to convert the report’s conclusions into concrete 2026 workplans can engage PW Consulting for a tailored briefing and war‑room session.
Contact PW Consulting to schedule a briefing and obtain the full Modified Chlorinated Polyolefin Market report and supporting strategic toolkits that will accelerate your 2026 planning and execution.
For detailed analysis of this topic, please visit the official page: Modified Chlorinated Polyolefin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SiC and TaC Coated Graphite Market Set to Grow at 11.2% CAGR Through 2032
By pmarketresearch, 2026-07-02
SiC and TaC Coated Graphite Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s latest market study on SiC and TaC coated graphite provides a focused intelligence package designed to inform executive decisions in 2026. The sector is entering a high-growth phase: our base-year assessment pegs the total market at USD 850.0 Million (2025), with a modeled compound annual growth rate of 11.2% across the 2026–2032 forecast window. Under the baseline scenario the market accelerates to roughly USD 972.6 Million in 2026 and approaches USD 1.79 Billion by 2032. These headline dynamics are clear evidence that coated graphite is transitioning from niche process inputs into strategic manufacturing enablers for advanced wafer processing and high-temperature device production.
SiC and TaC Coated Graphite Market
Why 2026 Is an Inflection Point for Buyers, Producers and Investors
-
Demand maturation: Multiple end-markets are moving from experimental to production scale, creating predictable recurring demand patterns for susceptors, trays and other coated-graphite consumables. This changes procurement from tactical buying to strategic supplier partnership models.
SiC and TaC Coated Graphite Market -
Concentration and control: Market concentration indicators show a relatively consolidated supplier base (CR3 ~62.4%; CR5 ~78.15%), which favors incumbent producers with scale, technical IP and validated quality systems — and elevates the risk for OEMs and contract manufacturers who lack alternative qualified sources.
SiC and TaC Coated Graphite Market -
Regulatory and tariff pressure: Recent trade interventions and tariff measures on graphite feedstocks are reshaping sourcing economics. These policy levers are active variables in our modeling and materially affect cost structures and supplier selection frameworks for 2026 sourcing strategies.
-
Signals from the field: Strategic moves — capacity expansions by established coating specialists and targeted asset acquisitions by materials groups — signal a supply-side response to long-term market growth and underscore the need for buyers to re-evaluate procurement horizons and risk exposure.
What Our Study Covers — Practical, Decision-Ready Intelligence (Preview)
-
Robust market-sizing and trend analysis through 2032 with scenario-based projections and sensitivity to tariffs, raw material availability and equipment adoption curves.
-
Supply-chain maps highlighting process steps (substrate specification, CVD/PVD coating options, post-coating treatments, testing and qualification timelines) and where value and risk concentrate.
-
Competitive landscape dossiers for the leading global suppliers — technology positioning, capacity footprints, commercial models and partnership plays — enabling buy-side benchmarking and supplier prioritization.
-
Actionable procurement tools: supplier scorecards, qualification checklists, a cost-to-serve framework calibrated to coated graphite, and negotiation playbooks tailored to short- and long-term contracting.
-
Investment and M&A screen identifying categories of targets (technology owners, regional capacity, aftermarket service providers) and financial metrics used in our buy-side valuation overlay.
-
Operational playbooks for plant and process engineers — coating selection guidance (SiC vs TaC tradeoffs), lifetime versus unit-cost analyses, and examples of real-world failure modes with mitigation checklists.
Competition Landscape — Who Matters and Why
-
Toyo Tanso Co., Ltd. (Japan) — recognized for proprietary CVD capabilities and branded product lines tailored to epitaxial and high-temperature uses. Their recent focus on capacity expansion for TaC-class products is an important market signal about demand for higher heat-resistance solutions.
-
SGL Carbon (Germany) — strong product portfolio for wafer processing and crystal growth, combining material science and scale to serve tier-1 semiconductor OEMs.
-
Schunk Xycarb Technology (Schunk Group, Netherlands/Germany) — differentiated by breadth across systems (EPI, RTP, CVD, PVD) and deep OEM relationships that often make them a ‘first-call’ supplier for complex tool programs.
-
Mersen (France) — focuses on quality and purity for high-reliability processes and serves customers requiring tight contamination control and lifecycle support.
-
Regional and specialist players — a cohort of suppliers based in China and the United States provide capacity, faster customization cycles and competitive cost structures. Their presence creates multilayered competitive dynamics where technical certification becomes the gatekeeper for supply contracts.
-
Smaller niche innovators — a handful of technology-focused firms are commercializing variants (e.g., porous substrates with specialized coatings, or cubic-SiC formulations) that may disrupt specific application pockets if they achieve scale and reliability.
Collectively, these provider profiles explain why CR3/CR5 concentration levels are moderate-to-high: scale and validated processes are required to meet OEM qualification cycles, which raises barriers to entry but also creates opportunities for M&A and strategic partnerships for those that can demonstrate predictable performance.
Regulatory & Raw-Material Shocks — Modeling Their Strategic Impact
The report models the direct and indirect effects of tariff scenarios and raw-material constraints that are active as policy levers today. For example, reinstated or new tariffs on certain graphite feedstocks materially change landed costs and push OEMs to consider nearshoring, dual-sourcing, or supplier-financing solutions. Our scenario set includes a baseline aligned to the 11.2% CAGR, an upside scenario where adoption accelerates and tariff disruptions are contained, and a downside where tariff escalations and supply bottlenecks delay procurement cycles. Each scenario maps to discrete operational triggers and recommended responses.
Actionable Strategic Playbook for 2026
-
Secure multi-year supply commitments with staged capacity release clauses to lock-in price and availability while retaining flexibility for technological pivots.
-
Segment suppliers by strategic value: anchor partners for mission-critical tooling, secondary partners for volume hedging, and specialist partners for novel coatings and rapid prototyping.
-
Pursue selective co-investment or offtake agreements in regions offering tariff or logistic advantages to mitigate near-term trade-policy risk.
-
Embed coating performance specifications and life-cycle metrics into qualification protocols to reduce unexpected replacement cycles and long-term TCO.
-
Monitor M&A pipelines: targeted acquisitions can rapidly buy capacity, regulatory approvals, or customer relationships; the market’s consolidation dynamics make timing and target selection critical.
-
Invest in supplier development and traceability programs to secure upstream feedstock quality and to prepare for extended producer responsibility or circular-materials programs.
How PW Consulting’s Report Adds Immediate Value to 2026 Decision-Making
-
It translates market growth trajectories into procurement and capital-allocation thresholds, enabling CFOs and procurement leaders to set contract terms and hedge strategies that align with projected demand ramps.
-
It distills competitive positioning into pragmatic partnership options and a shortlist of prioritized suppliers for rapid qualification.
-
It operationalizes regulatory scenarios into playbooks: what to do if feedstock tariffs persist, when to accelerate nearshoring, and how to price for pass-through vs absorb strategies.
-
It supplies engineers with coating-selection matrices keyed to process conditions and life-cycle economics rather than vendor claims, shortening qualification cycles and reducing production risk.
Next Steps and Where to Find the Complete Intelligence
This briefing is intentionally selective — it highlights the directional drivers and strategic levers you need now while withholding proprietary segmentation minutiae that are included in the full report. The comprehensive analysis contains granular, application-level size and growth data, supplier scorecards, detailed scenario outputs, and executable procurement templates — all designed for immediate deployment by corporate strategy, procurement and operations teams in 2026.
To review the full dataset, access supplier dossiers, or schedule a tailored executive briefing, please visit the PW Consulting publications page or contact our industry practice leads. For companies facing imminent sourcing choices or capital deployment decisions, we recommend commissioning a short-form workshop to apply the report’s scenarios to your specific supply footprint and product roadmap.
Closing Perspective
The coated-graphite market is shifting from episodic buying to programmatic procurement as device manufacturers scale new processes. With a robust baseline growth rate and strong signals of supplier consolidation and investment, 2026 will reward organizations that convert market intelligence into contractual certainty, targeted capacity exposure, and technical partnerships. PW Consulting’s SiC and TaC Coated Graphite Market report delivers the operationally usable insight your team needs to make prescriptive choices — while preserving the proprietary modeling and segmentation that differentiate actionable intelligence from generic commentary.
For detailed analysis of this topic, please visit the official page: SiC and TaC Coated Graphite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 13.98% CAGR for Bio-Based Superabsorbent Polymers Market in Hygiene Products Through 2032
By pmarketresearch, 2026-07-02
Bio-Based Superabsorbent Polymers for Hygiene Products: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive snapshot
The market for bio-based superabsorbent polymers (bio-SAP) used in disposable hygiene products — baby diapers, adult incontinence, and female hygiene — has moved from niche sustainability experiments to a nascent commercial wave. Our PW Consulting base-year assessment (2025) shows a global market valued at approximately USD 428.5 million, and our forecast model projects expansion to roughly USD 1,070.3 million by 2032, reflecting a compound annual growth rate (CAGR) of 13.98% for the 2026–2032 forecast window. Historical development between 2020–2025 demonstrates accelerating adoption as manufacturing validation, product launches and corporate sustainability commitments reduce non-technical barriers to uptake.
Bio-Based Superabsorbent Polymers (SAP) for Hygiene Products Market
Why 2026 is a strategic inflection point
-
Commercial validation is converging with supply-side maturation. Recent industrial-scale performance validation of fully bio-based formulations on diaper manufacturing lines and multiple product launches indicate that product-function parity is increasingly achievable for mainstream SKUs.
Bio-Based Superabsorbent Polymers (SAP) for Hygiene Products Market -
Sustainability credentialing and certification have migrated from marketing to procurement gatekeepers. Mass-balance ISCC approaches and biomass-balanced offerings are being used pragmatically to meet corporate targets while supply expansion continues.
Bio-Based Superabsorbent Polymers (SAP) for Hygiene Products Market -
However, bio-SAP economics remain delicate. Production cost differentials versus incumbent acrylic-based SAPs, feedstock price volatility (notably cornstarch swings) and spot feedstock price dynamics for intermediates create margin pressure and procurement complexity for buyers and suppliers alike.
-
For executives responsible for 2026 capex, sourcing, and product roadmap decisions, the intersection of demonstrated manufacturing compatibility and improving supply options makes this year the practical window to pilot supply contracts, secure offtake, and define go-to-market profiles for bio-SAP-containing SKUs.
What this PW Consulting report delivers (practical, decision-focused)
-
Bankable market sizing and scenario-driven forecasts (2026–2032) built from bottom-up demand drivers and manufacturer-validated adoption curves.
-
Technology readiness matrix that rates chemistries (starch-, cellulose-, bio-acrylic-, polyaspartic acid–based routes) by performance, manufacturability, biodegradability claims, and retrofit cost for existing hygiene converting lines.
-
Supplier and partner scorecards with commercial, technical and ESG attributes to support shortlisting and procurement negotiations.
-
Supply-chain stress-testing and cost-curve modelling that quantify the impact of feedstock price swings and production yield assumptions on landed cost.
-
Regulatory and certification playbook summarizing ISCC, mass-balance implications, and evidence packages buyers need for clean sustainability claims.
-
Adoption roadmaps and pilot templates (commercial, technical, and consumer validation) designed for OEMs, private label brands, and ingredient suppliers.
-
M&A and partnership playbook including screening criteria for target profiles and valuation sensitivities unique to bio-based SAP ventures.
Competitive landscape — who to watch and why
The competitive set is a mix of innovative start-ups, specialty intermediates providers, and incumbent chemical majors. Each player brings a distinct strategic vector — novel chemistry, feedstock control, manufacturing scale or certification credibility. Key strategic observations:
-
ZymoChem — A fast-moving innovator that has demonstrated scalable, fully bio-based, biodegradable SAP formulations engineered to run on industrial diaper lines. Its trajectory from launch to industrial validation points to a compelling supplier for OEMs seeking a single-supplier, plug-and-play alternative; potential acquirers and strategic partners should evaluate run-rate scalability and IP defense as primary diligence items.
-
NAGASE & Co. / Nagase ChemteX / Nagase Viita — A commercially oriented industrialization pathway with focus on high biomass content bio-SAP and near-term mass production readiness. Their approach is attractive to brand owners pursuing rapid scale with conservative performance risk profiles through established supply chains in Asia and Japan.
-
Planet Smart Products — Delivers fully bio-based, biodegradable SAP positioned as a drop-in replacement with attention to microplastics-free claims. For buyers prioritizing clean end-of-life narratives, Planet Smart represents an accessible supplier for early portfolio deployments.
-
Lygos — Pursues a bio-inspired chemistry route (polyaspartic acid derivatives) that could offer differentiated performance and sustainability trade-offs. Their technology is of strategic interest to formulators seeking alternative backbones that may sidestep feedstock concentration risks.
-
AquaSol Corporation — Focused on starch-based formulations with the commercial advantage of alignment to agricultural feedstock supply chains; their offering is relevant where agricultural integration and local sourcing reduce carbon intensity and logistics cost.
-
BASF and Nippon Shokubai — Incumbent chemical majors are converging on biomass-balanced routes and ISCC mass-balance approaches, giving them distinct advantages in certification, global logistics, and existing customer relationships. Their moves make them credible partners for large OEMs that prioritize supply security and scale.
-
ADM and A&B Smart Materials — Represent the upstream agricultural processing and specialty materials angles; ADM brings feedstock integration capabilities, while niche developers offer focused sustainability claims and compatibility with existing converting processes.
Market dynamics and risk matrix for 2026 decisions
-
Production economics: Bio-SAP routes currently carry a production cost premium versus conventional acrylic SAPs. Buyers negotiating in 2026 must weigh premium pass-through, blended-SKU strategies, and marketing ROI tied to sustainability claims.
-
Feedstock volatility: Cornstarch and other agricultural inputs show material annual price volatility; intermediate feedstock and acrylic acid market swings remain a commercial risk for producers and buyers alike.
-
Scale and line compatibility: While several suppliers report successful runs on industrial diaper lines, buyers should condition larger rollouts on multi-design, multi-line testing to avoid retrofit surprises.
-
Certification and claims: ISCC/mass-balance and biomass-balance frameworks are available, but translating certification into defensible consumer claims requires careful evidence trails and supplier traceability.
-
Concentration dynamics: The supplier base is diversifying but remains immature versus petrochemical SAP incumbents; strategic buyers should plan for staged multi-sourcing and risk-sharing structures during the 2026 scale-up window.
Commercial levers and recommended actions for 2026
-
Run targeted production pilots on representative SKUs and core designs before broad portfolio rollouts; require third-party performance validation as part of supplier contracts.
-
Negotiate staged offtake agreements with price collars tied to feedstock indices to mitigate input volatility while sharing near-term commercialization upside with suppliers.
-
Adopt blended SAP strategies that combine bio-based and conventional SAP to smooth cost and performance risks during the transition window.
-
Pursue vertical integration selectively — e.g., long-term supply contracts with upstream feedstock suppliers or joint investments in bio-acrylic capacity — where strategic scale and margin control justify capex.
-
Build consumer-facing sustainability narratives grounded in verifiable certification to protect brand equity and avoid greenwashing exposure.
Why PW Consulting’s report is the practical playbook for 2026
Our report is structured for decisions, not just insight. It combines bankable quantitative forecasts, a supplier diligence toolkit, techno-economic models you can re-run with your own assumptions, and contract templates and pilot protocols you can deploy immediately. The work is designed to shorten the procurement cycle, derisk pilot-to-scale transitions, and provide M&A-ready screening criteria for corporate development teams. We intentionally present deep strategic direction and operational tools while reserving the full segmented data tables and supplier-level commercial benchmarks for the complete report — to ensure those who need execution-ready figures access the full methodology and annexes.
Bottom line
Bio-based SAPs are no longer a speculative topic for R&D teams alone; 2026 is the year procurement, product and corporate development leaders must translate validated lab promise into commercial strategy. With a robust forecast horizon showing near-tripling market potential by 2032 (at a ~14% CAGR for 2026–2032), executives who use pilots, structured offtakes, and blended commercialization strategies will capture the value upside while containing execution risk. Read our full PW Consulting report to access the detailed segmented sizing, supplier scorecards, cost curves, and negotiation playbooks that underpin confident commercial commitments in 2026.
For detailed analysis of this topic, please visit the official page: Bio-Based Superabsorbent Polymers (SAP) for Hygiene Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Leucoxene Market Poised for 5.4% CAGR, Surging to USD 310.82 Million by 2032
By pmarketresearch, 2026-07-02
Leucoxene Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
As demand for higher-grade titanium feedstocks tightens and buyers search for supply resilience, PW Consulting’s latest Leucoxene Market report delivers the practical intelligence executives need to make confident 2026 decisions. Anchored in a comprehensive base-year review (2020–2025) and a detailed forecast through 2032, the study combines granular supply-side mapping, price scenario analysis and commercial playbooks—while purposefully reserving proprietary segment-level datapoints to encourage direct engagement with the full report.
Leucoxene Market
Executive Snapshot: Why Leucoxene Matters in 2026
Leucoxene sits at the intersection of metallurgical feedstock markets and specialty pigments. Our analysis finds the global leucoxene market to have grown steadily through the 2020–2025 base period, reaching an estimated market value of approximately USD 215.1 million in 2025. The market is forecast to expand at a steady compound annual growth rate (CAGR) of roughly 5.4% over the 2026–2032 horizon, reaching an estimated market size in excess of USD 300 million by 2032. This trajectory reflects durable end‑use demand and ongoing substitution dynamics among titanium feedstocks—drivers that will shape sourcing, pricing and project economics in 2026 and beyond.
Leucoxene Market
What This Means for 2026 Decision-Makers
-
Buyers (TiO₂ producers, welding consumables, titanium metal makers): Expect tighter quality differentials and episodic price volatility driven by feedstock quality mix and regional logistics. Procurement teams should prioritize flexible contracts with volume bands, quality-adjusted pricing clauses and access to alternative sources. Tactical reserve purchases and staged offtake agreements will de-risk feedstock continuity in the near term.
Leucoxene Market -
Producers and project developers: Greenfield and brownfield investments need to embed near-term price scenarios, capex sensitivity and ESG compliance costs into FID (final investment decision) triggers. Our modelling shows that relatively small shifts in feedstock quality or operating performance can materially affect project IRRs—underscoring the value of staged commissioning and contingency planning.
-
Investors and M&A teams: The market displays meaningful concentration among the leading players—top-three producers account for a majority share while the top-five capture a substantial portion of supply—creating opportunities for bolt-on consolidation, tolling agreements and strategic offtakes. However, expected regulatory scrutiny and supply chain due diligence mean that valuation premia should reflect both operational and ESG execution risk.
What the Report Delivers: Practical, Transaction-Ready Intelligence
PW Consulting designed this brief as an operational toolkit rather than a purely academic study. Key deliverables included in the full report are:
-
Validated market sizing and forward-looking demand scenarios —three-price-path forecasts linked to demand shocks, substitution rates and downstream capacity ramps.
-
Supply-chain heatmaps and vulnerability scoring —detailed node-level analysis of mineral sands origins, processing points, port logistics and single-point-of-failure risks.
-
Price sensitivity and margin modeling (spread decks) —interactive models showing how feedstock quality mixes influence downstream cost curves for pigment and metal producers.
-
Commercial templates and contract playbooks —practical clauses for quality acceptance, force majeure, demurrage and quality escrow tailored to leucoxene trade flows.
-
Project viability checklists and ESG due-diligence frameworks —including local permitting timelines, community engagement risk matrices and certification pathways for responsible mining standards.
-
Target screening for M&A and off-take partnerships —an anonymized short-list of acquisition and partnership targets with estimated integration synergies and downside scenarios.
These components are combined into an executive playbook that supports rapid decision cycles in 2026—whether the mandate is to secure feedstock, accelerate a project, or evaluate an acquisition.
Competitive Landscape: Strategic Profiles and Implications
The leucoxene supply chain is anchored by vertically integrated mineral-sands operators and select processors/distributors. Our report analyzes leading firms—highlighting strategic positioning, operational capabilities and near-term levers they may employ.
-
Iwatani Corporation (Japan) : Through its subsidiary operations in Western Australia, Iwatani controls high-value, primary leucoxene deposits that are differentiated by grade consistency. This gives it leverage in premium markets and targeting high-margin niche end-uses. Strategic takeaway: expect selective offtake and direct partnerships with pigment and specialty weld consumable makers.
-
The Kerala Minerals & Metals Limited (India) : As a state-backed supplier with integrated beach-sands separation operations, KMML is a stable regional supplier with strategic importance for South Asian manufacturers. Strategic takeaway: regional security of supply considerations will factor into long-term sourcing decisions.
-
Eramet (France) — Grande Côte Operations : Eramet’s marketing push around high-TiO₂ leucoxene (circa ~90% TiO₂) and attainment of recognized responsible mining performance levels underscore its dual commercial and ESG positioning. Strategic takeaway: premium product marketing and ESG credentials can command price and contracting advantages in quality-sensitive market segments.
-
Iluka Resources (Australia) : A major mineral sands producer, Iluka’s recent production reviews point to the market effects of variable feedstock quality. Strategic takeaway: buyers must hedge not just quantity risk but quality variability that can propagate through pigment and metal manufacturing costs.
-
Tronox Holdings Plc (United States) : As an integrated TiO₂ producer, Tronox’s vertical integration provides downstream demand security and internal balancing of feedstock quality. Strategic takeaway: integrated players can internalize price shifts, but they remain vulnerable to supply concentration at certain nodes.
-
Astron Limited, Kenmare Resources, Arima Minerals Processing, Mineral Global Trading : These regional developers, processors and traders play critical roles in bridging resource-rich locales with global demand centers. Strategic takeaway: nimble project developers and traders will be important arbitrageurs and partners for buyers seeking to diversify supply.
Market Dynamics & Emerging Risk Signals
-
Price environment: Benchmark reporting indicates bulk ilmenite and leucoxene pricing at roughly USD 400/ton f.o.b. Australia in 2025. While leucoxene commands premiums in grade-sensitive applications, the broader market follows the balance of ilmenite, rutile and slag supply trends—creating periodic re‑rating opportunities.
-
Supply concentration: The market exhibits concentrated supply: the top three and five producers capture a meaningful share of global availability. For buyers and new entrants, this creates both counterparty concentration risk and attractive arbitrage opportunities where smaller players can undercut or outcompete based on niche attributes.
-
ESG and certification: Responsible mining credentials are becoming commercially material. Recent certifications and public reporting by large producers are increasingly being embedded into purchase specifications and financing covenants.
-
Geopolitical flows: Geographic production footprints and cross-border concentrate flows affect availability. For example, production and trade flows from major producing countries continue to shape sourcing patterns for Asian and European consumers—a structural consideration for securing long-term supply.
Recommended 90‑Day Playbook for 2026
-
Immediate (0–30 days): Conduct a quality‑profile audit of current feedstock contracts; renegotiate acceptance tolerances and incorporate short-term flexibility clauses.
-
Near-term (30–90 days): Execute a dual-track sourcing strategy: secure a core anchor offtake with a high-credit, high‑quality supplier while piloting alternative suppliers and spot purchases to test logistics and quality assurance processes. Deploy PW Consulting’s spread models to stress-test margins under three price-path scenarios.
-
Strategic (90+ days): Assess acquisition or JV opportunities among regional developers and processors identified in our target short-list. Build ESG-compliance roadmaps for any potential transaction to accelerate financing and commercialization.
How to Use This Brief—and Where to Find the Full Intelligence
This press brief is designed as a decision-trigger: it summarizes the strategic levers and immediate actions that will matter in 2026 while intentionally withholding certain proprietary segmentation tables, supplier-by-supplier volumes and the full interactive financial models. Those proprietary deliverables are included in the complete PW Consulting Leucoxene Market report and accompanying data pack—resources that procurement, strategy and M&A teams should consult before committing to significant contractual or capital decisions.
For organizations preparing to bid, negotiate or invest in the leucoxene value chain in 2026, the full report provides:
-
Supplier scorecards and contact-ready outreach templates;
-
Downloadable Excel models with scenario toggles for price, quality and logistics;
-
Anonymized M&A target matrices and integration checklists;
-
Detailed ESG compliance pathways and certification comparators.
PW Consulting stands ready to support tailored engagements—ranging from rapid procurement due diligence to multi‑month transaction advisory—built around the levers and playbooks outlined above. To access the full report and the proprietary datasets that underpin our 2026 strategic recommendations, please visit the PW Consulting report hub.
For detailed analysis of this topic, please visit the official page: Leucoxene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low Alpha Spherical Alumina Market Poised for Rapid Growth at a 14.02% CAGR Through 2032, Led by Asia Pacific
By pmarketresearch, 2026-07-02
Low Alpha Spherical Alumina Market — 2026 Strategic Outlook
Executive summary
As semiconductor packaging and thermal management demands accelerate into 2026, low alpha spherical alumina has moved from a niche specialty material into a strategic procurement and R&D priority for semiconductor OEMs, advanced packaging houses, and materials formulators. PW Consulting’s newest market study — covering historical performance from 2020–2025 and a forward-looking forecast through 2032 — models a robust compound annual growth rate of approximately 14.0% and projects the market to grow markedly from its 2025 baseline. The market structure is highly concentrated (top-3 providers account for over eight in ten dollars of revenue, and top-5 capture more than nine in ten), creating both stability and strategic risk for buyers and new entrants.
Low Alpha Spherical Alumina Market
Why 2026 is a strategic inflection
-
Node scaling, memory stacking (HBM evolutions), and the broader shift to heterogeneous integration are forcing customers to re-evaluate filler and encapsulant chemistries to avoid radiation-induced soft errors — a technical domain where low alpha spherical alumina plays a decisive role.
Low Alpha Spherical Alumina Market -
Supply-side consolidation and elevated concentration ratios mean buyers face limited sourcing elasticity. Where historical demand shocks were absorbed via regional substitution, 2026’s tightening of qualifying cycles and quality expectations lengthens qualification lead times and elevates supplier leverage.
Low Alpha Spherical Alumina Market -
Raw-material and policy forces remain material to near-term margin dynamics: precipitation feedstocks and alumina intermediates have shown price volatility and regional differentials, while tariff regimes continue to create location-specific premiums that downstream strategists must price into sourcing decisions.
Market trajectory and what it means for strategic planning
Our forecast (2026–2032) constructs demand scenarios anchored to the strong historical growth observed through 2025 and an expected multi-year expansion driven by packaging, TIMs, and high-frequency substrates. Practically, executives should plan for a near-term environment where capacity ramp timelines, qualification cycles, and raw-material swings dominate supplier selection and product roadmap choices.
Key implications for 2026 decision cycles:
-
Prioritize multi-sourcing strategies early in the qualification pipeline to compress lead-time risk and avoid single-point exposure to concentrated suppliers.
-
Embed low-alpha performance targets and testing protocols into design-for-reliability workstreams; waiting for late-stage supplier qualification will materially delay time-to-market.
-
Revisit total-cost-of-ownership (TCO) frameworks to include tariff-affected premiums, logistics complexity, and qualification amortization rather than relying on unit price alone.
Competitive landscape — what we observe in supplier positioning
The competitive map of low alpha spherical alumina combines established high-purity specialty producers with regional scale players that have made rapid technical progress. The report’s supplier analysis synthesizes publicly disclosed R&D and commercial milestones, plant capabilities, qualification timelines, and go-to-market plays.
-
Long-standing specialty manufacturers with proprietary synthesis routes (e.g., vaporized-metal or fusion-based processes) are leveraging their high-purity heritage to target ultra-low-alpha grades needed for cutting-edge memory and packaging. Their strength lies in process control, documented low U/Th footprints, and long-term reliability data — assets that are costly and time-consuming to replicate.
-
Large materials groups and engineered-mineral producers are competing on scale, formulation support, and integrated supply chains aimed at TIMs, power modules, and EV battery thermals. These players translate controlled particle engineering and broad customer relationships into faster commercial rollout for thermal management applications.
-
Regional new entrants, particularly from China, are closing the qualification gap through multi-batch sampling and local co-development with advanced packaging customers. Their advantage is speed-to-volume and localized logistics; their risk exposure centers on consistency at scale and long-term purity assurance.
Recent public moves typify these trends: one incumbent specialty firm has accelerated R&D focused on next-generation HBM memory families to mitigate soft-error risk; another has confirmed commercial production of low-alpha grades for thermal conductive molding compounds and set multi-year revenue ambitions tied to advanced substrate demand. Collectively, these developments indicate both supplier willingness to invest in qualification cycles and the emergence of segmented go-to-market strategies — proprietary ultra-low alpha for critical packaging vs. engineered formulations for thermal applications.
Supply chain dynamics and raw-material sensitivity
Materials executives must manage two linked dimensions: feedstock and process energy. Precipitated intermediates (e.g., aluminum hydroxide) and regional alumina supply balances feed directly into cost curves for spherical alumina. Recent market intelligence points to notable price adjustments in certain markets during early 2026, influenced by downstream demand cycles and energy cost swings at precipitation facilities. Concurrently, trade policy effects (notably aluminum import measures) have generated location-specific premiums, which can materially alter landed costs for higher-purity inputs.
Consequently, manufacturers and buyers should adopt three practical supply-side actions in 2026:
-
Implement rolling two-to-three-year sourcing scenarios that layer spot, contract, and hedged feedstock positions to blunt single-point price shocks.
-
Quantify qualification cost and time explicitly in any supplier TCO model; for many advanced packages the cost of delayed qualification exceeds raw material cost differentials.
-
Stress-test capacity roadmaps against energy and bauxite/alumina availability scenarios — localized disruptions can cascade rapidly into specialty alumina backlogs.
What PW Consulting’s report delivers — practical, purchase-ready intelligence
The full report goes beyond high-level forecasting to equip procurement, product, and corporate strategy teams with actionable deliverables that are essential in 2026 planning cycles:
-
Supplier scorecards: technical capabilities, qualification footprint, capacity roadmap, and risk indicators calibrated to customer qualification timelines.
-
Techno-economic models: build vs. buy decision matrices, capex-to-throughput benchmarks, and sensitivity runs that incorporate feedstock and tariff scenarios.
-
Scenario playbooks: four discrete demand-supply trajectories (base, upstream-constrained, accelerated-HBM-adoption, and substitution-risk) with recommended commercial and operational responses for each.
-
Operational templates: qualification roadmaps, sample-flow timelines, and joint-development term sheets designed to shorten approval cycles without sacrificing reliability.
-
Risk register and mitigation matrix: covering geopolitics, single-source exposure, raw-material volatility, and regulatory change — with prioritized action items for 90/180/365 day horizons.
In keeping with our “trailer” approach, we outline these capabilities here at a strategic level; the full report contains the granular segment-level breakdowns, company benchmarking tables, and model inputs that buyers and investors require to execute with confidence.
How executives should use this report in 2026 decision-making
-
Procurement leaders: use the supplier scorecards and TCO models to re-baseline 12–36 month supply plans and to justify accelerated multi-sourcing investments.
-
R&D and packaging teams: integrate the qualification templates into product roadmaps and gate reviews; demand-side lead indicators in our scenarios identify when to accelerate material co-development.
-
Corporate strategy and M&A teams: the concentration metrics and supply-side capacity maps in the report are designed to highlight strategic bolt-on targets, partnership opportunities, and potential choke points worth remediation.
Concluding perspective
Low alpha spherical alumina is no longer a marginal inputs debate — it is a foundational materials decision that affects yield, reliability, and time-to-market for many of the highest-growth semiconductor and power electronics applications. Our forecast and supplier intelligence indicate a market at once expansive and concentrated: growth creates opportunity, but the concentration of supply and the cost/qualification dynamics create distinct strategic risk that must be actively managed in 2026.
PW Consulting’s report is intended as the operational playbook for executives who need to convert market growth into durable competitive advantage. For the detailed segment tables, supplier rankings, and model inputs necessary to validate sourcing, investment, or partnership decisions, please consult the full report and our interactive data tools on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Low Alpha Spherical Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com