

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: SiC and TaC Coated Graphite Market Set to Grow at 11.2% CAGR Through 2032

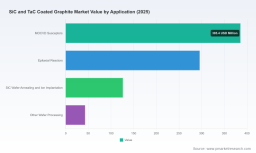
SiC and TaC Coated Graphite Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s latest market study on SiC and TaC coated graphite provides a focused intelligence package designed to inform executive decisions in 2026. The sector is entering a high-growth phase: our base-year assessment pegs the total market at USD 850.0 Million (2025), with a modeled compound annual growth rate of 11.2% across the 2026–2032 forecast window. Under the baseline scenario the market accelerates to roughly USD 972.6 Million in 2026 and approaches USD 1.79 Billion by 2032. These headline dynamics are clear evidence that coated graphite is transitioning from niche process inputs into strategic manufacturing enablers for advanced wafer processing and high-temperature device production.
SiC and TaC Coated Graphite Market
Why 2026 Is an Inflection Point for Buyers, Producers and Investors
-
Demand maturation: Multiple end-markets are moving from experimental to production scale, creating predictable recurring demand patterns for susceptors, trays and other coated-graphite consumables. This changes procurement from tactical buying to strategic supplier partnership models.
SiC and TaC Coated Graphite Market -
Concentration and control: Market concentration indicators show a relatively consolidated supplier base (CR3 ~62.4%; CR5 ~78.15%), which favors incumbent producers with scale, technical IP and validated quality systems — and elevates the risk for OEMs and contract manufacturers who lack alternative qualified sources.
SiC and TaC Coated Graphite Market -
Regulatory and tariff pressure: Recent trade interventions and tariff measures on graphite feedstocks are reshaping sourcing economics. These policy levers are active variables in our modeling and materially affect cost structures and supplier selection frameworks for 2026 sourcing strategies.
-
Signals from the field: Strategic moves — capacity expansions by established coating specialists and targeted asset acquisitions by materials groups — signal a supply-side response to long-term market growth and underscore the need for buyers to re-evaluate procurement horizons and risk exposure.
What Our Study Covers — Practical, Decision-Ready Intelligence (Preview)
-
Robust market-sizing and trend analysis through 2032 with scenario-based projections and sensitivity to tariffs, raw material availability and equipment adoption curves.
-
Supply-chain maps highlighting process steps (substrate specification, CVD/PVD coating options, post-coating treatments, testing and qualification timelines) and where value and risk concentrate.
-
Competitive landscape dossiers for the leading global suppliers — technology positioning, capacity footprints, commercial models and partnership plays — enabling buy-side benchmarking and supplier prioritization.
-
Actionable procurement tools: supplier scorecards, qualification checklists, a cost-to-serve framework calibrated to coated graphite, and negotiation playbooks tailored to short- and long-term contracting.
-
Investment and M&A screen identifying categories of targets (technology owners, regional capacity, aftermarket service providers) and financial metrics used in our buy-side valuation overlay.
-
Operational playbooks for plant and process engineers — coating selection guidance (SiC vs TaC tradeoffs), lifetime versus unit-cost analyses, and examples of real-world failure modes with mitigation checklists.
Competition Landscape — Who Matters and Why
-
Toyo Tanso Co., Ltd. (Japan) — recognized for proprietary CVD capabilities and branded product lines tailored to epitaxial and high-temperature uses. Their recent focus on capacity expansion for TaC-class products is an important market signal about demand for higher heat-resistance solutions.
-
SGL Carbon (Germany) — strong product portfolio for wafer processing and crystal growth, combining material science and scale to serve tier-1 semiconductor OEMs.
-
Schunk Xycarb Technology (Schunk Group, Netherlands/Germany) — differentiated by breadth across systems (EPI, RTP, CVD, PVD) and deep OEM relationships that often make them a ‘first-call’ supplier for complex tool programs.
-
Mersen (France) — focuses on quality and purity for high-reliability processes and serves customers requiring tight contamination control and lifecycle support.
-
Regional and specialist players — a cohort of suppliers based in China and the United States provide capacity, faster customization cycles and competitive cost structures. Their presence creates multilayered competitive dynamics where technical certification becomes the gatekeeper for supply contracts.
-
Smaller niche innovators — a handful of technology-focused firms are commercializing variants (e.g., porous substrates with specialized coatings, or cubic-SiC formulations) that may disrupt specific application pockets if they achieve scale and reliability.
Collectively, these provider profiles explain why CR3/CR5 concentration levels are moderate-to-high: scale and validated processes are required to meet OEM qualification cycles, which raises barriers to entry but also creates opportunities for M&A and strategic partnerships for those that can demonstrate predictable performance.
Regulatory & Raw-Material Shocks — Modeling Their Strategic Impact
The report models the direct and indirect effects of tariff scenarios and raw-material constraints that are active as policy levers today. For example, reinstated or new tariffs on certain graphite feedstocks materially change landed costs and push OEMs to consider nearshoring, dual-sourcing, or supplier-financing solutions. Our scenario set includes a baseline aligned to the 11.2% CAGR, an upside scenario where adoption accelerates and tariff disruptions are contained, and a downside where tariff escalations and supply bottlenecks delay procurement cycles. Each scenario maps to discrete operational triggers and recommended responses.
Actionable Strategic Playbook for 2026
-
Secure multi-year supply commitments with staged capacity release clauses to lock-in price and availability while retaining flexibility for technological pivots.
-
Segment suppliers by strategic value: anchor partners for mission-critical tooling, secondary partners for volume hedging, and specialist partners for novel coatings and rapid prototyping.
-
Pursue selective co-investment or offtake agreements in regions offering tariff or logistic advantages to mitigate near-term trade-policy risk.
-
Embed coating performance specifications and life-cycle metrics into qualification protocols to reduce unexpected replacement cycles and long-term TCO.
-
Monitor M&A pipelines: targeted acquisitions can rapidly buy capacity, regulatory approvals, or customer relationships; the market’s consolidation dynamics make timing and target selection critical.
-
Invest in supplier development and traceability programs to secure upstream feedstock quality and to prepare for extended producer responsibility or circular-materials programs.
How PW Consulting’s Report Adds Immediate Value to 2026 Decision-Making
-
It translates market growth trajectories into procurement and capital-allocation thresholds, enabling CFOs and procurement leaders to set contract terms and hedge strategies that align with projected demand ramps.
-
It distills competitive positioning into pragmatic partnership options and a shortlist of prioritized suppliers for rapid qualification.
-
It operationalizes regulatory scenarios into playbooks: what to do if feedstock tariffs persist, when to accelerate nearshoring, and how to price for pass-through vs absorb strategies.
-
It supplies engineers with coating-selection matrices keyed to process conditions and life-cycle economics rather than vendor claims, shortening qualification cycles and reducing production risk.
Next Steps and Where to Find the Complete Intelligence
This briefing is intentionally selective — it highlights the directional drivers and strategic levers you need now while withholding proprietary segmentation minutiae that are included in the full report. The comprehensive analysis contains granular, application-level size and growth data, supplier scorecards, detailed scenario outputs, and executable procurement templates — all designed for immediate deployment by corporate strategy, procurement and operations teams in 2026.
To review the full dataset, access supplier dossiers, or schedule a tailored executive briefing, please visit the PW Consulting publications page or contact our industry practice leads. For companies facing imminent sourcing choices or capital deployment decisions, we recommend commissioning a short-form workshop to apply the report’s scenarios to your specific supply footprint and product roadmap.
Closing Perspective
The coated-graphite market is shifting from episodic buying to programmatic procurement as device manufacturers scale new processes. With a robust baseline growth rate and strong signals of supplier consolidation and investment, 2026 will reward organizations that convert market intelligence into contractual certainty, targeted capacity exposure, and technical partnerships. PW Consulting’s SiC and TaC Coated Graphite Market report delivers the operationally usable insight your team needs to make prescriptive choices — while preserving the proprietary modeling and segmentation that differentiate actionable intelligence from generic commentary.
For detailed analysis of this topic, please visit the official page: SiC and TaC Coated Graphite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com