
Blogs
PW Consulting: Worldwide Dried Lemon Market to Reach USD 504.63 Million by 2032, Growing at a 6.8% CAGR
By pmarketresearch, 2026-08-18
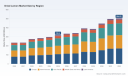
Worldwide Dried Lemon Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market brief on the Worldwide Dried Lemon Market distills the strategic intelligence senior leaders need as they finalize 2026 plans. Built from a systematic review of industry reporting, primary interviews, trade flows and price indices, the study synthesizes historical performance (2020–2025), sets an explicit base year of 2025, and delivers a seven‑year forecast through 2032. The market is projected to grow at a compound annual growth rate (CAGR) of 6.8% across the forecast window, reflecting resilient demand for dehydrated citrus ingredients across food, beverage, nutraceutical and specialty applications. This preview highlights the report’s practical value while deliberately withholding certain proprietary subsegment tables to encourage use of our full data package.
Disposable Suture Grasper Closure Device Market
Why this report matters for 2026 planning
-
Timing: 2026 is a pivot year—post‑pandemic reconfiguration of supply chains meets structural changes in ingredient sourcing and sustainability expectations. Executives who update sourcing, pricing and product roadmaps now will capture margin and share benefits as market dynamics normalize.
Worldwide Psychiatry EMR Software Market -
Scale and trajectory: The dried lemon market expanded materially through 2020–2025 and was valued at USD 318.4 Million in the 2025 base year. Our forecast shows continued expansion, with the market approaching a mid‑hundreds million USD opportunity by the end of the 2032 horizon—supporting investment cases for capacity, premiumization and downstream processing.
Internet Intelligent Elderly Care Service Platform Market -
Competitive context: The market remains fragmented (CR3 ≈ 18.5%; CR5 ≈ 28.3%), leaving meaningful space for differentiated offers, regional champions and scale consolidation—especially for players that can secure stable raw material access and deliver validated sustainability credentials.
Market trajectory at a glance
After an uneven recovery through 2020–2024, the dried lemon market posted renewed momentum in 2025. Our forecasted CAGR of 6.8% from 2026–2032 integrates price and supply shocks observed in late 2025 and early 2026, as well as growth drivers tied to convenience foods, beverage innovation, and nutraceutical formulation. While headline growth is attractive, the path to value requires targeted execution across sourcing, product differentiation and route‑to‑market strategies.
Supply‑side dynamics and near‑term risks
-
Raw material pressure: Multiple indicators point to constrained fresh lemon supply in the 2025/26 marketing year, including a projected global decline in fresh lemon and lime production. Parallel price signals—such as the uptick in U.S. Producer Price Index for farm lemons into early 2026 and elevated EU wholesale quotes—create immediate margin pressure for processors and exporters.
-
Processing and classification: International trade classification (e.g., HS code 0814.00 covering citrus fruit peel) continues to shape cross‑border movements and duty planning. Firms that optimize product specifications to minimize classification ambiguity will reduce friction and duty leakage in export markets.
-
Sustainability and traceability: Leading processors are accelerating investments in renewable energy and circular waste streams. Recent corporate disclosures demonstrate an industry shift from compliance to differentiation—producers that can document lifecycle emissions, water footprint and regenerative sourcing will command premium access to brands seeking verified inputs.
Demand drivers shaping product strategy
-
Formulation and convenience: Food and beverage manufacturers continue to favor stable, shelf‑ready citrus ingredients for flavoring, garnish and functional fortification. Innovations in powderization and volatile retention expand the addressable market for dried citrus beyond traditional uses.
-
Health and nutraceuticals: Renewed interest in vitamin C, botanical actives and gut‑friendly formulations supports higher value applications of dried lemon derivatives in supplements and functional beverages.
-
Premiumization of culinary and beverage segments: Co‑branded and artisanal product lines seek unique provenance claims (e.g., varietal, terroir, organic), which create differentiated pricing lanes for processors that can segregate and certify supply.
Competitive landscape — players to watch
The market’s fragmentation creates room for both global ingredient specialists and regional processors to capture niche leadership. Our review highlights a mix of integrated growers, dehydrators and ingredient conglomerates whose strategic moves will influence supply, pricing and innovation in 2026.
-
Lemon Concentrate S.L. (Spain) — A specialist in dehydrated peel and citrus inputs for industrial food processing, the company’s European footprint and focus on sauces and marinades position it as a key supplier to large food manufacturers.
-
Citrusvil (Argentina) — Vertically integrated from orchard to processing, Citrusvil’s sustainability initiative continues to support its global distribution model. Their emphasis on renewable processing aligns with rising buyer requirements for documented ESG performance.
-
Citromax (Argentina) — A producer focused on organic lemons and long‑term sustainable production, Citromax is strategically positioned to serve premium and certified organic channels.
-
Sunkist Growers & Dole (USA) — As major cooperatives and global fruit companies, these organizations provide scale and branded trust; their focus on quality dehydrated variants helps anchor mainstream foodservice and retail supply.
-
NutraDry (Australia), Van Drunen Farms, Limoneira (USA), Kerry Group (Ireland) — These firms represent the spectrum from specialist dehydrators to ingredient technologists, each contributing to innovation in powder forms, flavor systems and formulated ingredients.
-
EIC for Export (Egypt) — A notable bulk exporter with product relevance for spice, tea and specialty food processing markets—highlighting the continuing role of regional exporters in global spice and beverage value chains.
Recent developments reinforce these dynamics: Citrusvil’s sustainability announcements in early 2026, USDA FAS signals about organic peel expansion in the EU, and corporate financial disclosures from growers such as Limoneira collectively underscore how production, certification and forward guidance will shape 2026 sourcing and capacity decisions.
Strategic playbook for 2026
Based on the combination of market growth, price volatility and fragmented competition, PW Consulting recommends a set of prioritized actions for suppliers, brand owners and investors preparing 2026 budgets.
-
Hedge raw material exposure: Implement layered procurement contracts that combine fixed volumes, indexed pricing clauses and spot coverage. Scenario test cost pass‑through models for customers and incorporate margin protection in commercial agreements.
-
Segment selectively, without overextending: Pursue product variants that align with top‑line demand (e.g., premiumized powder formats for beverages, certified organic peel) but avoid broad SKU proliferation. Use pilot customers to validate premium claims before scaling.
-
Operationalize sustainability: Prioritize investments with rapid payback that also strengthen commercial positioning—solarization of drying facilities, water‑recycling, and traceability platforms. Account for these in R&D and capital plans as they increasingly unlock procurement preferences among large buyers.
-
Commercial partnerships and co‑development: Engage downstream beverage, flavor and nutraceutical partners in shared‑risk product development to accelerate adoption and secure long‑term off‑take agreements.
-
M&A and consolidation lens: Given low aggregate concentration, strategic acquisitions—particularly of regional processors with strong orchard linkages—remain an efficient route to secure feedstock and achieve scale synergies.
-
Regulatory and customs optimization: Audit classification and packing strategies to reduce trade friction tied to HS classifications and origin rules; small changes in product specs can materially affect landed costs in key export markets.
What the full PW Consulting report delivers
Our comprehensive report includes:
-
Methodology, data sources and a transparent model covering historical performance and forecast scenarios through 2032.
-
Proprietary demand‑side driver mapping and an assessment of growth vectors by form, application and channel (note: granular subsegment tables and region‑application grids are reserved for the full report and interactive dashboard).
-
Supply chain risk heatmaps, supplier scorecards and an actionable supplier segmentation framework that buyers and processors can use to prioritize partnerships.
-
Condensed M&A playbook and valuation benchmarks tailored for investors considering roll‑up and vertical integration strategies.
-
Commercial templates, KPIs and a 12‑month implementation checklist to convert strategy into execution.
How to use this intelligence in boardroom decisions
For 2026 planning cycles, treat this brief as the executive narrative and our full report as the tactical manual. Use the headline metrics—market scale, trajectory and concentration—to set investment envelopes. Then apply the procurement, sustainability and commercial playbooks to stress‑test budgets and prioritize capital allocation. Where uncertainty is highest (raw material availability and short‑term price swings), build contingency lines into operating plans rather than relying on single‑sourced assumptions.
Closing note — why PW Consulting
PW Consulting combines primary industry access with a pragmatic, implementation‑focused approach. Our dried lemon market study is designed to inform strategic choices without overwhelming stakeholders with raw tables; full subsegment analytics and the interactive forecast model are available through our client portal for executives who want the complete data set and executable templates.
Contact PW Consulting to arrange a briefing with our lead analyst team and obtain access to the full report and downloadable model—tailored workshops for procurement, R&D and M&A teams are available on request.
For detailed analysis of this topic, please visit the official page: Worldwide Dried Lemon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Educational & Training Software Market Poised for Rapid Expansion — 15.12% CAGR Forecast Through 2032
By pmarketresearch, 2026-08-18
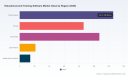
Educational and Training Software Market — Strategic Imperatives for 2026
PW Consulting’s latest market research on the Educational and Training Software Market provides a sharply actionable, executive-grade playbook for 2026 decision-makers. Anchored in five years of historical analysis (2020–2025) and a multi-scenario forecast through 2032, the report translates rapid market expansion, technology disruption, and evolving regulation into clear, prioritized choices for vendors, enterprise buyers, and investors.
Predictive Behavioral Analytics Softwares Market
Why 2026 is a Pivotal Year
The sector’s structural momentum is unambiguous. Between 2020 and 2025 the global market more than doubled, reflecting widespread digitalization across K‑12, higher education and corporate learning. By our base year (2025) the market has reached a scale that makes platform selection, content strategy, and AI governance strategic rather than purely tactical concerns. Looking forward, our forecast shows a sustained compound annual growth rate (CAGR) of 15.12% for the 2026–2032 period, with the market roughly trebling over the forecast horizon under the baseline scenario.
Pharma Grade Conjugated Linoleic Acid Market
For leaders planning budgets and M&A in 2026, this combination of scale and growth shifts the calculus: investments in interoperability, data governance, and AI-enabled learning pathways offer outsized returns relative to incremental content spend. Conversely, lagging on standards and compliance will create asymmetric downside as regulatory scrutiny tightens.
Oil Property Monitor Market
What PW Consulting’s Report Delivers
- Actionable market sizing and scenarios: A validated historical series to 2025 and three forward-looking scenarios through 2032 that quantify upside risk and downside contingencies for planning cycles and board discussions.
- Decision frameworks: Vendor selection matrices, ROI triangulation tools, and procurement scorecards tailored to distinct buyer personas (e.g., national education ministries, universities, enterprise L&D functions).
- Technology adoption blueprints: Roadmaps for migrating to cloud-native platforms, integrating generative AI capabilities, adopting standards-based assessment engines, and operationalizing data privacy controls.
- Go‑to‑market playbooks: GTM frameworks for vendors seeking to prioritize product investments, channel partnerships, and pricing models in 2026, with sample KPIs and churn-minimization tactics.
- Vendor and competitive heatmaps: Tactical profiles and capability assessments of the sector’s leading providers—highlighting differentiation vectors without disclosing proprietary benchmarking scores in this release.
- Compliance and risk mitigation modules: Practical checklists to align AI-enhanced offerings with emerging regulatory regimes, including high-risk AI classifications and data-protection expectations.
Key Strategic Insights for 2026 Decision-Making
- Prioritize composable architectures: Buyers should favor platforms that support modular integration—LMS, assessment engines, content repositories, and analytics services—because the pace of innovation (especially in AI) will make monolithic solutions brittle. The economics of switching costs and incremental functionality strongly favor composability in vendor evaluations.
- Invest early in AI governance and explainability: With generative AI now embedded in product roadmaps and national initiatives promoting AI literacy, organizations must build governance controls around pedagogical validity, bias mitigation, and auditability. Our practical templates enable procurement teams to score AI features on safety and pedagogical alignment.
- Turn compliance into a competitive asset: The regulatory environment — including guidance and enforcement in 2026 from supranational and national bodies — will redefine procurement criteria. Vendors that bake in compliance and transparent model governance will unlock larger public-sector contracts and partnerships.
- Measure learning impact, not just engagement: As customers demand demonstrable outcomes, focus metrics should shift from time-on-platform to competency attainment, transfer-to-job outcomes, and longitudinal ROI. The report’s outcome-mapping methodology helps buyers construct defensible business cases.
- Consolidation opportunity, but with an innovation premium: Market concentration remains moderate; the three- and five-firm concentration ratios indicate room for scale plays as well as specialist vertical winners. Strategic M&A that preserves product differentiation while accelerating cloud and AI capabilities will be rewarded.
Competitive Landscape: Who’s Moving and Why It Matters
The market’s leading commercial players are executing a mix of platform expansion, vertical specialization, and AI-led product innovation. Our qualitative analysis of incumbents and fast-scaling challengers reveals distinct strategic postures:
- Platform aggregators and marketplace players (e.g., Coursera): These providers are leveraging university and corporate partnerships to broaden credentialing, micro-credential pathways, and degree-completion offerings. Their competitive strengths lie in content breadth, brand association with top-tier institutions, and marketplace economics that scale well with demand.
- Consumer-first education apps (e.g., Duolingo): With engagement-driven product design and gamified learning loops, consumer apps are moving into adjacent categories (math, coding, soft skills) and proving the viability of learning-as-a-service models that can be adapted for corporate skilling.
- LMS incumbents (e.g., Instructure, Anthology/Blackboard): These firms maintain footholds in institutional procurement cycles. Their near-term challenge and opportunity is integrating AI-assistive tooling while modernizing architectures to support cloud-native deployment and seamless analytics.
- Corporate content specialists (e.g., Skillsoft, Pluralsight): Focused on professional reskilling and technical skill development, these vendors are competing on content depth, skill-path curation, and integration with enterprise HR systems and skill taxonomies.
- Cloud and platform titans (e.g., Microsoft, Google): Their strategic advantage is ecosystem integration—productivity suites, identity and device management, and increasingly, AI developer tooling. Recent 2026 initiatives from major cloud providers underscore the move to embed learning tools directly into daily workflows.
Recent developments—such as new AI-powered educator tools from major cloud providers, product innovations that automate personalized learning journeys, and national upskilling initiatives—validate our thesis that the race in 2026 is as much about platform ecosystem control as it is about content quality.
Regulatory and Macro Drivers to Watch
- AI-specific regulation: Emerging frameworks classify particular AI applications in education as higher risk and impose requirements for transparency, human oversight, and performance documentation. These regimes will meaningfully affect vendor roadmaps and procurement specifications in 2026.
- Public upskilling initiatives: Governments are rolling out AI-literacy and workforce development programs that create large-volume, low-margin demand — attractive for platform players that can deliver scalable, auditable outcomes.
- Standards and interoperability momentum: There is growing adoption of technical and data standards to enable credential portability and learning record stores; organizations that align early will reduce integration costs and accelerate cross-institution collaboration.
How PW Consulting Recommends Organizations Act in 2026
- For buyers: Run short, focused pilot programs that test composable integrations and learning-outcome metrics before committing to enterprise-wide deployments. Use the report’s procurement scorecards to compare vendors on governance, interoperability, and measurable outcomes rather than headline features.
- For vendors: Prioritize modular API-first designs, invest in robust AI safety and explainability features, and pursue partnerships that extend credentialing pathways into bona fide career outcomes. Consider disciplined bolt-on acquisitions that accelerate AI content creation or assessment automation.
- For investors: Target companies with defensible channels into public education and enterprise HR systems, clear paths to margin expansion via cloud economics, and demonstrable KPIs on learning-to-job transfer.
What We’re Not Releasing Here (and Why)
To preserve utility for procurement and investment workflows, the full report contains granular segmentation by deployment model, sector, region and product type, alongside vendor benchmarking scores and proprietary revenue splits. This release intentionally showcases strategic conclusions and practical tools while withholding the detailed subsegment tables and exact vendor metrics that organizations rely on for procurement or M&A diligence. That level of granularity is available in the full report and supporting data package.
Next Steps for Executives
PW Consulting’s report is designed to be immediately operationalizable in 2026 planning cycles. Clients can license the full dataset and toolkit for use in procurement RFPs, M&A diligence, and enterprise L&D strategy workshops. For executives preparing 2026 budgets, our recommendation is to reallocate a portion of content spend toward platform modernization, AI governance, and measurable outcome pilots—steps that the full report quantifies and prioritizes by expected ROI.
To explore the complete dataset, vendor profiles, and buy/sell playbooks, please consult the full PW Consulting publication and supporting tools on our website. Our analysts are available for tailored briefings and scenario workshops to translate the research into an actionable 90‑day roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Educational and Training Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modified Phenolic Resins Market Poised to Grow at a 5.29% CAGR, 2025 Insight Forecasts
By pmarketresearch, 2026-08-18
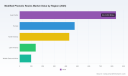
Modified Phenolic Resins Market: Strategic Imperatives for 2026 — PW Consulting Insights
As global manufacturers recalibrate for a new phase of industrial demand, Modified Phenolic Resins are re‑emerging as a strategic material class for adhesives, inks, coatings, friction materials and foundry applications. PW Consulting’s latest market model shows a steady expansion trajectory: the global market that stood below USD 1.6 billion in 2020 has approached the USD 2.0 billion mark by the 2025 base year, and our forecast projects continued growth at a compound annual growth rate (CAGR) of roughly 5.3% through 2032. For decision‑makers planning capex, sourcing and product strategy in 2026, that growth—coupled with shifting feedstock dynamics and an accelerating sustainability agenda—creates a narrow window of competitive opportunity.
Calcium Titanate for Ceramic Capacitors Market
Why 2026 is a Strategic Inflection Point
-
Supply‑side geometry is changing. Phenolic resins historically ride on the economics of phenol and downstream thermoset demand; between 2020 and 2025 we observed volatile but manageable swings in overall market value. With phenol prices moderating in 2025 and forecast ranges for 2026 dependent on benzene fundamentals, procurement teams must balance short‑term cost relief with medium‑term supply risk.
Separation and Purification Media Market -
Decarbonization and biomass substitution are now operational realities. Leading producers are commercializing lignin‑modified and other bio‑derived modifiers—reducing lifecycle carbon footprints while preserving performance attributes. These launches are not niche PR; they are influencing procurement specs and OEM sourcing decisions in plywood, friction applications and selected industrial end‑uses.
Self-curing Acrylic Resin Market -
Market structure favors focused differentiation. The industry’s concentration metrics indicate that top players command meaningful share without creating an impenetrable oligopoly—leaving room for specialized suppliers, toll manufacturers and regional champions to exploit niches or vertically integrate. This fragmentation underlines the strategic value of focused product and channel plays over blanket scale expansion.
-
Regulatory and customer requirements—especially on emissions and formaldehyde—are tightening selectively across jurisdictions. Manufacturers that can demonstrate lower emissions and certified biomass content are gaining preferential access to specification lists in construction and wood products sectors.
What the Report Delivers — Practical, Actionable Intelligence
We designed the Modified Phenolic Resins Market report as an operational toolkit for executives and technical leaders, not a static desk reference. Key deliverables include:
-
A robust market forecast model (2026–2032) with scenario branches covering demand‑led, supply‑shock and decarbonization accelerations—built to be re‑run with client‑specific inputs.
-
Supply‑chain stress tests and raw‑material sensitivity analyses that translate phenol, benzene and propylene movements into P&L and working capital impacts for typical resin portfolios.
-
Go‑to‑market blueprints for premium and commodity segments, including channel economics for tolling versus direct manufacture, and recommended KPIs for integration.
-
Commercial playbooks for low‑emissions product launches, including regulatory alignment, certification roadmaps and pricing levers that preserve margin while enabling volume adoption.
-
M&A / partnership screening—rapid assessment templates to identify bolt‑on assets, local tollers or biomass feedstock partners that deliver near‑term revenue accretion and long‑term resilience.
Competitive Landscape: Reading the Leaders
Our competitive analysis synthesizes corporate strategy, product portfolios and recent initiatives to reveal where incumbents are placing their bets. Several archetypes emerge:
-
Heritage formulators with sustainability R&D: Companies such as Sumitomo Bakelite and Prefere Resins are leveraging deep resin know‑how to commercialize lignin and other biomass‑modified grades. These players are moving beyond pilot announcements to industrialized offerings—an important signal that biomass substitution is migrating into mainstream procurement conversations.
-
Specialty, high‑performance-focused formulators: Hexion, DIC and SI Group continue to concentrate on electronics, aerospace and automotive niches that demand strict thermal, dielectric or mechanical performance. Their engineering sophistication enables higher ASPs and lower exposure to commodity cyclicality.
-
Toll manufacturers and regional champions: Plastics Engineering Company (PLENCO), Capital Resin Corporation and several agile players in Asia (including Polyols & Polymers) provide configurable supply models and multiple delivery formats—pastilles, powders, liquids—that large OEMs use to de‑risk manufacturing and shorten qualification cycles.
-
Integrated industrial suppliers: Producers with wood‑product, insulation or construction affiliations (e.g., Georgia‑Pacific Chemicals, Kolon Industries) use backward or forward integration to lock demand and optimize resin formulations for specific downstream processes.
Recent commercial moves underscore these dynamics. Notably, a major Japanese manufacturer commercialized a resol‑type lignin‑modified product in late 2024, marketing demonstrable lifecycle carbon benefits and certification credentials. That launch crystallizes two trends—first, that biomass substitution can be introduced without compromising key performance attributes; second, that credible third‑party certification amplifies commercial uptake by risk‑averse specification owners.
Raw Materials & Cost Dynamics to Watch in 2026
-
Phenol price trajectory. After peaking in earlier cycles, phenol softened through 2025. Market intelligence shows phenol moving from roughly USD 1.05/kg to the low‑USD 0.9x/kg band by 2025, with 2026 consensus reflecting a range driven by benzene fundamentals and recovery in adjacent polymer sectors. Procurement teams should plan for mid‑cycle volatility and embed dynamic price triggers into long‑term contracts.
-
Benzene and propylene linkage. Upstream feedstock swings—especially benzene and propylene—remain primary drivers of phenolic resin production cost. Regional cost differentials will persist, and North‑Asia sourcing economics warrant focused analysis for companies operating global supply footprints.
-
Biomass feedstock economics. Lignin and CNSL pathways are maturing but have distinct supply profiles and processing costs compared with petrochemical feedstocks. Early movers should quantify not only raw material costs but also processing CAPEX and certification timelines when modeling total cost of ownership.
Strategic Playbook for 2026: Five Actions for Executives
-
Operationalize feedstock diversification. Convert pilot bio‑formulations into commercial lines where upstream partnerships and certification can be secured. Prioritize feedstock trials that minimally disrupt existing cure and process windows to accelerate customer qualification.
-
Adopt scenario‑based procurement. Move from static long‑term contracts to blended strategies that combine fixed‑price volumes, indexed volumes and rolling call‑offs. Use the report’s sensitivity model to quantify how phenol swings map to EBITDA and to set hedging thresholds.
-
Differentiate through formulation services. For resin producers, offer application engineering and co‑development as a bundled service—this raises switching costs and shifts competition from price to value.
-
Fast‑track regulatory compliance as a commercial lever. Achieving demonstrated reductions in VOCs and formaldehyde, and securing biomass credentials, creates privileged access to spec lists in wood paneling, plywood and OEM parts specifications.
-
Execute selective M&A and toll partnerships. Identify regional tollers or specialty formulators that can be integrated quickly to capture demand in high‑growth subsegments without heavy CAPEX outlay.
Where PW Consulting Adds Value
PW Consulting’s report is designed for executives who need to act in 2026. Beyond the headline forecast and qualitative context, our deliverables include downloadable financial models, supplier heatmaps, qualification roadmaps for bio‑modified grades, and M&A playbooks tailored to different corporate archetypes (integrator, specialist, toll partner). We also package an interactive workshop that applies the model to a client’s portfolio, yielding a prioritized, executable roadmap with quantified ROI and implementation timelines.
We intentionally preserve granular segmentation tables and company‑level financials for the full report: this article follows a “trailer” principle—demonstrating methodological depth and strategic implications while directing commercial audiences to the complete data set for transaction‑grade decision‑making.
Next Steps
For procurement leads, product managers and corporate strategists, 2026 will be a year to convert optionality into differentiated capability. If you are planning raw‑material commitments, product launches, or inorganic moves in the resin space, access to segmented forecasts, supplier scorecards and our sensitivity engine is essential. Contact PW Consulting to license the full Modified Phenolic Resins Market report and schedule a tailored strategy session to convert the forecast into an executable action plan.
For detailed analysis of this topic, please visit the official page: Modified Phenolic Resins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: p,p'-Dibromobiphenyl Market to Grow at a 4.12% CAGR Through 2032
By pmarketresearch, 2026-08-18
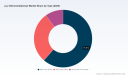
p.p'-Dibromobiphenyl Market Outlook 2026: Strategic Imperatives for Corporate Decision‑Makers
PW Consulting’s latest market brief on p.p'-Dibromobiphenyl arrives at a pivotal moment for companies operating across advanced materials, specialty chemicals, and pharmaceutical intermediates. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study synthesizes price signals, feedstock dynamics, regulatory pressures, and supplier capability to produce an actionable view for boardrooms and strategy teams. The market reached approximately USD 14.5 Million in 2025 and, at a compound annual growth rate (CAGR) of 4.12% through the forecast window, is projected to approach roughly USD 19.2 Million by 2032 — trajectory that is modest in headline size but strategically outsized given the molecule’s role as an enabler in high‑value downstream applications.
Door Profiles Market
Why this report matters in 2026
-
Material leverage: p.p'-Dibromobiphenyl functions as a core intermediate for OLED materials, liquid crystal polymers and other specialty chemistries. Small shifts in availability, quality distribution or pricing ripple into technology roadmaps and cost curves for device manufacturers, polymer formulators and research institutions.
Automotive Coordinate Measuring Machine Market -
Supply stress and cost volatility: recent raw‑material developments have materially altered the economics of brominated intermediates. Notably, bromine prices in China surged from roughly 28,000 RMB/ton in mid‑October 2025 to about 41,000 RMB/ton by late February 2026 — an approximate 46% move driven by tight supply. Concurrently, regional bromine benchmarks in early 2026 show variance (Northeast Asia reported near USD 6.16/kg in March 2026 while Europe was at USD 3.49/kg), underscoring regional supply chain arbitrage and input‑cost risk.
Engineering Research and Development Service Market -
Regulatory tailwinds and risks: 4,4'-Dibromobiphenyl appears under REACH monitoring in contexts related to polybrominated biphenyls (PBBs) due to concerns over persistence and aquatic toxicity. This evolving regulatory landscape creates both compliance costs and strategic opportunities for suppliers who can document high‑purity, low‑impurity manufacturing and robust stewardship.
Market dynamics — what the numbers tell us (and what they don’t)
The overall market’s measured expansion — from the mid‑teens USD million range in the early 2020s to an expected near‑double‑digit escalation by 2032 — indicates steady, technology‑linked demand rather than commoditized volume growth. This pattern matters: incumbents in concentrated supply chains can extract margin through quality differentiation, traceability and reliable logistics, while late entrants face gatekeeping by established formularies in electronics and pharma R&D.
Concentration metrics are instructive: the top three suppliers control a meaningful portion of market share, and the top five capture an even larger share — a structure that favors strategic partnerships, tolling agreements and capacity coordination over pure price competition. For procurement and corporate development teams, the practical consequence is that supply relationships and qualification cycles matter as much as unit costs.
Supply side: structural and near‑term considerations
-
Feedstock and upstream integration: The economics of p.p'-Dibromobiphenyl are intimately linked to biphenyl and bromine supply chains. Analysts’ view of the global biphenyl market — a larger but related feedstock market estimated in the low hundreds of millions USD in 2025 and forecast to rise in the coming decade — signals potential upstream volatility tied to benzene feedstocks and refining activity. Manufacturers with integrated bromination or secured bromine contracts are positioned to weather input shocks better.
-
Quality and qualification: End‑users in OLED and high‑performance polymers require narrow impurity profiles and documentation. Suppliers that offer certified purity grades, detailed analytical dossiers and small‑batch sampling capability achieve faster customer qualification and premium positioning.
-
Capacity and geographic footprint: A mix of specialty producers and larger chemical houses supply the market, with manufacturing clusters concentrated in Asia. Capacity flexibility (e.g., tolling, batch scale‑up) is a differentiator given episodic demand from electronics cycles and research procurement.
Competitive landscape — practical takes on key suppliers
Our competitive review evaluates supplier capabilities across four vectors: product quality and purity range, regulatory and documentation readiness, logistics and inventory footprint, and scale/flexibility. Below are distilled profiles of representative participants that illustrate the market’s competitive architecture.
-
Tokyo Chemical Industry Co., Ltd. (TCI, Japan) — A globally recognized specialty reagent supplier, TCI brings manufacturing discipline and extensive distribution channels. With product variants geared to organic semiconductors and lab applications, TCI’s stock‑in‑warehouse model and packaging options streamline procurement for small‑to‑medium research users.
-
Simson Pharma Ltd. and Pharmaffiliates (India) — These suppliers focus on pharmaceutical intermediates and analytical standards. Their strengths lie in regulatory awareness for pharmaceutical supply chains and in serving customers that demand reference‑grade material alongside commercial batches.
-
Alfa Chem and Chinese manufacturers (multiple firms) — Producers from China deliver breadth of supply, competitive unit economics and a range of documented physical specifications. Several of these suppliers highlight high‑purity offerings and export orientation, making them central to global sourcing strategies.
-
Deep Pharm Chem (India) — An ISO 9001 certified manufacturer that emphasizes production controls and assay performance; its presence underscores the role of certified quality systems in securing contracts with regulated buyers.
-
Export specialists (various) — Several suppliers position themselves for cross‑border trade to North America, Europe and Asia Pacific markets, supporting the qualification and logistics needs of multinational buyers.
Collectively, these firms reveal a market where differentiated service models (catalog reagent supplier vs. toll manufacturer vs. large‑scale chemical exporter) coexist. For buyers, matching supplier archetype to use case — analytical standard, pilot scale, or continuous supply for production — materially reduces time‑to‑qualification and total landed cost.
Strategic implications for 2026 corporate planning
-
Buyers should segment suppliers by strategic function: Reserve long‑term, volume contracts for manufacturers with documented capacity resilience and qualify catalog suppliers for R&D and lab needs. This two‑tier approach mitigates exposure to feedstock shocks while keeping innovation pipelines fed.
-
Invest in traceability and substitution pathways: Given regulatory monitoring under REACH and environmental scrutiny, firms should invest in impurity mapping, alternate chemistries where feasible, and forward inventory to cover regulatory delays.
-
Hedge exposure to bromine volatility: Input‑cost swings observed in late 2025–early 2026 advise the use of hedging strategies — long‑dated contracts, strategic bromine purchase agreements, or shared sourcing consortia among smaller buyers to stabilize supply and price.
-
Consider M&A and partnership plays: The market’s concentration suggests value in targeted acquisitions for vertical integration (bromination/halogenation capabilities) or strategic partnerships to secure guaranteed supply for high‑value downstream applications.
-
Prioritize certification and supply chain audits: Suppliers that maintain ISO standards, provide robust HSE documentation and can demonstrate low‑impurity manufacture will be preferred as regulators and customers heighten scrutiny.
Report contents — what PW Consulting delivers
Our full report is designed as an operational playbook for strategy, procurement, and product teams. Highlights include:
-
Market sizing and a transparent forecasting model with scenario analysis across demand shocks, feedstock volatility, and regulatory outcomes (base case, constrained supply, and accelerated regulation scenarios).
-
Supply chain heat maps and supplier scorecards evaluating technical capability, documentation readiness, capacity flexibility, and commercial terms.
-
Cost build‑ups and sensitivity analyses linking bromine and biphenyl inputs to landed cost at different trade points.
-
Practical go‑to‑market frameworks for suppliers (product positioning, purity premium strategies, and channel segmentation) and procurement playbooks for buyers (qualification pathways, dual‑sourcing templates, and inventory governance).
-
Regulatory tracker and compliance checklist focused on REACH monitoring and other jurisdictional obligations affecting production, waste handling and exports.
-
M&A and partnership screening, including valuation levers keyed to capacity, certification and customer concentration.
Methodology and data integrity
The study integrates proprietary supplier intelligence, third‑party pricing data, and primary interviews with industry stakeholders. The base year is 2025, with historical analysis covering 2020–2025 and forecasts constructed for 2026–2032. We apply a blended demand model that ties application‑level uptakes (consumer electronics materials, specialty polymers, laboratory reagents and specialty synthesis) to macro technology adoption curves, while conservatively modeling substitution and regulatory impact. Where public pricing benchmarks are volatile — notably bromine indices — our sensitivity layers present low, mid and high impact paths for decision use.
Next steps — how to use this insight
For executive teams, this brief functions as an orientation that converts market movement into prioritized actions: secure supply for critical applications, accelerate supplier qualification where purity and documentation give competitive leverage, and evaluate strategic investments to stabilize feedstock exposure. For procurement and product teams, the full report provides templates and supplier scorecards that materially shorten qualification timelines and improve negotiating positions.
PW Consulting’s full p.p'-Dibromobiphenyl Market Report contains the granular segmentation, supplier profiles, and downloadable data tables that corporate teams use to execute. For organizations that require an executable roadmap for 2026 — from hedging tactics to M&A screening — the full dossier provides the numbers and playbooks to move from insight to action.
Contact and access
Access to the comprehensive dataset, detailed supplier scorecards and scenario models is available via PW Consulting’s report distribution channels. Our team stands ready to provide bespoke briefings and rapid‑turn advisory to translate findings into procurement contracts, supplier audits, or strategic investments.
For detailed analysis of this topic, please visit the official page: p.p'-Dibromobiphenyl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aldehyde‑Free Disinfectants Market to Grow at 6.42% CAGR, Surpassing USD 11.2 Billion by 2032 (Base Year 2025)
By pmarketresearch, 2026-08-18
Worldwide Aldehyde-Free Disinfectants Market: Strategic Signals for 2026 — A PW Consulting Preview
As healthcare, food service, and institutional operators confront ongoing infection-prevention pressures and tightening regulatory scrutiny, aldehyde-free disinfectants are no longer a niche alternative — they are strategic imperatives. PW Consulting’s forthcoming Worldwide Aldehyde-Free Disinfectants Market report (base year 2025; forecast 2026–2032) synthesizes primary research, regulatory scanning, and proprietary scenario modelling to equip senior leaders with the directional intelligence they need to make high-consequence decisions in 2026.
Hydraulic/Pneumatic Rotary Joints Market
Why this market matters now
Our model shows the aldehyde-free disinfectants market continuing on a structurally positive trajectory, underpinned by sustained demand from healthcare and institutional end users, regulatory momentum in favor of lower-toxicity chemistries, and steady innovation in alternative actives and delivery platforms. PW Consulting’s forecast horizon captures an expected compound annual growth rate (CAGR) of c. 6.42% through 2032 — enough growth to attract new entrants, justify R&D investments, and reshape procurement strategies, but not so rapid as to eliminate competitive differentiation.
Containerized Mobile Renewable Energy Unit Market
For corporate strategists, product chiefs, procurement leaders, and private equity investors preparing 2026 plans, that trajectory creates three immediate lines of opportunity: (1) accelerate validated, market-ready aldehyde-free formulations into priority channels; (2) shore up regulatory and supply-chain resilience for alternative actives; and (3) evaluate selective M&A and partnership plays that close capability gaps without overpaying for scale in a moderately concentrated market (CR3 ~31%; CR5 ~43%).
AI in Machine Vision Market
Report highlights: what PW Consulting delivers (practical, action-oriented)
- Robust market sizing and calibrated scenarios — Transparent methodology detailing how we harmonize statutory filings, vendor disclosures, and in-field purchase data to produce a defensible market baseline and three policy/technology scenarios to stress-test planning assumptions for 2026 budgeting cycles.
- Regulatory risk matrix — A prioritized map of near-term regulatory vectors (global and major markets) with likelihood-impact scoring and playbooks for label claims, registration acceleration, and contingency responses.
- Technology and raw-materials playbook — Comparative assessment frameworks for dominant aldehyde-free actives (quats, accelerated peroxides, citric-based chemistries and emergent alternatives), including efficacy envelopes, material-compatibility constraints, occupational safety profiles, and supplier concentration risks.
- Commercial route-to-market blueprints — Channel segmentation and go-to-market options tailored to healthcare, food & beverage, and institutional buyers; pricing levers and tender playbooks to optimize margin capture without eroding adoption.
- Supply-chain and procurement toolkit — Sourcing scorecards, contingency planning templates, and recommended KPIs to reduce single-source exposure while controlling total cost of ownership in volatile raw-material cycles.
- M&A and partnership screening — An actionable shortlist methodology for targets (technology acquirers, formulation specialists, regional scale players) with high integration-readiness and defensible synergies; valuation sensitivities modeled under multiple regulatory outcomes.
- Operational implementation guides — Laboratory-to-market validation checklists, label-claim optimization procedures, and commercial pilot templates to compress time-to-adoption in large institutional customers.
Competitive landscape: capabilities, gaps and strategic moves
The market is shaped by a mix of large, diversified hygiene conglomerates and specialized disinfectant innovators. Leading incumbents combine deep distribution, regulatory affairs resources, and broad product portfolios that span concentrated chemistries and ready-to-use formats. Several firms stand out for distinct reasons:
- Ecolab Inc. — Strengths: extensive institutional and healthcare penetration, capabilities in concentrated systems and dosing platforms, and continued investment in active-ingredient innovation. Recent regulatory wins around new actives highlight Ecolab’s ability to translate science into scalable products for high-risk environments.
- Reckitt Benckiser Group — Strengths: consumer and institutional brand recognition, large-scale manufacturing and distribution networks, and acceleration of hospital-grade, aldehyde-free surface disinfectants under established brand architectures that facilitate adoption.
- STERIS plc — Strengths: deep healthcare relationships and expertise in device reprocessing and facility-level infection control; advantage in selling integrated service and product bundles to hospitals.
- 3M Company — Strengths: cross-disciplinary R&D and product engineering, regulatory depth, and broad reach into industrial and healthcare segments where material compatibility and occupational health are critical.
- The Clorox Company — Strengths: heritage in surface disinfection, institutional contracts, and rapid go-to-market capability for hospital-grade formulations that are aldehyde-free.
- Diversey, GOJO, Paul Hartmann, B. Braun, Virox — Strengths: varying mixes of specialized formulations, strong ties to healthcare procurement, and focused technology bets (e.g., accelerated hydrogen peroxide, citric-based chemistries, quat-free options) that position them as attractive acquisition or partner candidates for larger platform players.
Competitive dynamics are evolving: larger players use scale to secure formulary placements, while smaller innovators attempt to leapfrog through differentiated actives and sustainable claims. PW Consulting’s report examines these dynamics in detail, including readiness-to-scale assessments and three playbook archetypes for incumbents, scale-ups, and new entrants.
Regulation, innovation and raw-material dynamics shaping 2026 choices
Regulatory flux is a dominant near-term consideration. In 2025 the US EPA significantly increased disinfectant registrations, reflecting renewed attention to alternative actives and label claims. This environment rewards companies that can combine rigorous efficacy evidence with nimble registration strategies. At the same time, certain high-level aldehydes (e.g., ortho-phthalaldehyde) have known clinical safety caveats in specific applications, reinforcing demand for lower-toxicity options and for manufacturers to clearly delineate use-case boundaries.
From a raw-material perspective, aldehyde-free formulations depend on a narrower but rapidly innovating set of actives — quaternary ammonium compounds, accelerated peroxides, citric-acid derivatives and other emergent chemistries. Each option brings trade-offs in efficacy spectrum, material compatibility, residue profile, and cost volatility. Our technical-economic matrices quantify these trade-offs and prescribe procurement and hedging tactics tailored to company size and exposure profile.
Five strategic moves for 2026
- Prioritize label-claim speed and defensibility — Allocate regulatory and clinical-validation spend to secure the specific claims that unlock hospital and institutional formularies. Fast-cycle, real-world efficacy pilots can shorten procurement approval timelines.
- Adopt a hybrid sourcing strategy — Combine multi-sourcing for critical actives with strategic long-term partnerships to stabilize pricing and ensure supply continuity in a market where certain inputs are increasingly specialized.
- Invest in differentiated delivery platforms — Value accrues not just from the chemistry but from how it is delivered (e.g., dosing systems, safe-use formulations, reduced-contact protocols). Packaging innovation and compatibility with existing dispenser infrastructure accelerate adoption.
- Pursue targeted M&A with integration discipline — Look for bolt-on targets that fill technical gaps or provide regional footholds; use staged-earnouts tied to regulatory approvals and commercial milestones to manage execution risk.
- Embed sustainability and occupational safety in product positioning — Buyers increasingly value formulations that reduce worker exposure and environmental impact; credible LCA-backed claims and third-party validations generate commercial uplift.
What we intentionally withhold — and why
In keeping with PW Consulting’s “trailer” publishing approach, this preview surfaces strategic conclusions, methodological transparency, and actionable frameworks while withholding our full granular segmentation and proprietary subregional and application-specific revenue breakdowns. Those detailed splits, channel-level unit economics, and vendor-by-vendor share estimates are core deliverables within the full report and are provided to paying clients to preserve the utility of our primary research investments.
How to use this intelligence in your 2026 planning cycle
Corporate leaders should treat this intelligence as a decision-enabling input: incorporate the report’s scenarios into budgeting cadences, use the regulatory risk matrix to prioritize label investments, and apply the M&A screening filters when evaluating pipeline targets. Procurement and operations teams should adopt the supply-chain toolkit to de-risk exposure to single-source raw materials ahead of expected demand spikes tied to tender competitions and hospital procurement cycles.
Next steps
- Download the executive summary and methodology brief on PW Consulting’s website to review our data sources and scenario assumptions.
- Engage with our advisory team for a tailored 90-minute briefing that aligns the report’s implications to your commercial, R&D, or M&A agenda for 2026.
- Commission a bespoke deep-dive — we offer custom market models and supplier due diligence packages for transaction support and portfolio optimization.
PW Consulting’s Worldwide Aldehyde-Free Disinfectants Market report equips decision-makers with a pragmatic blend of market foresight, regulatory navigation tools, and executable commercial playbooks. In a market growing at an anticipated mid-single-digit CAGR and rebalancing around safer, more compatible chemistries, the 2026 planning window is an inflection point: move with evidence, protect supply, and prioritize the regulatory claims that open the largest institutional doors.
For detailed analysis of this topic, please visit the official page: Worldwide Aldehyde Free Disinfectants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Integrated Workforce Mobility Market Poised to Hit USD 28.69 Billion by 2032 at a 10.25% CAGR
By pmarketresearch, 2026-08-18
Integrated Workforce Mobility Market — 2026 Strategic Briefing for C-Suites
Executive snapshot
In an era where talent is borderless but compliance, experience and security are not, the Integrated Workforce Mobility market is entering a decisive inflection. PW Consulting’s latest market study (base year 2025, historical 2020–2025, forecast 2026–2032) quantifies a clear trajectory: the market expands from an estimated USD 14.5 Billion in 2025 to roughly USD 28.7 Billion by 2032, growing at a compound annual growth rate (CAGR) of approximately 10.25% during the forecast window. For executives planning capital allocation, program design, or M&A activity in 2026, the question is no longer whether to invest in workforce mobility capabilities but how to architect capability stacks that convert scale, compliance and user experience into measurable business outcomes.
1.6T High-speed Optical Modules Market
Why 2026 is a strategic pivot year
-
Momentum meets regulation: After multi-year adoption of hybrid and remote working models, enterprises are shifting from ad hoc fixes to integrated platforms that unify immigration, tax, payroll, security and device/application management. This market movement is reflected in the robust mid‑teens growth profile PW Consulting documents—sustained, broad-based expansion driven by technology modernization and programization of mobility services.
Portable LED Light Facial Device Market -
Infrastructure enables functionality: Recent regulatory and infrastructure initiatives—ranging from national broadband and spectrum priorities to advanced network buildouts—are lowering the operational friction for data‑intensive mobility tooling. These changes materially increase the attainable addressable market for richer real‑time orchestration, analytics and edge-enabled employee experiences.
Surface Grinding Services Market -
Economic and talent pressures compress timelines: Talent scarcity in key skills and a renewed focus on cross-border assignment cost‑efficiency means mobility decisions are being pushed higher up the agenda and accelerated into 2026 budgeting cycles.
Core market dynamics shaping 2026 decisions
-
Convergence of services and platforms — The market is shifting from siloed offerings (tax, immigration, relocation operations, device management) toward integrated delivery models. Buyers increasingly expect end‑to‑end program engines: policy governance, global compliance checks, payroll orchestration, digital onboarding and employee experience layers delivered as a cohesive service.
-
Security and identity as table stakes — As mobile endpoints and distributed access points proliferate, identity, device and application management solutions are required components of any mobility program. Integration with enterprise security stacks and zero‑trust architectures is becoming a procurement prerequisite.
-
Data orchestration and measurement — Decision-makers need a consistent, auditable view of assignment costs, tax exposure, and productivity impact. Advanced analytics and payroll data integration are emerging as high‑value differentiators for vendors and service providers that can translate mobility activity into workforce ROI.
-
Policy and border control tightening — Governments are investing in digital border systems and intensifying scrutiny on cross‑border tax and social security obligations. That increases compliance complexity for organizations and drives demand for trusted advisory plus technology-enabled compliance workflows.
What PW Consulting’s report delivers — practical, board‑ready tools
This study is designed as an operational playbook for 2026 decision cycles. Rather than a purely academic forecast, the report blends quantitative market sizing with application-ready frameworks to accelerate executable initiatives. Key practical components include:
-
Strategic diagnostic worksheets to assess current mobility maturity against business strategy and risk appetite.
-
Use-case driven TCO and ROI models that allow finance and HR leaders to run scenario comparisons—short‑term cost reduction vs. long‑term talent enablement tradeoffs.
-
Vendor selection architecture: an evaluation matrix and integration checklist that prioritize interoperability with existing HR, payroll, and security stacks.
-
Implementation playbooks and governance templates—covering policy design, compliance escalation paths and SLA structures for managed services.
-
Case studies and negotiated commercial templates demonstrating pricing levers and contracting approaches across direct technology purchases and managed services engagements.
-
Roadmaps for phased modernization—covering quick wins for 6–12 months and transformation milestones for 24–36 months aligned to the firm’s risk tolerance and resource capacity.
To preserve competitive integrity for our clients, the report intentionally abstracts certain granular market splits in public summaries; subscribers receive the full regional and solution-level matrices along with model files.
Competitive landscape — who matters and why
The competitive field is a mix of global professional services firms, specialized mobility advisors, enterprise software vendors and platform providers offering device and identity management. The market is neither atomized nor tightly monopolized; a set of global integrators and a second tier of niche specialists together shape buyer options. Strategic implications for buyers:
-
Global professional services (e.g., EY) are buying share through consultative, integrated engagements that bundle tax, immigration and transformation services with technology platforms. Their strength lies in advisory depth, regulatory relationships and enterprise change programs—making them preferred partners for complex, high‑risk transformations.
-
Specialist mobility firms (e.g., Vialto Partners, Mercer, Cartus) win where operational execution and customer experience are paramount. These providers excel at program design, policy benchmarking and managed services for assignments and relocations, and they increasingly integrate payroll and travel data to optimize outcomes.
-
Enterprise technology vendors (e.g., Microsoft, IBM, VMware) are anchoring the platform layer—cloud, collaboration, identity and endpoint security. Partnerships between advisors and technology vendors are the dominant go‑to‑market model for large deals, as buyers demand end‑to‑end interoperability and single-pane reporting.
-
Recent vendor activity underscores these dynamics: EY’s 2026 survey emphasized trust infrastructure and embedding mobility into business strategy; Vialto’s recent publications and awards recognition highlight the role of payroll data and program design in delivering measurable business value. These moves reflect a competitive focus on integration rather than point solutions.
How executives should act in 2026 — a concise decision checklist
-
Prioritize interoperability: Insist on open APIs and clear data ownership models when procuring platforms. Your mobility architecture must integrate with payroll, HRIS, identity providers and security monitoring to realize full value.
-
Start with high‑impact pilots: Use 6–12 month pilots focused on high-cost geographies or employee segments to build measurement capabilities and refine commercial models before enterprise rollouts.
-
Design for compliance scalability: Embed regulatory intelligence and audit trails in program design to reduce expedition risk as border and tax authorities increase scrutiny.
-
Balance in-house expertise with managed services: Retain strategic control of policy and governance while outsourcing operational execution where suppliers demonstrate proven KPIs and data transparency.
-
Align mobility KPIs to business outcomes: Move beyond cost-per-assignment to metrics that capture productivity, retention and speed-to-value for critical skill sets.
Investment and M&A considerations
Given the market’s growth profile and the ongoing convergence of advisory and platform capabilities, 2026 is a fertile year for bolt-on acquisitions and strategic partnerships. Buyers should look for targets that provide:
-
Proven integration IP (connectors, payroll adapters, identity bridges).
-
Repeatable managed-services processes and measurable SLAs.
-
Analytics and reporting modules that translate mobility activity into finance and talent metrics.
For corporate development teams, the most defensible value is in assets that shorten time-to-market for integrated mobility propositions and that embed recurring revenue through managed services or subscriptions.
How to use this study
PW Consulting’s Integrated Workforce Mobility market report is structured to support three common 2026 use cases:
-
Board-level strategic planning: executive summaries, scenario models and stakeholder impact analyses for capital and HR investment decisions.
-
Procurement and vendor selection: comparative vendor scoring, RFP templates and integration checklists to accelerate sourcing cycles.
-
Operational transformation: playbooks, policy templates and implementation roadmaps to deliver measurable improvement within 12–24 months.
Because the full value lies in the report’s interactive models and vendor matrices, PW Consulting provides subscribers with downloadable financial models, integration templates and a prioritized action plan tailored to sector and scale.
Closing perspective
The next 12–18 months will separate early movers who translate mobility investment into sustained talent advantage from organizations that tinker at the margins. With the market expected to nearly double in size from 2025 to 2032 under a roughly 10.25% CAGR, leaders who move decisively in 2026—by institutionalizing interoperability, embedding compliance automation, and tying mobility KPIs to business outcomes—will capture both operational efficiencies and strategic optionality. For detailed regional, solution and vendor-level intelligence (including the full set of market matrices and the model files), readers are invited to consult the full PW Consulting report and subscriber materials.
For detailed analysis of this topic, please visit the official page: Integrated Workforce Mobility Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide NIV Masks Market to Reach USD 4,894.48 Million by 2032, Expanding at a 6.21% CAGR
By pmarketresearch, 2026-08-18
Worldwide Non‑invasive Ventilation (NIV) Masks Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study on Worldwide Non‑invasive Ventilation (NIV) Masks delivers a compact, high‑signal briefing tailored for executives and strategy teams preparing plans for 2026. Built on a robust historical window (2020–2025) and a forward forecast covering 2026–2032, the report quantifies market scale, growth trajectory, competitive dynamics, regulatory inflection points, and operational levers that will determine winners and losers in the next planning cycle.
Worldwide Hydronic Manometers Market
Snapshot: What the headline numbers mean for strategy
The global NIV masks market expanded from approximately USD 2,520 million in 2020 to roughly USD 3,212 million in 2025 (base year). Our modeled forecasts show sustained momentum through the next planning horizon, with an expected compound annual growth rate (CAGR) of 6.21% across the forecast window and a projected market size approaching USD 4,894 million by 2032. These macro dynamics reflect persistent demand across acute care and home health settings, evolving reimbursement frameworks, and an innovation wave around patient comfort and single‑use infection‑control solutions.
Worldwide Flexible Compact Spectrometers Market
For 2026 planning cycles this profile has three immediate implications: (1) the market is large enough to support scale investments but concentrated enough that competitive moves by leading OEMs will materially alter access to customers, (2) mid‑single digit CAGR supports incremental capacity and targeted R&D rather than speculative greenfield projects, and (3) reimbursement and regulatory shifts are accelerating adoption at scale in segments where clinical evidence and device compatibility are aligned.
Worldwide Operation and Maintenance Training Market
What’s inside the full report (practical deliverables)
- Actionable demand forecasts and scenario planning templates for 2026–2032 (base/optimistic/stress scenarios) calibrated to clinical and reimbursement permutations.
- Commercial playbooks for hospital procurement, home health suppliers, and ambulatory channels—covering pricing levers, tender dynamics, and inventory policies.
- Regulatory and reimbursement trackers with decision trees showing the commercial impact of 510(k) approvals, CMS NCD updates, and regional labeling requirements.
- Supply‑chain risk assessments focused on critical raw materials (medical‑grade silicone and headgear textiles), single‑source dependencies, and strategies for nearshoring/dual‑sourcing.
- A competitive matrix with capability maps (product breadth, hospital vs home focus, single‑use vs reusable strategies, pediatric capabilities, and aftermarket services).
- M&A and partnership opportunity framework highlighting target archetypes, valuation multiples observed in adjacent respiratory device transactions, and integration diagnostics.
- Clinical and human factors evidence library summarizing performance metrics (seal efficacy, leak profiles, pressure tolerance, comfort indices) that buyers use in procurement scoring.
Competitive landscape — how incumbents are positioning for 2026
The competitive field is characterized by a handful of global leaders with deep OEM and channel relationships, supported by a layer of specialist manufacturers focusing on design differentiation (total‑face interfaces, pediatric masks, interchangeable elbows, and silicone‑based comfort cushions). Market concentration is material: the top three players command a clear leading share, and the top five control an even larger portion of the market — a structure that favors scale, regulatory bandwidth, and broad distribution networks.
- ResMed — Strengths: established hospital and home portfolios, proven sealing solutions for high‑pressure NIV, and global channel reach. Strategic posture emphasizes clinical reliability and compatibility with high‑pressure ventilatory settings.
- Fisher & Paykel Healthcare — Strengths: product breadth with multi‑configuration full‑face masks and focus on single‑limb circuit compatibility. Recent regulatory wins (including 510(k) clearances during the review period) sharpen its hospital market proposition and support cross‑sell into acute care ventilator ecosystems.
- Philips Respironics — Strengths: deep clinical relationships and a line‑up emphasizing modular headgear and under‑nose cushion technologies. Competitive advantage resides in integrated device‑plus‑accessory strategies that reduce switching costs for providers.
- Hamilton Medical — Strengths: new portfolio launches that target flexibility (interchangeable elbows, adult and pediatric sizing) and rapid adoption in critical care units. Product innovation is explicitly aimed at reducing mask inventory complexity.
- Dräger — Strengths: system‑level solutions and customization for acute care workflows. Dräger’s offering appeals to hospital purchasers prioritizing fit, seal, and lifecycle cost of therapy.
- Specialists and regional manufacturers (Dimar, GaleMed, Hans Rudolph, DEAS, AirLife and others) — Strengths: niche differentiation—total‑face interfaces, pediatric ranges, single‑patient disposables—plus competitive pricing and agility in responding to procurement tenders.
Recent product launches and regulatory clearances during the review period have created windows of opportunity. Examples include hospital‑oriented vented/non‑vented full‑face ranges cleared for single‑limb circuits and single‑patient use masks that align with infection control priorities. These moves both expand addressable use cases and raise the bar for entry by smaller competitors.
Regulation, reimbursement and clinical drivers shaping 2026 actions
Regulatory classification under 21 CFR 868 (Class II) and the 510(k) pathway remains a gating factor for market access in the U.S., compelling a consistent investment in clinical substantiation and quality systems. Beyond approvals, reimbursement is an accelerant: notable policy changes—specifically revisions to national coverage criteria for home noninvasive positive pressure ventilation—have reduced administrative barriers and broadened eligibility in key payor markets. For strategy teams, this combination means compliance and health‑economics evidence are non‑negotiable line items in product planning and market entry cost models.
On the clinical front, buyers are increasingly evaluating masks not only on price but on demonstrable impacts to therapy tolerance, leak control, and staff time spent fitting devices. Innovations that reduce setup time, deliver consistent seals at higher pressures, or simplify disposables handling will command pricing premium and procurement preference.
Supply‑chain and materials lens
Medical‑grade silicone remains the dominant cushion material due to its contouring properties and hypoallergenic profile. This technical dependency creates a predictable risk vector: volatility in silicone supply or quality can ripple through production timelines and unit economics. Mitigation options in the report include strategic supplier contracts, qualification of alternative hypoallergenic polymers, and assembly footprint redesigns to shorten logistics lanes.
Strategic recommendations for 2026 planning
- Prioritize interoperability: engineering masks that are compatible with prevalent ventilator circuits (including single‑limb systems) will unlock hospital tenders and reduce clinician friction.
- Invest in clinical evidence and HCP education: allocate budget to comparative seal/leak studies and in‑service training to accelerate adoption among respiratory therapists.
- Reassess product portfolio cadence: favor modular designs (interchangeable elbows, universal headgear) to reduce SKUs while addressing pediatric and specialty needs.
- Hedge material risk: execute dual‑sourcing for silicone and evaluate semi‑automated assembly to protect gross margins under demand shocks.
- Leverage reimbursement change: align commercial messaging and coverage documentation with the updated eligibility criteria to capture home‑care demand uplift.
- Consider M&A for capability buy‑in: small, specialized mask manufacturers with strong clinical endorsements are attractive tuck‑ins to accelerate market share at scale.
Commercial playbook — positioning, pricing and channel considerations
Competition will be decided at the intersection of clinical credibility and supply reliability. For 2026, high‑value opportunities will come from:
- Bundling masks with ventilator disposables or service contracts to increase switching costs.
- Offering tiered SKUs—premium comfort options for private pay/home users and cost‑optimized single‑use options for high‑volume hospital procurement.
- Building stronger distributor partnerships in fragmented markets where local regulatory navigation is the primary barrier.
Why PW Consulting’s full report matters
This briefing highlights strategic inflection points and competitive postures; the full report provides the decision‑support artifacts executives need to turn insight into action—detailed regional and product‑level forecasts, buyer scoring templates, supplier due‑diligence checklists, and executable M&A playbooks. We deliberately withhold granular segment and regional share tables in this public synopsis to preserve the consulting value chain; these datasets and the underlying model are included in the full deliverable and are purpose‑built for 2026 budgeting, capacity planning, and go‑to‑market roadmaps.
Next steps
For market entrants, product teams, and investor due diligence groups preparing 2026 plans, PW Consulting offers tailored briefings that map the quantitative forecast to your specific business case. Contact details and access to the full dataset and strategic annexes are available on the report landing page—where you can download executive slide decks, scenario models, and a buyer‑facing one‑pager for internal use.
PW Consulting’s industry team will continue monitoring regulatory rulings, 510(k) clearances, and payer updates through 2026 and will issue periodic updates to subscribers to ensure your plans remain aligned to market reality.
For detailed analysis of this topic, please visit the official page: Worldwide Non-invasive Ventilation (NIV) Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Refined Lanolin Market Set to Expand at a 5.12% CAGR, New Report Reveals
By pmarketresearch, 2026-08-18
Worldwide Refined Lanolin Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
Executive snapshot
PW Consulting’s newest market research, the Worldwide Refined Lanolin Market report (base year 2025; historical window 2020–2025; forecast period 2026–2032), crystallizes why refined lanolin has regained strategic importance for formulators, pharmaceutical manufacturers, ingredients distributors and specialty chemical investors. The sector’s recovery and steady mid-single-digit expansion—characterized by an industry compound annual growth rate (CAGR) of 5.12%—translates into a clear, actionable opportunity set for executives planning investments and commercial pivots in 2026.
Worldwide Heat Resistant Polyamide Market
Market dynamics at a glance
Over the historical window, global revenue expanded from a lower base to an estimated USD 273.35 Million in 2025, reflecting demand resilience across personal care and pharmaceutical ointments. Our baseline forecast anticipates the market to progress from an estimated USD 290.03 Million in 2026 toward approximately USD 387.72 Million by 2032 under the central scenario—underscoring predictable, investible growth rather than speculative volatility. Market concentration metrics—with the top three and top five players commanding a meaningful share—indicate an industry that is neither fragmented nor monopolized, leaving room for new premium entrants and mid-market consolidators alike.
LED Panel Lamps Market
Raw material and trade dynamics remain significant drivers. Refined lanolin originates from wool grease recovered during wool scouring; global trade in wool-grease derivatives registered notable volumes in recent years, and spot/export price behavior for wool grease has material implications for COGS and contract negotiations. Regulatory signals—such as the retention of lanolin in the U.S. FDA OTC skin-protectant monograph and permissive classification for certain wool-grease derivatives in UK import rules—create differentiated routes to market for pharmaceutical versus industrial users.
Steam Jet Ejector Market
What the report delivers — practical, transaction-focused outputs
-
Executive summary with actionable conclusions that can be translated into 90–180 day playbooks for commercial teams.
-
Price-sensitivity and margin-impact models tied to raw-wool grease price scenarios and refining yield assumptions (USD Million base unit economics included).
-
Supplier scorecards and procurement RFP templates that account for certification regimes (pharmacopoeia, GMP, ISO, Halal) and technical specifications such as pesticide residue thresholds.
-
Regulatory matrix mapping regional OTC and pharmaceutical frameworks, import classifications, and compliance checkpoints relevant to product registration and cross-border distribution.
-
Commercial segmentation playbooks (by route-to-market, by application cluster, and by value-capture node) plus go-to-market templates for premium versus industrial grade strategies. Note: full regional and application splits are reserved for the comprehensive report to preserve competitive value for subscribers.
-
M&A and partnership scouting checklist with diligence scorecards and suggested KPIs for bolt-on targets and JV partners, including integration risk heatmaps.
-
Sustainability and traceability roadmap templates to support claims and audit trails from raw wool source to finished refined lanolin product.
Competitive landscape — strategic positioning of core players
The refined lanolin value chain combines legacy refiners with nimble regional specialists. Our competitive analysis of leading firms reveals three distinct strategic postures:
-
Global incumbents with proprietary refining technology and multi-site manufacturing capacity. These players command premium positioning in pharmaceutical and high-end personal care markets through super-refining processes, broad pharmacopeial credentials and resilient distribution networks. Recent product innovation and capacity investments by global leaders are sharpening their edge in purity and oxidative stability for premium skincare and medical applications.
-
Regional specialists and contract-focused producers that emphasize cost-competitive supply, flexible grades and local certification footprints. Many of these firms specialize in solvent-free or chromatographic refining variants that address low-residue specifications attractive to pharmaceutical formulators and export markets with specific regulatory demands.
-
Distributors and branded ingredient houses that add formulation support, warehousing and value-added services—essential for rapid customer trials and scale-up, especially in Europe and Asia where proximity to cosmetics clusters matters.
Selective recent developments illustrate market momentum: leading refiners launched ultra-refined lanolin oils targeted at premium skincare and medical formulations, and greenfield expansions in Asia underline an expectation of sustained regional demand growth. Parallel capacity upgrades by smaller specialist refiners aim to capture pharmaceutical-grade contracts and longer-term supply agreements.
Company-level strategic takeaways (high level)
-
Proprietary refining and clear pharmacopeial compliance are decisive moats. Companies investing in ultra-pure, low-odor, stable lanolin derivatives gain privileged access to dermatology and medical device formulators.
-
Geographic manufacturing presence and warehousing reduce lead times and inventory carrying costs for fast-moving cosmetics customers; recent facility openings in Asia are deliberate moves to support that model.
-
Specialist refiners that can demonstrate solvent-free or low-residue processes will increasingly negotiate higher margins with pharma customers wary of trace contaminants.
-
Distributors adding formulation expertise and small-batch fulfilment are becoming preferred partners for innovation-led brands seeking speed to market.
Strategic priorities for 2026 decision-makers
For executives setting 2026 strategy, the refined lanolin market presents a combination of organic growth and consolidation opportunities. Our recommendations are oriented to capture near-term upside while building defensible, margin-accretive positions over the medium term:
-
Secure raw material contracts with price collars and volume flexibility. Given the sensitivity of margins to wool-grease price movements, negotiate two-stage contracts that combine spot-indexed volumes with fixed-price tranches tied to forecasted demand.
-
Differentiate through grade and certification ladders. Establish a “good-better-best” product taxonomy aligned to certifications (pharma-grade, cosmetic/pharmacopeial, Halal) and explicitly price the value of traceability and low-residue claims.
-
Invest selectively in refining capability or long-term tolling arrangements. For companies without the scale to build proprietary refining, tolling partnerships with capacity-equipped refiners reduce capital intensity while retaining control over specifications.
-
Pursue bolt-on acquisitions or exclusive distribution partnerships in adjacent regional hubs to improve service levels and capture incremental share—especially in markets where lead time and certification accelerate purchasing decisions.
-
Embed sustainability and provenance into commercial narratives. Traceable wool-sourcing programs and transparent processing data will command premium positioning with both regulators and brand customers.
-
Monitor regulatory changes and monograph statuses closely. Retention or expansion of recognized pharmacopeial uses materially affects TAM for therapeutic and dermatological segments.
How to use this report on day one
Subscribers will be able to convert insight into action within weeks: deploy our supplier scorecards in procurement RFPs, use our scenario-based margin models to stress-test pricing proposals, integrate our regulatory matrix into product registration timelines, and activate our M&A checklist to prioritize targets by strategic fit. For business development teams, the playbooks translate into prioritized outreach lists, sample timelines and technical acceptance criteria that materially shorten sales cycles.
Why this is the right moment to act
With the market on a steady growth trajectory and technological improvements in refining enabling cleaner, higher-margin product variants, 2026 is a pivotal decision year. Companies that lock in secure raw-material flows, diversify route-to-market, and invest where refining capability yields clear differentiation will capture disproportionate value. Conversely, inaction risks margin pressure from input-price volatility or loss of high-value customers to more agile suppliers.
Next steps — where to access full intelligence
This briefing highlights the strategic contours and actionable implications derived from PW Consulting’s full Worldwide Refined Lanolin Market report. The complete study contains the regional and application-level segmentation, granular vendor benchmarking, downloadable financial models (USD Million basis), and contract language templates reserved for subscribers. Visit our report portal to request the full dataset, schedule a 1:1 strategic briefing with our lanolin practice lead, or commission a bespoke commercial due-diligence pack aligned to your strategic questions.
For detailed analysis of this topic, please visit the official page: Worldwide Refined Lanolin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Rodder Machine Market to Expand at a 5.01% CAGR During 2026–2032 Forecast
By pmarketresearch, 2026-08-18
Worldwide Rodder Machine Market 2026: Strategic Preview for Decision‑Makers
Executive snapshot — from PW Consulting
PW Consulting’s latest market research, the Worldwide Rodder Machine Market Report (base year 2025, forecast 2026–2032), is designed as a strategic playbook for executives, procurement officers, product leaders, and investors who must make confident, near‑term decisions under accelerating infrastructure and regulatory pressures. The market has shown steady expansion from USD 345.5 million in 2020 to USD 432.5 million in 2025 and is projected to continue climbing — reaching approximately USD 448.2 million in 2026 and approaching USD 608.5 million by 2032. Our forecast period CAGR is 5.01% (2026–2032), a tempo that rewards disciplined positioning and targeted investments.
Bispecific Antibody Development Platform Market
Why this report matters for 2026 decisions
-
Procurement optimization — Municipalities and utilities facing tighter budgets must reconcile regulatory inspection cycles with total cost of ownership (TCO) and lifecycle maintenance. Our research translates market growth and procurement trends into buying triggers and timing recommendations that reduce cycle time and financial risk.
Worldwide Heavy Duty Truck Seat Market -
Product strategy — Manufacturers and OEMs evaluating electrification, modular designs, or hybrid rodding platforms need to match R&D priorities with adoption curves and procurement specifications. The report maps those inflection points to practical product roadmaps.
Worldwide Speed Gate Market -
M&A and partnership screening — With a moderately concentrated vendor landscape, granular competitive intelligence and scenario modeling in the report help acquirers and strategic partners prioritize targets and integration pathways.
-
Supply‑chain and raw material risk management — Steel and aluminum price volatility are not abstract threats; they materially affect margins and quoting consistency. We provide hedging and sourcing playbooks tuned to different business models (OEM, contract manufacturer, rental fleet).
Market dynamics: actionable insights
-
Infrastructure and regulatory demand anchors growth. Mandated inspection and cleaning cycles — notably in North America and the EU — continue to underwrite recurring procurement for municipal and utility fleets. These regulatory drivers create a predictable replacement and fleet‑expansion cadence that can be monetized through consumables, maintenance contracts, and retrofit programs.
-
Electrification and non‑invasive solutions are moving from novelty to procurement line items. The commercial introduction and promotion of battery‑electric continuous rodders have opened a second wave of substitution away from diesel‑powered units in applications where noise, emissions, and operational footprint matter.
-
Raw material cost exposure is a lever and a constraint. Frame and cable metallurgy represents a material portion of BOM cost; volatility in steel and aluminum markets translates into price sensitivity at the OEM and contractor levels. Effective 2026 sourcing strategies will combine forward contracts, alternate materials analysis, and local supplier diversification.
-
Service‑led revenue models are emerging as a margin stabilizer. Rental fleets, maintenance contracts, and outcome‑based service agreements (e.g., guaranteed throughput or downtime SLAs) can offset cyclical equipment sales and capture aftermarket economics.
-
Market concentration is meaningful but not prohibitive. A small number of established vendors account for a significant share of supplier revenue, creating a competitive environment where regional specialists and niche innovators can still carve defensible positions.
Competitive landscape — who matters and why
The competitive field blends long‑established North American OEMs, specialist manufacturers, and international volume producers. PW Consulting’s vendor analysis focuses on capability vectors that matter for 2026: product breadth (continuous vs sectional rodders), power architecture (diesel, electric, battery), service network, and aftermarket ecosystem.
-
RIDGID (Emerson) — Elyria, Ohio ( https://www.ridgid.com): RIDGID’s legacy in mainline solutions and robust sectional systems positions it as a go‑to for municipal and heavy institutional customers. Strengths: product robustness, tool kit breadth, and established service channels. Strategic implication: incumbency advantage for large‑scale bids, but incremental opportunity exists for RIDGID to accelerate digital services and battery options.
-
TSE International (OK Champion) — USA ( https://tse-international.com): TSE’s continued investment in the S660E battery‑electric continuous rodder marks a pivotal technology shift that buyers are beginning to consider as a direct alternative to larger vacuum fleets in sensitive urban operations. Strengths: battery drive systems, high production capacity, and a strong value proposition for emission‑constrained environments. Strategic implication: suppliers and fleet managers should model TCO and operational impact of battery units within 12–36 month procurement cycles.
-
General Pipe Cleaners (General Wire Spring Company) — McKees Rocks, Pennsylvania ( https://drainbrain.com): With sectional Rodrunner machines and proven two‑way operation for professional and municipal use, General Pipe Cleaners remains a performance leader for tough clogs and long runs. Strengths: product focus on performance and durability. Strategic implication: attractive target for rental fleet specialists seeking reliable, high‑utilization platforms.
-
Electric Eel Manufacturing Company — Springfield, Ohio ( https://www.electriceel.com): A longstanding drum and continuous machine manufacturer, Electric Eel’s emphasis on product range and rental/professional markets makes it a cornerstone supplier for service companies. Strengths: deep OEM heritage, broad product line. Strategic implication: an ideal partner for businesses layering telematics and predictive maintenance on existing fleets.
-
Sewer Equipment Co. of America — USA ( https://sewerequipment.com): Focused on water‑conserving mechanical rodding solutions, Sewer Equipment addresses utilities where water use and environmental impact are procurement constraints. Strategic implication: niche differentiation through sustainability‑focused features can win municipal RFPs.
-
Spartan Tool LLC — USA: Spartan remains a practical option for contractors and municipalities seeking reliable rodding and drain cleaning equipment. Strategic implication: strong distribution partnerships and rental house relationships are key competitive levers.
-
Hebei Sinta FRP Co., Ltd — China ( https://www.sintaductrodder.com): Specializing in fiberglass duct rodders and cable pullers, Hebei Sinta brings lower‑cost alternatives and accessory integration to global cable‑laying and pipeline cleaning deployments. Strategic implication: international buyers should balance initial capex savings with logistics, certification, and aftermarket readiness.
Recent market signals to watch in 2026
-
Public procurement continues to shape fleet composition — a recent municipal bid for a truck‑mounted jet rodder underscores ongoing investment in capacity for storm and sanitary infrastructure (public bid, March 2026).
-
Electrified rodding platforms are moving from announcement to field availability — OEMs are actively promoting battery‑electric models as quiet, emission‑free alternatives (product launch and promotion activities in 2025–2026).
-
Raw material attention remains high across design and procurement planning cycles; teams should model material price scenarios in their 2026 budgets.
What the PW Consulting report delivers (practical content)
We built this report as a toolkit for executives who must act in 2026. Key deliverables include:
-
Macro market sizing and seven‑year forecast (2026–2032) with scenario overlays and sensitivity to raw material and regulatory shocks.
-
Buyer persona segmentation and procurement playbooks for municipalities, utilities, rental houses, and telecom integrators.
-
Product benchmarking and capability matrices that compare continuous vs sectional platforms, propulsion options, and maintenance footprints.
-
Supply‑chain stress tests and sourcing playbooks that quantify exposure to steel and aluminum pricing and propose mitigation levers.
-
Vendor scorecards and M&A screening templates focused on integration risk, aftermarket potential, and cross‑sell opportunities.
-
Operational tools — TCO calculators, maintenance scheduling templates, and procurement specification language ready for RFP inclusion.
-
Case studies and procurement timelines designed to compress evaluation cycles and reduce fleet disruption during unit rollouts.
Strategic recommendations for 2026 (high‑impact, low‑latency)
-
For OEMs: Prioritize modular electrification. Develop hybrid architectures that retrofit existing frames to accept battery packs and telematics modules to capture early adopters while protecting legacy revenue.
-
For fleet operators: Pilot battery‑electric continuous rodders in high‑sensitivity districts with defined emissions or noise constraints. Use short‑term rental or lease pilots to validate TCO before large capital purchases.
-
For procurement teams: Embed lifecycle cost and service availability clauses into RFPs; require performance data under local operating conditions rather than relying solely on vendor claims.
-
For private equity and strategics: Use the report’s M&A screen to identify targets that complement incumbent service networks or provide technology adjacency (telematics, battery integration, specialized tooling).
-
For supply‑chain leaders: Lock in strategic allotments of critical metals, qualify secondary suppliers for key subassemblies, and evaluate near‑shoring options for high‑value components.
How to use this preview — next steps
This article is a deliberately calibrated preview: it highlights structural growth, vendor dynamics, and strategic playbooks while withholding detailed segment allocations and granular regional splits to preserve the full operational intelligence available in the full report. If your 2026 capital planning, R&D roadmap, or M&A pipeline depends on a precise, executable view of the rodder machine market, PW Consulting’s full report provides the complete dataset, vendor scorecards, and ready‑to‑deploy templates.
Contact PW Consulting to access the full Worldwide Rodder Machine Market Report and schedule a tailored briefing with our senior industry analysts. We will walk your team through customized scenarios, procurement contract language, and an implementation checklist to convert insight into measurable outcomes within 90 days.
About the author
Prepared by PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst — our practice combines field‑tested infrastructure procurement experience with rigorous market analytics to help clients convert market momentum into defensible growth and sustainable operations.
For detailed analysis of this topic, please visit the official page: Worldwide Rodder Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide NTP & PTP Time Servers Market Poised for 8.12% CAGR Through 2026–2032
By pmarketresearch, 2026-08-18
PW Consulting: Strategic Brief — Worldwide NTP & PTP Time Servers Market Outlook (2026 Strategic Preview)
Executive summary
As enterprises prepare their 2026 technology roadmaps, precise timekeeping is moving from a niche infrastructure concern to an operational imperative. PW Consulting’s new Worldwide NTP & PTP Time Servers Market report synthesizes five years of historical tracking (2020–2025) with a rigorous forecast through 2032, delivering decision-grade insight for CIOs, CTOs, network architects, and procurement leads. The market has expanded from roughly USD 425 million in 2020 to an estimated USD 642.5 million in 2025, and our modeling projects continued acceleration — reaching approximately USD 1,109.7 million by 2032 driven by an 8.12% CAGR across the forecast horizon. This growth is underpinned by regulatory tightening, the migration of real-time workloads to edge and cloud fabrics, and advances in PTP (IEEE 1588) implementations and GNSS-anchored timing resilience.
Worldwide Data and Analytics Service Market
Why this matters for 2026 planning
- Strategic timing is now a differentiator: Accurate and auditable timestamps are mandatory for regulatory compliance in financial markets, essential for 5G and telco service-level guarantees, and increasingly critical for distributed cloud-native applications and real-time industrial control.
- Procurement must balance accuracy, resilience and cybersecurity: Buyers need to evaluate products not only on sub-microsecond accuracy but also on GNSS holdover performance, oscillator technology, hardware timestamping, and integration with Zero Trust security models.
- Operational visibility trumps vendor feature lists: Operators need playbooks for deployment, monitoring and incident handling when GNSS is disrupted — the report includes practical checklists and failure-mode mitigation patterns that materially reduce operational risk.
Market trajectory and what the numbers reveal
The market’s compound annual growth trajectory (8.12% CAGR through 2026–2032) reflects sustained demand across multiple verticals. Our longitudinal series shows a steady climb from the mid-400s (USD million) in the early 2020s to the mid-600s by 2025, with an inflection as PTP adoption and telco modernization programmes accelerate. For 2026 specifically, the market is poised to break through new thresholds as hyperscale data center operators, telecom providers rolling out profile-compliant PTP, and regulated financial institutions refresh on-premises timing infrastructure.
Worldwide Oil & Gas Processing Seals Market
Core dynamics shaping vendor strategy
- PTP adoption and the NTP transition: A major structural shift is underway: applications that once tolerated millisecond-class NTP are migrating to sub-microsecond and nanosecond-class PTP solutions. This transition creates demand not only for PTP grandmasters and hardware timestamping but also for hybrid NTP/PTP architectures that enable phased migration.
- GNSS dependency and holdover engineering: GNSS remains the predominant primary reference, but engineering emphasis has shifted to oscillator-based holdover (OCXO, Rubidium, Cesium) and multi-constellation resilience strategies to maintain service integrity during signal outages.
- Security and zero trust: Time servers are now part of the attack surface. Vendors embedding cryptographic protections, hardware security modules, and compliance with enterprise Zero Trust standards will outcompete legacy offerings in procurement cycles.
- Service alternatives and platformization: Precision Time as a Service offerings from major colocation and cloud players are reshaping buy vs. build decisions. Buyers must weigh the operational simplicity of managed PTP/NTP services against sovereignty, latency determinism and auditability of on-premise appliances.
Report deliverables — what’s inside (practical, decision-ready)
PW Consulting’s report is structured around actionable modules that translate market data into procurement and deployment actions. Highlights include:
Worldwide Tampography Inks Market
- Transparent market-sizing methodology and reconciled historical series (2020–2025) with scenario-based forecasting through 2032.
- Technology deep-dives: comparative analysis of PTP profiles, hardware timestamping implementations, GNSS integrations, and oscillator holdover engineering.
- Regulatory and standards mapping: how financial regulations, telecom specifications, and critical-infrastructure requirements affect timing tolerances and procurement criteria.
- Vendor benchmarking and feature-mapping: an objective scorecard focused on accuracy, resilience, security, manageability and total cost of ownership.
- Deployment playbooks: risk registers, monitoring KPIs, incident runbooks for GNSS loss, and sample procurement RFIs tailored to enterprise and service-provider needs.
- Investment and ROI models: multi-year total-cost scenarios for appliance purchases vs. managed services, including sensitivity to oscillator type and failure rates.
Competitive landscape: who matters and why
The time-servers market is moderately consolidated, with our concentration metrics indicating that the top vendors hold a substantial portion of industry revenue — an important signal for buyers seeking longevity and support stability. The competitive field brings a mix of specialist manufacturers, semiconductor-enabled platform vendors, and systems integrators. Key positioning observations:
- Meinberg (Bad Pyrmont, Germany): A long-standing specialist whose LANTIME and microSync lines emphasize hardware timestamping and oscillator options across industrial, broadcast and data center use cases. Recent product introductions signal a focus on energy efficiency and trading-grade timestamp fidelity.
- Microchip Technology (Chandler, AZ): Combines semiconductor-level timing expertise with enterprise-class appliances that align to Zero Trust architectures — attractive for large networks demanding integrated security and scale.
- Safran — Navigation & Timing (formerly Orolia/Spectracom): Targets the high-end of the market with sub-nanosecond-capable devices and resilience features suitable for telecom, finance and defense applications.
- Oscilloquartz (ADVA): Focused on telco and mobile infrastructure operators with compact grandmasters and profile-compliant PTP implementations that ease integration into existing timing fabrics.
- EndRun Technologies, Brandywine Communications, Masterclock and specialist OEMs: Provide focused offerings for enterprise, broadcast, transportation and government sectors — their product breadth supports bespoke solutions where domain-specific certifications and integrations matter.
- Regional and emerging players: A number of localized vendors and integrators cater to government and critical-infrastructure procurements; these players can be attractive for missions requiring local support, certification and price-competitive alternatives.
Recent industry moves you should factor into 2026 decisions
- Product innovation continues: established vendors introduced next-gen PTP grandmasters and compact GNSS‑synchronized appliances with improved power efficiency and dual-port PTP capability, tightening the performance gap between high-end and mid-market devices.
- Regulatory pressure remains material: timestamp accuracy requirements from financial regulators and auditing frameworks are driving adoption of PTP or enhanced NTP in trading and compliance-sensitive environments.
- Colocation and cloud providers are offering precision time services that change the calculus for distributed enterprises, especially those balancing latency-sensitive physics against operational overhead.
Practical recommendations for technology and procurement leaders
- Adopt a phased migration strategy to PTP where mission-critical workloads require sub-microsecond fidelity; retain hybrid NTP/PTP architectures to preserve legacy integrations.
- Specify holdover performance in procurement documentation; OCXO vs. Rubidium choices materially affect incident recovery and TCO under GNSS outage scenarios.
- Embed security requirements into RFPs: mandate signed time sources, authenticated NTP/PTP, and integration with enterprise identity and key management systems.
- Model managed services as an overlay, not a replacement, for core sovereign functions — use colocation PTP as a scalability lever while retaining auditable on-premise references for compliance.
Conclusion — the strategic imperative
Accurate, resilient and secure time distribution has moved from a technical utility to a strategic enabler. With the market on a steady growth path and the 2026 planning cycle underway, organizations that treat timing as a first-class architectural decision — combining resilient hardware, rigorous procurement criteria and operational runbooks — will reduce compliance risk, improve performance for latency-sensitive workloads and gain an operational advantage in distributed systems.
Next steps
PW Consulting’s full report contains the complete dataset, vendor scorecards, deployment templates, and the proprietary scenario models that underpin our forecast. For procurement teams, network architects, and executive sponsors preparing 2026 budgets, the report provides the evidence-based guidance needed to prioritize investments and select suppliers. Visit the PW Consulting website to access the full report and supporting materials.
For detailed analysis of this topic, please visit the official page: Worldwide NTP & PTP Time Servers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com