

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Integrated Workforce Mobility Market Poised to Hit USD 28.69 Billion by 2032 at a 10.25% CAGR

Integrated Workforce Mobility Market — 2026 Strategic Briefing for C-Suites
Executive snapshot
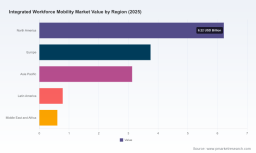
In an era where talent is borderless but compliance, experience and security are not, the Integrated Workforce Mobility market is entering a decisive inflection. PW Consulting’s latest market study (base year 2025, historical 2020–2025, forecast 2026–2032) quantifies a clear trajectory: the market expands from an estimated USD 14.5 Billion in 2025 to roughly USD 28.7 Billion by 2032, growing at a compound annual growth rate (CAGR) of approximately 10.25% during the forecast window. For executives planning capital allocation, program design, or M&A activity in 2026, the question is no longer whether to invest in workforce mobility capabilities but how to architect capability stacks that convert scale, compliance and user experience into measurable business outcomes.
1.6T High-speed Optical Modules Market
Why 2026 is a strategic pivot year
-
Momentum meets regulation: After multi-year adoption of hybrid and remote working models, enterprises are shifting from ad hoc fixes to integrated platforms that unify immigration, tax, payroll, security and device/application management. This market movement is reflected in the robust mid‑teens growth profile PW Consulting documents—sustained, broad-based expansion driven by technology modernization and programization of mobility services.
Portable LED Light Facial Device Market -
Infrastructure enables functionality: Recent regulatory and infrastructure initiatives—ranging from national broadband and spectrum priorities to advanced network buildouts—are lowering the operational friction for data‑intensive mobility tooling. These changes materially increase the attainable addressable market for richer real‑time orchestration, analytics and edge-enabled employee experiences.
Surface Grinding Services Market -
Economic and talent pressures compress timelines: Talent scarcity in key skills and a renewed focus on cross-border assignment cost‑efficiency means mobility decisions are being pushed higher up the agenda and accelerated into 2026 budgeting cycles.
Core market dynamics shaping 2026 decisions
-
Convergence of services and platforms — The market is shifting from siloed offerings (tax, immigration, relocation operations, device management) toward integrated delivery models. Buyers increasingly expect end‑to‑end program engines: policy governance, global compliance checks, payroll orchestration, digital onboarding and employee experience layers delivered as a cohesive service.
-
Security and identity as table stakes — As mobile endpoints and distributed access points proliferate, identity, device and application management solutions are required components of any mobility program. Integration with enterprise security stacks and zero‑trust architectures is becoming a procurement prerequisite.
-
Data orchestration and measurement — Decision-makers need a consistent, auditable view of assignment costs, tax exposure, and productivity impact. Advanced analytics and payroll data integration are emerging as high‑value differentiators for vendors and service providers that can translate mobility activity into workforce ROI.
-
Policy and border control tightening — Governments are investing in digital border systems and intensifying scrutiny on cross‑border tax and social security obligations. That increases compliance complexity for organizations and drives demand for trusted advisory plus technology-enabled compliance workflows.
What PW Consulting’s report delivers — practical, board‑ready tools
This study is designed as an operational playbook for 2026 decision cycles. Rather than a purely academic forecast, the report blends quantitative market sizing with application-ready frameworks to accelerate executable initiatives. Key practical components include:
-
Strategic diagnostic worksheets to assess current mobility maturity against business strategy and risk appetite.
-
Use-case driven TCO and ROI models that allow finance and HR leaders to run scenario comparisons—short‑term cost reduction vs. long‑term talent enablement tradeoffs.
-
Vendor selection architecture: an evaluation matrix and integration checklist that prioritize interoperability with existing HR, payroll, and security stacks.
-
Implementation playbooks and governance templates—covering policy design, compliance escalation paths and SLA structures for managed services.
-
Case studies and negotiated commercial templates demonstrating pricing levers and contracting approaches across direct technology purchases and managed services engagements.
-
Roadmaps for phased modernization—covering quick wins for 6–12 months and transformation milestones for 24–36 months aligned to the firm’s risk tolerance and resource capacity.
To preserve competitive integrity for our clients, the report intentionally abstracts certain granular market splits in public summaries; subscribers receive the full regional and solution-level matrices along with model files.
Competitive landscape — who matters and why
The competitive field is a mix of global professional services firms, specialized mobility advisors, enterprise software vendors and platform providers offering device and identity management. The market is neither atomized nor tightly monopolized; a set of global integrators and a second tier of niche specialists together shape buyer options. Strategic implications for buyers:
-
Global professional services (e.g., EY) are buying share through consultative, integrated engagements that bundle tax, immigration and transformation services with technology platforms. Their strength lies in advisory depth, regulatory relationships and enterprise change programs—making them preferred partners for complex, high‑risk transformations.
-
Specialist mobility firms (e.g., Vialto Partners, Mercer, Cartus) win where operational execution and customer experience are paramount. These providers excel at program design, policy benchmarking and managed services for assignments and relocations, and they increasingly integrate payroll and travel data to optimize outcomes.
-
Enterprise technology vendors (e.g., Microsoft, IBM, VMware) are anchoring the platform layer—cloud, collaboration, identity and endpoint security. Partnerships between advisors and technology vendors are the dominant go‑to‑market model for large deals, as buyers demand end‑to‑end interoperability and single-pane reporting.
-
Recent vendor activity underscores these dynamics: EY’s 2026 survey emphasized trust infrastructure and embedding mobility into business strategy; Vialto’s recent publications and awards recognition highlight the role of payroll data and program design in delivering measurable business value. These moves reflect a competitive focus on integration rather than point solutions.
How executives should act in 2026 — a concise decision checklist
-
Prioritize interoperability: Insist on open APIs and clear data ownership models when procuring platforms. Your mobility architecture must integrate with payroll, HRIS, identity providers and security monitoring to realize full value.
-
Start with high‑impact pilots: Use 6–12 month pilots focused on high-cost geographies or employee segments to build measurement capabilities and refine commercial models before enterprise rollouts.
-
Design for compliance scalability: Embed regulatory intelligence and audit trails in program design to reduce expedition risk as border and tax authorities increase scrutiny.
-
Balance in-house expertise with managed services: Retain strategic control of policy and governance while outsourcing operational execution where suppliers demonstrate proven KPIs and data transparency.
-
Align mobility KPIs to business outcomes: Move beyond cost-per-assignment to metrics that capture productivity, retention and speed-to-value for critical skill sets.
Investment and M&A considerations
Given the market’s growth profile and the ongoing convergence of advisory and platform capabilities, 2026 is a fertile year for bolt-on acquisitions and strategic partnerships. Buyers should look for targets that provide:
-
Proven integration IP (connectors, payroll adapters, identity bridges).
-
Repeatable managed-services processes and measurable SLAs.
-
Analytics and reporting modules that translate mobility activity into finance and talent metrics.
For corporate development teams, the most defensible value is in assets that shorten time-to-market for integrated mobility propositions and that embed recurring revenue through managed services or subscriptions.
How to use this study
PW Consulting’s Integrated Workforce Mobility market report is structured to support three common 2026 use cases:
-
Board-level strategic planning: executive summaries, scenario models and stakeholder impact analyses for capital and HR investment decisions.
-
Procurement and vendor selection: comparative vendor scoring, RFP templates and integration checklists to accelerate sourcing cycles.
-
Operational transformation: playbooks, policy templates and implementation roadmaps to deliver measurable improvement within 12–24 months.
Because the full value lies in the report’s interactive models and vendor matrices, PW Consulting provides subscribers with downloadable financial models, integration templates and a prioritized action plan tailored to sector and scale.
Closing perspective
The next 12–18 months will separate early movers who translate mobility investment into sustained talent advantage from organizations that tinker at the margins. With the market expected to nearly double in size from 2025 to 2032 under a roughly 10.25% CAGR, leaders who move decisively in 2026—by institutionalizing interoperability, embedding compliance automation, and tying mobility KPIs to business outcomes—will capture both operational efficiencies and strategic optionality. For detailed regional, solution and vendor-level intelligence (including the full set of market matrices and the model files), readers are invited to consult the full PW Consulting report and subscriber materials.
For detailed analysis of this topic, please visit the official page: Integrated Workforce Mobility Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com