

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Rodder Machine Market to Expand at a 5.01% CAGR During 2026–2032 Forecast

Worldwide Rodder Machine Market 2026: Strategic Preview for Decision‑Makers
Executive snapshot — from PW Consulting
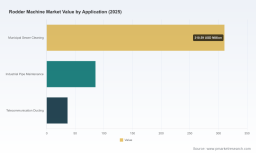
PW Consulting’s latest market research, the Worldwide Rodder Machine Market Report (base year 2025, forecast 2026–2032), is designed as a strategic playbook for executives, procurement officers, product leaders, and investors who must make confident, near‑term decisions under accelerating infrastructure and regulatory pressures. The market has shown steady expansion from USD 345.5 million in 2020 to USD 432.5 million in 2025 and is projected to continue climbing — reaching approximately USD 448.2 million in 2026 and approaching USD 608.5 million by 2032. Our forecast period CAGR is 5.01% (2026–2032), a tempo that rewards disciplined positioning and targeted investments.
Bispecific Antibody Development Platform Market
Why this report matters for 2026 decisions
-
Procurement optimization — Municipalities and utilities facing tighter budgets must reconcile regulatory inspection cycles with total cost of ownership (TCO) and lifecycle maintenance. Our research translates market growth and procurement trends into buying triggers and timing recommendations that reduce cycle time and financial risk.
Worldwide Heavy Duty Truck Seat Market -
Product strategy — Manufacturers and OEMs evaluating electrification, modular designs, or hybrid rodding platforms need to match R&D priorities with adoption curves and procurement specifications. The report maps those inflection points to practical product roadmaps.
Worldwide Speed Gate Market -
M&A and partnership screening — With a moderately concentrated vendor landscape, granular competitive intelligence and scenario modeling in the report help acquirers and strategic partners prioritize targets and integration pathways.
-
Supply‑chain and raw material risk management — Steel and aluminum price volatility are not abstract threats; they materially affect margins and quoting consistency. We provide hedging and sourcing playbooks tuned to different business models (OEM, contract manufacturer, rental fleet).
Market dynamics: actionable insights
-
Infrastructure and regulatory demand anchors growth. Mandated inspection and cleaning cycles — notably in North America and the EU — continue to underwrite recurring procurement for municipal and utility fleets. These regulatory drivers create a predictable replacement and fleet‑expansion cadence that can be monetized through consumables, maintenance contracts, and retrofit programs.
-
Electrification and non‑invasive solutions are moving from novelty to procurement line items. The commercial introduction and promotion of battery‑electric continuous rodders have opened a second wave of substitution away from diesel‑powered units in applications where noise, emissions, and operational footprint matter.
-
Raw material cost exposure is a lever and a constraint. Frame and cable metallurgy represents a material portion of BOM cost; volatility in steel and aluminum markets translates into price sensitivity at the OEM and contractor levels. Effective 2026 sourcing strategies will combine forward contracts, alternate materials analysis, and local supplier diversification.
-
Service‑led revenue models are emerging as a margin stabilizer. Rental fleets, maintenance contracts, and outcome‑based service agreements (e.g., guaranteed throughput or downtime SLAs) can offset cyclical equipment sales and capture aftermarket economics.
-
Market concentration is meaningful but not prohibitive. A small number of established vendors account for a significant share of supplier revenue, creating a competitive environment where regional specialists and niche innovators can still carve defensible positions.
Competitive landscape — who matters and why
The competitive field blends long‑established North American OEMs, specialist manufacturers, and international volume producers. PW Consulting’s vendor analysis focuses on capability vectors that matter for 2026: product breadth (continuous vs sectional rodders), power architecture (diesel, electric, battery), service network, and aftermarket ecosystem.
-
RIDGID (Emerson) — Elyria, Ohio ( https://www.ridgid.com): RIDGID’s legacy in mainline solutions and robust sectional systems positions it as a go‑to for municipal and heavy institutional customers. Strengths: product robustness, tool kit breadth, and established service channels. Strategic implication: incumbency advantage for large‑scale bids, but incremental opportunity exists for RIDGID to accelerate digital services and battery options.
-
TSE International (OK Champion) — USA ( https://tse-international.com): TSE’s continued investment in the S660E battery‑electric continuous rodder marks a pivotal technology shift that buyers are beginning to consider as a direct alternative to larger vacuum fleets in sensitive urban operations. Strengths: battery drive systems, high production capacity, and a strong value proposition for emission‑constrained environments. Strategic implication: suppliers and fleet managers should model TCO and operational impact of battery units within 12–36 month procurement cycles.
-
General Pipe Cleaners (General Wire Spring Company) — McKees Rocks, Pennsylvania ( https://drainbrain.com): With sectional Rodrunner machines and proven two‑way operation for professional and municipal use, General Pipe Cleaners remains a performance leader for tough clogs and long runs. Strengths: product focus on performance and durability. Strategic implication: attractive target for rental fleet specialists seeking reliable, high‑utilization platforms.
-
Electric Eel Manufacturing Company — Springfield, Ohio ( https://www.electriceel.com): A longstanding drum and continuous machine manufacturer, Electric Eel’s emphasis on product range and rental/professional markets makes it a cornerstone supplier for service companies. Strengths: deep OEM heritage, broad product line. Strategic implication: an ideal partner for businesses layering telematics and predictive maintenance on existing fleets.
-
Sewer Equipment Co. of America — USA ( https://sewerequipment.com): Focused on water‑conserving mechanical rodding solutions, Sewer Equipment addresses utilities where water use and environmental impact are procurement constraints. Strategic implication: niche differentiation through sustainability‑focused features can win municipal RFPs.
-
Spartan Tool LLC — USA: Spartan remains a practical option for contractors and municipalities seeking reliable rodding and drain cleaning equipment. Strategic implication: strong distribution partnerships and rental house relationships are key competitive levers.
-
Hebei Sinta FRP Co., Ltd — China ( https://www.sintaductrodder.com): Specializing in fiberglass duct rodders and cable pullers, Hebei Sinta brings lower‑cost alternatives and accessory integration to global cable‑laying and pipeline cleaning deployments. Strategic implication: international buyers should balance initial capex savings with logistics, certification, and aftermarket readiness.
Recent market signals to watch in 2026
-
Public procurement continues to shape fleet composition — a recent municipal bid for a truck‑mounted jet rodder underscores ongoing investment in capacity for storm and sanitary infrastructure (public bid, March 2026).
-
Electrified rodding platforms are moving from announcement to field availability — OEMs are actively promoting battery‑electric models as quiet, emission‑free alternatives (product launch and promotion activities in 2025–2026).
-
Raw material attention remains high across design and procurement planning cycles; teams should model material price scenarios in their 2026 budgets.
What the PW Consulting report delivers (practical content)
We built this report as a toolkit for executives who must act in 2026. Key deliverables include:
-
Macro market sizing and seven‑year forecast (2026–2032) with scenario overlays and sensitivity to raw material and regulatory shocks.
-
Buyer persona segmentation and procurement playbooks for municipalities, utilities, rental houses, and telecom integrators.
-
Product benchmarking and capability matrices that compare continuous vs sectional platforms, propulsion options, and maintenance footprints.
-
Supply‑chain stress tests and sourcing playbooks that quantify exposure to steel and aluminum pricing and propose mitigation levers.
-
Vendor scorecards and M&A screening templates focused on integration risk, aftermarket potential, and cross‑sell opportunities.
-
Operational tools — TCO calculators, maintenance scheduling templates, and procurement specification language ready for RFP inclusion.
-
Case studies and procurement timelines designed to compress evaluation cycles and reduce fleet disruption during unit rollouts.
Strategic recommendations for 2026 (high‑impact, low‑latency)
-
For OEMs: Prioritize modular electrification. Develop hybrid architectures that retrofit existing frames to accept battery packs and telematics modules to capture early adopters while protecting legacy revenue.
-
For fleet operators: Pilot battery‑electric continuous rodders in high‑sensitivity districts with defined emissions or noise constraints. Use short‑term rental or lease pilots to validate TCO before large capital purchases.
-
For procurement teams: Embed lifecycle cost and service availability clauses into RFPs; require performance data under local operating conditions rather than relying solely on vendor claims.
-
For private equity and strategics: Use the report’s M&A screen to identify targets that complement incumbent service networks or provide technology adjacency (telematics, battery integration, specialized tooling).
-
For supply‑chain leaders: Lock in strategic allotments of critical metals, qualify secondary suppliers for key subassemblies, and evaluate near‑shoring options for high‑value components.
How to use this preview — next steps
This article is a deliberately calibrated preview: it highlights structural growth, vendor dynamics, and strategic playbooks while withholding detailed segment allocations and granular regional splits to preserve the full operational intelligence available in the full report. If your 2026 capital planning, R&D roadmap, or M&A pipeline depends on a precise, executable view of the rodder machine market, PW Consulting’s full report provides the complete dataset, vendor scorecards, and ready‑to‑deploy templates.
Contact PW Consulting to access the full Worldwide Rodder Machine Market Report and schedule a tailored briefing with our senior industry analysts. We will walk your team through customized scenarios, procurement contract language, and an implementation checklist to convert insight into measurable outcomes within 90 days.
About the author
Prepared by PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst — our practice combines field‑tested infrastructure procurement experience with rigorous market analytics to help clients convert market momentum into defensible growth and sustainable operations.
For detailed analysis of this topic, please visit the official page: Worldwide Rodder Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com