

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: p,p'-Dibromobiphenyl Market to Grow at a 4.12% CAGR Through 2032

p.p'-Dibromobiphenyl Market Outlook 2026: Strategic Imperatives for Corporate Decision‑Makers
PW Consulting’s latest market brief on p.p'-Dibromobiphenyl arrives at a pivotal moment for companies operating across advanced materials, specialty chemicals, and pharmaceutical intermediates. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study synthesizes price signals, feedstock dynamics, regulatory pressures, and supplier capability to produce an actionable view for boardrooms and strategy teams. The market reached approximately USD 14.5 Million in 2025 and, at a compound annual growth rate (CAGR) of 4.12% through the forecast window, is projected to approach roughly USD 19.2 Million by 2032 — trajectory that is modest in headline size but strategically outsized given the molecule’s role as an enabler in high‑value downstream applications.
Door Profiles Market
Why this report matters in 2026
-
Material leverage: p.p'-Dibromobiphenyl functions as a core intermediate for OLED materials, liquid crystal polymers and other specialty chemistries. Small shifts in availability, quality distribution or pricing ripple into technology roadmaps and cost curves for device manufacturers, polymer formulators and research institutions.
Automotive Coordinate Measuring Machine Market -
Supply stress and cost volatility: recent raw‑material developments have materially altered the economics of brominated intermediates. Notably, bromine prices in China surged from roughly 28,000 RMB/ton in mid‑October 2025 to about 41,000 RMB/ton by late February 2026 — an approximate 46% move driven by tight supply. Concurrently, regional bromine benchmarks in early 2026 show variance (Northeast Asia reported near USD 6.16/kg in March 2026 while Europe was at USD 3.49/kg), underscoring regional supply chain arbitrage and input‑cost risk.
Engineering Research and Development Service Market -
Regulatory tailwinds and risks: 4,4'-Dibromobiphenyl appears under REACH monitoring in contexts related to polybrominated biphenyls (PBBs) due to concerns over persistence and aquatic toxicity. This evolving regulatory landscape creates both compliance costs and strategic opportunities for suppliers who can document high‑purity, low‑impurity manufacturing and robust stewardship.
Market dynamics — what the numbers tell us (and what they don’t)
The overall market’s measured expansion — from the mid‑teens USD million range in the early 2020s to an expected near‑double‑digit escalation by 2032 — indicates steady, technology‑linked demand rather than commoditized volume growth. This pattern matters: incumbents in concentrated supply chains can extract margin through quality differentiation, traceability and reliable logistics, while late entrants face gatekeeping by established formularies in electronics and pharma R&D.
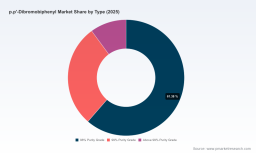
Concentration metrics are instructive: the top three suppliers control a meaningful portion of market share, and the top five capture an even larger share — a structure that favors strategic partnerships, tolling agreements and capacity coordination over pure price competition. For procurement and corporate development teams, the practical consequence is that supply relationships and qualification cycles matter as much as unit costs.
Supply side: structural and near‑term considerations
-
Feedstock and upstream integration: The economics of p.p'-Dibromobiphenyl are intimately linked to biphenyl and bromine supply chains. Analysts’ view of the global biphenyl market — a larger but related feedstock market estimated in the low hundreds of millions USD in 2025 and forecast to rise in the coming decade — signals potential upstream volatility tied to benzene feedstocks and refining activity. Manufacturers with integrated bromination or secured bromine contracts are positioned to weather input shocks better.
-
Quality and qualification: End‑users in OLED and high‑performance polymers require narrow impurity profiles and documentation. Suppliers that offer certified purity grades, detailed analytical dossiers and small‑batch sampling capability achieve faster customer qualification and premium positioning.
-
Capacity and geographic footprint: A mix of specialty producers and larger chemical houses supply the market, with manufacturing clusters concentrated in Asia. Capacity flexibility (e.g., tolling, batch scale‑up) is a differentiator given episodic demand from electronics cycles and research procurement.
Competitive landscape — practical takes on key suppliers
Our competitive review evaluates supplier capabilities across four vectors: product quality and purity range, regulatory and documentation readiness, logistics and inventory footprint, and scale/flexibility. Below are distilled profiles of representative participants that illustrate the market’s competitive architecture.
-
Tokyo Chemical Industry Co., Ltd. (TCI, Japan) — A globally recognized specialty reagent supplier, TCI brings manufacturing discipline and extensive distribution channels. With product variants geared to organic semiconductors and lab applications, TCI’s stock‑in‑warehouse model and packaging options streamline procurement for small‑to‑medium research users.
-
Simson Pharma Ltd. and Pharmaffiliates (India) — These suppliers focus on pharmaceutical intermediates and analytical standards. Their strengths lie in regulatory awareness for pharmaceutical supply chains and in serving customers that demand reference‑grade material alongside commercial batches.
-
Alfa Chem and Chinese manufacturers (multiple firms) — Producers from China deliver breadth of supply, competitive unit economics and a range of documented physical specifications. Several of these suppliers highlight high‑purity offerings and export orientation, making them central to global sourcing strategies.
-
Deep Pharm Chem (India) — An ISO 9001 certified manufacturer that emphasizes production controls and assay performance; its presence underscores the role of certified quality systems in securing contracts with regulated buyers.
-
Export specialists (various) — Several suppliers position themselves for cross‑border trade to North America, Europe and Asia Pacific markets, supporting the qualification and logistics needs of multinational buyers.
Collectively, these firms reveal a market where differentiated service models (catalog reagent supplier vs. toll manufacturer vs. large‑scale chemical exporter) coexist. For buyers, matching supplier archetype to use case — analytical standard, pilot scale, or continuous supply for production — materially reduces time‑to‑qualification and total landed cost.
Strategic implications for 2026 corporate planning
-
Buyers should segment suppliers by strategic function: Reserve long‑term, volume contracts for manufacturers with documented capacity resilience and qualify catalog suppliers for R&D and lab needs. This two‑tier approach mitigates exposure to feedstock shocks while keeping innovation pipelines fed.
-
Invest in traceability and substitution pathways: Given regulatory monitoring under REACH and environmental scrutiny, firms should invest in impurity mapping, alternate chemistries where feasible, and forward inventory to cover regulatory delays.
-
Hedge exposure to bromine volatility: Input‑cost swings observed in late 2025–early 2026 advise the use of hedging strategies — long‑dated contracts, strategic bromine purchase agreements, or shared sourcing consortia among smaller buyers to stabilize supply and price.
-
Consider M&A and partnership plays: The market’s concentration suggests value in targeted acquisitions for vertical integration (bromination/halogenation capabilities) or strategic partnerships to secure guaranteed supply for high‑value downstream applications.
-
Prioritize certification and supply chain audits: Suppliers that maintain ISO standards, provide robust HSE documentation and can demonstrate low‑impurity manufacture will be preferred as regulators and customers heighten scrutiny.
Report contents — what PW Consulting delivers
Our full report is designed as an operational playbook for strategy, procurement, and product teams. Highlights include:
-
Market sizing and a transparent forecasting model with scenario analysis across demand shocks, feedstock volatility, and regulatory outcomes (base case, constrained supply, and accelerated regulation scenarios).
-
Supply chain heat maps and supplier scorecards evaluating technical capability, documentation readiness, capacity flexibility, and commercial terms.
-
Cost build‑ups and sensitivity analyses linking bromine and biphenyl inputs to landed cost at different trade points.
-
Practical go‑to‑market frameworks for suppliers (product positioning, purity premium strategies, and channel segmentation) and procurement playbooks for buyers (qualification pathways, dual‑sourcing templates, and inventory governance).
-
Regulatory tracker and compliance checklist focused on REACH monitoring and other jurisdictional obligations affecting production, waste handling and exports.
-
M&A and partnership screening, including valuation levers keyed to capacity, certification and customer concentration.
Methodology and data integrity
The study integrates proprietary supplier intelligence, third‑party pricing data, and primary interviews with industry stakeholders. The base year is 2025, with historical analysis covering 2020–2025 and forecasts constructed for 2026–2032. We apply a blended demand model that ties application‑level uptakes (consumer electronics materials, specialty polymers, laboratory reagents and specialty synthesis) to macro technology adoption curves, while conservatively modeling substitution and regulatory impact. Where public pricing benchmarks are volatile — notably bromine indices — our sensitivity layers present low, mid and high impact paths for decision use.
Next steps — how to use this insight
For executive teams, this brief functions as an orientation that converts market movement into prioritized actions: secure supply for critical applications, accelerate supplier qualification where purity and documentation give competitive leverage, and evaluate strategic investments to stabilize feedstock exposure. For procurement and product teams, the full report provides templates and supplier scorecards that materially shorten qualification timelines and improve negotiating positions.
PW Consulting’s full p.p'-Dibromobiphenyl Market Report contains the granular segmentation, supplier profiles, and downloadable data tables that corporate teams use to execute. For organizations that require an executable roadmap for 2026 — from hedging tactics to M&A screening — the full dossier provides the numbers and playbooks to move from insight to action.
Contact and access
Access to the comprehensive dataset, detailed supplier scorecards and scenario models is available via PW Consulting’s report distribution channels. Our team stands ready to provide bespoke briefings and rapid‑turn advisory to translate findings into procurement contracts, supplier audits, or strategic investments.
For detailed analysis of this topic, please visit the official page: p.p'-Dibromobiphenyl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com