
Blogs
Baobab Powder Market to Hit $568.91M by 2032, Reflecting 7.28% CAGR in New PW Consulting Report
By pmarketresearch, 2026-09-17
Strategic Intelligence in the Global Baobab Powder Market 2026-2032: Navigating Growth, Regulation, and Competitive Dynamics
The global baobab powder market stands at a pivotal inflection point. As consumer demand for plant-based superfoods, clean-label ingredients, and sustainable sourcing continues to accelerate, baobab fruit powder has transitioned from a niche wellness additive to a mainstream category across food and beverage, nutraceutical, and cosmetics applications. Our latest Worldwide Baobab Powder Market study delivers a comprehensive, decision-ready intelligence framework designed specifically for executives, procurement leaders, and strategic planners operating between 2026 and 2032.
Built on extensive primary research, analyst triangulation, and rigorous valuation modeling, this report equips organizations with the macro and micro insights required to allocate capital, secure supply chains, and position product portfolios ahead of structural market shifts. Rather than offering static snapshots, the analysis maps the trajectory of demand, evaluates the competitive landscape, and isolates the regulatory and operational variables that will define profitability in the coming years. This article provides a strategic preview of the report’s scope, methodology, and actionable architecture, demonstrating why it has become an essential reference for enterprise decision-making.
Market Trajectory and Strategic Context
The baobab powder market has demonstrated consistent expansion over the past half-decade, with the sector surpassing 324 million USD in 2024 and reaching approximately 347.87 million USD in 2025. Looking forward, our baseline projections indicate that market revenue will climb to 373.19 million USD in 2026, followed by a steady ascent toward 568.91 million USD by 2032. This trajectory translates into a compound annual growth rate of 7.28 percent across the forecast horizon, reflecting sustained institutional and consumer adoption, expanding formulation possibilities, and deepening global distribution networks.
Several structural factors underpin this momentum. Regulatory clarity has improved considerably across key import markets, with baobab fruit pulp and powder securing novel food approvals and regulatory endorsements in both the European Union and the United States. These milestones remove historical barriers to entry for food and beverage manufacturers, enabling faster product development cycles and broader retail penetration. Simultaneously, the U.S. Food and Drug Administration proposed a front-of-package nutrition labeling framework in 2025 that introduces simplified Low, Medium, and High indicators for saturated fat, sodium, and added sugar across most packaged goods, including superfood powders. While compliance requirements will reshape packaging and formulation strategies, they also create an opportunity for ingredient suppliers and brands that can position baobab powder as a clean, nutrient-dense, and label-friendly alternative.
Trade policy further shapes the competitive environment. The African Growth and Opportunity Act was renewed by the United States through December 31, 2026, preserving duty-free access for qualifying African exports, including baobab products from eligible countries. This provision reinforces the strategic importance of African-origin sourcing for North American importers and provides a measurable cost advantage for supply chains that align with AGOA eligibility criteria. On the pricing side, raw material economics have shifted meaningfully. Global export and import prices for baobab fruit powder trended downward in 2024, settling in a range of roughly 0.54 to 0.77 USD per kilogram, compared with elevated levels observed in 2023. This compression introduces both margin considerations and procurement opportunities, making it essential for buyers to distinguish between volatile spot pricing and long-term contract structures.
Worldwide Blackcurrant Powder Market
Report Architecture and Decision-Ready Intelligence
The Worldwide Baobab Powder Market report is engineered to translate complex market signals into executable strategy. It opens with a foundational market overview that establishes baseline sizing, growth velocity, and the macroeconomic and consumer trends shaping end-use demand. From there, the analysis moves into segmentation and demand mapping, examining how different natures of baobab powder and distinct end-use verticals contribute to overall revenue generation. Rather than presenting isolated percentages, the report contextualizes each segment through volume dynamics, pricing behavior, formulation trends, and buyer procurement patterns, enabling stakeholders to identify where demand is consolidating and where whitespace opportunities are forming.
A substantial portion of the study is dedicated to competitive intelligence. The report profiles the organizations that define pricing norms, control distribution pathways, and set quality expectations across multiple geographies. Coverage includes harvesters, bulk suppliers, wholesale distributors, and specialty ingredient formulators operating from North America, Europe, Southern Africa, and West Africa. Profiles capture headquarters locations, supply chain configurations, certification portfolios, product range breadth, and recent commercial activities. By mapping these players against their operational footprints and strategic positioning, the report provides a realistic view of who controls supply at each tier and how value is distributed across the chain.
The regulatory and compliance section addresses the practical requirements that govern market entry and ongoing operations. It details novel food obligations, food safety and quality standards, labeling expectations, and the documentation needed to maintain consistent import eligibility. This guidance is particularly valuable for brands expanding into the European Union, where quality control consistency and certification alignment directly influence clearance speed and retailer acceptance. The report also examines how proposed packaging and nutrition labeling frameworks will influence ingredient positioning, especially for superfood applications that depend on transparent front-of-pack communication.
Supply chain and raw material dynamics receive dedicated analysis, including export and import price movements, logistical considerations, and the impact of trade policy on landed costs. The study further incorporates a forward-looking risk and opportunity assessment that highlights concentration patterns, sourcing dependencies, certification requirements, and the commercial implications of sustainability verification. By integrating these elements, the report gives procurement teams, product developers, and strategy leaders a single reference point for evaluating cost structures, supply resilience, and market entry feasibility.
Competitive Landscape and Strategic Positioning
The baobab powder market is characterized by a broad, multi-tiered supplier base rather than heavy consolidation. Our concentration analysis indicates that the top three firms account for approximately 18.42 percent of market revenue, while the top five represent about 25.16 percent. This fragmented structure creates both challenges and opportunities. On one hand, it means that no single organization dominates pricing across all regions or end-use segments. On the other hand, it requires buyers to navigate a diverse ecosystem of harvesters, bulk exporters, regional warehouses, and specialty distributors, each with distinct capabilities, certification statuses, and commercial models.
Worldwide Baobab Powder Market
Several organizations define the market’s operational center of gravity. Baobest, also known as Baobab Foods LLC, operates from the United States and supplies organic baobab fruit powder to food, beverage, and wellness brands worldwide, supported by global shipping and premium quality certifications. B'Ayoba, based in Zimbabwe, is widely recognized as one of the largest global producers of ethically and sustainably harvested baobab products, sourcing from Southern African rural communities and standing as the first entity certified under the FairWild label. Baobab Exports, headquartered in South Africa with warehouses in the Netherlands and the United States, functions as a leading bulk organic supplier with international distribution reach and a foundational role in the African Baobab Alliance. KAIBAE, based in the United States, provides wild-harvested, certified organic baobab fruit powder, oil, and leaf to food, beverage, nutraceutical, and cosmetic markets, and recently expanded its North American footprint through a distribution partnership with Caldic North America to support nutrition companies seeking natural vitamins, minerals, fiber, and polyphenols.
Beyond these anchor players, the market includes a wide range of specialized and regional participants. Baobab Fruit Company Senegal serves as a major global producer of organic wholesale baobab powder and oil for food products, cosmetics, and animal feeds. Afriplex Pty Ltd produces baobab powder alongside oil and pulp, actively expanding its product lines for the ingredient market. Abbott Blackstone operates as a European wholesale distributor of organic baobab powder sourced from East Africa, supplying bulk quantities to food manufacturers and retailers. Nutriboost Superfoods functions as a B2B supplier offering high-quality organic powder in bulk, including private label options for superfood applications. Woodland Foods integrates baobab powder into chef-focused and foodservice applications, while Nexira supplies processed powder for food and nutraceutical uses with quality testing and formulation support. Additional contributors such as Eco-Products, Aduna Limited, Mighty Baobab Limited, and Organic Africa extend the supply base across Africa and Europe, each emphasizing distinct sourcing models, certification strategies, and application focuses.
This competitive breadth means that strategic success depends less on identifying a single dominant supplier and more on aligning sourcing decisions with product positioning, compliance requirements, volume needs, and sustainability expectations. The report evaluates these players not as a static roster, but as a living competitive field in which distribution partnerships, certification milestones, and regional warehouse networks continuously reshape access and pricing power.
Regulatory, Trade, and Sourcing Dynamics
Regulatory alignment remains one of the most decisive variables for market participants. Baobab powder’s progression through novel food approvals and regulatory endorsements in the European Union and United States has opened substantial application scope, but it has also raised the bar for documentation, traceability, and quality consistency. Importers and manufacturers must navigate evolving food safety expectations, maintain rigorous quality control across batches, and ensure that sourcing documentation supports both regulatory compliance and retailer requirements. The report details these obligations in practical terms, helping teams anticipate clearance requirements and reduce the risk of disruption.
Trade policy continues to influence landed cost and supply strategy. The renewal of AGOA through the end of 2026 preserves preferential access for qualifying African exports, reinforcing the commercial rationale for sourcing from eligible countries. For organizations building or expanding North American supply chains, this framework offers a measurable advantage, but it also requires careful eligibility verification and supply chain alignment. At the same time, raw material pricing dynamics remain fluid. The decline in global export and import prices during 2024 illustrates how market conditions can shift quickly, rewarding organizations that combine strategic contracting with active price monitoring and diversified sourcing options.
On the consumer and retail side, emerging labeling frameworks are poised to affect product architecture. The FDA’s proposed front-of-package indicators for saturated fat, sodium, and added sugar will influence how superfood powders are presented and evaluated by shoppers. Brands and ingredient suppliers that can demonstrate clean nutritional profiles, transparent sourcing, and formulation flexibility will be better positioned to adapt packaging and marketing strategies without compromising product integrity. The report integrates these dynamics into a broader assessment of how regulatory and retail trends will shape demand across applications.
Why This Research Matters for 2026 Decision-Making
Enterprise decisions made in 2026 will set the tone for competitive positioning through the end of the decade. Whether the objective is to secure reliable bulk supply, launch a new baobab-based formulation, evaluate private label opportunities, or assess regional expansion potential, organizations need a clear view of how market size, growth rate, competitive structure, and regulatory conditions interact. The Worldwide Baobab Powder Market report provides that view in a format built for action.
The study gives procurement leaders a framework for evaluating supplier options against volume requirements, certification expectations, and price trends. It supports product developers by mapping end-use demand patterns and identifying application areas where baobab powder’s functional and nutritional properties align with consumer priorities. It helps strategy and finance teams assess margin implications arising from raw material pricing, trade policy, and concentration dynamics. And it equips market access and compliance teams with the regulatory context needed to plan entries into the European Union and United States with greater confidence.
Equally important, the report is structured to support scenario planning. Because the market is influenced by certification evolution, trade policy renewal timelines, raw material price variability, and shifting retail labeling requirements, decision-makers benefit from an analysis that does more than report historical performance. It connects the dots between supply chain structure, regulatory momentum, and end-use adoption, allowing organizations to test assumptions and prepare for multiple plausible outcomes.
How to Use the Full Report
The preview above outlines the strategic architecture of the study, but the complete report delivers the detailed segmentation analysis, company profiling, regulatory guidance, and forward-looking scenario frameworks required for execution. Readers who need precise regional demand interpretations, application-level growth dynamics, sourcing cost considerations, and competitor benchmarking will find the full document designed to support those decisions directly.
The report is intended for use for cross-functional planning sessions, supplier evaluations, portfolio reviews, and market entry assessments. It combines quantitative framing with qualitative competitive insight, ensuring that executives can move from high-level market understanding to specific operational choices. For teams responsible for ingredient sourcing, product innovation, or international expansion, the analysis offers a structured basis for aligning commercial objectives with market realities.
Conclusion
The worldwide baobab powder market is expanding within a favorable but increasingly complex environment. Sustained revenue growth, improving regulatory access, active trade policy support, and a broad competitive landscape create meaningful opportunity, while pricing volatility, certification requirements, and evolving labeling expectations demand disciplined strategy. Our Worldwide Baobab Powder Market report translates these forces into a clear, decision-oriented intelligence platform for 2026 and the forecast period through 2032.
Organizations that engage with the full study will gain a more precise understanding of where demand is forming, how supply is structured, which players are shaping competitive norms, and what regulatory and trade conditions will influence cost and access. For decision-makers seeking to act with confidence in a fast-moving category, the report provides the depth, structure, and strategic context needed to convert market insight into executable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Baobab Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Armodafinil Market to Hit $647.62M by 2032, Driven by 4.52% CAGR and North America
By pmarketresearch, 2026-09-17
Strategic Imperatives in the Global Armodafinil Market: Navigating Growth, Regulation, and Competitive Shifts Through 2032
The worldwide armodafinil market stands at a critical inflection point as it enters the 2026–2032 forecast horizon. For pharmaceutical executives, investors, and healthcare supply chain strategists, understanding the forces shaping this wakefulness-promoting agent’s commercial trajectory is no longer optional. PW Consulting’s latest Worldwide Armodafinil Market research report delivers a comprehensive, forward-looking intelligence framework designed to support evidence-based decision-making across R&D, commercialization, and market access functions. With rigorous historical tracking from 2020 through 2025 and a structured outlook extending to 2032, this study provides the analytical depth required to anticipate demand shifts, regulatory bottlenecks, and competitive repositioning in a space where intellectual property transitions and controlled-substance oversight intersect.
Market Evolution and the Strategic Relevance of Macro Forecasts
Armodafinil has established itself as a cornerstone therapy for excessive daytime sleepiness across multiple sleep-related indications, driven by clinical adoption in narcolepsy, obstructive sleep apnea, and shift work sleep disorder. Over the historical window from 2020 to 2025, the market demonstrated consistent top-line expansion, with global revenue progressing from 385.2 USD Million in 2020 to 475.25 USD Million in 2025. This trajectory reflects sustained prescription volumes alongside the gradual maturation of generic supply networks. Looking ahead, the compound annual growth rate is projected at 4.52 percent across the 2026–2032 forecast period, signaling a steady but measured expansion phase rather than a speculative surge. By 2032, aggregate market size is expected to reach 647.62 USD Million.
For corporate strategy teams, these headline figures are only the starting point. The real value lies in how growth compounds across dosage strengths, therapeutic indications, and regional distribution channels, and how structural constraints such as controlled-substance manufacturing quotas modulate supply reliability. Our analysis contextualizes the 4.52 percent CAGR within a regulatory and competitive environment where pricing pressure, generic substitution dynamics, and DEA quota cycles interact to shape realizable market share. Decision-makers relying on static sizing alone risk misallocating commercial resources; this report translates macro growth into actionable scenario planning.
Report Architecture: Translating Data into Execution-Ready Intelligence
The Worldwide Armodafinil Market report is structured to move beyond descriptive market sizing and into operational guidance. Each analytical module is designed to answer specific executive questions:
- Comprehensive historical and forecast revenue modeling that isolates baseline demand trends from one-off regulatory or supply disruptions
- Segment-level breakdowns across indications, dosage strengths, and geographic markets, with attention to adoption velocity and substitution patterns rather than surface-level share figures
- Competitive profiling of originator and generic manufacturers, mapping product portfolios, approval statuses, API sourcing strategies, and recent rights acquisitions
- Regulatory and supply chain risk assessment covering controlled-substance scheduling, DEA quota mechanics, and documented availability patterns observed in early 2026
- Strategic recommendations for market entry, portfolio expansion, generic positioning, and supply chain resilience in a quota-constrained manufacturing environment
By embedding quantitative forecasts within qualitative operational context, the report equips stakeholders to evaluate not just how large the market may become, but how value will be captured under differing competitive and regulatory conditions.
Competitive Landscape: Originator Positioning, Generic Acceleration, and Strategic Consolidation
The competitive architecture of the armodafinil market has undergone material shifts as foundational patents expired in 2024, opening the door to expanded multisource generic competition. Teva Pharmaceutical Industries Ltd., operating through its legacy Cephalon subsidiary, remains the originator of Nuvigil and continues to supply both the reference listed drug and generic formulations worldwide. Its enduring presence anchors a market where branded heritage and generic scale coexist, particularly in narcolepsy and obstructive sleep apnea segments where clinical familiarity drives prescriber behavior.
A defining strategic move in early 2025 came from Apotex Inc., via its Nuvo Pharmaceuticals affiliate. In January and February 2025, the company finalized the acquisition of U.S. marketing rights to branded NUVIGIL, integrating the asset into Apotex’s diversified portfolio. This consolidation of branded rights alongside existing generic capabilities positions Apotex to navigate both premium and value-oriented channels, a dual-strategy posture that is increasingly relevant as payers and formularies seek flexibility in wakefulness-promoting therapies.
The generic supply side is heavily anchored by Indian pharmaceutical manufacturers with FDA-approved facilities and active API-to-finished-dosage capabilities. Lupin Ltd., Natco Pharma Ltd., and Aurobindo Pharma Ltd. each maintain approved armodafinil tablet lines across multiple strengths and serve as critical nodes in global distribution. Mylan Pharms Inc., now operating under Viatris, contributes a long-standing U.S. and international generic supply footprint. Collectively, these players reinforce a market structure in which concentration is meaningful but not absolute, with the top three and top five players holding substantial combined share. This concentration shapes pricing negotiations, tender competitiveness, and supply continuity expectations.
Worldwide Armodafinil Market
API sourcing represents an equally important layer of the competitive picture. Producers such as Acura Labs, Unimark Remedies Ltd., HRV Pharma, and Wellona Pharma provide GMP-compliant armodafinil API with full documentation support for global finished-product manufacturers. The availability of qualified API sources has enabled rapid scale-up following patent expiry, but it also means that supply chain resilience depends on the reliability of quota-adjusted production planning and the ability of API suppliers to align output with DEA semi-annual allocation cycles.
Regulatory and Supply Chain Dynamics: The Quota Constraint as a Strategic Variable
Armodafinil’s classification as a Schedule IV controlled substance in the United States introduces structural complexity that extends well beyond routine pharmaceutical compliance. The DEA manufacturing quota system imposes production limits and licensing requirements that directly affect annual output volumes. Implementation of semi-annual quota allocations since 2023 has introduced timing challenges for manufacturers, requiring closer coordination between API procurement, finished-dose production scheduling, and distribution logistics.
While armodafinil is not listed on official FDA or ASHP drug shortage databases as of early 2026, patient and channel reports of intermittent availability issues persist. These disruptions are typically attributable to the interaction of quota constraints, manufacturing concentration, and demand variability rather than a single systemic failure. For market participants, this environment rewards proactive capacity planning, diversified supplier relationships, and scenario-based inventory strategies. Companies that treat quota cycles as a fixed background condition rather than a manageable variable risk exposing their commercial timelines to avoidable volatility.
Why 2026 Decision-Makers Need This Research Now
The 2026 landscape demands a more granular understanding of how growth, regulation, and competition interact. With patent expiry already enabling broader generic participation and branded rights consolidating under new ownership, the window for strategic positioning is active. Simultaneously, controlled-substance oversight continues to influence production cadence, making supply-side intelligence as important as demand forecasting. PW Consulting’s report is built to support:
Vinpocetine Market
- Portfolio and launch planning that accounts for dosage strength preferences and indication-specific adoption curves
- Competitive response strategies in a market where originator presence, branded rights acquisition, and generic scale are all in flux
- Risk-adjusted supply planning that incorporates DEA quota timing and API sourcing redundancy
- Market access and pricing considerations shaped by concentration dynamics and regional demand distribution
Rather than presenting isolated statistics, the study integrates segmentation context, corporate profiles, regulatory mechanisms, and recent proprietary developments into a unified strategic narrative. This allows executives to evaluate opportunity sizing alongside execution risk, a distinction that separates reactive market participation from deliberate value capture.
Conclusion: From Market Awareness to Strategic Advantage
The worldwide armodafinil market is entering a phase where steady growth coexists with evolving competitive ownership and persistent regulatory constraints. The projected expansion from 482.41 USD Million in 2026 toward 647.62 USD Million by 2032 reflects a market that is maturing, not saturating, and where share dynamics will be determined by execution quality as much as by underlying demand. PW Consulting’s Worldwide Armodafinil Market research provides the structured intelligence needed to navigate this environment with confidence. For leaders seeking detailed segmentation analysis, competitive benchmarking, regulatory scenario modeling, and region-specific demand context, the full report offers the complete evidence base required to translate market insight into operational advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Armodafinil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Purity Alumina Sol Market Hits $140M in 2025, Forecast 14% CAGR to $350M by 2032
By pmarketresearch, 2026-09-17
Navigating the High Purity Alumina Sol Horizon: Strategic Imperatives for 2026 and Beyond
The high purity alumina sol market stands at a critical inflection point. For decision-makers in specialty chemicals, advanced materials, and downstream manufacturing, the ability to read the signals of this evolving landscape will separate the prepared from the reactive. Our latest market intelligence release maps the trajectory of this sector with a forensic lens, transforming raw data into a navigable framework for enterprise strategy. As capital allocation and R&D roadmaps transition from 2025 baselines into the 2026–2032 horizon, understanding the velocity, structural drivers, and competitive fault lines of this market is no longer optional. It is a strategic requirement.
The Trajectory: From Steady Growth to Accelerated Expansion
The market's historical arc tells a story of compounding momentum. Between 2020 and 2025, the sector progressed through a period of robust scaling, with revenue climbing from 75.4 million USD to 140.0 million USD. This five-year climb reflects more than cyclical demand; it signals a structural awakening as high purity alumina sol cements its role across high-performance applications.
Looking ahead, the forecast period from 2026 through 2032 paints a picture of sustained acceleration. The base year of 2025 anchors at 140.0 million USD, with the market projected to cross 155.95 million USD in 2026 and continue its ascent toward 350.32 million USD by 2032. This expansion is underpinned by a compound annual growth rate of 14.0%, a velocity that places the sector firmly in growth-market territory. For executives building scenario models, this CAGR is more than a headline figure. It represents the pace at which addressable demand, manufacturing capacity, and value-chain integration will need to adapt.
What makes this trajectory strategically significant is the combination of scale and speed. A market nearly doubling in size over a seven-year window demands careful timing in capacity planning, supply agreements, and product portfolio decisions. The data behind this forecast reveals nuanced inflection points—periods where adoption curves steepen, where regional production shifts alter cost dynamics, and where application-specific demand creates pockets of outsized opportunity. These patterns are mapped in detail within the full study, but their strategic implication is clear: the window to build defensible positions is opening now.
Segment Architecture: Where Demand Energy Concentrates
No market moves uniformly. The architecture of demand in this sector reveals distinct concentration patterns that influence pricing power, production priorities, and partnership pathways. By type, water-based alumina sol solutions command a dominant share of the market, reaching 104.89 million USD, while solvent-based variants account for 35.11 million USD. This split suggests that aqueous dispersion technologies are aligning with broader industry shifts toward safer handling, regulatory compliance, and lower environmental footprints. For manufacturers, the choice between solvent and water-based formulations is increasingly tied to downstream customer requirements and process compatibility rather than simple cost arbitrage.
The application landscape further illuminates where growth energy is concentrated. Lithium-ion battery separators represent the largest single demand pillar, with a market size of 88.2 million USD. This positioning reflects the ongoing electrification of transport and energy storage, where high purity alumina sol serves as a critical functional coating that enhances thermal stability and mechanical integrity. The scale of this application channel means that even modest shifts in battery adoption rates, separator specifications, or coating process efficiencies can ripple through the entire alumina sol value chain.
Beyond the dominant channel, several specialized applications contribute meaningful and growing demand. Catalysts and support applications account for 22.72 million USD, precision ceramics contribute 18.65 million USD, and semiconductors and electronics add 10.43 million USD. Each of these segments carries its own technical requirements, qualification cycles, and growth catalysts. Catalyst carriers and support materials, for instance, intersect with refining, petrochemical, and specialty chemical processes where alumina sol's surface properties and dispersion stability are essential. Precision ceramics leverage high purity grades for advanced structural and functional components. Semiconductor and electronics applications demand stringent purity and particle-size control, linking the market to the broader trajectory of advanced manufacturing and miniaturization. The report examines how these segments interact, where substitution risks exist, and which applications are likely to drive incremental volume growth across the forecast period.
Regional Dynamics and Supply Chain Architecture
Geography shapes both opportunity and constraint. Asia Pacific dominates the market with a regional size of 82.29 million USD, reflecting the concentration of manufacturing capacity, downstream industrial demand, and investment in advanced materials across the region. North America follows at 28.53 million USD, Europe at 21.2 million USD, and the Rest of the World at 7.98 million USD. These figures do not merely describe where revenue is generated today; they indicate where supply-chain relationships, production footprints, and partnership ecosystems are most likely to evolve.
For companies evaluating market entry, expansion, or sourcing strategies, regional dynamics require careful reading. The balance between regional self-sufficiency and cross-border trade, the localization of precursor feedstocks, and the proximity of high-value applications all influence cost structures and responsiveness. The full analysis breaks down how these regional channels differ in terms of growth trajectories, demand character, and competitive intensity, giving strategists a basis for allocating resources with geographic precision.
Competitive Landscape: Concentration, Capability, and the Firms Shaping the Field
Market structure matters as much as market size. With a CR3 of 54.2% and a CR5 of 72.8%, the sector exhibits meaningful concentration, yet retains enough fragmentation that regional specialists and application-focused producers can carve out defensible niches. In such an environment, competitive advantage rarely comes from size alone. It emerges from formulation expertise, process control, customer qualification relationships, and the ability to align product grades with specific application requirements.
A global cohort of firms is actively shaping this landscape. Nissan Chemical, headquartered in Japan, offers high purity alumina sol as nano dispersions tailored for coatings, catalysts, and precision applications. Its product positioning reflects a focus on dispersion quality and functional performance across demanding end uses. Sasol Performance Chemicals, based in South Africa, produces and supplies high purity alumina sol grades for catalyst carriers, advanced ceramics, coatings, and specialty chemical uses, linking its portfolio to both industrial and performance-driven segments.
The APAC region also hosts a practical array of manufacturers that serve specialized industrial channels. Zibo Jiarun operates as a manufacturer of high purity alumina sol for refractory coatings, ceramic treatment, and industrial binding applications, while Hangzhou Veking produces high purity alumina sol for coatings and industrial uses. Zibo Jinqi focuses on high purity alumina sol product manufacturing, and Beijing Yataiaohua supplies the material for specialty applications. Zibo Senchi produces high purity alumina sol for refractory and coating markets, rounding out a regional ecosystem that underscores the breadth of industrial demand and the role of application-specific suppliers.
High Purity Alumina Sol Market
In Japan, beyond Nissan Chemical, Kawaken Fine Chemicals supplies high purity alumina sol for catalyst and ceramic precursor applications, and JGC Catalysts and Chemicals provides high purity alumina sol used in catalysts and fine chemical processes. These firms demonstrate how specialized chemistry expertise can translate into sustained relevance within controlled-process industries.
In the United States, Nyacol Nanotechnologies specializes in colloidal dispersions including high purity alumina sol for coatings and performance materials, while Wesbond offers high purity alumina sol for refractory and ceramic binding systems. Together, these companies illustrate how regional producers maintain competitive positioning by targeting performance-grade applications and serving technical customers who value consistency, purity, and material compatibility.
The strategic implication of this competitive map is straightforward: customers and investors should evaluate suppliers not just by scale, but by their alignment to specific application channels, their process reliability, and their ability to sustain quality across batches and production cycles. The report profiles these firms and their positioning in greater depth, examining how their product lines intersect with the largest demand channels and where differentiation is likely to crystallize over the forecast period.
Raw Material Vectors and Cost Dynamics
Feedstock conditions exert a direct influence on production economics and margin trajectories. Aluminum hydroxide serves as a key precursor feedstock for high purity alumina sol production via controlled hydrolysis or peptization processes, making its price behavior a material factor in cost modeling. Recent market observations show a divergence in regional pricing that warrants attention.
In Northeast Asia, aluminum hydroxide prices reached 0.24 USD per kilogram in March 2026, reflecting a 17.2% decline from December 2025. This movement was driven by weakened downstream demand and excess inventories, signaling a period of input-cost relief for producers sourcing in that region. Europe saw aluminum hydroxide prices at 0.63 USD per kilogram in March 2026, with a more moderate 3.1% decline from December 2025 linked to softer demand in flame retardants and construction. North America recorded prices at 0.59 USD per kilogram in March 2026, supported by steadier demand from flame retardants and specialty chemicals despite upstream variations.
These regional differences matter because they affect the relative cost position of producers operating in different geographies and influence the economics of export-oriented supply. The broader context of the aluminum hydroxide market, valued at 12.75 billion USD in 2025 and projected to reach 13.28 billion USD in 2026, further situates the precursor environment within a large and dynamic commodity landscape. Understanding how these input trends interact with regional alumina sol production, inventory cycles, and pricing strategies is essential for building resilient cost assumptions. The full study connects these raw-material signals to the broader market framework, helping leaders anticipate where cost advantages may emerge and where volatility could reshape sourcing decisions.
What the Report Delivers: An Operational Toolkit, Not a Static Snapshot
Strategic intelligence is only valuable if it can be deployed. This study is built to translate market behavior into decision-ready structure. It moves beyond aggregate figures to give executives, procurement leaders, R&D directors, and investors a functional view of how the market is organized and where critical leverage points lie.
At its core, the report provides a layered market model that connects historical performance with the 2026–2032 forecast period. It outlines the market's expansion path, draws attention to the segments and applications driving incremental growth, and identifies the channels where demand is likely to accelerate most rapidly. The segmentation analysis examines how type-based and application-based demand structures interact, helping readers understand which product channels are aligned with the largest volume pools and which are positioned for higher-margin, technically demanding use cases.
Beyond sizing and segmentation, the report includes competitive profiling that places key manufacturers within the context of their product focus, regional presence, and application alignment. It also integrates ingredient and feedstock dynamics into the market narrative, so that cost assumptions are grounded in observable raw-material behavior rather than abstract averages. This integrated approach is designed to support practical decisions: where to invest, how to structure supply, which applications to prioritize, and how to evaluate competitive threats and partnership opportunities.
For teams planning 2026 initiatives, the report serves as a reference point for scenario building. It helps answer questions such as how shifts in battery adoption pathways could alter coating demand, how regional cost differentials might influence sourcing or production footprints, and how concentration in the competitive field could affect negotiation leverage and market entry timing. The detail behind these insights is preserved in the full document, where segmentation splits, application-level sizing, regional breakdowns, and company-level profiles are presented with the granularity needed for operational planning.
Strategic Horizon for 2026: Positioning for What Comes Next
The next phase of this market will favor organizations that can act with both speed and precision. A double-digit CAGR over a multi-year forecast window, a concentrated but still diverse competitive field, and a demand structure anchored by a dominant application channel create a landscape where timing, differentiation, and supply-chain coherence determine outcomes. Leaders will need to assess how their product portfolios align with the highest-growth applications, how their sourcing strategies respond to regional raw-material dynamics, and how their commercial models can capture value in a market where technical performance and consistency are increasingly determinative.
For investors, the opportunity lies in understanding which segments and regional channels offer the most favorable risk-adjusted growth profiles. For producers, the priority is to ensure that capacity, formulation capability, and customer relationships are aligned with the applications that will drive incremental volume. For buyers and downstream manufacturers, the imperative is to map supply resilience, qualify partners with compatible technical capabilities, and anticipate how cost and availability trends may shape procurement over the forecast period.
This market study is designed to give each of these audiences a shared, rigorous foundation for decision-making. It preserves the macro structure that frames strategic direction while embedding the granular intelligence necessary for execution. We invite you to explore the full report to access the detailed segmentation data, regional and application-level sizing, competitive profiles, and raw-material context that complete the picture. In a market expanding at this pace, the advantage belongs to those who move from awareness to informed action.
High Purity Boehmite Market
For detailed analysis of this topic, please visit the official page: High Purity Alumina Sol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
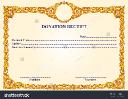
A donation receipt is an official document that confirms a charitable organization has received a contribution from a donor. It provides a record of the donation and can help both the donor and organization maintain accurate financial documentation.
People donate to NGOs, charitable trusts, nonprofit organizations, and other eligible institutions for many reasons. Since donations can be made through UPI, bank transfers, cards, cheques, cash where permitted, and online platforms, maintaining a proper record of every contribution is important.
What Is a Donation Receipt?
A donation receipt is a document issued by a charitable organization to acknowledge a donation. It normally identifies the donor, amount contributed, date of payment, and details of the organization receiving the contribution.
For example, if a donor contributes ₹5,000 to an eligible charitable organization, the organization may issue a receipt confirming the amount received.
The receipt can be provided in printed or digital form, depending on the organization's donation and accounting system.
Why Do You Need a Donation Receipt?
Keeping a donation receipt offers several practical benefits.
Proof of Contribution
A receipt confirms that the organization received the donation. It can be retained as evidence of the transaction.
Easy Financial Tracking
If you donate to different organizations throughout the year, individual receipts make it easier to track your total charitable contributions.
Tax Documentation
Some donations may qualify for tax deductions when the applicable legal requirements are satisfied. In such cases, the relevant receipt or other documentation can help maintain records for a tax claim.
However, not every donation qualifies for a deduction. Donors should verify the applicable tax rules and the eligibility of the recipient organization.
Better Record Management
A receipt creates a clear connection between the donor, organization, amount, and date of the contribution. This can be helpful if a payment needs to be verified later.
What Details Should a Donation Receipt Include?
A properly prepared receipt generally contains important information about the contribution.
Common details include:
- Name of the organization
- Registered address
- Receipt number
- Date of donation
- Donor's name
- Donation amount
- Payment method
- Transaction or reference number
- Purpose of donation, where applicable
- Relevant registration information
- Applicable tax-related information
- Authorized signature or digital authentication
The exact requirements can vary depending on the organization and applicable regulations.
Sample Donation Receipt Format
A basic donation receipt can look like this:
DONATION RECEIPT
Organization Name: ABC Charitable Trust
Receipt No.: 2026-00125
Date: 16 September 2026
Donor Name: __________________
Donation Amount: ₹____________
Payment Method: ______________
Transaction ID: _______________
Purpose of Donation: Charitable Activities
We acknowledge receipt of the above contribution.
Authorized Signatory
ABC Charitable Trust
Organizations should modify this format according to their specific accounting and legal requirements.
How to Get a Donation Receipt
Most organizations issue a receipt after receiving a donation. For online donations, the receipt may be generated automatically and sent to the email address provided during the payment process.
If you do not receive a receipt, contact the organization and share relevant payment details, such as:
- Donor name
- Donation amount
- Date of payment
- Payment method
- Transaction ID
- Registered email address
The organization can use these details to locate the transaction and provide the appropriate documentation.
Digital Donation Receipt
Digital donation receipts are increasingly common because they are convenient and easy to store. An organization may send the receipt as a PDF attachment or provide a download option through its website.
Donors should save digital receipts in a secure location and keep them with their payment confirmations.
For regular donors, creating folders based on financial years can make it easier to locate old receipts.
Donation Receipt for Tax Benefits
A donation receipt can be relevant when maintaining documents for an eligible tax deduction. However, whether a donation qualifies depends on the applicable tax provisions, the recipient organization's eligibility, the type of contribution, and other conditions.
Before claiming a deduction, donors should confirm the relevant requirements and retain all necessary documentation.
A receipt should therefore be viewed as evidence of the contribution rather than an automatic guarantee of a tax benefit.
Donation Receipt for NGOs
NGOs can use donation receipts to maintain systematic records of contributions received from individuals, businesses, and other donors.
A good receipt-management process can help an organization:
- Track donations accurately
- Assign unique receipt numbers
- Maintain donor records
- Record payment details
- Issue receipts promptly
- Organize financial documentation
- Provide donors with appropriate acknowledgment
Digital systems can make this process faster and reduce manual record-keeping work.
Common Mistakes to Avoid
When handling donation receipts, donors should avoid the following mistakes:
- Not saving the receipt
- Providing incorrect donor information
- Failing to check the donation amount
- Losing the transaction reference
- Assuming every donation is tax-deductible
- Ignoring errors on the receipt
- Not requesting a receipt when one is expected
Reviewing the receipt after receiving it can help identify errors quickly.
Tips for Keeping Donation Receipts
To maintain good records, donors can:
- Save digital copies immediately.
- Keep payment confirmations with receipts.
- Organize documents by financial year.
- Check donor information and donation amount.
- Keep transaction IDs available.
- Verify tax eligibility before making a claim.
- Contact the organization if the receipt contains incorrect information.
These simple steps can make donation record management much easier.
Conclusion
A donation receipt provides official confirmation that a charitable contribution has been received by an organization. It is useful for maintaining financial records, tracking charitable contributions, and supporting documentation where a donation is eligible for a tax benefit.
Whether you donate online or offline, keeping your receipt and payment confirmation is a good record-keeping practice. Donors should also verify the applicable tax requirements and the eligibility of the recipient organization before claiming any deduction.
FAQs About Donation Receipts
What is a donation receipt?
A donation receipt is an acknowledgment issued by a charitable organization confirming that it has received a contribution from a donor.
Can a donation receipt be issued online?
Yes. Many organizations issue digital receipts through email or online donation platforms.
What information is included in a donation receipt?
It generally includes the organization name, donor name, donation amount, date, receipt number, payment method, and transaction details.
Is a donation receipt required for a tax deduction?
A receipt may be an important supporting document, but tax-deduction eligibility depends on applicable laws and the recipient organization's eligibility.
How can I get a duplicate donation receipt?
If you lose your receipt, contact the organization that received your donation and provide the payment date, amount, transaction ID, and donor details.
PW Consulting: SMA Market Hits $163.1M in 2025, Projected 5.48% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Horizons in the Global Stearyl Methacrylate Market: A 2026 Executive Briefing
The global specialty chemicals sector continues to demonstrate remarkable resilience and adaptability, with niche intermediates playing increasingly critical roles in downstream performance formulations. Among these, Stearyl Methacrylate (SMA) has emerged as a vital functional monomer bridging the gap between polymer science and industrial application. As we move further into the mid-2020s, executives and strategic planners across coatings, lubricant, and personal care industries require a precise, data-backed understanding of market trajectories to navigate supply chain complexities, pricing volatility, and shifting regulatory landscapes.
This article serves as a strategic preview of our latest comprehensive research initiative: the Worldwide Stearyl Methacrylate (SMA) Market study. Drawing on extensive historical analysis and forward-looking modeling, this report is designed to empower decision-makers with the intelligence necessary to capitalize on growth opportunities from 2026 through 2032. Below, we explore the macro-economic foundations, competitive architectures, and operational dynamics that define this evolving landscape, offering a compelling case for why deep-dive intelligence is indispensable for your next strategic move.
Styrene-Maleic Anhydride Copolymer Market
Market Trajectory: A Decade of Resilient Expansion
Understanding the historical baseline and future velocity of the SMA market is fundamental to capacity planning and investment allocation. Our analysis tracks a robust growth curve that underscores the material's entrenched position across multiple high-value sectors. From a market valuation in the early 2020s, the global Stearyl Methacrylate market has demonstrated consistent upward momentum, driven by steady industrial demand and the ongoing innovation in polymer-modified formulations.
Looking at the macro data, the market closed the base year of 2025 at approximately 163.1 million USD. This figure represents the culmination of a steady historical climb from 2020 onwards, reflecting the sector's ability to maintain demand even amidst global macroeconomic headwinds. More critically, the forecast period projects a sustained compound annual growth rate (CAGR) of 5.48 percent from 2026 to 2032. By the end of this forecast window, the market is anticipated to approach a valuation nearing 237 million USD.
Such growth is not merely linear expansion; it signals structural intensification. The mid-to-late 2020s forecast indicates a phase where demand creation begins to outpace basic replacement cycles, fueled by advanced applications in high-performance lubricants and next-generation personal care formulations. Recognizing these inflection points is vital for stakeholders aiming to align their production capacities, inventory strategies, and R&D investments with market realities. Our report dissects these temporal shifts, providing a granular timeline that highlights when specific growth accelerants are expected to materialize across the value chain.
Application Dynamics: The Multifaceted Demand Engine
Stearyl Methacrylate is not a commodity chemical; its value lies in its functional versatility. The demand landscape is shaped by several key application verticals, each with distinct consumption patterns, pricing sensitivities, and technical requirements. Lubricant additives represent a dominant force within the market, where SMA functions as a critical component in viscosity index improvers and pour point depressants for paraffinic oils. As the automotive and industrial machinery sectors push toward longer drain intervals and improved fuel efficiency, the reliance on advanced polymeric additives continues to deepen.
Parallel to the industrial sector, the personal care and cosmetics industry leverages the emollient and film-forming properties of SMA. The shift toward high-performance, aesthetically pleasing skincare and haircare formulations has sustained demand in this segment, particularly in premium product lines where texture and stability are paramount. Furthermore, applications in adhesives, sealants, and coatings showcase the monomer's ability to enhance adhesion, durability, and chemical resistance, making it indispensable in construction, packaging, and protective coating formulations.
Our market study goes beyond mere application identification. It maps the interplay between these sectors, analyzing how fluctuations in one vertical—such as a surge in automotive lubricant demand—can ripple through supply allocations and pricing structures for others. By understanding the relative weight and growth trajectories of these application verticals, companies can better predict where demand spikes will occur and how to prioritize their customer engagement and product development pipelines. The report provides a systematic breakdown of these application dynamics, revealing which segments are poised for the most significant volume shifts and value creation over the coming years.
Geographic & Segment Dimensions: Unpacking Regional Strengths
Geography remains a decisive factor in market strategy, influencing everything from raw material sourcing to competitive positioning. The Asia Pacific region stands out as a formidable hub of consumption and production, reflecting the broader shift of global manufacturing and chemical processing capabilities toward this highly industrialized zone. North America and Europe continue to hold substantial market footprints, driven by mature industrial bases, stringent quality standards, and steady demand in specialty coatings and personal care sectors.
In addition to regional consumption patterns, purity specifications play a critical role in market segmentation. The market is broadly divided between standard purity grades, which cater to volume-driven industrial applications, and high-purity variants that serve niche, high-performance requirements where impurity thresholds are strictly controlled. The balance between these purity tiers is not static; it evolves alongside technological advancements in synthesis and downstream processing capabilities. Companies that fail to appreciate the nuance between standard and high-purity demand risk misalignment in their product portfolios and pricing strategies.
This research deliverable includes a detailed geographic and segment analysis that maps these regional and purity-based dimensions. It illuminates where the highest concentration of value is generated, how regional supply-demand balances interact, and what strategic implications arise from shifting production footprints. For executives evaluating potential market entry, diversification, or capacity expansion, this geographic and segment intelligence is a cornerstone of risk mitigation and opportunity capture.
Competitive Landscape: Key Players and Strategic Positioning
The Stearyl Methacrylate market exhibits a moderately concentrated structure, with a select group of global specialty chemical manufacturers commanding significant market share. Our analysis highlights a competitive environment where established players leverage integrated production capabilities, global distribution networks, and deep technical expertise to maintain their positions. Key companies profiled in our research include industry giants such as BASF SE, headquartered in Ludwigshafen, Germany, which offers specialized SMA grades such as SMA 1618 and SMA 1618 F, utilized across coatings, oil additives as flow improvers and pour point depressants, and as feedstock for chemical syntheses.
From the Asian market, Mitsubishi Gas Chemical Company, Inc. and NOF Corporation stand as pivotal suppliers. Mitsubishi Gas Chemical produces and supplies SMA for applications encompassing fiber treatment agents, coating compounds, and adhesive compounds, reflecting a broad application portfolio. NOF Corporation lists and supplies stearyl methacrylate as part of its comprehensive functional monomers and oleo & specialty chemicals portfolio, underscoring its strategic integration within a wider high-performance chemicals ecosystem. Additionally, Jamorin International, operating globally with headquarters in Luxembourg, supplies SMA 1618 F specifically tailored for oil additives, functioning as a viscosity index improver and pour point depressant for paraffinic oils.
The competitive dynamics are further shaped by market concentration metrics, indicating that a relatively small number of firms control a substantial portion of the market revenue. This concentration suggests that competitive responses to price changes, capacity adjustments, or technological innovations can have amplified effects across the entire supply chain. Our report provides a deep-dive competitive analysis, examining the strategic profiles of these key players, their product diversification strategies, and their positioning relative to market segments. By understanding the strengths, vulnerabilities, and potential moves of these incumbents, new entrants and existing participants can craft more effective competitive strategies.
Raw Material Dynamics & Supply Chain Resilience
Any robust market analysis must account for the upstream factors that influence production costs and supply stability. Stearyl Methacrylate is produced via the esterification of methacrylic acid with stearyl alcohol, also known as octadecan-1-ol. This means that the availability, pricing, and quality of stearyl alcohol are primary drivers of SMA production economics. Stearyl alcohol itself is a key upstream fatty alcohol feedstock, derived from either natural oils or petrochemical sources, introducing a degree of volatility tied to agricultural commodity markets and energy pricing.
Historically, variations in raw material supply have impacted production schedules and margin structures for manufacturers. The synthesis process requires precise control over reaction conditions and purification steps to meet the purity specifications demanded by downstream customers. Consequently, supply chain resilience depends not only on securing reliable sources of methacrylic acid and stearyl alcohol but also on maintaining robust processing infrastructure capable of handling both standard and high-purity production runs.
Our market study integrates a thorough examination of these raw material dynamics. It explores the historical context of feedstock availability, the interplay between natural and synthetic sourcing routes, and the implications of input cost fluctuations for end-market pricing. For procurement teams, operations managers, and strategic planners, understanding these upstream linkages is essential for building cost models that withstand volatility and for negotiating contracts that hedge against supply disruptions.
Strategic Imperatives for 2026 and Beyond
As we step into 2026, the Stearyl Methacrylate market presents a confluence of opportunities and challenges that demand proactive strategic planning. The projected growth trajectory suggests that demand will continue to outpace simple population or GDP growth, pointing to genuine value creation in high-performance applications. However, realizing this growth requires companies to navigate a complex environment characterized by regional supply-demand imbalances, evolving purity requirements, and an increasingly sophisticated competitive landscape.
Strategic decisions in the coming year must be grounded in precise intelligence. Whether an organization is considering capacity expansion, product line optimization, geographic market entry, or vertical integration, the ability to quantify opportunity and assess risk is paramount. This includes evaluating how shifts in lubricant formulation standards, cosmetic ingredient trends, or adhesive performance requirements will reshape demand profiles. It also involves anticipating how major market players might adjust their inventories, pricing, or M&A activities in response to macroeconomic signals.
The findings contained in our Worldwide Stearyl Methacrylate Market research are structured to support these high-stakes decisions. By combining historical data, forward-looking forecasts, competitive profiling, and application-specific insights, the report provides a 360-degree view of the market. It enables stakeholders to move beyond anecdotal assessments and base their strategies on rigorous, validated analysis.
For executives and analysts seeking to secure a competitive edge, the depth of information available in this comprehensive market study is indispensable. To explore the full suite of data, detailed regional breakdowns, segment-specific projections, and an exhaustive competitive intelligence dossier, we invite you to access the complete research deliverable. The full report offers the granular detail and actionable insights necessary to translate market understanding into tangible business growth.
Worldwide Stearyl Methacrylate (SMA) Market
For detailed analysis of this topic, please visit the official page: Worldwide Stearyl Methacrylate (SMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Industrial Diaphragm Pump Market Hits $6.86B in 2025, Projected 5.15% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Industrial Diaphragm Pump Market
As industrial operations grow increasingly complex, the demand for reliable, efficient, and compliant fluid handling solutions has never been more critical. The global industrial diaphragm pump market stands at a pivotal juncture, shaped by evolving regulatory frameworks, raw material volatility, and a decisive shift toward energy-efficient and digitally integrated pumping technologies. For executives, procurement leaders, and strategy teams operating in 2026, understanding the structural forces driving this market is no longer optional—it is a prerequisite for competitive positioning, supply chain resilience, and long-term capital allocation.
This strategic overview introduces our latest comprehensive research on the Worldwide Industrial Diaphragm Pump Market, a publication designed to translate macroeconomic trajectories, competitive dynamics, and technology adoption patterns into actionable intelligence. Rather than offering static snapshots, the study maps the market from its 2020 baseline through a detailed forecast horizon extending to 2032, providing decision-makers with a forward-looking lens calibrated for real-world operational planning.
Market Trajectory & Structural Growth Drivers
The industrial diaphragm pump sector has demonstrated consistent expansion over the past half-decade, supported by sustained capital expenditure in water infrastructure, chemical processing, and pharmaceutical manufacturing. Historical data reveals a market that has steadily scaled from 2020 through 2025, culminating in a base-year valuation of USD 6,860.68 million in 2025. This momentum carries forward into the forecast period, with the market projected to reach USD 7,379.6 million in 2026 and continue its upward trajectory toward a 2032 valuation of USD 9,750.61 million.
At the heart of this growth lies a compound annual growth rate of 5.15 percent across the 2026 to 2032 forecast window. This moderate yet persistent expansion reflects a maturing industrial landscape where demand is increasingly driven by replacement cycles, regulatory compliance upgrades, and the gradual electrification of fluid handling systems. Rather than experiencing explosive, disruption-led spikes, the market is characterized by steady volume growth, incremental technological refinement, and a competitive environment that rewards operational efficiency and material innovation.
Several overarching dynamics are reinforcing this trajectory. Stricter environmental regulations governing wastewater discharge and effluent treatment continue to accelerate adoption of diaphragm pumps in industrial water and wastewater management, where seal-less designs and chemically resistant constructions offer distinct compliance advantages. Simultaneously, energy efficiency mandates and advancements in electrically operated diaphragm pumps are reshaping procurement criteria, with certain next-generation models delivering significant power reductions compared to traditional air-operated alternatives. These factors collectively position the diaphragm pump segment as a critical enabler of sustainable industrial fluid transfer.
Competitive Landscape: Consolidation, Innovation, and Regional Footprints
The competitive architecture of the worldwide industrial diaphragm pump market is defined by a blend of established multinational enterprises, specialized engineering firms, and increasingly capable regional manufacturers. Market concentration metrics indicate that the top three players command approximately 32.4 percent of total revenue, while the top five collectively account for 46.85 percent. This moderate concentration suggests a market that remains sufficiently fragmented to allow niche players and regional specialists to compete on customization, application expertise, and localized service networks, even as larger conglomerates leverage portfolio breadth and global distribution channels.
Leading participants span multiple geographies and operational philosophies. North American-headquartered firms such as Xylem Inc., Wanner Engineering Inc., Graco Inc., Dover Corporation (through its PSG division encompassing Wilden, Blackmer, and All-Flo), Ingersoll Rand's ARO division, IDEX Corporation (via Warren Rupp and Sandpiper), Flowserve Corporation, and Finish Thompson Inc. maintain strong positions across chemical transfer, industrial fluid handling, and sanitary applications. Their portfolios frequently emphasize air-operated double diaphragm designs, seal-less positive displacement architectures, and specialized material paths for corrosive or hazardous fluids.
European manufacturers contribute heavily to precision dosing, high-pressure metering, and compliance-driven applications. Grundfos A/S, Tapflo Group, Verder Group, KNF Neuberger GmbH, ProMinent GmbH, LEWA GmbH, and FLUX-GERÄTE GMBH are widely recognized for engineered solutions targeting water treatment, pharmaceutical processes, viscous liquid handling, and analytical or laboratory-grade fluid control. Meanwhile, Asian enterprises such as Yamada Corporation in Japan and GODO Manufacturing Co. Ltd. in China are expanding their footprints through cost-competitive electric models, environmental application focus, and integrated control features. Additional specialists like Albin Pump in Sweden and SAVINO BARBERA Srl in Italy further enrich the competitive matrix with compact designs and hazardous-chemical certifications.
Recent product launches underscore the pace of innovation. In March 2026, KNF Group introduced four advanced diaphragm pumps incorporating integrated sensor technology for flow, pressure, and vacuum control, extending their applicability across industrial, medical, and analytical use cases. The same month, Finish Thompson Inc. unveiled the FTI Air FT30P, a three-inch plastic air-operated double diaphragm pump engineered for high-flow chemical transfer. Earlier in 2025, GODO PUMPS showcased a new electric diaphragm pump with pressure relief controller at IE Expo, targeting environmental and high-flow scenarios, while ARO launched the EVO 210 electric diaphragm pump in September 2025 to improve efficiency and reliability in industrial settings. These releases illustrate a broader industry trend: manufacturers are embedding intelligence, enhancing material compatibility, and broadening electric offerings to meet evolving operational and sustainability expectations.
Segmentation Insights & Application-Side Demand Patterns
Understanding how demand distributes across operational types, end-user industries, and geographic regions is essential for targeted market entry, capacity planning, and product portfolio strategy. The market's revenue base reflects a clear preference for air-operated configurations, which continue to dominate industrial fluid handling due to their robustness, simplicity, and suitability for hazardous or abrasive environments. Electrically operated diaphragm pumps, while representing a smaller share of current revenue, are gaining traction as energy efficiency requirements intensify and facilities modernize legacy pneumatic infrastructure.
End-user demand is dispersed across multiple verticals, with water and wastewater management, chemicals and petrochemicals, food and beverage, oil and gas, pharmaceuticals, and a diversified remainder each contributing meaningfully to total consumption. This breadth indicates that diaphragm pumps are not confined to a single flagship application but rather serve as cross-industry workhorses where leak-free operation, chemical resistance, and precise metering are paramount. The multiplicity of end-use sectors also provides natural demand hedging: downturns in one vertical can be partially offset by sustained or growing requirements in another.
Geographically, the market's revenue distribution highlights the importance of regional industrialization rates, regulatory environments, and infrastructure investment cycles. Asia Pacific represents the largest regional revenue pool, followed by North America and Europe, with Latin America and the Middle East and Africa contributing smaller yet strategically significant volumes. These regional differentials matter because they shape localized competitive dynamics, service expectations, and the relative attractiveness of electric versus air-operated solutions. Decision-makers evaluating expansion, sourcing, or partnership opportunities must align their strategies with region-specific demand drivers rather than relying on global averages alone.
Material Supply, Regulatory Pressures, and Operational Implications
Market performance is inseparable from the underlying supply chain and regulatory environment. Raw material conditions have emerged as a critical variable for manufacturers and buyers alike. Since 2024, volatility in stainless steel, aluminum, and high-grade elastomer pricing has influenced manufacturing costs and average selling prices across the diaphragm pump segment. These fluctuations affect margin structures, lead times, and the economics of proprietary material formulations, making supplier diversification and forward contracting increasingly relevant for both producers and large-scale end users.
Material innovation continues to play a strategic role, particularly in chemically aggressive environments. PTFE remains a cornerstone material for chemical-resistant diaphragms, with global market volume reaching approximately 238.40 kilotons in 2026 and sustained demand from pump components in chemical processing. The availability, processing quality, and cost trajectory of such specialized materials directly affect product reliability, certification pathways, and the feasibility of sealing hazardous or corrosive fluids without compromising operational integrity.
Regulatory compliance is equally influential. Stricter environmental standards on wastewater discharge and effluent treatment are accelerating the deployment of diaphragm pumps in industrial water management, where sealless construction and compatible wet-end materials help facilities meet discharge limits and reduce maintenance interruptions. At the same time, compliance with explosion-proof design standards such as ATEX and adherence to ISO fugitive-emission limits are promoting the use of sealless diaphragm pumps built with advanced materials in hazardous industrial environments. These regulatory pressures do not merely constrain design choices; they actively redirect demand toward technologies that reduce leakage, improve containment, and simplify compliance documentation.
Sustainability objectives are further reshaping procurement logic. Energy efficiency mandates and demonstrable performance improvements in electric diaphragm pumps are encouraging facilities to reassess pneumatic dependencies. Certain electric models claim substantial energy reductions relative to traditional air-operated units, making them attractive in contexts where electricity costs, carbon targets, and total cost of ownership calculations intersect. For strategy teams, this trend signals a gradual but meaningful realignment in capital equipment specifications, with long-term implications for installed base composition and aftermarket service demand.
What the Full Study Delivers: A Practical Toolkit for 2026 Decision-Making
Our Worldwide Industrial Diaphragm Pump Market research is constructed to move beyond high-level commentary and equip teams with a structured, decision-ready analytical framework. The report integrates historical performance data, baseline valuations, and a multi-year forecast to clarify growth pacing, demand inflection points, and the relative contribution of different market segments. It maps revenue distribution across operational types, end-user industries, and regions, enabling readers to identify where volume is concentrated and where emerging opportunities may be underappreciated.
The study also provides a detailed competitive landscape assessment, examining the strategic positioning, product architectures, and market approaches of key participants. By contextualizing recent product launches, technology upgrades, and application-specific engineering focus, the report helps readers gauge how incumbents and challengers are shaping future supply dynamics. This competitive intelligence is paired with an analysis of market concentration, allowing stakeholders to evaluate competitive intensity, substitution risk, and the potential impact of consolidation or portfolio expansion.
Operational and supply-side factors are addressed with equal rigor. The research incorporates material market context, cost-structure considerations, and regulatory developments that influence product design, pricing, and adoption timelines. It further explores the interplay between energy efficiency expectations, electrification trends, and compliance requirements, offering a consolidated view of the forces that will determine which specifications win in procurement evaluations and which legacy configurations face gradual displacement.
Importantly, the study is designed to support scenario planning rather than prescribe a single path. Readers will find context for evaluating regional entry strategies, assessing supplier dependencies, benchmarking product roadmaps, and anticipating shifts in end-user preferences. By aligning quantitative forecasts with qualitative drivers, the report gives executives a coherent basis for investment prioritization, risk management, and cross-functional alignment between engineering, procurement, and commercial teams.
Worldwide Industrial Diaphragm Pump Market
Why This Research Matters Now
The 2026 decision environment demands more than retrospective reporting. Industrial buyers and suppliers alike are navigating material price variability, evolving compliance expectations, and a technology transition that favors smarter, more efficient fluid handling. In this context, a disciplined understanding of market size, growth pacing, segmentation structure, and competitive behavior becomes a strategic asset. It informs where to invest, which specifications to prioritize, how to structure supplier relationships, and when to anticipate shifts in regional demand intensity.
Diaphragm Valve Market
The Worldwide Industrial Diaphragm Pump Market study is built to serve as that strategic reference point. It combines a robust historical foundation with a forward-looking forecast through 2032, situates key industry players within a clear competitive framework, and ties market movements to the regulatory, material, and sustainability forces that are actively reshaping procurement and engineering decisions. For organizations seeking to reduce uncertainty and act with precision in 2026 and beyond, the full report provides the depth, structure, and operational relevance required to convert market intelligence into concrete business advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Diaphragm Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cell Controller Market Reaches $745.5M in 2025, Projected at 8.45% CAGR to 2032
By pmarketresearch, 2026-09-16
The Worldwide Cell Controller Market: Strategic Imperatives for the 2026–2032 Horizon
The global transition toward electrification, smart manufacturing, and advanced energy storage is fundamentally reshaping the architecture of power management systems. At the core of this transformation lies the cell controller—a critical component responsible for monitoring, balancing, and safeguarding individual battery cells within complex packs. As industries from automotive to aerospace demand higher energy density, longer cycle life, and uncompromising functional safety, the cell controller market has evolved from a niche engineering requirement into a standalone strategic growth vector. Our newly published Worldwide Cell Controller Market research delivers a comprehensive, data-rich panorama of this transition, offering enterprise leaders the clarity needed to navigate an increasingly complex competitive and regulatory landscape through 2032.
This analysis is not merely a retrospective ledger of growth figures. It is a forward-looking strategic instrument designed to inform capital allocation, product roadmap decisions, supply chain resilience planning, and partnership strategies. By synthesizing historical performance, macro-industry tailwinds, and emerging technology paradigms, the report provides a structured framework for executives who must act decisively in a market defined by rapid innovation cycles and stringent safety mandates.
Macro Trajectory and Growth Architecture
The cell controller market has demonstrated consistent upward momentum over the past half-decade, reflecting the broader acceleration of battery-dependent applications across multiple verticals. Historical revenue data from 2020 through 2025 reveals a structured expansion trajectory, with the market scaling from approximately 498 million USD in 2020 to an estimated 745.5 million USD by 2025. This historical baseline establishes a clear inflection point, setting the stage for a forecast period that projects continued, though progressively maturing, growth.
Our forward-looking projections for 2026 through 2032 indicate that the market will surpass the 849 million USD threshold in 2026 and continue its ascent toward an estimated 1.315 billion USD by the end of the forecast window. The compound annual growth rate across this period is calculated at 8.45 percent, a figure that reflects both sustained demand pull and the incremental penetration of advanced cell monitoring architectures in legacy and emerging applications alike. This growth rate is neither speculative nor overly conservative; it emerges from a careful reconciliation of deployment forecasts, supply-side capacity expansions, and the gradual standardization of high-channel-count controller topologies across diverse industrial and automotive platforms.
The revenue trajectory underscores a market that is moving beyond early-adopter saturation into broader industrial adoption. As battery pack architectures grow in complexity—incorporating higher series cell counts, tighter thermal tolerances, and integrated communication layers—the reliance on precision cell controllers becomes a structural requirement rather than an optional enhancement. This shift is visibly reflected in the steady year-over-year revenue increments observed throughout the forecast horizon, signaling that demand is being driven by both volume expansion and architectural upgrades in existing installations.
Structural Segmentation and Application Diversification
While the aggregate market figures provide directional clarity, the true strategic value of this research lies in its granular segmentation framework. The report dissects the market across multiple analytical dimensions, enabling executives to identify where growth is concentrating, which application verticals are driving incremental adoption, and how regional deployment patterns are evolving. The segmentation analysis reveals a market that is no longer monolithic; it is increasingly defined by divergent adoption curves, distinct regulatory pressures, and varying performance thresholds across sectors.
By examining regional distribution patterns, the report highlights how manufacturing footprints, localized supply chain strategies, and region-specific electrification mandates are shaping demand geography. Historical and projected revenue distributions across major geographic zones illustrate where infrastructure investment, automotive production scaling, and industrial battery deployment are converging to create sustained procurement cycles. These regional insights are critical for companies evaluating market entry strategies, localizing production capabilities, or optimizing logistics and distributor networks.
The application-side segmentation further clarifies where cell controller integration is becoming mission-critical. High-voltage battery management in mobility and energy storage, precision monitoring in semiconductor and electronics manufacturing, and safety-critical deployments in aerospace and defense represent distinct adoption profiles, each with 고유한 performance expectations and compliance burdens. Additional verticals, including food and beverage processing and specialized industrial use cases, contribute incremental but strategically meaningful demand, particularly where battery-backed control systems must meet stringent operational reliability standards. The report maps these application pathways in detail, enabling readers to assess where their existing product portfolios align with market needs and where adjacent opportunities may be underpenetrated.
A type-based breakdown distinguishes between hardware-centric controller solutions and the expanding domain of software and services that accompany modern battery management architectures. As cell controllers become more integrated into broader system-level diagnostics, remote monitoring, and predictive maintenance workflows, the service and software layer is increasingly contributing to total addressable value. This bifurcation is essential for suppliers deciding whether to compete purely on silicon performance or to build differentiated value through integrated firmware, calibration services, and system-level validation support.
Competitive Landscape and Strategic Positioning
The cell controller ecosystem is characterized by a relatively concentrated leadership tier, yet it remains open to innovation-driven differentiation. Market concentration indicators suggest that a limited number of established players command a substantial share of revenue, but the competitive environment is far from static. Continuous architectural improvements, functional safety certifications, and ecosystem partnerships are actively reshaping positioning. Our report provides a detailed competitive profiling framework that moves beyond headline market shares to examine how leading firms are structuring their technology roadmaps, securing supply chain advantages, and aligning with end-market compliance requirements.
NXP Semiconductors has maintained a prominent role in the cell controller space, offering a broad portfolio of battery cell controller ICs that span multiple safety and channel-count requirements. Its product families, including the MC3377x series and the BMA7318/BMA7518 18-channel architectures, reflect a deliberate strategy centered on high-voltage battery management systems for electric vehicles, energy storage systems, and 48V platform applications. These solutions emphasize daisy-chain communication, precision voltage and temperature monitoring, cell balancing, and rigorous functional safety integration. The recent introduction of the BMx7318/7518 family in mid-2025 further illustrates this trajectory, delivering per-channel dedicated ADCs, hardware alarm capabilities for overcurrent scenarios, and compliance aligned with ASIL-C and SIL-2 standards. This launch signals a continued commitment to supporting both automotive and industrial customers who require scalable, safety-certified monitoring hardware.
Texas Instruments continues to compete through its battery management system IC portfolio, with cell controller solutions such as the BQ79616 family supporting cell monitoring, balancing, and communication across automotive and industrial battery packs. TI’s approach emphasizes integration, manufacturability, and broad ecosystem compatibility, positioning its devices as foundational elements in pack-level architectures that require reliable communication and balanced charge-discharge performance.
Cell Fenders Market
Analog Devices contributes to the landscape through precision monitoring and controller ICs designed for high-voltage battery management applications. Its controller families focus on accurate voltage, temperature, and current measurement, supporting system designs that demand tight tolerance management and robust diagnostics. In markets where measurement fidelity directly influences pack longevity and safety margins, ADI’s positioning reflects a clear emphasis on performance-grade instrumentation integrated into controller architectures.
Beyond silicon suppliers, the competitive ecosystem also includes tooling and validation providers such as dSPACE, which offers Cell Controller Virtualization solutions for testing and simulation of battery management systems. By supporting controller validation across multiple hardware providers, dSPACE illustrates how the market is expanding beyond component manufacturing into system-level test infrastructure. This development is significant for enterprises seeking to reduce validation cycles, de-risk functional safety certification, and accelerate time-to-market for complex battery pack designs.
The report’s competitive analysis extends beyond company profiles to examine how these players interact with regulatory frameworks, standard-setting bodies, and downstream system integrators. Understanding these relationships is essential for executives evaluating partnership opportunities, assessing supplier risk, or planning acquisitions and technology licensing strategies.
Regulatory and Technical Dynamics Shaping Adoption
Market growth in cell controllers cannot be analyzed in isolation from the regulatory and technical standards that govern battery system design. Functional safety requirements have become a defining architectural constraint, particularly in automotive applications where battery management systems must align with ISO 26262 expectations. Many contemporary cell controller devices are engineered to support ASIL-C or ASIL-D compliance, incorporating built-in diagnostics, fault detection mechanisms, and fail-safe communication pathways. This safety-centric design philosophy is no longer optional for high-voltage applications; it is a baseline procurement requirement that directly influences component selection and system architecture decisions.
Parallel standards such as ISO 12405-3 and ISO 12405-4 further codify performance and safety expectations for electrically propelled road vehicles, explicitly referencing cell electronics and controller functions for monitoring and balancing. As these standards continue to shape engineering practices and certification processes, suppliers that can demonstrate measurable alignment with established protocols gain a meaningful advantage in qualifying for Tier-1 and OEM procurement pipelines. The research examines how these regulatory touchpoints are influencing product development cycles, validation methodologies, and market entry timing across different application segments.
In addition to safety standards, communication architecture has emerged as a critical technical differentiator. Modern battery management systems increasingly rely on isolated daisy-chain communication protocols and transformer-based physical layers to maintain signal integrity across large cell strings. This design approach supports reliable operation in high-noise electrical environments and enables scalable pack configurations that may incorporate hundreds of cells per series. The report evaluates how communication topology choices affect system cost, thermal design, fault isolation, and overall pack reliability, providing context for engineering leaders evaluating next-generation controller deployments.
Operational Content and Decision-Executing Frameworks
A market intelligence report is only as valuable as the operational clarity it provides. Accordingly, this research is structured to translate macro trends into actionable decision support. The publication includes detailed historical and forecast data tables, allowing readers to model revenue scenarios, track growth velocity, and benchmark internal performance against market trajectories. Segmentation breakdowns are presented across region, type, and application dimensions, enabling targeted analysis for product managers, regional sales directors, and strategic planning teams.
The report also provides competitive profiling, recent development tracking, and regulatory mapping, ensuring that readers can connect technical evolution with commercial implications. Recent product launches, functional safety certification milestones, and system-level validation innovations are contextualized within broader adoption patterns, helping executives anticipate where supplier capabilities are heading and how procurement requirements may shift. Strategic frameworks are embedded throughout the analysis to support use cases such as market entry assessment, portfolio gap analysis, supply chain localization planning, and partnership identification.
By combining quantitative market architecture with qualitative competitive and regulatory context, the publication is designed to serve as a reference point for cross-functional decision-making. Engineering leadership can use the segmentation and standard-compliance sections to guide architecture choices; commercial teams can leverage regional and application breakdowns to prioritize go-to-market resource allocation; and executive leadership can rely on the forecast trajectory and concentration analysis to inform long-term investment thesis development.
Why This Research Matters for 2026 Decision-Making
The 2026–2032 period will be defined by the maturation of battery system architectures, the tightening of safety and performance expectations, and the continued expansion of cell controller adoption beyond early-adopter verticals. Enterprises that enter this window with fragmented market intelligence risk misallocating R&D focus, underestimating compliance-driven procurement shifts, or overlooking regional demand concentrations that could shape revenue timing. This research was developed to close that intelligence gap.
Worldwide Cell Controller Market
The strategic value of the report lies in its ability to connect high-level growth data with the operational realities of product planning, supplier evaluation, and market prioritization. It does not simply report that the market is expanding; it explains where that expansion is concentrating, which technical and regulatory forces are accelerating adoption, and how the competitive field is evolving in response. For organizations operating in automotive electrification, energy storage integration, industrial battery deployment, or precision electronics manufacturing, the insights contained here are directly applicable to roadmap alignment and risk mitigation.
The complete dataset, segmentation detail, competitive profiles, and scenario-ready forecasting tables are available in the full Worldwide Cell Controller Market research publication. We invite executives, strategy teams, and industry analysts to access the complete report for the comprehensive intelligence required to make confident, evidence-based decisions in the 2026 planning cycle and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Cell Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Alternate Light Sources Market to Hit $694.05M by 2032 with 5.72% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence in the Worldwide Alternate Light Sources Market: A 2026 Decision Framework
The global landscape for Alternate Light Sources (ALS) is undergoing a period of structural refinement, driven by sustained demand across forensic, medical, and industrial applications. As enterprises navigate an environment defined by technological maturation and regulatory standardization, the necessity for precise, forward-looking market intelligence has never been more critical. PW Consulting's latest Worldwide Alternate Light Sources Market research study offers a comprehensive strategic lens designed specifically to inform high-stakes corporate decisions throughout 2026 and beyond.
This analysis serves as a foundational brief for executive teams, product strategists, and investment committees seeking to align their portfolios with the evolving dynamics of the ALS sector. By synthesizing historical performance data, forward-looking projections, and granular competitive profiling, the report eliminates the ambiguity that often plagues strategic planning in specialized lighting and photonics markets.
Macro-Market Trajectory and Growth Dynamics
Understanding the baseline momentum of the alternate light sources industry is the first step in any robust strategic assessment. Our research tracks the market's revenue evolution from the base year of 2025 backward through 2020, while simultaneously projecting performance through the forecast horizon of 2032. The data reveals a consistent expansion trajectory that reflects both steady historical adoption and anticipated future acceleration.
Between 2020 and 2025, the worldwide ALS market demonstrated resilient growth, climbing from an aggregate revenue baseline of approximately USD 365 million to a 2025 valuation of nearly USD 471 million. This historical progression underscores the technology's transition from specialized niche equipment to broader operational staples within law enforcement agencies, clinical diagnostic facilities, and quality assurance laboratories. The market's momentum carries forward into the forecast period, with 2026 expected to mark a significant inflection point as the aggregate valuation surpasses the USD 507 million threshold.
Looking across the full forecast window extending to 2032, the compound annual growth rate (CAGR) is calculated at 5.72 percent. This sustained growth profile suggests that market expansion will be characterized by methodical, dependable increases in procurement spend rather than volatile spikes. By the end of the decade, revenue projections indicate that the market will approach an annual valuation exceeding USD 600 million, with continued upward pressure through the early 2030s as next-generation portable systems and laboratory-grade multi-spectral platforms gain deeper integration into standard operating procedures worldwide.
Demand Drivers Shaping the 2026 Horizon
Several converging factors are positioning the ALS sector for continued relevance and procurement growth during 2026. The interplay between regulatory standardization, operational efficiency requirements, and technological miniaturization is reshaping how end-users evaluate and deploy alternate light solutions.
- Regulatory and Standardization Tailwinds: Industry definitions and equipment classifications are becoming increasingly formalized. For instance, authoritative bodies now formally recognize alternate light sources as specialized equipment designed to produce light at precise wavelengths to enhance or visualize potential evidentiary items. Simultaneously, portable forensic light kits—which must integrate an alternate light source, a barrier filter, a dedicated power source, and a carrying case—have been codified within recognized authorized equipment listings for law enforcement crime scene operations. These standardization efforts reduce procurement ambiguity and create clearer pathways for vendor qualification.
- Operational Protocol Evolution: Professional guidelines are increasingly specifying how ALS technologies should be deployed in low-light documentation scenarios. Established protocols now emphasize controlled photographic conditions, including tripod mounting, manual or aperture-priority exposure modes, and strict adherence to wavelength-specific eye protection requirements. These standards elevate the importance of purchasing certified, guideline-compliant equipment rather than ad-hoc lighting solutions, thereby strengthening the addressable market for professional-grade ALS providers.
- Safety and Compliance Emphasis: As shortwave UV configurations remain widely utilized for evidence detection and specialized inspection tasks, manufacturers and procurement officers alike are placing greater weight on integrated safety features. Vendor documentation increasingly highlights mandatory eye and skin protection protocols, reinforcing the market's shift toward systems that bundle protective accessories and operator training materials alongside core illumination hardware.
Report Scope and Operational Content Architecture
The Worldwide Alternate Light Sources Market research deliverable is structured to provide actionable intelligence rather than abstract market commentary. PW Consulting's analytical framework ensures that every section of the report translates directly into executable strategy for product development, regional expansion, pricing optimization, and competitive positioning.
At its core, the study delivers a multi-dimensional segmentation analysis that dissects the market across critical operational axes. Readers will find dedicated evaluations of the primary technology categories that define the ALS product universe, including an in-depth examination of LED-based illumination platforms, which currently represent the dominant share of deployed systems, alongside detailed profiles of Xenon and Laser light source segments. Each technology category is assessed for its distinct adoption curves, price band positioning, and suitability for specific end-use environments ranging from field-deployed crime scene units to controlled laboratory screening workflows.
The application-driven segmentation module provides equal granularity, mapping market activity across the principal domains where alternate light technologies generate measurable value. Forensic investigation remains the most substantial demand pillar, with specialized ALS kits and multi-wavelength laboratory screening systems forming an integral component of modern evidence processing pipelines. Medical diagnostics represents a secondary but growing application vector, where wavelength-specific illumination supports diagnostic visualization and procedural guidance. Industrial inspection rounds out the core application landscape, encompassing quality assurance, defect detection, and material analysis workflows that rely on precise spectral output to identify anomalies invisible under standard lighting conditions.
Geographic coverage within the report is comprehensive, capturing revenue distribution and growth characteristics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Rather than presenting raw figure tables in isolation, the regional analysis contextualizes each market's procurement environment, regulatory maturity, agency budget cycles, and technology adoption timelines. This approach enables readers to identify not only which regions represent the largest current revenue pools, but also which territories exhibit the strongest forward indicators for incremental market entry or distribution partnership development.
Competitive Landscape and Strategic Positioning
The ALS market features a diverse ecosystem of specialized manufacturers and distributors, each competing across different price tiers, feature sets, and end-user segments. Our competitive analysis module evaluates the strategic posture of key market participants, mapping their product portfolios, innovation trajectories, and recent commercial activities to provide a clear picture of where competitive intensity is concentrated and where whitespace opportunities may exist.
Leading Participant Profiles
Several established firms anchor the competitive structure of the worldwide ALS market, with leadership positions often correlated to deep domain specialization, regional distribution strength, and the ability to deliver certified, guideline-compliant equipment.
- Foster + Freeman: Headquartered in the United Kingdom, this organization has built a reputation as a pioneer in high-intensity LED forensic illumination, anchored by its widely deployed Crime-lite product family. The portfolio spans handheld crime scene series, multi-wavelength laboratory configurations, and advanced multi-spectral and laser-enabled screening platforms. Recent commercial activity has highlighted next-generation evidence screening tools designed for forensic laboratory environments, reinforcing a strategic emphasis on laboratory-grade throughput and multi-wavelength integration.
- Labino AB: Based in Vallentuna, Sweden, this manufacturer focuses on waterproof LED alternate light source kits engineered specifically for crime scene investigation workflows. Product design emphasizes operational simplicity, with straightforward on/off functionality and robust field-ready engineering. Recent catalog updates have expanded specification transparency for core ALS kits, reflecting a broader industry trend toward clearer technical documentation and streamlined procurement evaluation.
- Sirchie: Operating from the United States, this supplier provides a range of forensic alternate light solutions tailored for law enforcement evidence detection. Its product lines include high-output three-watt illumination systems, tactical field kits, and shortwave UV configurations optimized for crime scene processing. The emphasis on law enforcement readiness and tactical deployment architecture positions this participant strongly within public-sector procurement channels.
- HORIBA Scientific (SPEX Forensics): This United States-based entity offers compact handheld and laboratory-focused LED alternate light platforms designed for visualizing latent prints, body fluids, and other forensic evidence markers. The brand's positioning centers on precision visualization tools that bridge field collection and laboratory confirmation workflows.
- FoxFury: Also headquartered in the United States, this supplier specializes in rugged, cordless forensic lighting and alternate light source configurations intended for field investigators. Product families include portable series designed for cordless operation, emphasizing durability, rapid deployment, and flexible wavelength options across multiple kit configurations.
- Lynn Peavey Company: A United States-based distributor and supplier, this organization provisions portable ALS units alongside complementary forensic processing materials. Its distribution-centric model enables broad catalog reach across evidence processing workflows, making it a significant channel presence within the North American supply ecosystem.
- UltraLite ALS: Operating as a specialized provider of portable forensic alternate light sources, this participant focuses on compact, wavelength-configurable kits intended for direct crime scene deployment. The product emphasis aligns with the broader market shift toward lightweight, field-portable systems that maintain professional-grade spectral output in a streamlined form factor.
Concentration Dynamics and Portfolio Strategy Implications
The competitive structure of the worldwide ALS market exhibits meaningful concentration at the top tier, with the largest players collectively commanding a substantial share of aggregate revenue. This concentration pattern reflects the importance of brand certification, regulatory familiarity, and established distribution relationships in public-sector and institutional procurement environments. Simultaneously, the market maintains a broad product diversity across more than a dozen manufacturers and upwards of fifty distinct configurations, with price points spanning a wide range from entry-level field kits to high-specification laboratory systems. This bifurcated structure creates a strategic landscape where premium differentiation, compliance documentation, and total-cost-of-ownership positioning often matter more than unit-price competition alone.
Worldwide Alternate Light Sources Market
Regulatory Context and Standardization as a Market Accelerator
One of the most important yet underappreciated drivers in the ALS sector is the accelerating pace of regulatory definition and equipment standardization. As forensic and public-safety agencies seek to formalize equipment procurement criteria, clear technical standards increasingly function as market accelerants rather than purely compliance burdens.
Shadowless Lamps Market
Authoritative glossary definitions now explicitly frame alternate light sources as equipment engineered to produce light at specific wavelengths for the enhancement and visualization of potential evidence. This definitional clarity helps procurement officers narrow their evaluation criteria and reduces the risk of acquiring non-compliant or under-specified illumination tools. In parallel, recognized authorized equipment frameworks now list portable forensic light kits—comprising at least one alternate light source, a barrier filter, a dedicated power source, and a carrying case—as qualified equipment categories for law enforcement crime scene operations.
These standardization developments carry direct strategic implications. For manufacturers, they create clearer specifications around what constitutes a qualified kit, potentially raising the barrier to entry for non-integrated or non-certified alternatives. For procurement leaders, they streamline the justification process for capital expenditure by linking equipment purchases to documented operational standards. For channel partners and distributors, they reinforce the value of carrying portfolios that explicitly reference these compliance frameworks in sales collateral and technical documentation.
Furthermore, professional guidelines governing low-light crime scene photography now specify operational requirements that emphasize controlled imaging conditions, tripod stability, manual or aperture-priority exposure modes, and wavelength-appropriate operator protection. Equipment vendors that design their systems with these documentation and safety protocols in mind are better positioned to meet institutional purchasing requirements and to reduce the friction associated with evidence admissibility and chain-of-custody considerations.
360-Degree Market Intelligence for 2026 Strategic Planning
Effective market strategy in 2026 requires more than a simple revenue forecast. It demands an integrated understanding of how technology readiness, regulatory evolution, competitive maneuvering, and application-specific procurement cycles interact to shape demand. PW Consulting's Worldwide Alternate Light Sources Market report is constructed to deliver that integrated view.
Readers will obtain a structured basis for evaluating product roadmap priorities, identifying which technology segments are most likely to capture incremental budget allocation, and determining whether regional expansion efforts should prioritize high-revenue incumbency or higher-growth developmental markets. The report also supports pricing strategy calibration by illuminating how different product tiers—from compact handheld units to sophisticated multi-wavelength laboratory platforms—are positioned across the broader ecosystem.
For investors and corporate development teams, the concentration analysis and participant profiling provide a practical framework for assessing acquisition targets, distribution partnership opportunities, and whitespace entry points. The combination of historical revenue validation, forecast-period trajectory modeling, and competitive activity tracking ensures that strategic decisions are grounded in observable market behavior rather than speculative sentiment.
Conclusion: Converting Market Intelligence into 2026 Advantage
The worldwide alternate light sources market stands at a point where steady structural growth intersects with meaningful technological and regulatory evolution. For organizations operating in, adjacent to, or seeking entry into this sector, the difference between reactive positioning and proactive advantage lies in the quality of market intelligence available at the planning table.
PW Consulting's comprehensive study equips decision-makers with the analytical depth required to navigate this landscape confidently. By linking macro-level revenue trajectories, segmented demand patterns, regulatory standardization momentum, and competitive portfolio dynamics into a single strategic framework, the report enables enterprises to align their 2026 initiatives with demonstrable market realities. The full dataset, detailed segmentation breakdowns, complete competitor evaluations, and forward forecast tables are available through the complete research release. For teams ready to move beyond surface-level industry overviews and into execution-ready intelligence, the full report provides the definitive reference point for the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Alternate Light Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Condensation Silicone Rubber Market Hits $2.25 Billion in 2025, Projects 4.82% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Horizons for the Global Condensation Cure Silicone Rubber Market: Navigating the 2026 to 2032 Era
The industrial materials landscape is entering a pivotal consolidation phase, and nowhere is this more evident than in the condensation cure silicone rubber (CCSR) sector. Our latest Worldwide Condensation Cure Silicone Rubber Market research report delivers the definitive intelligence framework required to navigate the forecast period from 2026 through 2032. For procurement directors, R&D strategists, and market expansion leaders, this study transforms macroeconomic signals into executable roadmaps, enabling precise capacity positioning, pricing architecture design, and competitive maneuvering in a market defined by steady structural growth and evolving technological trade-offs.
The condensation cure segment occupies a distinct competitive position within the broader elastomers ecosystem. Its room-temperature vulcanizing (RTV) characteristics, cost-effective tin-catalyzed chemistry, and proven compatibility with casting, molding, and sealant workflows continue to drive sustained demand across advanced manufacturing, construction, and specialized industrial applications. Understanding where this value chain is heading requires more than headline figures; it demands a rigorous dissection of historical trajectory, forward-looking velocity, regional polarization, product architecture shifts, and the dynamic pressures of raw material economics and regulatory evolution.
The Macro Trajectory: From Consolidation to Accelerated Expansion
Historical data reveals a market that has successfully weathered cyclical volatility to establish a robust baseline. Between the early baseline years and 2025, global revenue demonstrated clear upward momentum, reflecting sustained downstream adoption and manufacturing efficiency gains. The current market year has already settled into a trajectory that positions the sector for predictable expansion. Looking ahead, our forecast modeling outlines continued growth through 2032, supported by compounding demand from high-durability sealing solutions, precision mold making, and industrial maintenance workflows.
- The market has evolved from post-pandemic recalibration to a phase of measured, high-confidence scaling.
- Forecast modeling captures a compound annual growth rate that underscores steady structural expansion rather than speculative hype.
- Revenue progression across the decade points toward sustained valuation appreciation, creating clear windows for market share capture and premiumization strategies.
Absolute Scale and Growth Velocity: The Numbers That Redefine Opportunity
The financial architecture of this market provides a compelling foundation for long-term investment and commercial planning. At its historical baseline, the sector commanded a substantial global valuation measured in billions of dollars, confirming its entrenched role across multiple industrial verticals. By the current market year, revenue figures reflected both recovery resilience and expanded application penetration, setting a higher floor for the forecast horizon.
Silicone Resin Market
As we project forward, the market is positioned to traverse a multi-year expansion corridor, reaching a significantly elevated valuation by the end of the forecast window. The compound annual growth rate of the period translates into a powerful compounding effect, where territorial diversification, product line extensions, and application migration can amplify realized returns far beyond aggregate market growth. For strategic planners, this backdrop validates disciplined capacity allocation, targeted geographic entry, and formulation innovation as core value-creation levers.
Regional Polarization: Where Demand Converges and Where It Diversifies
Geographic demand distribution reveals a market that is simultaneously concentrated and diversifying. Asia Pacific commands the largest share of global revenue, driven by dense manufacturing ecosystems, expansive construction activity, and rapidly scaling production of molding and casting applications. North America and Europe maintain strong secondary positions, characterized by higher value-add specialization, stringent performance requirements in electronics and automotive-adjacent workflows, and mature maintenance-repair-overhaul (MRO) channels. Meanwhile, Latin America and the Middle East and Africa represent emerging expansion vectors, where infrastructure development and localized industrial supply chains are progressively unlocking new consumption nodes.
This geographic architecture carries a crucial strategic implication: competitive advantage no longer belongs solely to the largest aggregate player. It belongs to organizations that understand regional pricing elasticity, regulatory nuance, supply chain proximity, and application-specific formulation preferences. The report maps these regional demand signatures in detail, equipping stakeholders with the context required to align distribution footprints, formulation localization, and channel partnerships with the territories that offer the highest marginal returns.
Product Architecture and Application Migration: The Battlefield of Differentiation
The condensation cure market is structurally divided between one-component and two-component RTV systems, each serving distinct performance and processing philosophies. One-component formats continue to dominate in ease-of-use workflows, rapid deployment scenarios, and applications where operational simplicity outweighs the need for advanced formulation tuning. Two-component systems, by contrast, offer enhanced control over cure kinetics, depth-of-cure performance, and mechanical property optimization, making them the preferred architecture for precision tooling, demanding casting processes, and environments where cure inhibition sensitivity must be managed.
On the application side, demand concentration is both revealing and instructive. Mold making and tooling remains a central pillar, reflecting the enduring need for high-tear-strength, dimensionally stable elastomeric matrices in casting workflows ranging from wax and gypsum to urethane, epoxy, and polyester resins. Construction sealants form another major demand block, driven by durability requirements in architectural and infrastructure contexts. Electronics and electrical potting represent a high-growth specialization, where encapsulation reliability and thermal-responsiveness considerations continue to attract material innovation. Automotive components and general industrial maintenance round out the application footprint, providing steady-replacement demand streams that stabilize revenue during cyclical fluctuations.
The strategic question for formulators and distributors is not simply which segment is larger, but which segment offers the steepest trajectory for margin expansion, technical differentiation, and barrier creation. The report isolates these migration patterns and maps the competitive inflection points where formulation leadership can be converted into durable commercial advantage.
The Competitive Field: Who Is Defining the Next Standard of Performance
The competitive environment is defined by a blend of specialized formulators, regional manufacturing strength, and multinational technology presence. The market exhibits a moderately concentrated structure, with the top three players commanding a significant combined share and the top five extending that influence further. This concentration creates both a challenge and an opening: incumbents maintain formidable distribution, technical support, and formulation ranges, but the remaining share is large enough to reward focused differentiation, especially in application-specific customization, cure-time modulation, and localized service models.
Several companies illustrate the archetypes shaping market behavior. Smooth-On, Inc. has built a deep reputation around tin-cure mold rubbers, with product families engineered for varied hardness requirements and broad compatibility with casting materials. Polytek Development Corp. emphasizes flexible mold making with formulations noted for high tear strength and favorable release characteristics, alongside lower sensitivity to cure inhibition relative to addition-cure alternatives. Silicones, Inc. has maintained a long-standing focus on condensation cure RTV-2 silicones, offering both standard and custom formulations across mold-making, electronics potting, and special effects use cases.
CHT Group contributes a European formulation perspective, supplying condensation cure silicones for moulding applications compatible with a wide spectrum of casting substrates, plus catalysts and thixotroping agents for property modification and custom development. BBN Materials Co., Limited reflects the expanding capabilities within China's specialty silicone ecosystem, concentrating on tin-cured mold making for crafts, candles, soaps, resin, GFRC, and concrete products, with customizable operation and curing times. Silpak, Inc. continues to produce two-component condensation-cure RTV systems that deliver high-strength room-temperature curing for mold making and allied applications.
Worldwide Condensation Cure Silicone Rubber Market
On the global technology side, Elkem Silicones offers polycondensation tin-kit condensation cure silicones suitable for architectural molding, including plaster, gypsum, and concrete applications. Shin-Etsu Chemical Co., Ltd. extends its broad silicone portfolio with two-component condensation cure RTV rubbers, including rapid cure types and high-thermal-stability one-component grades. Momentive Performance Materials rounds out the competitive field with condensation cure RTV silicones tailored for mold making rubber applications, supported by catalyst systems that influence cure behavior and processing consistency.
These firms collectively demonstrate that performance leadership is increasingly defined by application engineering, cure robustness, and the ability to customize formulation parameters to user workflows. The report translates these competitive dynamics into actionable intelligence, mapping strategic positioning, capability overlaps, and whitespace opportunities for entrants and incumbents alike.
Raw Material Economics and Regulatory Flux: The Hidden Cost Structures
Market growth does not occur in a vacuum. Recent industry context signals point to tightening cost structures and regulatory complexity that are reshaping upstream economics and downstream margin expectations. Industrial-grade silicone oil prices in China have shown a moderate upward trend, with high-viscosity and modified grades commanding premium levels, driven by rising feedstock costs. D4 price movements have contributed meaningfully to higher production costs for silicone-based materials, including condensation cure systems. This input pressure interacts with broader cost dynamics in catalyst supply, packaging, and logistics, placing renewed emphasis on formulation efficiency and value engineering.
Simultaneously, stricter environmental policies have impacted silicone production costs and supply conditions in key manufacturing regions. For buyers and producers, this means resilience planning is no longer optional. Dual-sourcing strategies, regional inventory buffering, and formulation adaptability are becoming essential components of cost-containment roadmaps. Companies that can maintain performance consistency while navigating input volatility will capture disproportionate share in markets where competitors face throughput constraints or margin compression.
What the Report Delivers: The Operational Intelligence You Need
This study is designed as an execution-focused intelligence package rather than a static market snapshot. It provides a full historical-to-forecast value chain view, segmentation architecture across regions and product types, application-level demand mapping, and competitive profiling that connects corporate capabilities with market behavior. Procurement teams will gain clarity on volume trajectory, pricing pressure indicators, and regional sourcing considerations. R&D and formulation leaders will receive the structural context needed to prioritize cure optimization, inhibition management, and application-specific property tuning. Commercial and strategy teams will obtain the geographic and segment insights required to evaluate market entry, channel expansion, and customer-facing value propositions.
From Insight to Advantage: Why 2026 Decisions Depend on This Research
The condensation cure silicone rubber market is entering a phase where steady aggregate expansion will be matched by sharper competitive differentiation, regional complexity, and input-driven cost sensitivity. Organizations that act on incomplete intelligence risk misallocating capacity, undervaluing application-specific niches, or underestimating the strategic impact of raw material and regulatory shifts. Our Worldwide Condensation Cure Silicone Rubber Market report closes that intelligence gap by converting macro trends into precise operational guidance.
For decision-makers preparing for the 2026 planning cycle, this research offers the evidence base needed to align investment timing, commercial positioning, formulation strategy, and regional execution with the market's most probable trajectory. The full analysis, including granular segmentation, competitive benchmarking, and forward-looking scenario framing, is available through our complete report. Access the detailed intelligence now and position your organization to convert market momentum into durable strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Condensation Cure Silicone Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Military Off-Road Vehicle Market to Hit $26.17B by 2032 at 5.12% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Military Off-Road Vehicles Market: A 2026 Outlook
Navigating Terrain and Tactics in an Evolving Defense Landscape
The worldwide military off-road vehicles market stands at a critical juncture where operational necessity intersects with technological transformation. As defense organizations recalibrate their ground mobility strategies, the demand for vehicles capable of traversing complex terrains while maintaining tactical superiority has become increasingly pronounced. Our latest market research provides a comprehensive examination of this sector, offering decision-makers a clear view of the forces shaping procurement, production, and deployment patterns through the end of the decade.
Between 2020 and 2025, the global market expanded from approximately USD 14,500 million to USD 18,450 million, reflecting sustained investment in ground mobility capabilities and a consistent upward trajectory. Looking ahead, the forecast period from 2026 to 2032 projects continued growth, with the market expected to reach USD 26,169 million by the close of the forecast window. This expansion is supported by a compound annual growth rate of 5.12 percent, signaling a resilient demand environment even as defense budgets face periodic scrutiny and procurement cycles grow more complex.
Off-road Engines Market
For executives and strategists operating in this space, the numbers alone do not tell the full story. The underlying dynamics—technological integration, supply chain constraints, regulatory distinctions, and shifting operational requirements—are what ultimately determine competitive positioning and commercial success. This research is designed to translate macro-level momentum into actionable intelligence, enabling organizations to anticipate disruptions, identify partnership opportunities, and align product development with emerging military needs.
Market Structure and Segment Intelligence
A thorough understanding of how military off-road vehicles are categorized and deployed across different mission profiles is essential for strategic planning. The market encompasses a diverse range of vehicle types, each serving distinct operational functions and procurement priorities. Light tactical vehicles continue to hold significant relevance, driven by their versatility in rapid deployment scenarios and their adaptability to both combat and support roles. Medium and heavy tactical platforms remain integral to logistics, troop transportation, and combat support operations, particularly in theaters where payload capacity and survivability are prioritized alongside mobility.
Unmanned ground vehicles represent a growing dimension of the market, reflecting broader defense modernization efforts. The integration of autonomous navigation, sensor suites, and remote operation capabilities is reshaping how military organizations approach reconnaissance, breaching, and high-risk terrain traversal. These platforms are no longer conceptual prototypes; they are advancing through rigorous testing and integration programs that underscore a strategic shift toward reducing personnel exposure in contested environments.
Application-wise, the market is anchored by core mission requirements including troop transportation, combat operations, logistics and supply, and medical and command post support. Each of these application areas imposes different engineering, performance, and logistical demands, and procurement decisions increasingly reflect a balance between immediate operational needs and long-term capability development. The research provides granular segmentation analysis that examines how these categories interact with regional procurement patterns, production capacity, and evolving mission profiles, without relying on oversimplified assumptions about uniform demand across theaters.
Competitive Landscape and Organizational Positioning
The competitive environment in the military off-road vehicles market is characterized by a mix of established defense manufacturers, specialized tactical vehicle producers, and organizations increasingly focused on hybridization, modularity, and next-generation mobility solutions. Market concentration data indicates that a relatively small group of leading firms commands a substantial share of total revenue, with the top three companies accounting for approximately 42.15 percent and the top five reaching 58.4 percent. This concentration underscores the importance of scale, program continuity, and long-term procurement relationships, while also leaving room for specialized entrants that can differentiate through technology, platform flexibility, or regional partnerships.
Oshkosh Defense remains a prominent force in the tactical wheeled vehicle segment, with its portfolio including platforms designed for high off-road mobility, protection, and payload performance. Its continued emphasis on combat-proven systems and independent suspension technology reinforces its relevance in programs where terrain adaptability and survivability are paramount. AM General, widely recognized for its light tactical vehicle heritage, continues to support global armed forces with high-mobility platforms and enhanced tactical kits, maintaining a strong footprint in both legacy and next-generation vehicle families.
General Dynamics Land Systems brings a focused approach to wheeled armored vehicles and tactical platforms, emphasizing mobility, survivability, and system integration. Its development work, including hybrid-electric demonstrators, reflects a broader industry interest in power architecture innovation and mission flexibility. BAE Systems contributes armored and tactical wheeled vehicles with off-road capability, supporting a diverse set of global customers with platforms adapted for combat and support missions. Rheinmetall AG has expanded its presence through modular wheeled armored vehicle offerings that prioritize protection, mobility, and variant flexibility for troop transport and support roles.
Additional participants such as Navistar Defense, GM Defense, Iveco Defence Vehicles, Mack Defense, Arquus, Tata Motors, and Hanwha Defense each bring distinct strengths to the market. Some emphasize logistical truck platforms engineered for rigorous off-road military conditions, while others focus on light tactical and hybrid-electric solutions or armed forces mobility programs tailored to regional requirements. The presence of both multinational primes and regional specialists creates a layered competitive environment where procurement decisions often weigh proven performance, industrial base considerations, and technology roadmaps in combination rather than in isolation.
Recent Developments Shaping the Operational Agenda
Recent activity across the defense mobility sector illustrates how rapidly the strategic conversation is evolving. In late 2025, Oshkosh Defense showcased its combat-proven light tactical vehicle at the International Armoured Vehicles Conference, reinforcing the continued relevance of platforms that combine off-road mobility with protection and reliability in operational settings. Around the same time, GM Defense demonstrated its light vehicle lineup in the United Kingdom for the first time, signaling accelerated delivery planning and a broader push to position next-generation mobility solutions within international procurement considerations.
One of the most significant developments in the broader ecosystem has been the advancing role of autonomy in ground operations. DARPA's final tests of RACER autonomous platforms in early 2026 demonstrated complex terrain navigation in support of Army combat breaching operations, highlighting the operational value of autonomous mobility in high-consequence environments. In parallel, the U.S. Army selected Overland AI, Forterra, and Scout AI to integrate autonomous mobility into Infantry Squad Vehicles for off-road operations, with prototypes expected by May 2026. These initiatives point toward a future in which unmanned and semi-autonomous capabilities are not separate from the core vehicle market, but increasingly embedded within it.
Worldwide Military Off-road Vehicles Market
These developments matter because they illustrate how procurement priorities are shifting from purely mechanical performance to integrated mission systems, software-enabled mobility, and platform adaptability. Organizations that can align vehicle design, autonomy integration, and sustainment strategies with these emerging requirements will be better positioned to participate in next-generation programs.
Regulatory and Supply Chain Dynamics as Strategic Variables
Market performance in the military off-road vehicles sector is influenced not only by operational demand but also by regulatory frameworks and industrial supply conditions. A notable feature of this market is the regulatory environment surrounding military tactical vehicles, which distinguishes them from civilian on-road and off-road standards. U.S. Armed Forces tactical military off-road trucks are exempt from standard EPA on-road and off-road exhaust emissions regulations, allowing continued use of higher-sulfur JP-8 fuel and older engine configurations without aftertreatment devices. Similarly, military tactical vehicles are not subject to the same stringent civilian emissions standards, enabling optimized mobility and performance in off-road conditions. These distinctions matter because they preserve design flexibility for military platforms while also shaping fuel logistics, maintenance approaches, and engineering trade-offs.
On the industrial side, supply-chain fragility remains a defining challenge. The availability of armor steel and power electronics has affected production timelines and costs, introducing uncertainty into program planning and budgeting. Steel price volatility has had a measurable impact on armor production costs, with industry data indicating a significant increase in costs between 2022 and 2023 for military land vehicles. Such pressures can influence not only vehicle pricing but also lead times, configuration decisions, and the feasibility of certain platform upgrades.
For market participants, these dynamics are not peripheral concerns; they are central to risk management and program execution. The research examines how regulatory exemptions, material constraints, and production economics interact with procurement behavior, helping organizations anticipate where bottlenecks may emerge and where adaptation strategies can create competitive advantage. Understanding these variables is especially important as manufacturers balance performance requirements with cost discipline and delivery reliability.
Why This Research Matters for 2026 Decision-Making
The 2026 outlook for the worldwide military off-road vehicles market presents a landscape defined by sustained growth, technological differentiation, and an increasingly complex set of procurement and production variables. For defense contractors, vehicle integrators, component suppliers, and strategic investors, the ability to interpret market momentum in relation to segment dynamics, competitive positioning, and operational trends is a core strategic capability. This research is built to support that capability by providing a structured, evidence-based view of the market rather than a superficial summary of headline figures.
The report offers detailed segmentation analysis, historical performance tracking, and forward-looking forecasts that extend through the end of the forecast period. It examines vehicle type and application categories in the context of mission requirements and procurement logic, explores regional demand patterns without reducing them to isolated percentages, and analyzes the competitive environment through the lens of program relevance, technological direction, and market concentration. Equally important, it integrates recent developments and structural dynamics—including autonomy advancement, regulatory distinctions, and supply-chain pressures—into a coherent framework for strategic planning.
In practice, this means the research can support a range of high-value decisions. It can inform product roadmap prioritization, highlight where platform capabilities align with emerging mission demands, and identify which competitive differentiators are likely to carry the most weight in procurement evaluations. It can also help organizations assess where market concentration and program continuity create barriers, and where regional specialization or technology-led positioning may open more accessible opportunities. By combining quantitative trajectory data with qualitative insight into industry dynamics, the study is designed to reduce uncertainty and improve the quality of strategic judgment.
Prepared for Actionable Intelligence
The military off-road vehicles market is not defined solely by vehicle mobility; it is shaped by the interplay of operational doctrine, procurement timing, platform survivability, industrial capacity, and technology integration. As the market moves through the 2026 to 2032 forecast horizon, organizations that can read these signals clearly will be better equipped to allocate resources, plan partnerships, and respond to shifting requirements with discipline and speed.
Our Worldwide Military Off-road Vehicles Market research is intended to serve as a strategic reference point for that effort. It provides the analytical depth needed to move beyond surface-level trends and the structured insight required to translate market conditions into concrete decisions. The full report contains the detailed segmentation breakdowns, competitive profiles, and market trajectory data necessary to support planning at the executive and operational levels.
For leaders seeking a more complete view of segment performance, regional demand patterns, and the specific intelligence behind the forecasts discussed here, the full report offers the comprehensive dataset and analysis required to guide next steps with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Military Off-road Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com