

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High Purity Alumina Sol Market Hits $140M in 2025, Forecast 14% CAGR to $350M by 2032

Navigating the High Purity Alumina Sol Horizon: Strategic Imperatives for 2026 and Beyond
The high purity alumina sol market stands at a critical inflection point. For decision-makers in specialty chemicals, advanced materials, and downstream manufacturing, the ability to read the signals of this evolving landscape will separate the prepared from the reactive. Our latest market intelligence release maps the trajectory of this sector with a forensic lens, transforming raw data into a navigable framework for enterprise strategy. As capital allocation and R&D roadmaps transition from 2025 baselines into the 2026–2032 horizon, understanding the velocity, structural drivers, and competitive fault lines of this market is no longer optional. It is a strategic requirement.
The Trajectory: From Steady Growth to Accelerated Expansion
The market's historical arc tells a story of compounding momentum. Between 2020 and 2025, the sector progressed through a period of robust scaling, with revenue climbing from 75.4 million USD to 140.0 million USD. This five-year climb reflects more than cyclical demand; it signals a structural awakening as high purity alumina sol cements its role across high-performance applications.
Looking ahead, the forecast period from 2026 through 2032 paints a picture of sustained acceleration. The base year of 2025 anchors at 140.0 million USD, with the market projected to cross 155.95 million USD in 2026 and continue its ascent toward 350.32 million USD by 2032. This expansion is underpinned by a compound annual growth rate of 14.0%, a velocity that places the sector firmly in growth-market territory. For executives building scenario models, this CAGR is more than a headline figure. It represents the pace at which addressable demand, manufacturing capacity, and value-chain integration will need to adapt.
What makes this trajectory strategically significant is the combination of scale and speed. A market nearly doubling in size over a seven-year window demands careful timing in capacity planning, supply agreements, and product portfolio decisions. The data behind this forecast reveals nuanced inflection points—periods where adoption curves steepen, where regional production shifts alter cost dynamics, and where application-specific demand creates pockets of outsized opportunity. These patterns are mapped in detail within the full study, but their strategic implication is clear: the window to build defensible positions is opening now.
Segment Architecture: Where Demand Energy Concentrates
No market moves uniformly. The architecture of demand in this sector reveals distinct concentration patterns that influence pricing power, production priorities, and partnership pathways. By type, water-based alumina sol solutions command a dominant share of the market, reaching 104.89 million USD, while solvent-based variants account for 35.11 million USD. This split suggests that aqueous dispersion technologies are aligning with broader industry shifts toward safer handling, regulatory compliance, and lower environmental footprints. For manufacturers, the choice between solvent and water-based formulations is increasingly tied to downstream customer requirements and process compatibility rather than simple cost arbitrage.
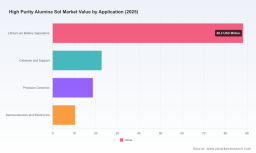
The application landscape further illuminates where growth energy is concentrated. Lithium-ion battery separators represent the largest single demand pillar, with a market size of 88.2 million USD. This positioning reflects the ongoing electrification of transport and energy storage, where high purity alumina sol serves as a critical functional coating that enhances thermal stability and mechanical integrity. The scale of this application channel means that even modest shifts in battery adoption rates, separator specifications, or coating process efficiencies can ripple through the entire alumina sol value chain.
Beyond the dominant channel, several specialized applications contribute meaningful and growing demand. Catalysts and support applications account for 22.72 million USD, precision ceramics contribute 18.65 million USD, and semiconductors and electronics add 10.43 million USD. Each of these segments carries its own technical requirements, qualification cycles, and growth catalysts. Catalyst carriers and support materials, for instance, intersect with refining, petrochemical, and specialty chemical processes where alumina sol's surface properties and dispersion stability are essential. Precision ceramics leverage high purity grades for advanced structural and functional components. Semiconductor and electronics applications demand stringent purity and particle-size control, linking the market to the broader trajectory of advanced manufacturing and miniaturization. The report examines how these segments interact, where substitution risks exist, and which applications are likely to drive incremental volume growth across the forecast period.
Regional Dynamics and Supply Chain Architecture
Geography shapes both opportunity and constraint. Asia Pacific dominates the market with a regional size of 82.29 million USD, reflecting the concentration of manufacturing capacity, downstream industrial demand, and investment in advanced materials across the region. North America follows at 28.53 million USD, Europe at 21.2 million USD, and the Rest of the World at 7.98 million USD. These figures do not merely describe where revenue is generated today; they indicate where supply-chain relationships, production footprints, and partnership ecosystems are most likely to evolve.
For companies evaluating market entry, expansion, or sourcing strategies, regional dynamics require careful reading. The balance between regional self-sufficiency and cross-border trade, the localization of precursor feedstocks, and the proximity of high-value applications all influence cost structures and responsiveness. The full analysis breaks down how these regional channels differ in terms of growth trajectories, demand character, and competitive intensity, giving strategists a basis for allocating resources with geographic precision.
Competitive Landscape: Concentration, Capability, and the Firms Shaping the Field
Market structure matters as much as market size. With a CR3 of 54.2% and a CR5 of 72.8%, the sector exhibits meaningful concentration, yet retains enough fragmentation that regional specialists and application-focused producers can carve out defensible niches. In such an environment, competitive advantage rarely comes from size alone. It emerges from formulation expertise, process control, customer qualification relationships, and the ability to align product grades with specific application requirements.
A global cohort of firms is actively shaping this landscape. Nissan Chemical, headquartered in Japan, offers high purity alumina sol as nano dispersions tailored for coatings, catalysts, and precision applications. Its product positioning reflects a focus on dispersion quality and functional performance across demanding end uses. Sasol Performance Chemicals, based in South Africa, produces and supplies high purity alumina sol grades for catalyst carriers, advanced ceramics, coatings, and specialty chemical uses, linking its portfolio to both industrial and performance-driven segments.
The APAC region also hosts a practical array of manufacturers that serve specialized industrial channels. Zibo Jiarun operates as a manufacturer of high purity alumina sol for refractory coatings, ceramic treatment, and industrial binding applications, while Hangzhou Veking produces high purity alumina sol for coatings and industrial uses. Zibo Jinqi focuses on high purity alumina sol product manufacturing, and Beijing Yataiaohua supplies the material for specialty applications. Zibo Senchi produces high purity alumina sol for refractory and coating markets, rounding out a regional ecosystem that underscores the breadth of industrial demand and the role of application-specific suppliers.
High Purity Alumina Sol Market
In Japan, beyond Nissan Chemical, Kawaken Fine Chemicals supplies high purity alumina sol for catalyst and ceramic precursor applications, and JGC Catalysts and Chemicals provides high purity alumina sol used in catalysts and fine chemical processes. These firms demonstrate how specialized chemistry expertise can translate into sustained relevance within controlled-process industries.
In the United States, Nyacol Nanotechnologies specializes in colloidal dispersions including high purity alumina sol for coatings and performance materials, while Wesbond offers high purity alumina sol for refractory and ceramic binding systems. Together, these companies illustrate how regional producers maintain competitive positioning by targeting performance-grade applications and serving technical customers who value consistency, purity, and material compatibility.
The strategic implication of this competitive map is straightforward: customers and investors should evaluate suppliers not just by scale, but by their alignment to specific application channels, their process reliability, and their ability to sustain quality across batches and production cycles. The report profiles these firms and their positioning in greater depth, examining how their product lines intersect with the largest demand channels and where differentiation is likely to crystallize over the forecast period.
Raw Material Vectors and Cost Dynamics
Feedstock conditions exert a direct influence on production economics and margin trajectories. Aluminum hydroxide serves as a key precursor feedstock for high purity alumina sol production via controlled hydrolysis or peptization processes, making its price behavior a material factor in cost modeling. Recent market observations show a divergence in regional pricing that warrants attention.
In Northeast Asia, aluminum hydroxide prices reached 0.24 USD per kilogram in March 2026, reflecting a 17.2% decline from December 2025. This movement was driven by weakened downstream demand and excess inventories, signaling a period of input-cost relief for producers sourcing in that region. Europe saw aluminum hydroxide prices at 0.63 USD per kilogram in March 2026, with a more moderate 3.1% decline from December 2025 linked to softer demand in flame retardants and construction. North America recorded prices at 0.59 USD per kilogram in March 2026, supported by steadier demand from flame retardants and specialty chemicals despite upstream variations.
These regional differences matter because they affect the relative cost position of producers operating in different geographies and influence the economics of export-oriented supply. The broader context of the aluminum hydroxide market, valued at 12.75 billion USD in 2025 and projected to reach 13.28 billion USD in 2026, further situates the precursor environment within a large and dynamic commodity landscape. Understanding how these input trends interact with regional alumina sol production, inventory cycles, and pricing strategies is essential for building resilient cost assumptions. The full study connects these raw-material signals to the broader market framework, helping leaders anticipate where cost advantages may emerge and where volatility could reshape sourcing decisions.
What the Report Delivers: An Operational Toolkit, Not a Static Snapshot
Strategic intelligence is only valuable if it can be deployed. This study is built to translate market behavior into decision-ready structure. It moves beyond aggregate figures to give executives, procurement leaders, R&D directors, and investors a functional view of how the market is organized and where critical leverage points lie.
At its core, the report provides a layered market model that connects historical performance with the 2026–2032 forecast period. It outlines the market's expansion path, draws attention to the segments and applications driving incremental growth, and identifies the channels where demand is likely to accelerate most rapidly. The segmentation analysis examines how type-based and application-based demand structures interact, helping readers understand which product channels are aligned with the largest volume pools and which are positioned for higher-margin, technically demanding use cases.
Beyond sizing and segmentation, the report includes competitive profiling that places key manufacturers within the context of their product focus, regional presence, and application alignment. It also integrates ingredient and feedstock dynamics into the market narrative, so that cost assumptions are grounded in observable raw-material behavior rather than abstract averages. This integrated approach is designed to support practical decisions: where to invest, how to structure supply, which applications to prioritize, and how to evaluate competitive threats and partnership opportunities.
For teams planning 2026 initiatives, the report serves as a reference point for scenario building. It helps answer questions such as how shifts in battery adoption pathways could alter coating demand, how regional cost differentials might influence sourcing or production footprints, and how concentration in the competitive field could affect negotiation leverage and market entry timing. The detail behind these insights is preserved in the full document, where segmentation splits, application-level sizing, regional breakdowns, and company-level profiles are presented with the granularity needed for operational planning.
Strategic Horizon for 2026: Positioning for What Comes Next
The next phase of this market will favor organizations that can act with both speed and precision. A double-digit CAGR over a multi-year forecast window, a concentrated but still diverse competitive field, and a demand structure anchored by a dominant application channel create a landscape where timing, differentiation, and supply-chain coherence determine outcomes. Leaders will need to assess how their product portfolios align with the highest-growth applications, how their sourcing strategies respond to regional raw-material dynamics, and how their commercial models can capture value in a market where technical performance and consistency are increasingly determinative.
For investors, the opportunity lies in understanding which segments and regional channels offer the most favorable risk-adjusted growth profiles. For producers, the priority is to ensure that capacity, formulation capability, and customer relationships are aligned with the applications that will drive incremental volume. For buyers and downstream manufacturers, the imperative is to map supply resilience, qualify partners with compatible technical capabilities, and anticipate how cost and availability trends may shape procurement over the forecast period.
This market study is designed to give each of these audiences a shared, rigorous foundation for decision-making. It preserves the macro structure that frames strategic direction while embedding the granular intelligence necessary for execution. We invite you to explore the full report to access the detailed segmentation data, regional and application-level sizing, competitive profiles, and raw-material context that complete the picture. In a market expanding at this pace, the advantage belongs to those who move from awareness to informed action.
High Purity Boehmite Market
For detailed analysis of this topic, please visit the official page: High Purity Alumina Sol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com