
Blogs
PW Consulting: Global Cloud Machine Translation Market Hits $1.85B in 2025, Projected to Reach $6.07B by 2032
By pmarketresearch, 2026-09-16
Global Cloud Machine Translation Market: Strategic Intelligence for Enterprise Decision-Making in 2026 and Beyond
The worldwide landscape of digital communication is undergoing a fundamental shift, driven by the rapid maturation of neural machine translation technologies deployed within cloud environments. As organizations expand their global footprint, the ability to localize content, facilitate cross-border collaboration, and engage customers in native languages has transitioned from a competitive advantage to a operational necessity. PW Consulting presents a comprehensive analysis of the Worldwide Cloud Machine Translation Market, offering a detailed roadmap of the industry's trajectory from 2026 through 2032. This report is designed not merely as a statistical overview, but as a strategic asset for executives, investors, and technology leaders who must navigate the complexities of this high-growth sector.
The expansion of this market reflects broader trends in artificial intelligence adoption, cloud infrastructure scalability, and the increasing demand for real-time language services across diverse industries. Our research provides a rigorous examination of market size, growth trajectories, competitive dynamics, and the regulatory environment that will define the next era of cloud-based translation services. By synthesizing historical performance data with forward-looking projections, we enable stakeholders to make informed decisions regarding investment, technology selection, and market entry strategies.
Market Scale and Growth Trajectory
The cloud machine translation market has demonstrated robust expansion over the past five years, establishing a strong foundation for continued acceleration. In 2025, the global market generated revenue of 1,850.0 million USD, representing a significant increase from 820.0 million USD in 2020. This historical progression underscores the growing reliance on cloud-based translation solutions as organizations move away from legacy on-premise systems and embrace the flexibility, scalability, and cost-efficiency of cloud deployment models.
Looking forward, the market is projected to maintain a compelling compound annual growth rate of 18.5 percent throughout the forecast period spanning 2026 to 2032. Under this growth trajectory, market revenue is expected to reach 2,326.58 million USD in 2026, followed by steady escalations to 2,583.93 million USD in 2027, 3,119.43 million USD in 2028, and 3,664.40 million USD in 2029. By the conclusion of the forecast horizon in 2032, the worldwide cloud machine translation market is anticipated to achieve a total revenue of 6,070.15 million USD. These figures highlight the substantial economic opportunity present in this sector and the critical importance of strategic positioning for organizations seeking to capture value within this expanding ecosystem.
Deployment Models and Industrial Adoption Patterns
The architecture of cloud machine translation adoption is shaped by diverse deployment preferences and industry-specific requirements. Organizations evaluate public cloud, private cloud, and hybrid cloud environments based on factors such as scalability needs, data security considerations, compliance obligations, and integration complexity. Each deployment model serves distinct use cases, and understanding the relative advantages of these approaches is essential for technology procurement and infrastructure planning. Our report provides a detailed breakdown of how revenue is distributed across these deployment categories, offering insight into prevailing enterprise preferences and emerging shifts in deployment strategy.
Worldwide AI Learning Machine Market
Industry verticalization represents another critical dimension of market analysis. Different sectors exhibit varying levels of adoption intensity, driven by unique operational demands and translation volume requirements. The information technology and telecommunications sector leads adoption, reflecting the industry's inherent global connectivity and reliance on multilingual interfaces for software, support, and user engagement. E-commerce and retail platforms leverage cloud machine translation to localize product catalogs, customer reviews, and marketing content, enabling seamless cross-border commerce experiences. Healthcare and life sciences organizations increasingly depend on accurate translation for medical documentation, research collaboration, and patient communication, where precision and regulatory compliance are paramount. Media and entertainment companies utilize these technologies for content localization, subtitle generation, and global distribution, while government and defense agencies apply translation solutions for intelligence analysis, diplomatic communication, and multinational operations. Our research maps these industry dynamics in detail, revealing the specific drivers, barriers, and growth opportunities within each vertical.
Regional Market Dynamics
Geographical distribution of cloud machine translation revenue reflects the varying maturity levels, digital infrastructure capabilities, and localization demands across global regions. North America constitutes a substantial share of the market, supported by advanced cloud infrastructure, a dense concentration of technology enterprises, and high adoption rates among both established corporations and emerging startups. Europe represents a significant market segment, characterized by diverse linguistic requirements, stringent data protection regulations, and a strong emphasis on translation quality and privacy-preserving deployment options. The Asia Pacific region demonstrates considerable growth potential, fueled by expanding digital economies, increasing cross-border trade, and the proliferation of multilingual user bases across countries such as China, Japan, South Korea, and India. Latin America and the Middle East and Africa regions, while currently representing smaller revenue contributions, are emerging as important growth corridors as digital transformation initiatives accelerate and localization requirements intensify.
Our report examines these regional dynamics with granularity, providing insights into local market characteristics, infrastructure developments, and the interplay between regional regulations and market growth. Understanding these geographical nuances is critical for organizations developing global market entry strategies or optimizing their cloud translation deployments across multiple jurisdictions.
Competitive Landscape: Key Market Participants
The cloud machine translation market is shaped by a diverse array of technology providers, ranging from hyperscale cloud platforms to specialized translation firms, each bringing distinct capabilities, ecosystem advantages, and strategic positioning. The competitive environment is characterized by ongoing innovation in neural network architectures, expansion of language coverage, integration with broader artificial intelligence and cloud service portfolios, and increasing focus on enterprise-grade security and customization.
Worldwide Cloud Machine Translation Market
Google LLC, headquartered in Mountain View, California, provides the Google Cloud Translation API, a scalable cloud-based neural machine translation service supporting over two hundred languages with real-time text and speech translation capabilities designed for enterprise integration. This offering leverages Google's extensive research in artificial intelligence and its global cloud infrastructure to deliver high-volume, low-latency translation services.
Microsoft Corporation, based in Redmond, Washington, offers Microsoft Azure Translator, a cloud machine translation service with neural models supporting more than one hundred languages. This service benefits from deep integration with the Microsoft ecosystem, including Office and Teams, enabling seamless translation functionality within productivity workflows and enterprise applications widely used across global organizations.
Amazon Web Services Inc., headquartered in Seattle, Washington, delivers Amazon Translate, a neural machine translation service within the AWS cloud supporting more than seventy-five languages. This offering is optimized for customization, batch processing, and tight integration with other AWS services, appealing to organizations already invested in the Amazon cloud ecosystem and seeking flexible, scalable translation solutions.
DeepL GmbH, headquartered in Cologne, Germany, provides the DeepL API and Enterprise cloud machine translation focused on high-accuracy neural translations, with particular strength in European language pairs. DeepL emphasizes quality and nuance in translation output, complemented by privacy-focused cloud deployment options that address the requirements of security-conscious enterprise clients.
IBM Corporation, based in Armonk, New York, offers IBM Watson Language Translator, a cloud-based machine translation service using neural networks with domain customization capabilities within the IBM Cloud. This solution targets organizations seeking tailored translation models aligned with specific industry terminology and operational contexts.
Alibaba Cloud, headquartered in Hangzhou, China, provides the Alibaba Cloud Machine Translation API, a neural machine translation service integrated with the Alibaba Cloud ecosystem. This offering supports multiple languages with a focus on Asian language pairs, catering to the growing digital commerce and communication needs of the Asia Pacific region.
Tencent Cloud, based in Shenzhen, China, delivers Tencent Machine Translation, a cloud-based neural machine translation service with strong performance in Chinese-English and other language pairs, integrated with Tencent Cloud infrastructure. This service supports the translation demands of enterprises operating within Tencent's extensive digital ecosystem.
SYSTRAN SA, headquartered in Paris, France, offers SYSTRAN Translate cloud and hybrid machine translation solutions with neural and hybrid models. SYSTRAN emphasizes secure enterprise deployments and customization capabilities, appealing to organizations with stringent security requirements and specialized translation needs.
The market concentration among existing participants reflects a moderately consolidated competitive environment, with the top three firms accounting for a combined revenue share that underscores the influence of major cloud platform providers while still leaving meaningful space for specialized vendors to differentiate through quality, domain expertise, and regional focus. The top five firms collectively represent a substantial portion of market revenue, illustrating the importance of ecosystem integration, brand recognition, and technological scale in this sector.
Regulatory and Infrastructure Dynamics Shaping Market Evolution
The trajectory of the cloud machine translation market is increasingly influenced by regulatory frameworks and infrastructure considerations that affect how translation services are deployed, governed, and consumed. Organizations operating in this space must navigate an evolving landscape of data protection laws, artificial intelligence regulations, and energy infrastructure constraints that collectively shape the operational and strategic environment.
In the regulatory domain, the European Union AI Act, which became effective in 2024 with phased implementation, classifies certain high-risk artificial intelligence systems, including advanced machine translation solutions, and imposes requirements for risk assessment, transparency, and compliance. This regulatory framework introduces new obligations for providers and users of cloud machine translation services operating within or targeting the European market, necessitating robust governance structures and documentation practices.
Data sovereignty regulations further complicate the deployment of cloud machine translation services. The General Data Protection Regulation, the EU Data Act applicable from September 2025, the Digital Operational Resilience Act, and the NIS2 Directive collectively require localized data processing and control for cloud services handling sensitive information within machine translation workflows. These requirements influence deployment model selection, provider choice, and architectural design, particularly for organizations managing personally identifiable information, confidential business data, or regulated content.
From an infrastructure perspective, the energy demands of artificial intelligence data centers represent a growing consideration for the cloud machine translation sector. AI data centers, which are critical for powering cloud machine translation inference workloads, are projected to drive significant increases in global electricity demand. Estimates suggest that United States data center consumption could reach between 325 and 580 terawatt-hours by 2028, according to research from the Lawrence Berkeley National Laboratory. This surge in energy consumption has implications for operational costs, sustainability initiatives, and the broader economic environment in which cloud services operate. Concurrently, United States residential electricity prices rose by 7.1 percent in 2025, with data center-driven demand cited as a major contributing factor alongside grid investments, as reported by the United States Energy Information Administration. These energy cost dynamics may influence cloud service pricing structures and the economic calculus of large-scale translation deployments.
In the United States, the CLOUD Act allows federal authorities to compel United States-based cloud providers to disclose data regardless of storage location, impacting data sovereignty considerations for international cloud machine translation users. This legal framework introduces additional complexity for multinational organizations evaluating provider options and data residency requirements.
Strategic Value of Comprehensive Market Intelligence
For enterprise leaders, technology investors, and strategic planners, the decisions made in 2026 will have lasting implications for competitive positioning and operational efficiency in the global marketplace. Selecting the appropriate cloud machine translation partner, determining the optimal deployment architecture, anticipating regulatory shifts, and understanding the competitive landscape require a depth of analysis that goes beyond surface-level market observations.
PW Consulting's Worldwide Cloud Machine Translation Market report delivers actionable intelligence across multiple dimensions critical to decision-making. The report provides detailed segmentation analysis across deployment models, industry verticals, and geographic regions, revealing the specific growth vectors and revenue concentrations that define the market. It includes comprehensive profiles of key market participants, examining their service offerings, technological capabilities, ecosystem integrations, and strategic positioning. The analysis incorporates an evaluation of market concentration metrics, competitive intensity, and the potential for new entrants or consolidation activities that could reshape the industry structure.
Furthermore, the report addresses the practical implications of regulatory developments and infrastructure trends, providing guidance on compliance considerations, data sovereignty management, and the economic factors influencing cloud service economics. By integrating these diverse elements into a cohesive analytical framework, the research enables organizations to develop robust strategies that account for both current market conditions and future evolution.
The insights contained within this report are essential for organizations seeking to optimize their translation technology investments, identify partnership opportunities, assess competitive threats, and capitalize on emerging growth areas. Whether you are evaluating vendor selection criteria, planning market expansion, or developing long-term technology roadmaps, the detailed analysis presented in this study provides the foundation for confident, data-informed strategic decisions.
To access the complete market intelligence, including all segmentation data, competitive profiles, regional breakdowns, and forward-looking projections, we invite you to obtain the full report through our official channels. The comprehensive analysis delivered in this publication represents the depth of expertise and rigorous research methodology that PW Consulting brings to complex technology markets, empowering our clients to navigate the future of cloud machine translation with clarity and strategic foresight.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud Machine Translation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Difurfuryldisulfide Market Hits $24.8M in 2025, Driven by F&B Flavoring and Asia Pacific
By pmarketresearch, 2026-09-16
Navigating the Difurfuryldisulfide Market: Strategic Intelligence for 2026 and Beyond
The specialty chemicals sector continues to reward organizations that pair operational precision with forward-looking market intelligence. As industrial formulators, flavor houses, and supply chain leaders finalize their 2026 procurement and capacity strategies, the difurfuryldisulfide market presents a compelling case for disciplined evaluation. In this landscape, our latest research deliverable arrives not as a static snapshot, but as a decision-enabling framework designed to align procurement, R&D, and competitive positioning with the realistic trajectory of a maturing, value-driven niche.
Built on a rigorous five-year historical baseline spanning 2020 through 2025 and extending through a seven-year forecast window to 2032, this analysis translates longitudinal demand signals, pricing behaviors, and structural shifts into actionable intelligence. The narrative that follows is deliberately curated: it demonstrates the depth of our methodology and the relevance of our findings while preserving the granular segmentation required for precise planning. For executives who require exact regional breakdowns, purity-tier valuations, and application-level market shares, the full report remains the definitive source.
A Measured Expansion Trajectory Anchored in Value-Tier Demand
The difurfuryldisulfide market has followed a disciplined growth curve, expanding from a baseline of USD 20.12 million in 2020 to a projected USD 26.26 million in 2026. This progression is not the result of volatile speculation but rather reflects steady consolidation across flavor, fragrance, and industrial applications where sulfur-linked furan derivatives serve distinct functional roles. Over the forecast horizon through 2032, the market is expected to reach USD 33.52 million, translating to a compound annual growth rate of 4.4 percent.
For strategic planners, that trajectory carries two immediate implications. First, growth is structural rather than cyclical, suggesting that demand is anchored in recurring formulation requirements rather than one-off sourcing events. Second, the pace of expansion is moderate enough to reward careful supplier evaluation and contract structuring, yet fast enough to penalize organizations that treat this category as a commoditized afterthought. Companies that treat difurfuryldisulfide as a strategic input, rather than a back-pocket ingredient, will be better positioned to manage continuity, specification compliance, and total cost of ownership.
The research also situates this trajectory within a broader feedstock and regulatory context. Furfural, the primary upstream material for furfuryl derivatives, is derived substantially from agricultural residues such as corn cobs, and its downstream pathways influence both availability and cost stability for difurfuryl disulfide producers. In parallel, evolving environmental frameworks, including European emission restrictions on formaldehyde that favor furfuryl alcohol-based resins over phenolic alternatives, are reshaping demand patterns in adjacent furan-chemistry applications. These dynamics do not merely color the headline numbers; they define the operating environment in which suppliers and buyers must make long-term commitments.
Competitive Architecture and the New Relevance of Compliance
The competitive landscape for difurfuryldisulfide is concentrated but diversified by function, geography, and certification posture. With the top three players holding approximately 42.5 percent of the market and the top five extending that share to 58.8 percent, the industry exhibits enough fragmentation to preserve sourcing flexibility while maintaining enough concentration to reward supplier relationship management. Organizations that understand who controls which grade, which certifications, and which distribution channels will move faster when specifications tighten or lead times compress.
Several established participants illustrate how the market is bifurcating between natural-identity positioning, synthetic-grade utility, and research-grade precision. In North America, Advanced Biotech Inc. continues to supply difurfuryl disulfide natural and synthetic grades for food, beverage, and aroma applications, with kosher and other certifications maintained through 2026. Its recent renewal of kosher certification for DIFURFURYL DISULFIDE 10% ETOH NATURAL, valid through November 2026, underscores how compliance continuity has become a differentiator in food and beverage supply chains. Axxence Aromatic GmbH, operating from Germany, provides a natural-grade offering recognized under EU natural and FEMA 3146 standards, and its December 2025 halal certification renewal reflects a broader trend: identity-preserved and certification-backed materials are increasingly tying up market share in sensitive applications.
Beyond these Western and European players, the competitive field extends across East Asia and specialized distribution networks. TCI America, through Tokyo Chemical Industry Co., Ltd., manufactures and distributes difurfuryl disulfide at 95.0+ percent purity for research, synthesis, and industrial use, often routed through established laboratory distributors. Spectrum Chemical Mfg. Corp. and Scimplify serve parallel but distinct roles in the U.S. market by offering laboratory-scale and bulk industrial supply, respectively, with regulatory documentation and COA/SDS support. Alfa Chemistry positions itself as an ISO 9001:2015 certified supplier of furan derivatives with 98+ percent purity options, while Aurochemicals addresses the natural flavor enhancement segment with diluted formats such as 1 percent in ethanol or propylene glycol. On the manufacturing side, Nanjing MSN Chemical Co., Ltd. and Beijing Lys Chemicals Co., Ltd. emphasize global distribution of fine chemicals and gram-to-ton scale production, respectively, while Tengzhou Runlong Fragrance Co., Ltd., operating since 2004, focuses on meat flavor agent applications with FEMA 3146 and CAS 4437-20-1 specifications.
This roster is not merely a directory; it is a map of capability, risk, and negotiation leverage. Some participants compete primarily on purity thresholds and documentation readiness, others on natural identity and certification portability, and still others on scale, logistics, and price architecture. The report’s competitive assessment section explains how these postures interact with buyer requirements across food and beverage, fragrance and cosmetics, and animal feed applications, helping procurement teams match specification needs with supplier strengths rather than defaulting to price alone.
Natural Sulforaphane Market
From Headline Numbers to Operating Decisions
A realistic market study must do more than describe demand; it must help teams convert context into commercial decisions. Our research is structured to support that translation through practical, cross-functional modules that move beyond the aggregate market size and CAGR. The report examines how upstream cost differentials and feedstock geography influence derivative pricing, how regulatory shifts alter preferred resin and polymer pathways and, by extension, downstream furan demand, and how certification renewals and safety data sheet updates affect sourcing continuity.
Readers will find detailed attention to the interplay between purity requirements and application suitability, a critical dimension in a category where 98+ percent purity often commands a premium but where certain formulations may be optimized at lower thresholds. The analysis also explores how regional manufacturing costs and logistics friction shape supply options, noting for example that furfural production economics can differ materially between China and North America due to labor and logistics variables, and that furfuryl alcohol pricing has moved within defined bands over recent years depending on purity and grade. These factors do not operate in isolation; they help explain why some buyers prioritize certified natural identity while others emphasize bulk pricing and documentation speed.
Equally important, the report assesses supply continuity risk through the lens of certification lifecycles, regulatory documentation, and distributor networks. With recent events ranging from Advanced Biotech’s SDS update in mid-2025 to Axxence’s halal certification in late 2025 and Advanced Biotech’s kosher renewal in early 2026, the evidence points to a market where compliance is not a static checkbox but an ongoing operational commitment. Organizations that track these milestones and incorporate them into supplier scorecards will face fewer surprises during qualification cycles and audits.
Difurfuryldisulfide Market
Where the Report Goes Further: Executive Intelligence Designed for Action
To support execution across procurement, R&D, and strategy, the full report delivers operational content that extends well beyond the macro summary. Decision-makers can expect:
- A structured view of market size evolution from the 2020 base through the 2026 forecast and the full projection period to 2032, framed in U.S. dollars and millions of dollars, with analysis of inflection points rather than isolated figures.
- A competitive mapping that aligns each key company’s product grades, purity ranges, certification posture, and distribution channels with the applications and geographies where they matter most.
- An examination of how upstream feedstock dynamics, including furfural availability and furfuryl alcohol pricing trends, influence derivative supply chains and downstream cost structures.
- A regulatory and compliance narrative that connects emission directives, certification renewals, and documentation practices to sourcing decisions and audit readiness.
- Practical guidance on evaluating natural versus synthetic identity, purity thresholds, and dilution formats across food, beverage, fragrance, cosmetics, and animal feed applications.
This structure is intentional. Rather than overwhelming readers with static tables, the report connects each insight to a decision point: which supplier to qualify, which purity tier to target, how to structure multi-period contracts, and where to place R&D emphasis as feedstock economics and regulatory frameworks evolve.
Why 2026 Decisions Depend on Precision, Not Just Direction
The difurfuryldisulfide market in 2026 is best understood as a category where the cost of ambiguity is rising. Moderate but steady growth, a moderately concentrated supplier base, and certification-sensitive end uses all point to the same conclusion: organizations that operate on generic assumptions will pay for it in qualification delays, specification mismatches, or avoidable premium pricing. By contrast, teams that integrate feedstock context, competitive capability, and compliance continuity into a single planning framework can protect continuity while improving unit economics.
That is precisely where the full research earns its place in the decision cycle. The executive overview presented here has outlined the strategic contours and demonstrated the analytical rigor behind the study. What it cannot do, by design, is replace the detailed regional, purity, and application segmentation that purchasing directors and formulation leads need before committing capital. Those specifics, including precise market values and split-level intelligence, are preserved in the complete report so that each organization can align the data with its own specification thresholds, volume profiles, and compliance requirements.
Accessing the Full Intelligence
A market of this shape rewards early clarity. The full Difurfuryldisulfide Market research report provides the granular segmentation, company-by-company capability mapping, regulatory timeline, and forecast detail required to convert strategy into procurement and product decisions with confidence. For leaders planning 2026 sourcing, R&D prioritization, and supplier qualification, the complete study is the optimal reference point. Detailed segmentation data, company profiles, and forecast tables are available through our research portal, where the full dataset can be aligned to your internal volume assumptions and compliance standards.
For detailed analysis of this topic, please visit the official page: Difurfuryldisulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Aesthetic Phototherapy Lamp Market Hits $645.5M in 2025, Poised for 8.75% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence: Navigating the Worldwide Aesthetic Phototherapy Lamps Market in 2026
The global aesthetic phototherapy lamps market stands at a pivotal inflection point as industry stakeholders transition from the 2020-2025 historical growth cycle into the 2026-2032 forecast period. Driven by a compound annual growth rate of 8.75 percent, the sector is projected to expand from a 2025 baseline of USD 645.5 million to an estimated USD 1.16 billion by 2032. This trajectory reflects a structural shift in how aesthetic dermatology, clinical skincare, and at-home wellness converge around evidence-based light-based interventions. For executives, investors, and product strategists, 2026 represents the year when regulatory clarity, reimbursement pathway maturation, and competitive consolidation will decisively shape market entry, portfolio positioning, and revenue forecasting. Our latest Worldwide Aesthetic Phototherapy Lamps Market research is designed to convert this momentum into executable intelligence.
Macro Trajectory and the 2026 Decision Window
The five-year historical record from 2020 through 2025 demonstrates consistent expansion, moving from USD 425.1 million to USD 594.85 million before reaching the 2025 anchor of USD 645.5 million. The forward projection series maps a steady climb: USD 701.98 million in 2026, USD 763.4 million in 2027, USD 830.2 million in 2028, USD 902.84 million in 2029, USD 981.84 million in 2030, USD 1.07 billion in 2031, and USD 1.16 billion in 2032. While aggregate figures establish the scale of opportunity, the strategic value of this research lies in unpacking the forces that will redistribute share, pricing power, and margin profiles across light source categories, application verticals, end-user channels, and regional ecosystems. Companies that treat 2026 as a planning horizon rather than a passive transition will be better positioned to align capital allocation, regulatory filings, and channel strategy with the market’s actual architecture.
What the Report Delivers: Actionable Scoping for Product, Pricing, and Channel Strategy
This study is structured to support operational decision-making rather than high-level observation. It maps the market across multiple dimensions, providing a granular view of how demand concentrates by technology platform, clinical and consumer application, procurement environment, and geography. The segmentation analysis examines light source dynamics across LED, IPL, and other lamp technologies, clarifying where performance characteristics, total cost of ownership, and regulatory status create durable advantages or exposure. The application lens dissects demand patterns across skin rejuvenation, acne treatment, pigmentation treatment, and wound healing, highlighting how clinical indications, consumer adoption curves, and service models diverge by use case. The end-user framework evaluates medical clinics, beauty salons, and home care settings, exposing the distinct purchasing behaviors, service expectations, and price sensitivity that define each channel.
Beyond segmentation, the report addresses competitive concentration and ecosystem structure. With the top three players accounting for approximately 42.15 percent of market value and the top five reaching roughly 58.8 percent, the landscape reflects meaningful incumbency advantages alongside persistent entry points in niche indications, regional channels, and consumer-grade devices. The study integrates company profiles, capability assessments, and recent development tracking to help strategists benchmark positioning, identify partnership targets, and anticipate where capacity expansion, product refreshes, or regulatory filings may alter local supply dynamics.
Regulatory and Reimbursement Context: Why 2026 Is a Policy-Sensitive Year
Aesthetic phototherapy is increasingly governed by a layered regulatory and reimbursement environment, and 2026 is a year in which several structural developments will influence commercial planning. Aesthetic LED phototherapy devices intended for wrinkle reduction and acne treatment are classified as Class II under 21 CFR 878.4810 with product codes including OHS, requiring 510(k) clearance for U.S. marketing. This clearance pathway has become a strategic gatekeeper, particularly as manufacturers pursue over-the-counter and at-home indications. Recent FDA 510(k) clearances illustrate the pace of this activity: in December 2025, Shenzhen Saidi Light Therapy Technology received clearance for its LED Light Therapy Face Mask series, including FM60X, FM80, and FM100X variants for facial wrinkles and mild to moderate inflammatory acne. In June 2025, Shenzhen Kaiyan Medical Equipment, the manufacturer behind CurrentBody Skin, secured clearance for the CurrentBody Skin LED Light Therapy Mask Series 2, MK-90H, for over-the-counter full-face wrinkle treatment. In February 2025, Xuzhou Kernel Medical Equipment obtained clearance for 308nm excimer phototherapy device models for psoriasis and vitiligo, which are relevant in aesthetic dermatology contexts. In November 2024, Shenzhen Walton Technology received clearance for LED Light Therapy Machine models G1, G3, G4, and G6 for over-the-counter aesthetic use in wrinkle treatment and acne.
These clearances are not isolated product events; they signal broader pathway trends. The American Medical Association activated CPT Category III Code 0936T effective January 1, 2025, for photobiomodulation therapy to support data collection toward potential future Medicare reimbursement. Simultaneously, revised CPT code descriptors for excimer laser procedures, CPT 96920, 96921, and 96922, are scheduled to become effective January 1, 2027, expanding reimbursable indications to include additional inflammatory and autoimmune skin conditions such as vitiligo, atopic dermatitis, and alopecia areata. In parallel, national CPT code reimbursement rates for excimer laser treatments in 2025 ranged from USD 137 to USD 183 per treatment depending on treated area, spanning under 250 square centimeters to over 500 square centimeters. Together, these developments shape the economics of clinical adoption, the attractiveness of medical-channel procurement, and the incentive structure for device manufacturers pursuing reimbursable indications.
Procurement realities further complicate the commercial picture. Hospital and institutional purchasing for phototherapy equipment is frequently executed as structured value-based purchases bundled with accessories, installation, and service, reflecting capital expenditure constraints in public tenders. This bundling behavior influences not only upfront pricing but also service-level expectations, lifecycle support requirements, and the competitive leverage of manufacturers that can deliver integrated deployment models rather than standalone hardware.
Competitive Landscape and Where Share Is Being Won or Lost
The competitive set in aesthetic phototherapy spans dermatologic device leaders, specialty lamp manufacturers, consumer-grade wearable and mask developers, and integrated energy-based aesthetic platform companies. Beijing Sincoheren offers dermatologic phototherapy lamps including LUMERA for aesthetic skin treatments. Kernel Medical Equipment, based in Xuzhou, Jiangsu, manufactures aesthetic and dermatologic phototherapy lamps and excimer devices for skin rejuvenation and treatment. LightSources and LightTech, headquartered in Orange, Connecticut, specialize in fluorescent and UV specialty light therapy lamps for medical and aesthetic phototherapy applications. Lumitex, based in Strongsville, Ohio, provides therapeutic lighting solutions and light therapy components for medical device manufacturers in aesthetic applications. ProReset, operating across Germany and Europe, offers aesthetic phototherapy lamps such as ProRed, Lumina, and Eva Led for skin rejuvenation, blood circulation, and muscle recovery. BioPhotas, Inc., in the United States, develops the Celluma series of biophotonic LED devices for aesthetic anti-aging, acne, and skin rejuvenation treatments. Shenzhen Idea Light Limited, also known as IDEATHERAPY, manufactures red light therapy panels and wearable LED phototherapy devices for aesthetic skin treatments. CurrentBody, manufactured by Shenzhen Kaiyan Medical Equipment, provides LED light therapy masks such as Series 2 for at-home aesthetic treatment of facial wrinkles. LightStim offers LED light therapy devices integrated in aesthetic systems for skin rejuvenation and acne treatment. Alma Lasers develops energy-based aesthetic devices including phototherapy and light-based systems for skin treatments. Lumenis provides laser and light-based aesthetic solutions with phototherapy capabilities for skin rejuvenation. Candela Medical, formerly Syneron Candela, offers aesthetic light and laser systems for phototherapy applications in dermatology and skin rejuvenation. Cutera manufactures aesthetic laser and light devices including phototherapy options for skin treatments. Fotona combines laser and light-based aesthetic solutions for precision skin rejuvenation and phototherapy. The Daavlin Company specializes in phototherapy lamps and units for dermatologic and aesthetic skin treatments. National Biological Corporation provides phototherapy lamps for aesthetic medicine and dermatologic applications. Herbert Waldmann GmbH & Co. KG manufactures phototherapy lamps and lighting systems used in aesthetic and medical treatments.
This diversity of players reflects a market in which technology leadership, regulatory access, distribution reach, and brand positioning all matter. Some firms compete primarily through clinical-grade performance and reimbursement-adjacent indications; others compete through consumer usability, aesthetics, and at-home convenience. The report evaluates where these strategies intersect, where overlap creates pricing pressure, and where differentiation remains defensible. It also tracks how recent FDA clearances and product introductions may alter regional supply, channel availability, and benchmark specifications for downstream procurement teams.
Segmentation Signals That Matter for 2026 Planning
While aggregate market size and growth rates set the overall context, the operational value of this research lies in its ability to help teams interpret where demand is forming and how it will translate into procurement, sales, and investment decisions. Light source selection, for example, is not merely a technical preference; it affects regulatory classification, treatment protocols, consumables and service economics, and the credibility of clinical claims. Application focus shapes channel strategy, because skin rejuvenation, acne treatment, pigmentation treatment, and wound healing each carry distinct practitioner adoption patterns, consumer expectations, and reimbursement or self-pay dynamics. End-user channel mix is equally critical, since medical clinics, beauty salons, and home care settings differ in purchasing cycles, training requirements, service contracts, and price elasticity.
The regional dimension further complicates planning. Demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, but distribution is not uniform in either volume or strategic significance. Local regulatory environments, clinical practice norms, aesthetic service infrastructure, and procurement models influence how quickly new products are adopted and how aggressively pricing is contested. Rather than presenting isolated percentage splits, the study frames regional analysis as a set of operational considerations: where channel access is mature, where regulatory clearance creates an entry barrier or an opportunity, and where procurement bundling and service expectations alter the economics of market participation.
How to Use This Research for 2026 Decision-Making
The report is intended to support a range of strategic actions. For product and R&D leaders, it provides context on where light source and application segmentation create the strongest case for investment, iteration, or portfolio pruning. For commercial and market-access teams, it clarifies how regulatory classification, 510(k) activity, CPT coding developments, and reimbursement ranges influence the viability of clinical versus consumer positioning. For corporate development and investor relations, it frames competitive concentration, company-level capabilities, and recent clearance activity in a way that supports benchmarking, partnership identification, and risk assessment. For regional and channel strategists, it connects segmentation and dynamics to practical questions about where to prioritize go-to-market resources, how to structure service and installation offerings, and which procurement environments demand bundled value propositions.
Crucially, the study is designed to be read as a decision framework, not a static snapshot. The 2026-2032 forecast horizon is long enough to matter for capital planning and product roadmaps, yet near enough that the assumptions behind it can be tested against live regulatory filings, procurement behavior, and competitor moves. By linking historical performance, forward projections, segmentation logic, and regulatory context, the report helps organizations avoid plans that are either too optimistic about adoption speed or too conservative about structural growth.
Worldwide Aesthetic Phototherapy Lamps Market
Why This Study Matters Now
The aesthetic phototherapy lamps market is expanding, but expansion alone does not create advantage. Advantage comes from understanding where growth is concentrated, which regulatory and reimbursement shifts alter commercial logic, and how competitive intensity differs across light sources, applications, channels, and regions. With an 8.75 percent CAGR driving the market from USD 645.5 million in 2025 toward USD 1.16 billion in 2032, the cost of misreading segmentation or timing is rising. The Worldwide Aesthetic Phototherapy Lamps Market research gives decision-makers the structured intelligence needed to calibrate strategy for 2026 and beyond.
To access the complete segmentation detail, competitive benchmarks, regional analysis, and forward forecast tables that support these conclusions, we invite you to explore the full report. The underlying data, scenario logic, and company-level profiles are available in the complete publication, where they can be used directly for internal planning, investment review, and market-entry assessment.
Aesthetic Devices Market
For detailed analysis of this topic, please visit the official page: Worldwide Aesthetic Phototherapy Lamps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
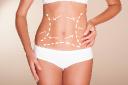
Getting back behind the wheel is an important part of returning to normal routines after surgery, but driving too soon can create unnecessary risks. After liposuction, temporary soreness, swelling, reduced mobility, and the effects of medication may affect your ability to respond safely in traffic. For patients considering Liposuction in Riyadh , knowing when driving may be appropriate and what factors should be considered can make the recovery period easier to manage.
How Soon Can You Drive After Liposuction?
There is no single driving timeline that applies to every patient. The appropriate time depends on the extent of the procedure, the treated areas, pain levels, mobility, and whether prescription pain medication is still being used.
Patients should generally wait until they are alert, comfortable, able to move freely, and capable of performing all necessary driving movements without hesitation. During recovery after Liposuction in Riyadh , your surgeon can provide individualized guidance based on how your healing is progressing.
Why Should You Avoid Driving Immediately?
Driving requires more than simply sitting comfortably in a vehicle. You need to turn your body, operate the pedals, use the steering wheel, check blind spots, and respond quickly to unexpected situations.
Pain or stiffness can make these movements uncomfortable or slower. Swelling or tenderness may also make sitting for extended periods difficult. Most importantly, medications that cause drowsiness or reduced alertness can make driving unsafe.
Does Pain Medication Affect Driving?
Medication is an important consideration when deciding whether to drive. Some prescription pain medicines can cause drowsiness, dizziness, slower reaction times, or impaired concentration.
Patients should not drive while taking medication that affects alertness or their ability to operate a vehicle safely. If you are uncertain about the effects of a medication, ask your surgeon or pharmacist before driving.
What Movements Should You Be Able to Perform?
Before returning to driving, you should be able to comfortably perform the movements required for normal vehicle operation. This may include getting into and out of the driver's seat, turning the steering wheel, checking behind you, pressing the brake firmly, and moving your legs without significant discomfort.
A useful consideration is whether you could perform an emergency maneuver without being limited by pain or stiffness. If you cannot confidently make these movements, it is better to wait.
Does the Treatment Area Matter?
The location of liposuction can influence driving comfort. Procedures involving the abdomen, waist, hips, thighs, or other areas involved in sitting and leg movement may temporarily make driving more uncomfortable.
For example, soreness around the thighs could make operating pedals uncomfortable, while abdominal tenderness may make sitting upright or twisting difficult. The more extensive the treatment, the more important it is to consider your individual recovery rather than relying on a fixed timeline.
What About Short Trips?
A short journey may seem easier than a long drive, but the same safety requirements still apply. Even a brief trip requires adequate alertness, mobility, and the ability to react quickly.
When you first return to driving, it may be sensible to keep the initial journey limited and familiar if your surgeon has cleared you to drive. Avoid situations that could require prolonged sitting or complicated driving until you feel fully comfortable.
Should Someone Drive You Home After Surgery?
Patients should arrange transportation home after liposuction rather than planning to drive themselves. Immediately after surgery, anesthesia or sedative medications may affect alertness and coordination.
Having a responsible adult accompany you can also provide practical support during the first part of recovery. Follow your surgical team's specific instructions regarding transportation and immediate postoperative care.
How Can You Prepare to Return to Driving?
Before driving again, make sure you can sit comfortably and access all vehicle controls without significant pain. Check that you can wear the required seat belt comfortably and move your arms, legs, and torso sufficiently for safe vehicle operation.
It can also help to consider the type of vehicle you drive. Getting into a low car or operating a manual transmission may require more movement than driving a vehicle with an easier seating position and automatic controls.
When Should You Ask Your Surgeon?
Your surgeon is the best person to assess your individual recovery and provide guidance about returning to driving. Follow-up appointments can help determine whether healing is progressing appropriately and whether your activity level can be increased.
Do not assume that feeling generally better means you are automatically ready to drive. You should be sufficiently recovered to react safely and should not be affected by medications that impair alertness or coordination.
What Other Activities Should You Consider?
Driving is only one part of returning to everyday life. Patients may also need guidance about returning to work, exercising, lifting objects, sleeping comfortably, and performing household activities.
These activities may have different recovery timelines depending on the treatment area and extent of surgery. Gradually increasing activity according to professional instructions can help avoid unnecessary strain during healing.
Warning Signs During Recovery
Some discomfort, swelling, and bruising can be expected after liposuction, but patients should remain attentive to unusual or worsening symptoms. Increasing pain, significant swelling, fever, breathing difficulties, chest pain, or other concerning symptoms should be discussed promptly with a healthcare professional.
Driving should also be postponed if you feel dizzy, unusually weak, excessively sleepy, or otherwise unable to concentrate fully. Safety should take priority over returning to a normal routine quickly.
Book Your Appointment at Royal Clinic Saudia
Returning to driving after liposuction depends on individual healing, mobility, comfort, and medication use rather than a universal schedule. If you are planning treatment and want to understand your expected recovery and activity restrictions, book a consultation with Royal Clinic Saudia for personalized guidance about Liposuction in Riyadh .
PW Consulting: LCD Scrubber Market to Hit $509.4M by 2032, Growing 5.85% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Heat Wet Scrubber for LCD Market
As the display manufacturing industry enters a critical phase of technological iteration and environmental compliance, the heat wet scrubber segment has emerged as a foundational infrastructure component. PW Consulting provides this strategic overview to introduce our latest comprehensive study on the Worldwide Heat Wet Scrubber for LCD Market, designed to equip executives, procurement leaders, and investment strategists with the analytical framework required for high-stakes decisions in 2026 and beyond. The intersection of next-generation production lines, stringent emission mandates, and evolving gas abatement architectures demands a clear, data-grounded understanding of market trajectories. This report delivers that clarity.
Macro Trajectory and the 2026 Decision Horizon
The heat wet scrubber market for LCD manufacturing has demonstrated consistent expansion over the past five years, reflecting the sector's structural reliance on reliable hazardous gas treatment. Historical performance from 2020 through 2025 establishes a clear growth baseline, with revenue scaling from 258.4 million USD to 342.15 million USD. This upward momentum carries into the forecast window, where the market is projected to advance at a compound annual growth rate of 5.85 percent, ultimately reaching 509.4 million USD by 2032. The trajectory underscores a shift from incremental capacity additions to strategically integrated abatement ecosystems.
For decision-makers in 2026, these figures are not merely historical artifacts or forward estimates; they represent a structural inflection point. The sustained growth pattern signals that heat wet scrubber deployment is transitioning from a peripheral compliance purchase to a core facility planning parameter. Manufacturers are increasingly evaluating scrubber architectures alongside line configurations, chemical process adjustments, and regional regulatory calendars. The forecast period extending to 2032 reveals continued expansion, with notable acceleration phases that will reshape supply chain negotiations, capacity planning, and technology roadmaps. Understanding where these inflection points occur, which product families capture incremental share, and how regional deployment patterns evolve will separate reactive procurement from proactive strategic positioning.
Technological Architecture and Segment Dynamics
Heat wet scrubbers within the LCD manufacturing environment are engineered to neutralize hazardous process gases, including perfluorocarbons and other reactive exhaust streams, through high-temperature interaction with liquid-phase treatment media. The operational demands of modern LCD fabs require systems that balance destruction efficiency, chemical resistance, and seamless integration into both point-of-use and central abatement layouts. Materials science plays a decisive role; corrosion-resistant alloys and specialized polymers are routinely specified to withstand acidic and reactive exhaust conditions, ensuring long-term reliability under continuous operational cycles.
The product landscape in this market is structured around distinct architectural approaches. Single-stage configurations offer streamlined installation and targeted treatment for specific exhaust profiles, while multi-stage architectures provide extended residence times and enhanced capture efficiency for complex gas mixtures. Integrated systems combine thermal treatment, wet scrubbing, and auxiliary control modules into unified platforms, increasingly favored by facilities seeking to minimize footprint, standardize maintenance protocols, and reduce inter-system coordination complexity. Parallel to these product categories, application segmentation reflects the generational evolution of LCD production lines. Legacy and mid-generation fabs continue to drive steady demand for abatement capacity aligned with established process chemistries, while advanced-generation lines, including Gen 8.5 and Gen 10.5 architectures, are reshaping throughput requirements and exhaust composition, prompting equipment manufacturers to refine thermal-wet treatment parameters and housing configurations.
Raw material selection, unit sizing, and integration topology are no longer purely engineering decisions; they directly influence total cost of ownership, downtime exposure, and future expansion flexibility. Decision-makers must evaluate how these architectural choices interact with their specific process roadmap and compliance timeline.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated competitive structure, with the top three players collectively representing 62.45 percent of revenue and the top five accounts capturing 78.3 percent. This concentration reflects the capital intensity of abatement engineering, the need for application-specific process validation, and the importance of long-term service and compliance support in LCD manufacturing environments. Established Korean and Japanese equipment providers dominate much of the installed base, leveraging deep experience in semiconductor and display fab environments, while specialized innovators continue to challenge incumbents through modular designs, plasma-hybrid configurations, and differentiated thermal-wet treatment platforms.
Several core enterprises define the current competitive terrain. Triple Cores Technology delivers plasma, thermal-wet, and heat wet scrubber systems tailored for hazardous gas treatment in semiconductor and LCD manufacturing, including PFC decomposition capabilities. YOUNGJIN IND specializes in gas abatement systems, offering heat wet scrubber models such as the YHS-06W and YHS-04W, complemented by high-temperature plasma and eco-friendly hazardous gas treatment options. Global Standard Technology manufactures a range of scrubbers, including thermal wet types, focused on harmful gas purification for semiconductor and LCD production. KC Innovation provides scrubber solutions for gas processing within semiconductor and display manufacturing workflows. Unisem supplies heat wet scrubbers and gas abatement equipment directed at LCD and semiconductor applications, while SemiAn Technology offers heat wet scrubber solutions integrated into broader gas treatment systems for LCD manufacturing. Japan Pionics contributes heat wet scrubber equipment aligned with LCD and semiconductor gas abatement requirements. Integrated Plasma Inc combines plasma and heat wet scrubber technologies for LCD process exhaust gas treatment, and Ebara Technologies provides wet scrubber abatement systems, including models engineered for display and LCD sub-fab environments, addressing water-soluble process gases across semiconductor and adjacent industries.
The competitive environment is further shaped by ongoing portfolio evolution. In March 2026, DAS Environmental Experts introduced a flexible SALIX wet scrubber portfolio optimized for semiconductor manufacturing applications, with relevance to high-purity exhaust treatment in display processes. Developments of this nature illustrate the continuous refinement of abatement platforms and the increasing emphasis on adaptability across process chemistries and fab layouts. For market participants, the strategic question is not simply which vendor offers the lowest upfront price, but which provider can sustain performance across generation transitions, minimize service disruption, and adapt to evolving emission standards without requiring costly architectural retrofits. The concentration metrics suggest that scale advantages, installed-base service networks, and application-specific validation remain decisive competitive moats.
Regulatory, Operational, and Supply Chain Forces
Regulatory pressure continues to be a primary catalyst for abatement investment. Semiconductor and LCD manufacturing facilities must deploy high-efficiency abatement systems to comply with strict emission standards for PFCs and other hazardous process gases. Compliance is no longer a static target; it is a moving threshold shaped by regional environmental policy, community exposure expectations, and evolving best-practice frameworks for process exhaust management. Facilities that treat abatement as a compliance checkbox risk encountering costly retrofits or operational interruptions when standards tighten. Conversely, organizations that integrate abatement strategy into long-range fab planning can align equipment selection with anticipated regulatory calendars and process chemistry shifts.
Operational durability and material resilience are equally critical. Heat wet scrubbers for LCD typically incorporate corrosion-resistant materials such as specialized alloys or polymers to handle acidic and reactive exhaust streams. The durability of these components directly affects maintenance frequency, replacement cycles, and overall system availability. In high-uptime environments, the choice of construction materials and the robustness of thermal management design can determine whether a scrubber functions as a stable backbone of the emission control infrastructure or becomes a recurring source of downtime and unplanned service spend.
On the demand side, increasing LCD and display panel production drives demand for reliable point-of-use and central abatement systems, including heat wet scrubbers, to manage process emissions. This production-driven demand is not uniform across regions or line generations, and procurement strategies must account for varying deployment intensities, local sourcing considerations, and integration requirements with existing sub-fab and exhaust infrastructure. Supply chain resilience also matters as manufacturers evaluate lead times, component availability, and the ability of suppliers to support rapid installation schedules aligned with line build-outs or upgrade cycles.
What the Analysis Delivers: Operational Intelligence for 2026
This research report is built to convert market complexity into executable intelligence. It provides a detailed mapping of historical performance and forecast trajectories, enabling executives to benchmark current procurement assumptions against macro growth patterns and identify periods of likely demand acceleration. The analysis examines segmentation architecture across product types and application generations, allowing strategy teams to evaluate which configurations are gaining traction, where capacity is expanding, and how line generational shifts influence equipment preferences. Regional deployment patterns are assessed to clarify where concentration is highest, where growth is emerging, and how geographic factors shape sourcing, installation, and service logistics.
Beyond market sizing, the report delivers a competitive benchmarking framework that evaluates the positioning of leading equipment providers, including their technology portfolios, application focus, and strategic movement patterns. It integrates the impact of recent product portfolio expansions and regulatory developments into an actionable context, helping procurement and engineering teams anticipate vendor evolution and align vendor selection with long-range compliance and capacity plans. The study also incorporates material and design considerations relevant to heat wet scrubber performance in LCD environments, linking corrosion-resistant construction, thermal treatment efficiency, and system integration choices to total cost of ownership and operational risk.
For 2026 decision-making, the report functions as a strategic filter. It helps leadership teams prioritize capital allocation, evaluate make-versus-buy considerations for abatement infrastructure, prepare for generation transitions in LCD production, and develop vendor engagement strategies that account for market concentration and ongoing product innovation. The objective is not to provide a static snapshot, but to equip decision-makers with the structural understanding required to anticipate change rather than merely react to it.
Worldwide Spray Scrubbers Market
Conclusion: Positioning for the Next Phase of Market Development
The worldwide heat wet scrubber market for LCD manufacturing is entering a phase defined by technological maturity, regulatory reinforcement, and evolving production architectures. Historical growth trajectories, forward forecast patterns, and the concentrated nature of the competitive field all point to a market where strategic clarity yields durable advantage. Organizations that approach abatement planning with a full understanding of product architecture, application generation shifts, regional deployment dynamics, and vendor positioning will be better prepared to manage cost, compliance, and operational continuity through 2032 and beyond.
This research study provides the depth, structure, and forward-looking analysis required to support those decisions. We invite industry leaders, engineering directors, and strategy teams to engage with the full report, where detailed segmentation insights, competition mapping, and forecast methodology are presented in complete form. The 2026 planning window demands more than surface-level market awareness; it requires the kind of structured intelligence that turns evolving market signals into confident strategic action.
Worldwide Heat Wet Scrubber for LCD Market
For detailed analysis of this topic, please visit the official page: Worldwide Heat Wet Scrubber for LCD Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CW DFB Laser Diode Market Hits $920M in 2025, Projects 8.15% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the High-Power CW DFB Laser Diode Market: Strategic Intelligence for 2026 and Beyond
The global landscape for Continuous Wave Distributed Feedback laser diodes is undergoing a definitive transformation. As enterprises anchor their technological roadmaps for the 2026 fiscal year, the capacity to secure reliable, high-performance optical sources has shifted from a technical preference to a strategic imperative. This market intelligence briefing serves as the executive introduction to the comprehensive CW DFB Laser Diode Market research report recently published by PW Consulting. Our analysis is designed to equip leadership teams with the granular visibility required to navigate supply chain constraints, competitive pressures, and shifting demand vectors across the optical communication and sensing sectors.
The semiconductor sector focused on high-power CW DFB architectures is no longer niche. The integration of silicon photonics with advanced transceiver architectures has created a surge in demand that is reshaping vendor priorities and capacity planning across the globe. This report provides a detailed examination of the revenue trajectories, regional dynamics, and competitive maneuvers that will define the market through the end of the decade. By exploring the following insights, stakeholders can better align their procurement strategies, investment decisions, and partnership models with the realities of a rapidly expanding ecosystem.
Market Trajectory and Macro Growth Dynamics
The baseline for 2026 operational planning is anchored in a sustained compound annual growth rate of approximately 8.15 percent measured in USD millions. According to our forecast period spanning from 2026 through 2032, the market value is projected to expand significantly from its established 2025 baseline. This trajectory reflects a consistent upward momentum that began accelerating in the early 2020s and has intensified through recent historical data points. The global market size reached roughly 920 million USD in the base year, with projections indicating a steady climb to exceed 1.5 billion USD by 2032.
Worldwide High Power CW Laser Market
This growth profile is not merely a function of volume expansion. It is deeply intertwined with engineering shifts in transceiver technology, particularly the migration toward 800G and 1.6T architectures within AI-driven data center environments. The demand for uncooled operation capabilities at elevated temperatures, alongside the push for higher power outputs to support co-packaged optics, has fundamentally altered the performance thresholds required from CW DFB components. Organizations evaluating market entry or expansion must account for these technical benchmarks, as they directly influence pricing power, qualification cycles, and long-term vendor retention.
The historical data series from 2020 through 2025 underscores a compounding effect. Each successive year has delivered incremental gains that signal structural rather than cyclical growth. For decision makers in 2026, this means that legacy assumptions regarding demand volatility must be recalibrated. The market is consolidating around high-power, high-reliability specifications that favor manufacturers with mature epitaxial processes and scalable packaging capabilities. Strategic planning should therefore prioritize partnerships and supply agreements that lock in capacity ahead of the projected inflection points across the forecast horizon.
Competitive Landscape and Key Player Intelligence
The competitive environment within the CW DFB segment is characterized by a moderate degree of concentration. Our analysis indicates a consolidated market structure where a small group of dominant players commands a substantial share of global revenue. The top three participants collectively hold approximately 48.5 percent of the market, while the top five entities extend their combined influence to roughly 62.2 percent. This concentration level carries important implications for procurement strategy, negotiation leverage, and risk diversification.
Several industry leaders have defined the current frontier through aggressive product development and targeted capacity initiatives. MACOM, headquartered in Lowell, Massachusetts, has reinforced its position with high-power CW DFB diode offerings designed for uncooled operation at temperatures up to 85 degrees Celsius. Their patented etched facet technology supports datacom and silicon photonics applications, with power levels such as 75mW and 100mW at 1310nm. These specifications address the growing need for thermal resilience and simplified thermal management in dense transceiver modules.
Coherent Corp., based in Saxonburg, Pennsylvania, continues to drive performance benchmarks with high-efficiency CW DFB chips optimized for next-generation silicon photonics. Their portfolio includes 70mW uncooled 1310nm variants and higher power configurations for CWDM4, specifically tailored for 800G and 1.6T transceiver ecosystems. The company has also advanced its sampling activities, introducing low-noise 400mW CW lasers on a BH DFB platform designed for co-packaged optics and silicon photonics at 1311nm, signaling a clear focus on the AI data center transition.
Broadcom, operating from San Jose, California, supplies edge-emitting CW DFB diode chips including the 247F series, which delivers up to 100mW uncooled performance across CWDM wavelengths. These components are positioned for silicon photonics and external modulator applications, reinforcing the company's role in high-volume transceiver supply chains. Meanwhile, Furukawa Electric in Tokyo has undertaken a significant capacity expansion initiative. The manufacturer produces 70mW and 100mW high-output CW DFB diode chips for silicon photonics and data center transceivers, and has announced a new manufacturing plant expected to increase capacity by over 500 percent by 2028. This move reflects the broader supply chain reality that InP-based epitaxial wafer processing and chip fabrication expansion are critical to absorbing surging demand for high-output CW DFB components.
Regional and specialized players further diversify the competitive field. Innolume GmbH, located in Dortmund, Germany, specializes in high-power quantum dot-based CW DFB lasers delivering 70mW to 400mW-plus in the O-band, with uncooled options for datacom, silicon photonics, and sensing applications. DenseLight Semiconductors in Singapore offers InP-based high-power CW DFB lasers ranging from 50mW to 70mW-plus, with customization options for datacom, telecom, and silicon photonics platforms. Eblana Photonics, based in Dublin, Ireland, provides single-frequency DFB-like laser diodes using discrete-mode technology across NIR and MIR bands for sensing, LIDAR, and telecom applications. SemiNex Corporation in Peabody, Massachusetts, delivers high-power CW DFB lasers and semiconductor optical amplifiers optimized for AI data center silicon photonics integration in both O-band and C-band configurations.
CW DFB Laser Diode Market
Additional contributors include Frankfurt Laser Company in Friedrichsdorf, Germany, which supplies DFB wavelength-stabilized laser diodes spanning 760nm to 3640nm for various application domains, and RPMC Lasers in O'Fallon, Missouri, which distributes and supports a broad range of DFB laser diodes including CW options from multiple manufacturers for precision applications. Recent market activity further illustrates the pace of change. In September 2025, Everbright Photonics introduced a 200mW uncooled CW DFB optical communication chip emphasizing high power and low consumption. Also in April 2025, HieFo launched high-efficiency CW DFB InP lasers for silicon photonics transceivers supporting uncooled O-band operation. By December 2025, MTC achieved small-batch shipment of DFB photonic chips and announced plans for CW light sources in 2026, indicating emerging competition and broadening supply options.
Segmentation, Applications, and Wavelength Dynamics
The revenue composition of the CW DFB market is shaped by distinct segmentation vectors that illuminate where growth capital and engineering attention are concentrated. Wavelength segmentation reveals a clear hierarchy of performance requirements. The 1310nm band commands the largest share of market value, followed by the 1550nm band, with other wavelengths comprising a smaller but strategically relevant portion. This distribution aligns with the optical communication industry's reliance on O-band for silicon photonics transceivers and C-band for extended reach and dense wavelength division multiplexing applications. Understanding these wavelength preferences is essential for vendors calibrating product roadmaps and for buyers evaluating component availability across different transceiver architectures.
Application segmentation further delineates the revenue drivers. Optical communication represents the dominant application category, reflecting the intense demand from data center interconnects, fiber optic transceivers, and silicon photonics integration. Sensing and LiDAR applications form a substantial secondary segment, leveraging the precision and stability of CW DFB diodes for range-finding, environmental monitoring, and advanced detection systems. Medical and industrial applications occupy a meaningful share as well, where the reliability and single-frequency characteristics of DFB architectures enable specialized instrumentation, material processing, and diagnostic tools. Each application vertical carries distinct qualification requirements, volume profiles, and price sensitivities that must be factored into market engagement strategies.
Regional segmentation underscores the geographic concentration of demand and manufacturing capability. Asia Pacific accounts for the largest revenue share, driven by the density of data center construction, silicon photonics fabrication infrastructure, and transceiver assembly capacity. North America follows as a significant contributor, supported by advanced transceiver developers, silicon photonics innovators, and AI infrastructure investments. Europe maintains a steady presence with a focus on specialized manufacturing, sensing applications, and telecom equipment integration. Latin America and the Middle East and Africa together represent smaller but emerging participation, reflecting gradual infrastructure development and niche deployment opportunities. These regional distributions inform supply chain planning, logistics optimization, and market entry timing for organizations operating across multiple geographies.
Technology Drivers, Standards, and Supply Chain Considerations
The performance expectations for CW DFB laser diodes in 2026 and beyond are governed by rigorous technical and regulatory frameworks. Data center transceiver deployments increasingly require compliance with Telcordia GR-468 reliability qualifications, particularly for non-hermetic uncooled operation at temperatures up to 85 degrees Celsius. This standard shapes component design, testing protocols, and lifecycle validation, creating a competitive filter that favors manufacturers with mature qualification pipelines and proven field reliability. The alignment of product specifications with these reliability benchmarks is no longer optional; it is a prerequisite for inclusion in high-volume transceiver supply chains.
Beyond compliance, the industry is propelled by macro trends tied to the rapid expansion of AI-driven data centers. The demand for high-power CW DFB lasers is directly linked to the evolution of 800G to 1.6T silicon photonics transceivers and the emergence of co-packaged optics architectures. These architectures demand higher optical output power, improved thermal stability, and tighter wavelength control to maintain signal integrity at higher data rates. Suppliers that can deliver uncooled high-power solutions while meeting spectral precision requirements are positioned to capture value in this expanding design space. The interplay between transceiver roadmaps and laser diode performance creates a feedback loop where advances in one domain accelerate requirements in the other.
Supply chain resilience is another critical dimension. The expansion of InP-based epitaxial wafer processing and chip fabrication capacity is essential to meet the surging demand for high-output CW DFB chips. Recent announcements of new manufacturing plants and capacity increases highlight the industry's recognition that wafer availability, epitaxial quality, and chip yield will become binding constraints if not proactively addressed. Procurement teams must evaluate supplier capacity roadmaps, wafer sourcing strategies, and packaging throughput to mitigate the risk of allocation bottlenecks. Additionally, the diversification of product offerings across O-band, C-band, and broader wavelength ranges allows organizations to hedge against single-point supply vulnerabilities while aligning with specific transceiver design requirements.
Strategic Takeaways for 2026 Decision Makers
The CW DFB Laser Diode Market research report provides a structured foundation for translating market intelligence into actionable strategy. For executive teams planning 2026 operations, several priorities emerge from the analysis. First, the growth trajectory and concentration profile suggest that long-term supply agreements and dual-sourcing strategies will be increasingly valuable as leading vendors scale capacity and tighten allocation for high-demand configurations. Second, the emphasis on uncooled high-power performance and GR-468 compliance indicates that qualification speed and reliability documentation will be decisive factors in supplier selection. Third, the segmentation data reveals that optical communication remains the primary revenue engine, while sensing, LiDAR, medical, and industrial applications offer diversification pathways that can buffer against transceiver cycle volatility.
The report also details competitive benchmarking, product specification landscapes, regional revenue distributions, and application-specific demand patterns. It examines the impact of recent product launches, capacity expansions, and sampling initiatives on market positioning and pricing dynamics. Readers gain access to a comprehensive assessment of how leading companies are aligning their technologies with silicon photonics integration, co-packaged optics, and AI data center requirements. The analysis further explores the implications of supply chain capacity investments for lead times, cost structures, and availability across different wavelength and power tiers.
By integrating these insights, organizations can refine their technology roadmaps, optimize procurement portfolios, and identify partnership opportunities that align with the market's structural evolution. The report is designed to support cross-functional decision making across engineering, procurement, strategy, and finance teams, ensuring that investments and commitments reflect the most current market realities. For stakeholders seeking the complete dataset, segmentation breakdowns, company profiles, and forecast models, the full research publication provides the depth required to convert intelligence into execution.
The CW DFB Laser Diode Market research represents a timely resource for navigating a sector defined by rapid technological change and expanding demand. As 2026 unfolds, the ability to anticipate capacity shifts, specification trends, and competitive moves will distinguish organizations that secure supply resilience from those that react to constraints. PW Consulting's analysis offers the strategic clarity needed to make those decisions with confidence, grounded in rigorous market data and informed by the latest industry developments.
For detailed analysis of this topic, please visit the official page: CW DFB Laser Diode Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pressure-resistant Sensor Market to Hit $3.87B by 2032, Growing at 6.82% CAGR
By pmarketresearch, 2026-09-16
Navigating the Depths: Strategic Intelligence for the 2026 Pressure-Resistant Sensor Landscape
The Imperative for Precision in High-Stake Environments
As industrial and medical technologies push into increasingly hostile environments, the demand for reliable pressure-resistant sensor solutions has transitioned from a niche requirement to a critical infrastructure necessity. From the crushing depths of the ocean to the precision-driven chambers of medical catheters, these sensors serve as the nerve endings of modern automation and healthcare. For executives and strategic planners navigating the 2026 fiscal year, understanding the trajectory of this market is not merely an academic exercise but a fundamental component of risk management and growth planning. The Worldwide Pressure-resistant Sensor Market is undergoing a period of significant transformation, driven by technological maturation, regulatory shifts, and expanding application scopes that demand higher fidelity and durability.
This market research report is designed to cut through the noise, offering a clear-eyed view of where value is being created and where capital should be allocated. The analysis covers a comprehensive forecast period extending to 2032, building upon a robust historical dataset from 2020 through 2025. By examining the historical revenue trends alongside forward-looking projections, stakeholders can identify inflection points that will define competitive advantage in the coming years. The market has demonstrated resilience and steady expansion, with overall revenue figures showing a consistent upward trajectory. Starting from a baseline of approximately 1.76 billion USD in 2020, the sector has grown steadily, reaching an estimated 2.44 billion USD by 2025. This growth underscores the increasing reliance on precision sensing across diverse heavy-duty and delicate diagnostic applications.
Looking ahead, the forecast indicates a sustained growth momentum with a Compound Annual Growth Rate (CAGR) of 6.82 percent. This rate suggests that the market is not merely expanding but evolving, with revenue projections climbing toward 3.87 billion USD by the end of the forecast period in 2032. For investors and corporate strategists, this trajectory signals a maturing industry where early movers in specific technology segments or geographic expansions stand to capture disproportionate value. However, raw growth numbers tell only half the story. The true strategic insight lies in understanding the segmentation dynamics, the competitive concentration, and the external regulatory forces that will shape profitability within this growth envelope.
Market Segmentation and Revenue Dynamics
A granular understanding of how revenue is distributed across different types, applications, and regions is essential for targeted strategy formulation. The report dissects the market into distinct categories to reveal where the primary drivers of value reside. Currently, the Piezoresistive Sensors segment represents a significant share of the revenue mix, reflecting its widespread adoption due to cost-effectiveness and proven reliability in varied conditions. Complementing this, Thin-film Strain Gauge Sensors maintain a strong presence, particularly where higher precision and temperature stability are required. Meanwhile, the Fiber Optic Sensors and Capacitive Pressure Sensors segments, while smaller in absolute terms, represent high-growth niches driven by specific needs for electromagnetic immunity and high-sensitivity measurements in specialized environments.
On the application front, the demand landscape is diversified but heavily weighted toward sectors where failure is not an option. Oil and Gas Downhole Monitoring continues to be a substantial revenue contributor, fueled by the need for accurate pressure data in extreme subsurface conditions. Aerospace and Defense Engines also command a significant portion of the market, driven by stringent safety requirements and the ongoing modernization of propulsion systems. Industrial Hydraulic Machinery remains a steady pillar of demand, while Deep-sea Marine Exploration represents an emerging frontier with growing investment in underwater infrastructure and resource exploration. The report provides detailed analysis on how these application verticals interact with technological types, offering insights into cross-segments opportunities that are often overlooked in broader industry surveys.
Geographic distribution of revenue reveals a complex landscape of regional strengths and strategic entry points. North America and Asia Pacific currently represent the largest revenue pools, reflecting mature industrial bases and rapid technological adoption respectively. Europe maintains a significant share, particularly in high-precision manufacturing and automotive-adjacent sensor applications. Latin America and the Middle East and Africa regions, while smaller in terms of absolute revenue share, offer specific growth trajectories tied to local industrial development and energy sector investments. The analysis within the report maps these regional dynamics without relying on outdated generalizations, providing localized intelligence that helps multinational corporations optimize their supply chain and sales strategies.
Worldwide Pressure-resistant Sensor Market
Voltage Pressure Sensor Market
Competitive Landscape and Strategic Consolidation
The pressure-resistant sensor market is characterized by a moderately concentrated competitive environment, where scale, technology portfolios, and regulatory compliance create significant barriers to entry. The report highlights that the top three companies account for approximately 38.45 percent of the market revenue, while the top five players control over half of the total market share at 52.12 percent. This concentration suggests that while there is room for niche players, the bulk of value generation is captured by established giants with diversified portfolios and strong customer integration capabilities. Understanding the specific positioning of these key entities is vital for any strategic maneuvering, whether it involves partnership, acquisition, or competitive repositioning.
Several core companies define the current competitive contours. TE Connectivity continues to expand its footprint, recently establishing new manufacturing facilities to increase capacity for medical microfluidic components, which supports broader sensor integration efforts. Their extensive portfolio includes medical-grade options suitable for harsh environments, reinforcing their position in both industrial and healthcare adjacent sectors. Honeywell International Inc. remains a pivotal supplier for high-precision applications, particularly in medical settings where reliability in clinical environments is paramount. Their focus on patient monitoring and respiratory devices aligns with broader trends in healthcare technology.
In the medical-specific domain, Edwards Lifesciences Corporation, now part of BD, provides dominant solutions in cardiac and ICU pressure monitoring kits, including disposable transducers for hemodynamic monitoring. Merit Sensor Systems specializes in MEMS piezoresistive technologies capable of withstanding extreme pressures up to 15,000 PSI with biocompatibility, catering to high-pressure inflation devices and harsh-media compatible needs. Utah Medical Products holds a strong position with single-use pressure transducers and biopharm-specific sensors compatible with rigorous sterilization methods like Gamma Irradiation and Ethylene Oxide. Amphenol All Sensors Corporation focuses on ultra-low to low pressure requirements for respiratory equipment, emphasizing precision. Millar Inc. stands out for high-fidelity MEMS catheter-tip solutions and chronic implantable sensor modules, recently showcasing customizable developer kits and long-term monitoring options at industry trade shows. Sensata Technologies, Setra Systems, Metallux SA, and Smiths Medical further round out a competitive field where differentiation often comes down to material science, certification levels, and application-specific engineering.
Regulatory Dynamics and Operational Realities
Strategic planning in this sector must account for the regulatory environment, which acts as both a gatekeeper and a growth enabler. Medical pressure sensors used inside the body are classified as Class III devices requiring FDA certification, imposing strict development and quality assurance timelines on market entrants. Common company certifications include ISO 13485 and ISO 9001, while product-level standards such as ANSI/3A and EHEDG apply where biomedical and hygiene requirements intersect with sensor design. These regulatory frameworks influence not just market access but also operational costs and time-to-market, factors that are rigorously analyzed in the report to help firms budget for compliance and risk mitigation.
Reimbursement policies are increasingly shaping demand, particularly in healthcare. The Centers for Medicare and Medicaid Services issued a National Coverage Determination effective 2025 covering FDA-approved implantable pulmonary artery pressure sensors for heart failure management. This regulatory milestone enables reimbursement for FDA-approved devices in clinical management, directly influencing the adoption rates of implantable solutions and encouraging manufacturers to invest in this growing sub-segment. Such policy shifts create ripple effects across the supply chain, affecting everything from raw material selection to sterile packaging strategies.
Operational realities also extend to material science and sterilization compatibility. Certain high-pressure sensor housings utilize materials like polysulfone or polycarbonate that are compatible with Gamma Irradiation and Ethylene Oxide sterilization, maintaining a five-year shelf life and USP Class VI compliance. These specifications are critical for biopharmaceutical and medical fluid monitoring applications where contamination control is non-negotiable. Additionally, specific high-pressure-resistant designs are utilized in specialized respiratory equipment, such as jet ventilators, where bias flow and occlusion detection are essential for patient safety. These technical nuances, often buried in product documentation or regulatory summaries, are elevated to strategic insights in our analysis, helping engineering and procurement teams make informed sourcing decisions.
Strategic Value for 2026 and Beyond
The release of this market research coincides with a critical juncture for industry stakeholders. As the market moves from the 2.63 billion USD projected revenue of 2026 toward its 2032 targets, the differentiation between success and stagnation will depend on the ability to interpret data accurately and act upon it swiftly. This report is not merely a collection of numbers; it is a strategic tool designed to answer the pressing questions that keep executives awake at night. Where should R&D budgets be allocated to capture the highest marginal returns? Which geographic regions offer the best risk-adjusted growth opportunities for the next fiscal cycle? How do recent regulatory changes alter the competitive balance between incumbent manufacturers and emerging challengers?
By integrating historical performance with forward-looking indicators, the research provides a framework for scenario planning. The identified CAGR of 6.82 percent serves as a benchmark against which internal projections can be validated. The segmentation breakdowns allow for the identification of overlooked niches where competition is less fierce but demand is stable. The competitive profiling of key companies offers a window into potential partnership opportunities or acquisition targets that align with long-term portfolio strategies. Furthermore, the analysis of recent developments, such as facility expansions and trade show revelations, provides real-time intelligence on where major players are investing their capital and focus.
For investors, the concentration metrics offer a lens through which to assess market stability and the potential for consolidation. For product managers, the detailed type and application splits illuminate the technical trends that will define the next generation of sensor requirements. For supply chain leaders, the regional revenue maps highlight potential vulnerabilities or opportunities for localization. In an era where data-driven decision-making is the standard, access to precise, validated, and strategically contextualized intelligence is a distinct competitive advantage.
To fully leverage these insights, stakeholders are encouraged to explore the complete report. The full version contains downloadable segments, proprietary data tables, and deep dives into specific technology trajectories that go beyond the scope of this overview. Access the full Worldwide Pressure-resistant Sensor Market research today to equip your organization with the intelligence needed to navigate the complexities of 2026 and secure a leadership position in the years to come.
For detailed analysis of this topic, please visit the official page: Worldwide Pressure-resistant Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Chlorotrifluoroethylene (CTFE) Market Outlook 2026: Strategic Insights for Industry Leaders
The global chemical landscape is undergoing a period of profound transformation, driven by the dual forces of advanced material demand and stringent regulatory frameworks. Within this complex ecosystem, Chlorotrifluoroethylene (CTFE) has emerged as a critical enabler for high-performance industries ranging from pharmaceuticals to aerospace. As we navigate the year 2026, the strategic decisions made by key stakeholders regarding supply chain resilience, capacity allocation, and technological adoption will define competitive advantage for the remainder of the decade. PW Consulting is pleased to present our latest comprehensive market research, designed to equip decision-makers with the actionable intelligence required to thrive in this evolving sector.
Our analysis consolidates historical data from 2020 through 2025 with a detailed forecast extending to 2032. The compound annual growth rate projected for this period stands at 5.1, signaling a robust trajectory for this specialty fluorochemical. While the market valuation recorded a slight adjustment from 866.47 million in 2025 to 859.98 million in 2026, this initial fluctuation precedes a significant upward trend, with revenues anticipated to surpass the 1.2 billion mark by 2032. Such dynamics suggest that while the immediate future may hold stabilization phases, the long-term demand fundamentals remain deeply embedded in the growth strategies of end-use industries. This report serves as a navigational chart through these figures, offering context rather than just raw numbers.
Market Trajectory and Historical Context
Understanding the past performance of the CTFE market is essential for validating future projections. The revenue data collected over the last half-decade illustrates a period of consistent expansion, with values rising from 685.4 million in 2020 to the recent 866.47 million. This growth reflects the escalating consumption of fluoropolymers and specialty chemicals that rely on CTFE as a primary feedstock. However, the forecast period introduces a more nuanced picture. Following the 2026 valuation, the market is expected to recover and accelerate, reaching 972.99 million in 2027 and continuing its climb toward the 2032 target. This pattern underscores the importance of strategic patience and investment timing for manufacturers looking to capitalize on the next phase of commercial growth.
For enterprise leaders, these figures represent more than just financial metrics. They indicate shifting capacity utilizations and potential supply-demand imbalances that could affect pricing strategies. Our research delves into the factors influencing these valuations, ensuring that your organization can anticipate market pulses rather than merely reacting to them. The stability of the long-term forecast suggests that the underlying drivers of demand are structural rather than cyclical, providing a secure foundation for capital investment planning.
Worldwide Chlorotrifluor Ethylene (CTFE) Market
Segmentation Dynamics and Application Drivers
The versatility of Chlorotrifluoroethylene is reflected in its diverse application landscape. Our report breaks down the market intensity across key sectors, highlighting where value is being generated and where growth opportunities are concentrated. Pharmaceutical blister packaging remains a dominant force within the application segment, driven by the need for high-barrier materials that ensure product safety and longevity. This sector alone represents a substantial portion of the total revenue mix, underscoring the critical role CTFE plays in healthcare supply chains.
Beyond pharmaceuticals, the chemical processing equipment sector continues to be a significant consumer, utilizing CTFE-based materials for their resistance to corrosive environments and high thermal stability. Aerospace and defense components also feature prominently, leveraging the lightweight and durable properties of fluoropolymers derived from CTFE. Furthermore, the electronics and semiconductors industry is increasingly reliant on high-purity materials for fabrication processes. This diverse spread across industries means that volatility in one sector can often be offset by stability or growth in another, creating a resilient overall market structure for investors and producers.
PVDF-TrFE Resin Market
Regional Landscape and Supply Chain Considerations
Geographically, the market is distributed across several key regions, each with distinct characteristics influencing supply and demand. Asia Pacific currently holds a significant share of the revenue, reflecting the region's massive manufacturing base and growing downstream demand. North America follows closely, driven by advanced industrial applications and regulatory standards that favor high-quality materials. Europe maintains a steady presence, supported by established chemical infrastructure and strict environmental compliance frameworks.
Latin America and the Middle East and Africa represent emerging opportunities, albeit with smaller current market footprints. Understanding the specific dynamics within these regions is crucial for companies considering expansion or sourcing strategies. Local capacity additions, logistical challenges, and regional regulatory environments all play a role in shaping the economic viability of operations in these areas. Our report provides the granular context needed to assess risk and opportunity in each geographic territory without getting lost in superficial generalizations.
Competitive Landscape and Key Industry Players
The CTFE market is characterized by a high level of concentration, with the top three companies accounting for 78.4 of the market share and the top five controlling 91.2. This concentration suggests that market movements are heavily influenced by the strategic actions of a few dominant players. Major entities such as Honeywell International Inc. and Daikin Industries Ltd. are pivotal in shaping the supply landscape. Honeywell, based in Charlotte, North Carolina, continues to be a major producer of high-purity CTFE monomer, supplying critical grades for fluoropolymer production and specialty chemicals. Their recent announcements regarding capacity investments highlight a commitment to meeting growing demand across electronics and aerospace sectors.
Daikin Industries Ltd., headquartered in Osaka, Japan, stands out as a leading global manufacturer that not only produces CTFE monomer but also polymerizes it into NEOFLON PCTFE resins. Their focus on semiconductor and cryogenic applications demonstrates a vertically integrated approach that adds value beyond basic material supply. Recent developments, including a strategic partnership with a leading semiconductor manufacturer in mid-2025 and an acquisition of a specialized CTFE fluid manufacturer in late 2024, illustrate their aggressive strategy to secure supply chains and expand product portfolios.
In the Chinese market, producers such as Jiangsu Bluestar Technology Co., Ltd. and Changshu Hongjia Fluorochemical Technology Co., Ltd. are significant contributors. Bluestar utilizes CTFE as a feedstock for a broader specialty fluorochemical portfolio, including fluorine rubber and coatings. Hongjia specializes in high-purity monomer for fluoropolymer applications. Additionally, suppliers like Yufeng Chemical emphasize high purity for polymerization in plastics and pharmaceutical industries. The presence of these players indicates a competitive environment where regional supply capabilities are increasingly important. Recent capacity data indicates that Chinese producers, including Dongyue Group and Chemours' Changshu facility, account for significant portions of regional supply, influencing global pricing dynamics.
Recent Developments and Strategic Moves
Recent industry activities provide clear signals regarding where capital and technology are flowing. In addition to the capacity expansions and partnerships mentioned earlier, Solvay expanded fluorochemical production capacity in 2024 to meet growing demand for high-purity CTFE fluids in electronics manufacturing. These moves collectively point toward a tightening supply environment for high-grade materials, particularly those meeting the rigorous standards of the semiconductor and electronics industries.
For competitors and investors, tracking these developments is essential. Capacity expansions by major incumbents can alter market balance, while partnerships often signal future demand hotspots. Our report analyzes these events not in isolation but as part of a broader strategic trend, helping you understand how competitor maneuvers might impact your own positioning.
Regulatory Environment and Raw Material Dynamics
Operating in the CTFE market requires navigating a complex regulatory landscape. CTFE and related fluorochemicals are subject to TSCA Section 12(b) export notification requirements by the US EPA. Additionally, stringent environmental regulations, including REACH in the EU and EPA rules in the US, influence production processes and drive shifts toward lower-impact formulations and sustainable manufacturing. Compliance with these regulations is not merely a legal obligation but a strategic differentiator that can open or close market access.
On the supply side, CTFE is primarily produced via dechlorination or catalytic hydrodechlorination of 1,1,2-trichloro-1,2,2-trifluoroethane (CFC-113). This reliance on specific precursor chemistry means that raw material availability and processing technology are critical bottlenecks or enablers. In China, CTFE prices have been reported in the range of RMB 45,000 to 66,000 per metric ton, with domestic supply increases potentially leading to future declines below RMB 40,000 per ton as new capacity comes online. Understanding these price trends and the underlying production technologies is vital for cost management and pricing strategy.
The Strategic Value of Our Market Research
Given the complexities outlined above, access to precise, forward-looking intelligence is invaluable. Our Worldwide Chlorotrifluoroethylene (CTFE) Market research report is designed to provide exactly that. It goes beyond high-level summaries to offer operational insights that can be immediately applied to strategic planning. Whether you are evaluating entry into new markets, assessing competitor capabilities, or planning capacity investments, this document serves as a foundational resource.
The report details the segmentation splits by type, distinguishing between High Purity Monomer and Technical Grade Monomer, allowing you to understand where value is concentrated. It analyzes the application breakdown to identify which sectors are driving consumption growth. Furthermore, it provides the regional context necessary to optimize logistics and sourcing. By consolidating data on market concentration, key company profiles, and recent developments, we offer a holistic view of the competitive arena. The inclusion of regulatory and raw material analysis ensures that your strategy accounts for external risks and constraints.
Conclusion: Navigating the Future with Confidence
The period from 2026 to 2032 promises to be a defining era for the Chlorotrifluoroethylene market. With a projected compound annual growth rate of 5.1 and a market size trajectory moving toward 1.2 billion, the opportunities are significant, but so are the challenges. Success will depend on the ability to interpret data, anticipate regulatory shifts, and align with the strategic moves of key industry players.
PW Consulting's latest market research offers the depth and clarity required to make informed decisions. We invite you to explore the full report to gain access to the detailed forecasts, specific company profiles, and comprehensive regional analyses that will empower your organization to lead rather than follow. The full intelligence necessary to capitalize on these trends is available through our detailed publication, ensuring your strategy is backed by the most reliable data available in the industry.
For detailed analysis of this topic, please visit the official page: Worldwide Chlorotrifluor Ethylene (CTFE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Litz Wire Market to Hit $1.08B by 2032 at 6.85% CAGR, Asia Pacific Leads
By pmarketresearch, 2026-09-16
Unlocking Growth in the Global Litz Wire Market: A Strategic Imperative for 2026 and Beyond
As industries accelerate their transition toward electrification, miniaturization, and high-frequency connectivity, Litz wire has evolved from a niche winding component into a foundational enabler of next-generation power and signal transmission systems. The worldwide market for this specialized conductor, engineered to mitigate skin effect and proximity losses at elevated frequencies, is experiencing a structural inflection point. For executives, procurement leaders, and strategic planners operating in 2026, understanding the underlying trajectories of demand, supply constraints, and competitive realignments is no longer optional. It is a prerequisite for capital allocation, supplier diversification, and product roadmap execution.
Worldwide Copper Litz Wire Market
The macro trajectory underscores this urgency. Between 2020 and 2025, the global market expanded steadily, reflecting consistent industrial uptake and the gradual mainstreaming of high-frequency power architectures. Looking forward, the forecast horizon from 2026 through 2032 projects a compound annual growth rate of 6.85 percent, translating historical momentum into sustained expansion. Revenue measured in millions of USD is anticipated to cross the seven hundred fifty six million threshold in 2026 and continue its upward march toward the one billion mark by the end of the decade, with further acceleration projected into 2032. These figures are not isolated statistics; they represent a measurable shift in how manufacturers, energy infrastructure developers, and medical device engineers approach conductor selection under tightening efficiency mandates and rising performance expectations.
Why These Numbers Matter for 2026 Decision-Making
The forecast period does not merely describe a continuation of past trends. It captures the convergence of multiple structural drivers that will redefine sourcing strategies, regional footprint planning, and technology investment priorities in the coming fiscal year. Automotive electrification and the rapid scaling of battery management architectures are compressing design cycles, forcing OEMs and Tier suppliers to evaluate conductor geometries that balance thermal resilience with high-frequency current handling. Simultaneously, the renewable energy and power supply sector is reengineering transformer and inverter topologies to meet grid stability requirements, creating sustained demand for precision-wound Litz configurations. Even traditionally conservative verticals such as medical instrumentation and industrial automation are prioritizing signal integrity and power density, pulling specialized wire architectures into mainstream engineering specifications.
For 2026 strategy teams, this environment demands more than superficial market sizing. It requires granular visibility into how demand vectors interact with production constraints, regulatory timelines, and raw material volatility. Decision-makers must assess which applications will absorb capacity first, how pricing architectures will adapt to input cost fluctuations, and where regional supply networks are likely to reconfigure in response to trade policy shifts. The strategic value of a comprehensive market intelligence report lies precisely in its ability to convert broad growth narratives into actionable allocation frameworks, risk mitigation pathways, and partnership evaluation criteria.
Navigating a Rapidly Evolving Competitive Landscape
The market concentration profile reveals a moderately consolidated playing field, where the top three participants collectively account for approximately thirty five percent of aggregate revenue, while the top five expand their combined share to nearly forty eight percent. This structure indicates a mature core of established manufacturers that have invested heavily in process engineering, certification portfolios, and application-specific development, alongside a periphery of agile specialists and regional producers capturing niche demand. The competitive dynamics are increasingly defined not by volume alone, but by technical differentiation, compliance readiness, and the ability to synchronize supply with fast-moving engineering programs.
Several cornerstone players illustrate the spectrum of strategic positioning shaping the market. Elektrisola, headquartered in Stolberg, Germany, maintains its stature as a global leader in enameled Litz wire production, with engineering emphasis on high-frequency inductors, transformers, and wireless charging architectures. Its recent introduction of a high-temperature Litz wire series tailored for EV wireless charging coils, certified to IATF 16949 standards, signals how incumbents are aligning product roadmaps with automotive qualification requirements and thermal stress scenarios. Across the Atlantic, MWS Wire Industries in Westlake, Ohio, continues to specialize in custom strand configurations for RF, medical, and aerospace environments. Its showcase of ultra-fine Litz wire for 5G antenna systems at CWIEME Americas highlights the sector-wide push toward miniaturized, high-efficiency signal conductors in telecommunications infrastructure.
North American manufacturing relevance is further reinforced by New England Wire Technologies, based in Lisbon, New Hampshire, which focuses on high-performance Litz wire for motors, sensors, and power electronics with an explicit emphasis on miniaturization. The firm's recent renewal of AS9100D certification for aerospace-grade production demonstrates how quality management frameworks are becoming competitive differentiators in regulated supply chains. Sam Dong Co., Ltd., operating from Gyeonggi-do, South Korea, occupies a strategically positioned role in Asian automotive ecosystems, producing Litz wire for EV chargers, inductors, and high-power applications. Its execution of a multi-year supply agreement with a major EV battery manufacturer underscores the commercial momentum linking conductor supply directly to electrified mobility scaling.
Worldwide Litz Wire Market
Global operations and high-volume production pathways are represented by Essex Furukawa, with its Fort Wayne, Indiana headquarters and worldwide operational footprint, delivering Litz wire variants for magnet wire applications in renewable energy and industrial transformers. In parallel, Ruiyuan Group, headquartered in Dongguan, China, functions as a high-volume producer serving consumer electronics and power supply markets, reflecting the scale advantages that Asian manufacturing ecosystems bring to cost-sensitive, high-throughput segments. On the application-specialist side, Cooner Wire in Chatsworth, California, provides standard and custom configurations for audio, RF, and medical device applications, while Fujikura Ltd., based in Tokyo, Japan, develops advanced Litz wire solutions for telecommunications and high-frequency components. Collectively, these organizations illustrate how competitive advantage is increasingly constructed through application-specific engineering, certification depth, and geographic supply alignment rather than commodity volume alone.
Forces Reshaping Supply, Cost, and Regional Access
The forward strategy calculus cannot be isolated from the operational realities currently pressing on production economics and trade flows. Raw material volatility remains a central consideration, with copper pricing exhibiting notable year-over-year increases as of early 2026, directly pressuring Litz wire manufacturing costs and prompting suppliers to revisit pricing architectures, alloy substitution evaluations, and inventory buffering strategies. The insulation and enamel supply chain introduces a parallel layer of complexity, as extended lead times for polyimide enamel resins reflect ongoing resin shortages that constrain production scheduling and require procurement teams to plan further ahead with qualified alternative material pathways.
Regulatory and compliance shifts add another dimension of strategic urgency. The updated EU RoHS Directive framework, mandating lower halogen content in wire insulations effective in 2026, compels manufacturers and downstream integrators to validate insulation material compatibility, re-qualify supplier portfolios, and adjust formulation specifications ahead of compliance deadlines. At the same time, geopolitical and trade dynamics are recalibrating cross-border material movement. Export controls related to high-purity copper enablers have tightened for China-bound Litz wire components, prompting regional supply chain actors to evaluate sourcing architectures, inventory localization, and second-source qualification strategies. Concurrently, customs enforcement actions imposing substantial tariffs on certain Chinese Litz wire imports have elevated the cost calculus for buyers relying on trans-Pacific procurement, reinforcing the case for regional supplier diversification and localized assembly considerations.
These intersecting forces are not isolated disruptions. They form a compound environment where cost management, regulatory readiness, and geographic access must be modeled together. Firms that continue to treat Litz wire procurement as a transactional purchasing function will face mounting exposure to lead-time variability, compliance friction, and margin compression. Those that embed the market's structural dynamics into supplier evaluation matrices, engineering specification reviews, and regional capacity planning will be better positioned to absorb volatility while preserving performance and schedule integrity.
What This Study Delivers for Strategic Teams
A rigorous market assessment must move beyond headline sizing and concentration ratios to provide the operational scaffolding required for 2026 execution. The research framework is designed to equip decision-makers with a layered view of the market, integrating historical performance baselines, forward forecast horizons, and structural segmentation that clarifies where demand is accumulating and how different product architectures are positioned. The analysis maps the interplay between conductor geometry preferences, application-driven qualification requirements, and regional demand profiles, while maintaining a disciplined focus on the variables that most directly influence sourcing, investment, and partnership strategy.
The study examines competitive positioning by synthesizing company profiles, technological emphasis, production specialization, and recent commercial milestones, enabling readers to benchmark incumbents, assess emerging entrants, and identify capability gaps that may present partnership or acquisition opportunities. It contextualizes market movements within the broader ecosystem of material availability, regulatory timelines, and trade policy evolution, offering a framework for scenario planning around cost behavior, supply continuity, and compliance adaptation. The deliverable structure supports multiple internal use cases, including procurement strategy refinement, R&D specification alignment, regional market entry evaluation, and capital allocation prioritization for high-growth application segments.
Importantly, the research preserves the granularity required for defensible planning without exposing the market to oversimplified narratives. Regional demand distributions, application-level revenue architecture, and product-type market shares are analyzed in depth to reveal the relative weight of each segment, the pacing of adoption across use cases, and the structural implications for manufacturing capacity and supplier service portfolios. This level of detail is essential for teams that need to determine where to concentrate negotiation leverage, which applications warrant accelerated engineering support, and how to sequence supply commitments in a market where timing differentials can translate directly into competitive advantage or exposure.
Positioning for the Next Wave of Electrification and High-Frequency Integration
The Litz wire market in 2026 is defined by a rare alignment of steady structural growth, accelerating application diversification, and a supply environment that rewards preparedness. The combination of a sustained growth trajectory, a moderately consolidated competitive base, and an ecosystem shaped by material constraints, regulatory updates, and trade realignments creates both opportunity and complexity. Organizations that approach this landscape with disciplined market intelligence will be able to prioritize the right applications, qualify the right partners, and build sourcing architectures that can withstand short-term volatility while capturing long-term demand.
The full Worldwide Litz Wire Market research study expands each of these dimensions into a comprehensive, decision-ready intelligence package. It provides the segmented market architecture, regional and application-level analysis, competitive profiling, and scenario-oriented context necessary to translate broad industry momentum into concrete strategic action. For executives preparing capital plans, procurement roadmaps, and technology investment decisions for the 2026 to 2032 horizon, the complete study offers the depth, structure, and current intelligence required to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: Worldwide Litz Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Berberine HCl API Market Hits $81.5M in 2025, Projected to Reach $141M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Decision Cycle: Inside the Global Berberine Hydrochloride API Market
The global berberine hydrochloride API market has entered a decisive expansion phase. In 2025, the worldwide market reached an estimated revenue of USD 81.5 million, building on a robust historical trajectory that saw the space grow from USD 55.08 million in 2020. Forecasts for the 2026 to 2032 window project the market to advance to USD 85.86 million in 2026 and further to USD 141.04 million by the close of the forecast period, supported by a compound annual growth rate of 8.15 percent. This growth narrative reflects more than steady volume increases. It signals a structural transition in how manufacturers, formulators, and procurement leaders source, qualify, and deploy berberine hydrochloride across dietary supplements, pharmaceutical formulations, and animal healthcare segments.
Worldwide Berberine Hydrochloride API Market
For executives setting strategy in 2026, these headline figures are only the starting point. The real decision value lies in understanding where growth concentrates, which sourcing pathways carry the least operational and regulatory friction, and how the competitive field is consolidating around vertically integrated supply chains. Our comprehensive Worldwide Berberine Hydrochloride API Market study translates macro momentum into actionable intelligence, giving sourcing directors, R&D leads, and commercial planners the clarity required to navigate pricing volatility, capacity constraints, and evolving pharmacopeial expectations.
This research is designed as a decision-support instrument rather than a static market summary. The analysis covers the full value chain, from botanical feedstock availability through extraction, crystallization, and API purification, to final deployment in regulated and non-regulated end-use channels. By anchoring historical data from 2020 through the base year of 2025 against forward projections through 2032, the report establishes a credible baseline for scenario planning. Readers gain visibility into the demand rhythms that shape quarterly procurement, the regional manufacturing footprint that influences lead times, and the quality infrastructure that determines market access.
A central feature of the study is its operational orientation. Rather than presenting undifferentiated growth statistics, the report decomposes demand and supply drivers into practical dimensions that procurement and production teams can act upon. The analysis examines how botanical inputs such as Coptis chinensis rhizomes, Phellodendron amurense bark, and various Berberis species roots and bark shape cost structures and supply resilience. It also maps the manufacturing clusters that dominate global output, with particular attention to Chinese provinces that benefit from proximity to raw material sources and vertically integrated processing capabilities. This structural perspective helps readers anticipate where capacity is likely to expand, where bottlenecks may emerge, and which sourcing geographies align with their quality, lead-time, and cost targets.
The report also addresses the regulatory and quality environment that governs market participation. Pharmaceutical-grade berberine hydrochloride API must satisfy demanding purity specifications, typically ranging from 98.0 percent to 105 percent by HPLC, alongside strict heavy metal limits and compliance with recognized pharmacopeial standards under GMP conditions. Manufacturers operating in this space increasingly provide DMF documentation, third-party testing for heavy metals and microbial limits, and certification frameworks such as cGMP, ISO 9001, and WHO-GMP. By integrating these requirements into the market assessment, the study clarifies which suppliers are positioned for regulated-market exposure and which production models are best suited to supplement and nutraceutical channels.
Competitive dynamics form another essential pillar of the analysis. The industry is characterized by a moderately concentrated field in which leading players collectively hold a significant share of global capacity, while a broader base of specialized producers competes on purity, extraction capability, and export readiness. The report profiles organizations across India and China that have established berberine hydrochloride API as part of their bulk drug, phytochemical, and herbal extraction portfolios. These include manufacturers operating under ISO 9001:2015, cGMP, and WHO-GMP certified facilities, as well as producers focused on high-purity bulk output with pharmaceutical and nutraceutical applications. The competitive review examines how these firms differentiate through vertically integrated supply from raw plant materials, advanced extraction and crystallization processes, and readiness to serve regulated international markets.
Metformin Hydrochloride Market
The study further evaluates regional dynamics without reducing the market to a shallow geographic tally. Instead, it contextualizes how major production clusters, export flows, and local raw material access influence pricing, availability, and risk exposure for global buyers. This regional lens helps decision-makers understand why certain sourcing hubs command disproportionate share, how logistics and regulatory alignment shape channel strategy, and where diversification may reduce dependency on single-origin supply. Insights into market concentration and the balance between dominant suppliers and niche producers give procurement leaders a clearer picture of negotiation leverage, alternate sourcing options, and long-term supplier viability.
Beyond structural description, the report connects market data to practical planning use cases. For commercial teams, the analysis supports market-entry prioritization by identifying the application channels and geographic corridors with the strongest growth alignment. For supply chain leaders, it informs dual-sourcing strategies, inventory buffering, and qualification pathways for alternative API sources. For R&D and product development groups, the report clarifies purity and documentation thresholds that affect formulation choices and time-to-market in regulated contexts. By bridging historical performance, forward forecasts, and operational requirements, the study equips multiple functions with a shared evidentiary base for 2026 planning.
The strategic relevance of this research is amplified by the pace of change across the berberine hydrochloride API ecosystem. Demand continues to be shaped by expanding supplement adoption, ongoing pharmaceutical interest in gastrointestinal and metabolic indications, and growing animal healthcare applications. At the same time, supply-side realities, including botanical harvest variability, extraction efficiency, and compliance with pharmacopeial expectations, create a market where informed sourcing decisions have direct financial and quality consequences. Executives who rely on aggregate market figures alone risk over-simplifying a landscape defined by feedstock dependence, certification intensity, and geographically uneven capacity. This report is built to close that gap.
Readers who engage with the full study will find a detailed segmentation framework, comprehensive competitor profiling, regional demand and supply balances, and forward-looking scenario analysis calibrated to the 2026 to 2032 horizon. The report connects revenue trajectories to underlying drivers, translating the projected expansion from the 2026 estimate to the 2032 endpoint into a coherent narrative about capacity additions, channel shifts, and competitive realignment. It also addresses the operational realities that determine whether growth is accessible to a given organization, including regulatory documentation, quality system maturity, and the ability to secure consistent botanical feedstocks.
The publication is intended for a broad strategic audience. Procurement and supply chain executives can use the analysis to validate sourcing geography choices, assess supplier qualification pathways, and stress-test procurement plans against capacity and compliance variables. Commercial and business development teams can leverage the market outlook to prioritize product launches, evaluate channel opportunities, and calibrate revenue assumptions for berberine-based offerings. R&D, quality, and regulatory stakeholders can reference the report’s documentation and purity expectations to align development programs with market-access requirements. Investment and corporate strategy teams can use the competitive and regional mapping to understand consolidation patterns and identify where value is likely to accrue over the forecast period.
As the market moves from the 2025 base year into the 2026 decision cycle, the margin between informed and reactive planning will widen. The projected trajectory toward USD 141.04 million by 2032 suggests that berberine hydrochloride API will remain a strategically important ingredient class, but realizing value from that growth requires more than tracking top-line numbers. It demands a clear view of where supply is generated, how quality and compliance expectations vary by channel, which competitors are positioned to scale, and how regional dynamics influence cost and continuity. Our Worldwide Berberine Hydrochloride API Market research is structured to provide precisely that view.
The full report extends well beyond the macro outline presented here. It delivers a granular segmentation analysis, detailed competitor evaluations, regional demand and supply mappings, and forward scenarios that connect volume growth with the operational conditions required to capture it. For organizations preparing sourcing strategies, launch plans, or investment assessments in 2026, the complete dataset and interpretive commentary offer the depth necessary to act with confidence. To access the full market intelligence, including the detailed segmentation splits, competitive profiles, and forward projections that underpin this strategic overview, visit the source page and download the complete research.
For detailed analysis of this topic, please visit the official page: Worldwide Berberine Hydrochloride API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com