

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Aesthetic Phototherapy Lamp Market Hits $645.5M in 2025, Poised for 8.75% CAGR Through 2032

Strategic Intelligence: Navigating the Worldwide Aesthetic Phototherapy Lamps Market in 2026
The global aesthetic phototherapy lamps market stands at a pivotal inflection point as industry stakeholders transition from the 2020-2025 historical growth cycle into the 2026-2032 forecast period. Driven by a compound annual growth rate of 8.75 percent, the sector is projected to expand from a 2025 baseline of USD 645.5 million to an estimated USD 1.16 billion by 2032. This trajectory reflects a structural shift in how aesthetic dermatology, clinical skincare, and at-home wellness converge around evidence-based light-based interventions. For executives, investors, and product strategists, 2026 represents the year when regulatory clarity, reimbursement pathway maturation, and competitive consolidation will decisively shape market entry, portfolio positioning, and revenue forecasting. Our latest Worldwide Aesthetic Phototherapy Lamps Market research is designed to convert this momentum into executable intelligence.
Macro Trajectory and the 2026 Decision Window
The five-year historical record from 2020 through 2025 demonstrates consistent expansion, moving from USD 425.1 million to USD 594.85 million before reaching the 2025 anchor of USD 645.5 million. The forward projection series maps a steady climb: USD 701.98 million in 2026, USD 763.4 million in 2027, USD 830.2 million in 2028, USD 902.84 million in 2029, USD 981.84 million in 2030, USD 1.07 billion in 2031, and USD 1.16 billion in 2032. While aggregate figures establish the scale of opportunity, the strategic value of this research lies in unpacking the forces that will redistribute share, pricing power, and margin profiles across light source categories, application verticals, end-user channels, and regional ecosystems. Companies that treat 2026 as a planning horizon rather than a passive transition will be better positioned to align capital allocation, regulatory filings, and channel strategy with the market’s actual architecture.
What the Report Delivers: Actionable Scoping for Product, Pricing, and Channel Strategy
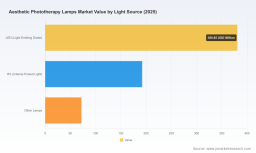
This study is structured to support operational decision-making rather than high-level observation. It maps the market across multiple dimensions, providing a granular view of how demand concentrates by technology platform, clinical and consumer application, procurement environment, and geography. The segmentation analysis examines light source dynamics across LED, IPL, and other lamp technologies, clarifying where performance characteristics, total cost of ownership, and regulatory status create durable advantages or exposure. The application lens dissects demand patterns across skin rejuvenation, acne treatment, pigmentation treatment, and wound healing, highlighting how clinical indications, consumer adoption curves, and service models diverge by use case. The end-user framework evaluates medical clinics, beauty salons, and home care settings, exposing the distinct purchasing behaviors, service expectations, and price sensitivity that define each channel.
Beyond segmentation, the report addresses competitive concentration and ecosystem structure. With the top three players accounting for approximately 42.15 percent of market value and the top five reaching roughly 58.8 percent, the landscape reflects meaningful incumbency advantages alongside persistent entry points in niche indications, regional channels, and consumer-grade devices. The study integrates company profiles, capability assessments, and recent development tracking to help strategists benchmark positioning, identify partnership targets, and anticipate where capacity expansion, product refreshes, or regulatory filings may alter local supply dynamics.
Regulatory and Reimbursement Context: Why 2026 Is a Policy-Sensitive Year
Aesthetic phototherapy is increasingly governed by a layered regulatory and reimbursement environment, and 2026 is a year in which several structural developments will influence commercial planning. Aesthetic LED phototherapy devices intended for wrinkle reduction and acne treatment are classified as Class II under 21 CFR 878.4810 with product codes including OHS, requiring 510(k) clearance for U.S. marketing. This clearance pathway has become a strategic gatekeeper, particularly as manufacturers pursue over-the-counter and at-home indications. Recent FDA 510(k) clearances illustrate the pace of this activity: in December 2025, Shenzhen Saidi Light Therapy Technology received clearance for its LED Light Therapy Face Mask series, including FM60X, FM80, and FM100X variants for facial wrinkles and mild to moderate inflammatory acne. In June 2025, Shenzhen Kaiyan Medical Equipment, the manufacturer behind CurrentBody Skin, secured clearance for the CurrentBody Skin LED Light Therapy Mask Series 2, MK-90H, for over-the-counter full-face wrinkle treatment. In February 2025, Xuzhou Kernel Medical Equipment obtained clearance for 308nm excimer phototherapy device models for psoriasis and vitiligo, which are relevant in aesthetic dermatology contexts. In November 2024, Shenzhen Walton Technology received clearance for LED Light Therapy Machine models G1, G3, G4, and G6 for over-the-counter aesthetic use in wrinkle treatment and acne.
These clearances are not isolated product events; they signal broader pathway trends. The American Medical Association activated CPT Category III Code 0936T effective January 1, 2025, for photobiomodulation therapy to support data collection toward potential future Medicare reimbursement. Simultaneously, revised CPT code descriptors for excimer laser procedures, CPT 96920, 96921, and 96922, are scheduled to become effective January 1, 2027, expanding reimbursable indications to include additional inflammatory and autoimmune skin conditions such as vitiligo, atopic dermatitis, and alopecia areata. In parallel, national CPT code reimbursement rates for excimer laser treatments in 2025 ranged from USD 137 to USD 183 per treatment depending on treated area, spanning under 250 square centimeters to over 500 square centimeters. Together, these developments shape the economics of clinical adoption, the attractiveness of medical-channel procurement, and the incentive structure for device manufacturers pursuing reimbursable indications.
Procurement realities further complicate the commercial picture. Hospital and institutional purchasing for phototherapy equipment is frequently executed as structured value-based purchases bundled with accessories, installation, and service, reflecting capital expenditure constraints in public tenders. This bundling behavior influences not only upfront pricing but also service-level expectations, lifecycle support requirements, and the competitive leverage of manufacturers that can deliver integrated deployment models rather than standalone hardware.
Competitive Landscape and Where Share Is Being Won or Lost
The competitive set in aesthetic phototherapy spans dermatologic device leaders, specialty lamp manufacturers, consumer-grade wearable and mask developers, and integrated energy-based aesthetic platform companies. Beijing Sincoheren offers dermatologic phototherapy lamps including LUMERA for aesthetic skin treatments. Kernel Medical Equipment, based in Xuzhou, Jiangsu, manufactures aesthetic and dermatologic phototherapy lamps and excimer devices for skin rejuvenation and treatment. LightSources and LightTech, headquartered in Orange, Connecticut, specialize in fluorescent and UV specialty light therapy lamps for medical and aesthetic phototherapy applications. Lumitex, based in Strongsville, Ohio, provides therapeutic lighting solutions and light therapy components for medical device manufacturers in aesthetic applications. ProReset, operating across Germany and Europe, offers aesthetic phototherapy lamps such as ProRed, Lumina, and Eva Led for skin rejuvenation, blood circulation, and muscle recovery. BioPhotas, Inc., in the United States, develops the Celluma series of biophotonic LED devices for aesthetic anti-aging, acne, and skin rejuvenation treatments. Shenzhen Idea Light Limited, also known as IDEATHERAPY, manufactures red light therapy panels and wearable LED phototherapy devices for aesthetic skin treatments. CurrentBody, manufactured by Shenzhen Kaiyan Medical Equipment, provides LED light therapy masks such as Series 2 for at-home aesthetic treatment of facial wrinkles. LightStim offers LED light therapy devices integrated in aesthetic systems for skin rejuvenation and acne treatment. Alma Lasers develops energy-based aesthetic devices including phototherapy and light-based systems for skin treatments. Lumenis provides laser and light-based aesthetic solutions with phototherapy capabilities for skin rejuvenation. Candela Medical, formerly Syneron Candela, offers aesthetic light and laser systems for phototherapy applications in dermatology and skin rejuvenation. Cutera manufactures aesthetic laser and light devices including phototherapy options for skin treatments. Fotona combines laser and light-based aesthetic solutions for precision skin rejuvenation and phototherapy. The Daavlin Company specializes in phototherapy lamps and units for dermatologic and aesthetic skin treatments. National Biological Corporation provides phototherapy lamps for aesthetic medicine and dermatologic applications. Herbert Waldmann GmbH & Co. KG manufactures phototherapy lamps and lighting systems used in aesthetic and medical treatments.
This diversity of players reflects a market in which technology leadership, regulatory access, distribution reach, and brand positioning all matter. Some firms compete primarily through clinical-grade performance and reimbursement-adjacent indications; others compete through consumer usability, aesthetics, and at-home convenience. The report evaluates where these strategies intersect, where overlap creates pricing pressure, and where differentiation remains defensible. It also tracks how recent FDA clearances and product introductions may alter regional supply, channel availability, and benchmark specifications for downstream procurement teams.
Segmentation Signals That Matter for 2026 Planning
While aggregate market size and growth rates set the overall context, the operational value of this research lies in its ability to help teams interpret where demand is forming and how it will translate into procurement, sales, and investment decisions. Light source selection, for example, is not merely a technical preference; it affects regulatory classification, treatment protocols, consumables and service economics, and the credibility of clinical claims. Application focus shapes channel strategy, because skin rejuvenation, acne treatment, pigmentation treatment, and wound healing each carry distinct practitioner adoption patterns, consumer expectations, and reimbursement or self-pay dynamics. End-user channel mix is equally critical, since medical clinics, beauty salons, and home care settings differ in purchasing cycles, training requirements, service contracts, and price elasticity.
The regional dimension further complicates planning. Demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, but distribution is not uniform in either volume or strategic significance. Local regulatory environments, clinical practice norms, aesthetic service infrastructure, and procurement models influence how quickly new products are adopted and how aggressively pricing is contested. Rather than presenting isolated percentage splits, the study frames regional analysis as a set of operational considerations: where channel access is mature, where regulatory clearance creates an entry barrier or an opportunity, and where procurement bundling and service expectations alter the economics of market participation.
How to Use This Research for 2026 Decision-Making
The report is intended to support a range of strategic actions. For product and R&D leaders, it provides context on where light source and application segmentation create the strongest case for investment, iteration, or portfolio pruning. For commercial and market-access teams, it clarifies how regulatory classification, 510(k) activity, CPT coding developments, and reimbursement ranges influence the viability of clinical versus consumer positioning. For corporate development and investor relations, it frames competitive concentration, company-level capabilities, and recent clearance activity in a way that supports benchmarking, partnership identification, and risk assessment. For regional and channel strategists, it connects segmentation and dynamics to practical questions about where to prioritize go-to-market resources, how to structure service and installation offerings, and which procurement environments demand bundled value propositions.
Crucially, the study is designed to be read as a decision framework, not a static snapshot. The 2026-2032 forecast horizon is long enough to matter for capital planning and product roadmaps, yet near enough that the assumptions behind it can be tested against live regulatory filings, procurement behavior, and competitor moves. By linking historical performance, forward projections, segmentation logic, and regulatory context, the report helps organizations avoid plans that are either too optimistic about adoption speed or too conservative about structural growth.
Worldwide Aesthetic Phototherapy Lamps Market
Why This Study Matters Now
The aesthetic phototherapy lamps market is expanding, but expansion alone does not create advantage. Advantage comes from understanding where growth is concentrated, which regulatory and reimbursement shifts alter commercial logic, and how competitive intensity differs across light sources, applications, channels, and regions. With an 8.75 percent CAGR driving the market from USD 645.5 million in 2025 toward USD 1.16 billion in 2032, the cost of misreading segmentation or timing is rising. The Worldwide Aesthetic Phototherapy Lamps Market research gives decision-makers the structured intelligence needed to calibrate strategy for 2026 and beyond.
To access the complete segmentation detail, competitive benchmarks, regional analysis, and forward forecast tables that support these conclusions, we invite you to explore the full report. The underlying data, scenario logic, and company-level profiles are available in the complete publication, where they can be used directly for internal planning, investment review, and market-entry assessment.
Aesthetic Devices Market
For detailed analysis of this topic, please visit the official page: Worldwide Aesthetic Phototherapy Lamps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com