

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CW DFB Laser Diode Market Hits $920M in 2025, Projects 8.15% CAGR Through 2032

Navigating the High-Power CW DFB Laser Diode Market: Strategic Intelligence for 2026 and Beyond
The global landscape for Continuous Wave Distributed Feedback laser diodes is undergoing a definitive transformation. As enterprises anchor their technological roadmaps for the 2026 fiscal year, the capacity to secure reliable, high-performance optical sources has shifted from a technical preference to a strategic imperative. This market intelligence briefing serves as the executive introduction to the comprehensive CW DFB Laser Diode Market research report recently published by PW Consulting. Our analysis is designed to equip leadership teams with the granular visibility required to navigate supply chain constraints, competitive pressures, and shifting demand vectors across the optical communication and sensing sectors.
The semiconductor sector focused on high-power CW DFB architectures is no longer niche. The integration of silicon photonics with advanced transceiver architectures has created a surge in demand that is reshaping vendor priorities and capacity planning across the globe. This report provides a detailed examination of the revenue trajectories, regional dynamics, and competitive maneuvers that will define the market through the end of the decade. By exploring the following insights, stakeholders can better align their procurement strategies, investment decisions, and partnership models with the realities of a rapidly expanding ecosystem.
Market Trajectory and Macro Growth Dynamics
The baseline for 2026 operational planning is anchored in a sustained compound annual growth rate of approximately 8.15 percent measured in USD millions. According to our forecast period spanning from 2026 through 2032, the market value is projected to expand significantly from its established 2025 baseline. This trajectory reflects a consistent upward momentum that began accelerating in the early 2020s and has intensified through recent historical data points. The global market size reached roughly 920 million USD in the base year, with projections indicating a steady climb to exceed 1.5 billion USD by 2032.
Worldwide High Power CW Laser Market
This growth profile is not merely a function of volume expansion. It is deeply intertwined with engineering shifts in transceiver technology, particularly the migration toward 800G and 1.6T architectures within AI-driven data center environments. The demand for uncooled operation capabilities at elevated temperatures, alongside the push for higher power outputs to support co-packaged optics, has fundamentally altered the performance thresholds required from CW DFB components. Organizations evaluating market entry or expansion must account for these technical benchmarks, as they directly influence pricing power, qualification cycles, and long-term vendor retention.
The historical data series from 2020 through 2025 underscores a compounding effect. Each successive year has delivered incremental gains that signal structural rather than cyclical growth. For decision makers in 2026, this means that legacy assumptions regarding demand volatility must be recalibrated. The market is consolidating around high-power, high-reliability specifications that favor manufacturers with mature epitaxial processes and scalable packaging capabilities. Strategic planning should therefore prioritize partnerships and supply agreements that lock in capacity ahead of the projected inflection points across the forecast horizon.
Competitive Landscape and Key Player Intelligence
The competitive environment within the CW DFB segment is characterized by a moderate degree of concentration. Our analysis indicates a consolidated market structure where a small group of dominant players commands a substantial share of global revenue. The top three participants collectively hold approximately 48.5 percent of the market, while the top five entities extend their combined influence to roughly 62.2 percent. This concentration level carries important implications for procurement strategy, negotiation leverage, and risk diversification.
Several industry leaders have defined the current frontier through aggressive product development and targeted capacity initiatives. MACOM, headquartered in Lowell, Massachusetts, has reinforced its position with high-power CW DFB diode offerings designed for uncooled operation at temperatures up to 85 degrees Celsius. Their patented etched facet technology supports datacom and silicon photonics applications, with power levels such as 75mW and 100mW at 1310nm. These specifications address the growing need for thermal resilience and simplified thermal management in dense transceiver modules.
Coherent Corp., based in Saxonburg, Pennsylvania, continues to drive performance benchmarks with high-efficiency CW DFB chips optimized for next-generation silicon photonics. Their portfolio includes 70mW uncooled 1310nm variants and higher power configurations for CWDM4, specifically tailored for 800G and 1.6T transceiver ecosystems. The company has also advanced its sampling activities, introducing low-noise 400mW CW lasers on a BH DFB platform designed for co-packaged optics and silicon photonics at 1311nm, signaling a clear focus on the AI data center transition.
Broadcom, operating from San Jose, California, supplies edge-emitting CW DFB diode chips including the 247F series, which delivers up to 100mW uncooled performance across CWDM wavelengths. These components are positioned for silicon photonics and external modulator applications, reinforcing the company's role in high-volume transceiver supply chains. Meanwhile, Furukawa Electric in Tokyo has undertaken a significant capacity expansion initiative. The manufacturer produces 70mW and 100mW high-output CW DFB diode chips for silicon photonics and data center transceivers, and has announced a new manufacturing plant expected to increase capacity by over 500 percent by 2028. This move reflects the broader supply chain reality that InP-based epitaxial wafer processing and chip fabrication expansion are critical to absorbing surging demand for high-output CW DFB components.
Regional and specialized players further diversify the competitive field. Innolume GmbH, located in Dortmund, Germany, specializes in high-power quantum dot-based CW DFB lasers delivering 70mW to 400mW-plus in the O-band, with uncooled options for datacom, silicon photonics, and sensing applications. DenseLight Semiconductors in Singapore offers InP-based high-power CW DFB lasers ranging from 50mW to 70mW-plus, with customization options for datacom, telecom, and silicon photonics platforms. Eblana Photonics, based in Dublin, Ireland, provides single-frequency DFB-like laser diodes using discrete-mode technology across NIR and MIR bands for sensing, LIDAR, and telecom applications. SemiNex Corporation in Peabody, Massachusetts, delivers high-power CW DFB lasers and semiconductor optical amplifiers optimized for AI data center silicon photonics integration in both O-band and C-band configurations.
CW DFB Laser Diode Market
Additional contributors include Frankfurt Laser Company in Friedrichsdorf, Germany, which supplies DFB wavelength-stabilized laser diodes spanning 760nm to 3640nm for various application domains, and RPMC Lasers in O'Fallon, Missouri, which distributes and supports a broad range of DFB laser diodes including CW options from multiple manufacturers for precision applications. Recent market activity further illustrates the pace of change. In September 2025, Everbright Photonics introduced a 200mW uncooled CW DFB optical communication chip emphasizing high power and low consumption. Also in April 2025, HieFo launched high-efficiency CW DFB InP lasers for silicon photonics transceivers supporting uncooled O-band operation. By December 2025, MTC achieved small-batch shipment of DFB photonic chips and announced plans for CW light sources in 2026, indicating emerging competition and broadening supply options.
Segmentation, Applications, and Wavelength Dynamics
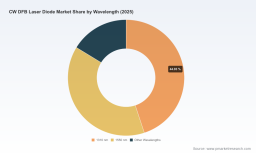
The revenue composition of the CW DFB market is shaped by distinct segmentation vectors that illuminate where growth capital and engineering attention are concentrated. Wavelength segmentation reveals a clear hierarchy of performance requirements. The 1310nm band commands the largest share of market value, followed by the 1550nm band, with other wavelengths comprising a smaller but strategically relevant portion. This distribution aligns with the optical communication industry's reliance on O-band for silicon photonics transceivers and C-band for extended reach and dense wavelength division multiplexing applications. Understanding these wavelength preferences is essential for vendors calibrating product roadmaps and for buyers evaluating component availability across different transceiver architectures.
Application segmentation further delineates the revenue drivers. Optical communication represents the dominant application category, reflecting the intense demand from data center interconnects, fiber optic transceivers, and silicon photonics integration. Sensing and LiDAR applications form a substantial secondary segment, leveraging the precision and stability of CW DFB diodes for range-finding, environmental monitoring, and advanced detection systems. Medical and industrial applications occupy a meaningful share as well, where the reliability and single-frequency characteristics of DFB architectures enable specialized instrumentation, material processing, and diagnostic tools. Each application vertical carries distinct qualification requirements, volume profiles, and price sensitivities that must be factored into market engagement strategies.
Regional segmentation underscores the geographic concentration of demand and manufacturing capability. Asia Pacific accounts for the largest revenue share, driven by the density of data center construction, silicon photonics fabrication infrastructure, and transceiver assembly capacity. North America follows as a significant contributor, supported by advanced transceiver developers, silicon photonics innovators, and AI infrastructure investments. Europe maintains a steady presence with a focus on specialized manufacturing, sensing applications, and telecom equipment integration. Latin America and the Middle East and Africa together represent smaller but emerging participation, reflecting gradual infrastructure development and niche deployment opportunities. These regional distributions inform supply chain planning, logistics optimization, and market entry timing for organizations operating across multiple geographies.
Technology Drivers, Standards, and Supply Chain Considerations
The performance expectations for CW DFB laser diodes in 2026 and beyond are governed by rigorous technical and regulatory frameworks. Data center transceiver deployments increasingly require compliance with Telcordia GR-468 reliability qualifications, particularly for non-hermetic uncooled operation at temperatures up to 85 degrees Celsius. This standard shapes component design, testing protocols, and lifecycle validation, creating a competitive filter that favors manufacturers with mature qualification pipelines and proven field reliability. The alignment of product specifications with these reliability benchmarks is no longer optional; it is a prerequisite for inclusion in high-volume transceiver supply chains.
Beyond compliance, the industry is propelled by macro trends tied to the rapid expansion of AI-driven data centers. The demand for high-power CW DFB lasers is directly linked to the evolution of 800G to 1.6T silicon photonics transceivers and the emergence of co-packaged optics architectures. These architectures demand higher optical output power, improved thermal stability, and tighter wavelength control to maintain signal integrity at higher data rates. Suppliers that can deliver uncooled high-power solutions while meeting spectral precision requirements are positioned to capture value in this expanding design space. The interplay between transceiver roadmaps and laser diode performance creates a feedback loop where advances in one domain accelerate requirements in the other.
Supply chain resilience is another critical dimension. The expansion of InP-based epitaxial wafer processing and chip fabrication capacity is essential to meet the surging demand for high-output CW DFB chips. Recent announcements of new manufacturing plants and capacity increases highlight the industry's recognition that wafer availability, epitaxial quality, and chip yield will become binding constraints if not proactively addressed. Procurement teams must evaluate supplier capacity roadmaps, wafer sourcing strategies, and packaging throughput to mitigate the risk of allocation bottlenecks. Additionally, the diversification of product offerings across O-band, C-band, and broader wavelength ranges allows organizations to hedge against single-point supply vulnerabilities while aligning with specific transceiver design requirements.
Strategic Takeaways for 2026 Decision Makers
The CW DFB Laser Diode Market research report provides a structured foundation for translating market intelligence into actionable strategy. For executive teams planning 2026 operations, several priorities emerge from the analysis. First, the growth trajectory and concentration profile suggest that long-term supply agreements and dual-sourcing strategies will be increasingly valuable as leading vendors scale capacity and tighten allocation for high-demand configurations. Second, the emphasis on uncooled high-power performance and GR-468 compliance indicates that qualification speed and reliability documentation will be decisive factors in supplier selection. Third, the segmentation data reveals that optical communication remains the primary revenue engine, while sensing, LiDAR, medical, and industrial applications offer diversification pathways that can buffer against transceiver cycle volatility.
The report also details competitive benchmarking, product specification landscapes, regional revenue distributions, and application-specific demand patterns. It examines the impact of recent product launches, capacity expansions, and sampling initiatives on market positioning and pricing dynamics. Readers gain access to a comprehensive assessment of how leading companies are aligning their technologies with silicon photonics integration, co-packaged optics, and AI data center requirements. The analysis further explores the implications of supply chain capacity investments for lead times, cost structures, and availability across different wavelength and power tiers.
By integrating these insights, organizations can refine their technology roadmaps, optimize procurement portfolios, and identify partnership opportunities that align with the market's structural evolution. The report is designed to support cross-functional decision making across engineering, procurement, strategy, and finance teams, ensuring that investments and commitments reflect the most current market realities. For stakeholders seeking the complete dataset, segmentation breakdowns, company profiles, and forecast models, the full research publication provides the depth required to convert intelligence into execution.
The CW DFB Laser Diode Market research represents a timely resource for navigating a sector defined by rapid technological change and expanding demand. As 2026 unfolds, the ability to anticipate capacity shifts, specification trends, and competitive moves will distinguish organizations that secure supply resilience from those that react to constraints. PW Consulting's analysis offers the strategic clarity needed to make those decisions with confidence, grounded in rigorous market data and informed by the latest industry developments.
For detailed analysis of this topic, please visit the official page: CW DFB Laser Diode Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com