

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Pressure-resistant Sensor Market to Hit $3.87B by 2032, Growing at 6.82% CAGR

Navigating the Depths: Strategic Intelligence for the 2026 Pressure-Resistant Sensor Landscape
The Imperative for Precision in High-Stake Environments
As industrial and medical technologies push into increasingly hostile environments, the demand for reliable pressure-resistant sensor solutions has transitioned from a niche requirement to a critical infrastructure necessity. From the crushing depths of the ocean to the precision-driven chambers of medical catheters, these sensors serve as the nerve endings of modern automation and healthcare. For executives and strategic planners navigating the 2026 fiscal year, understanding the trajectory of this market is not merely an academic exercise but a fundamental component of risk management and growth planning. The Worldwide Pressure-resistant Sensor Market is undergoing a period of significant transformation, driven by technological maturation, regulatory shifts, and expanding application scopes that demand higher fidelity and durability.
This market research report is designed to cut through the noise, offering a clear-eyed view of where value is being created and where capital should be allocated. The analysis covers a comprehensive forecast period extending to 2032, building upon a robust historical dataset from 2020 through 2025. By examining the historical revenue trends alongside forward-looking projections, stakeholders can identify inflection points that will define competitive advantage in the coming years. The market has demonstrated resilience and steady expansion, with overall revenue figures showing a consistent upward trajectory. Starting from a baseline of approximately 1.76 billion USD in 2020, the sector has grown steadily, reaching an estimated 2.44 billion USD by 2025. This growth underscores the increasing reliance on precision sensing across diverse heavy-duty and delicate diagnostic applications.
Looking ahead, the forecast indicates a sustained growth momentum with a Compound Annual Growth Rate (CAGR) of 6.82 percent. This rate suggests that the market is not merely expanding but evolving, with revenue projections climbing toward 3.87 billion USD by the end of the forecast period in 2032. For investors and corporate strategists, this trajectory signals a maturing industry where early movers in specific technology segments or geographic expansions stand to capture disproportionate value. However, raw growth numbers tell only half the story. The true strategic insight lies in understanding the segmentation dynamics, the competitive concentration, and the external regulatory forces that will shape profitability within this growth envelope.
Market Segmentation and Revenue Dynamics
A granular understanding of how revenue is distributed across different types, applications, and regions is essential for targeted strategy formulation. The report dissects the market into distinct categories to reveal where the primary drivers of value reside. Currently, the Piezoresistive Sensors segment represents a significant share of the revenue mix, reflecting its widespread adoption due to cost-effectiveness and proven reliability in varied conditions. Complementing this, Thin-film Strain Gauge Sensors maintain a strong presence, particularly where higher precision and temperature stability are required. Meanwhile, the Fiber Optic Sensors and Capacitive Pressure Sensors segments, while smaller in absolute terms, represent high-growth niches driven by specific needs for electromagnetic immunity and high-sensitivity measurements in specialized environments.
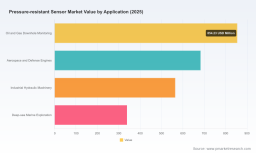
On the application front, the demand landscape is diversified but heavily weighted toward sectors where failure is not an option. Oil and Gas Downhole Monitoring continues to be a substantial revenue contributor, fueled by the need for accurate pressure data in extreme subsurface conditions. Aerospace and Defense Engines also command a significant portion of the market, driven by stringent safety requirements and the ongoing modernization of propulsion systems. Industrial Hydraulic Machinery remains a steady pillar of demand, while Deep-sea Marine Exploration represents an emerging frontier with growing investment in underwater infrastructure and resource exploration. The report provides detailed analysis on how these application verticals interact with technological types, offering insights into cross-segments opportunities that are often overlooked in broader industry surveys.
Geographic distribution of revenue reveals a complex landscape of regional strengths and strategic entry points. North America and Asia Pacific currently represent the largest revenue pools, reflecting mature industrial bases and rapid technological adoption respectively. Europe maintains a significant share, particularly in high-precision manufacturing and automotive-adjacent sensor applications. Latin America and the Middle East and Africa regions, while smaller in terms of absolute revenue share, offer specific growth trajectories tied to local industrial development and energy sector investments. The analysis within the report maps these regional dynamics without relying on outdated generalizations, providing localized intelligence that helps multinational corporations optimize their supply chain and sales strategies.
Worldwide Pressure-resistant Sensor Market
Voltage Pressure Sensor Market
Competitive Landscape and Strategic Consolidation
The pressure-resistant sensor market is characterized by a moderately concentrated competitive environment, where scale, technology portfolios, and regulatory compliance create significant barriers to entry. The report highlights that the top three companies account for approximately 38.45 percent of the market revenue, while the top five players control over half of the total market share at 52.12 percent. This concentration suggests that while there is room for niche players, the bulk of value generation is captured by established giants with diversified portfolios and strong customer integration capabilities. Understanding the specific positioning of these key entities is vital for any strategic maneuvering, whether it involves partnership, acquisition, or competitive repositioning.
Several core companies define the current competitive contours. TE Connectivity continues to expand its footprint, recently establishing new manufacturing facilities to increase capacity for medical microfluidic components, which supports broader sensor integration efforts. Their extensive portfolio includes medical-grade options suitable for harsh environments, reinforcing their position in both industrial and healthcare adjacent sectors. Honeywell International Inc. remains a pivotal supplier for high-precision applications, particularly in medical settings where reliability in clinical environments is paramount. Their focus on patient monitoring and respiratory devices aligns with broader trends in healthcare technology.
In the medical-specific domain, Edwards Lifesciences Corporation, now part of BD, provides dominant solutions in cardiac and ICU pressure monitoring kits, including disposable transducers for hemodynamic monitoring. Merit Sensor Systems specializes in MEMS piezoresistive technologies capable of withstanding extreme pressures up to 15,000 PSI with biocompatibility, catering to high-pressure inflation devices and harsh-media compatible needs. Utah Medical Products holds a strong position with single-use pressure transducers and biopharm-specific sensors compatible with rigorous sterilization methods like Gamma Irradiation and Ethylene Oxide. Amphenol All Sensors Corporation focuses on ultra-low to low pressure requirements for respiratory equipment, emphasizing precision. Millar Inc. stands out for high-fidelity MEMS catheter-tip solutions and chronic implantable sensor modules, recently showcasing customizable developer kits and long-term monitoring options at industry trade shows. Sensata Technologies, Setra Systems, Metallux SA, and Smiths Medical further round out a competitive field where differentiation often comes down to material science, certification levels, and application-specific engineering.
Regulatory Dynamics and Operational Realities
Strategic planning in this sector must account for the regulatory environment, which acts as both a gatekeeper and a growth enabler. Medical pressure sensors used inside the body are classified as Class III devices requiring FDA certification, imposing strict development and quality assurance timelines on market entrants. Common company certifications include ISO 13485 and ISO 9001, while product-level standards such as ANSI/3A and EHEDG apply where biomedical and hygiene requirements intersect with sensor design. These regulatory frameworks influence not just market access but also operational costs and time-to-market, factors that are rigorously analyzed in the report to help firms budget for compliance and risk mitigation.
Reimbursement policies are increasingly shaping demand, particularly in healthcare. The Centers for Medicare and Medicaid Services issued a National Coverage Determination effective 2025 covering FDA-approved implantable pulmonary artery pressure sensors for heart failure management. This regulatory milestone enables reimbursement for FDA-approved devices in clinical management, directly influencing the adoption rates of implantable solutions and encouraging manufacturers to invest in this growing sub-segment. Such policy shifts create ripple effects across the supply chain, affecting everything from raw material selection to sterile packaging strategies.
Operational realities also extend to material science and sterilization compatibility. Certain high-pressure sensor housings utilize materials like polysulfone or polycarbonate that are compatible with Gamma Irradiation and Ethylene Oxide sterilization, maintaining a five-year shelf life and USP Class VI compliance. These specifications are critical for biopharmaceutical and medical fluid monitoring applications where contamination control is non-negotiable. Additionally, specific high-pressure-resistant designs are utilized in specialized respiratory equipment, such as jet ventilators, where bias flow and occlusion detection are essential for patient safety. These technical nuances, often buried in product documentation or regulatory summaries, are elevated to strategic insights in our analysis, helping engineering and procurement teams make informed sourcing decisions.
Strategic Value for 2026 and Beyond
The release of this market research coincides with a critical juncture for industry stakeholders. As the market moves from the 2.63 billion USD projected revenue of 2026 toward its 2032 targets, the differentiation between success and stagnation will depend on the ability to interpret data accurately and act upon it swiftly. This report is not merely a collection of numbers; it is a strategic tool designed to answer the pressing questions that keep executives awake at night. Where should R&D budgets be allocated to capture the highest marginal returns? Which geographic regions offer the best risk-adjusted growth opportunities for the next fiscal cycle? How do recent regulatory changes alter the competitive balance between incumbent manufacturers and emerging challengers?
By integrating historical performance with forward-looking indicators, the research provides a framework for scenario planning. The identified CAGR of 6.82 percent serves as a benchmark against which internal projections can be validated. The segmentation breakdowns allow for the identification of overlooked niches where competition is less fierce but demand is stable. The competitive profiling of key companies offers a window into potential partnership opportunities or acquisition targets that align with long-term portfolio strategies. Furthermore, the analysis of recent developments, such as facility expansions and trade show revelations, provides real-time intelligence on where major players are investing their capital and focus.
For investors, the concentration metrics offer a lens through which to assess market stability and the potential for consolidation. For product managers, the detailed type and application splits illuminate the technical trends that will define the next generation of sensor requirements. For supply chain leaders, the regional revenue maps highlight potential vulnerabilities or opportunities for localization. In an era where data-driven decision-making is the standard, access to precise, validated, and strategically contextualized intelligence is a distinct competitive advantage.
To fully leverage these insights, stakeholders are encouraged to explore the complete report. The full version contains downloadable segments, proprietary data tables, and deep dives into specific technology trajectories that go beyond the scope of this overview. Access the full Worldwide Pressure-resistant Sensor Market research today to equip your organization with the intelligence needed to navigate the complexities of 2026 and secure a leadership position in the years to come.
For detailed analysis of this topic, please visit the official page: Worldwide Pressure-resistant Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com