

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LCD Scrubber Market to Hit $509.4M by 2032, Growing 5.85% CAGR

Strategic Intelligence for 2026: Navigating the Worldwide Heat Wet Scrubber for LCD Market
As the display manufacturing industry enters a critical phase of technological iteration and environmental compliance, the heat wet scrubber segment has emerged as a foundational infrastructure component. PW Consulting provides this strategic overview to introduce our latest comprehensive study on the Worldwide Heat Wet Scrubber for LCD Market, designed to equip executives, procurement leaders, and investment strategists with the analytical framework required for high-stakes decisions in 2026 and beyond. The intersection of next-generation production lines, stringent emission mandates, and evolving gas abatement architectures demands a clear, data-grounded understanding of market trajectories. This report delivers that clarity.
Macro Trajectory and the 2026 Decision Horizon
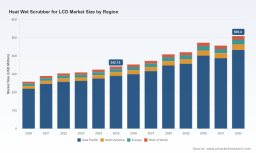
The heat wet scrubber market for LCD manufacturing has demonstrated consistent expansion over the past five years, reflecting the sector's structural reliance on reliable hazardous gas treatment. Historical performance from 2020 through 2025 establishes a clear growth baseline, with revenue scaling from 258.4 million USD to 342.15 million USD. This upward momentum carries into the forecast window, where the market is projected to advance at a compound annual growth rate of 5.85 percent, ultimately reaching 509.4 million USD by 2032. The trajectory underscores a shift from incremental capacity additions to strategically integrated abatement ecosystems.
For decision-makers in 2026, these figures are not merely historical artifacts or forward estimates; they represent a structural inflection point. The sustained growth pattern signals that heat wet scrubber deployment is transitioning from a peripheral compliance purchase to a core facility planning parameter. Manufacturers are increasingly evaluating scrubber architectures alongside line configurations, chemical process adjustments, and regional regulatory calendars. The forecast period extending to 2032 reveals continued expansion, with notable acceleration phases that will reshape supply chain negotiations, capacity planning, and technology roadmaps. Understanding where these inflection points occur, which product families capture incremental share, and how regional deployment patterns evolve will separate reactive procurement from proactive strategic positioning.
Technological Architecture and Segment Dynamics
Heat wet scrubbers within the LCD manufacturing environment are engineered to neutralize hazardous process gases, including perfluorocarbons and other reactive exhaust streams, through high-temperature interaction with liquid-phase treatment media. The operational demands of modern LCD fabs require systems that balance destruction efficiency, chemical resistance, and seamless integration into both point-of-use and central abatement layouts. Materials science plays a decisive role; corrosion-resistant alloys and specialized polymers are routinely specified to withstand acidic and reactive exhaust conditions, ensuring long-term reliability under continuous operational cycles.
The product landscape in this market is structured around distinct architectural approaches. Single-stage configurations offer streamlined installation and targeted treatment for specific exhaust profiles, while multi-stage architectures provide extended residence times and enhanced capture efficiency for complex gas mixtures. Integrated systems combine thermal treatment, wet scrubbing, and auxiliary control modules into unified platforms, increasingly favored by facilities seeking to minimize footprint, standardize maintenance protocols, and reduce inter-system coordination complexity. Parallel to these product categories, application segmentation reflects the generational evolution of LCD production lines. Legacy and mid-generation fabs continue to drive steady demand for abatement capacity aligned with established process chemistries, while advanced-generation lines, including Gen 8.5 and Gen 10.5 architectures, are reshaping throughput requirements and exhaust composition, prompting equipment manufacturers to refine thermal-wet treatment parameters and housing configurations.
Raw material selection, unit sizing, and integration topology are no longer purely engineering decisions; they directly influence total cost of ownership, downtime exposure, and future expansion flexibility. Decision-makers must evaluate how these architectural choices interact with their specific process roadmap and compliance timeline.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated competitive structure, with the top three players collectively representing 62.45 percent of revenue and the top five accounts capturing 78.3 percent. This concentration reflects the capital intensity of abatement engineering, the need for application-specific process validation, and the importance of long-term service and compliance support in LCD manufacturing environments. Established Korean and Japanese equipment providers dominate much of the installed base, leveraging deep experience in semiconductor and display fab environments, while specialized innovators continue to challenge incumbents through modular designs, plasma-hybrid configurations, and differentiated thermal-wet treatment platforms.
Several core enterprises define the current competitive terrain. Triple Cores Technology delivers plasma, thermal-wet, and heat wet scrubber systems tailored for hazardous gas treatment in semiconductor and LCD manufacturing, including PFC decomposition capabilities. YOUNGJIN IND specializes in gas abatement systems, offering heat wet scrubber models such as the YHS-06W and YHS-04W, complemented by high-temperature plasma and eco-friendly hazardous gas treatment options. Global Standard Technology manufactures a range of scrubbers, including thermal wet types, focused on harmful gas purification for semiconductor and LCD production. KC Innovation provides scrubber solutions for gas processing within semiconductor and display manufacturing workflows. Unisem supplies heat wet scrubbers and gas abatement equipment directed at LCD and semiconductor applications, while SemiAn Technology offers heat wet scrubber solutions integrated into broader gas treatment systems for LCD manufacturing. Japan Pionics contributes heat wet scrubber equipment aligned with LCD and semiconductor gas abatement requirements. Integrated Plasma Inc combines plasma and heat wet scrubber technologies for LCD process exhaust gas treatment, and Ebara Technologies provides wet scrubber abatement systems, including models engineered for display and LCD sub-fab environments, addressing water-soluble process gases across semiconductor and adjacent industries.
The competitive environment is further shaped by ongoing portfolio evolution. In March 2026, DAS Environmental Experts introduced a flexible SALIX wet scrubber portfolio optimized for semiconductor manufacturing applications, with relevance to high-purity exhaust treatment in display processes. Developments of this nature illustrate the continuous refinement of abatement platforms and the increasing emphasis on adaptability across process chemistries and fab layouts. For market participants, the strategic question is not simply which vendor offers the lowest upfront price, but which provider can sustain performance across generation transitions, minimize service disruption, and adapt to evolving emission standards without requiring costly architectural retrofits. The concentration metrics suggest that scale advantages, installed-base service networks, and application-specific validation remain decisive competitive moats.
Regulatory, Operational, and Supply Chain Forces
Regulatory pressure continues to be a primary catalyst for abatement investment. Semiconductor and LCD manufacturing facilities must deploy high-efficiency abatement systems to comply with strict emission standards for PFCs and other hazardous process gases. Compliance is no longer a static target; it is a moving threshold shaped by regional environmental policy, community exposure expectations, and evolving best-practice frameworks for process exhaust management. Facilities that treat abatement as a compliance checkbox risk encountering costly retrofits or operational interruptions when standards tighten. Conversely, organizations that integrate abatement strategy into long-range fab planning can align equipment selection with anticipated regulatory calendars and process chemistry shifts.
Operational durability and material resilience are equally critical. Heat wet scrubbers for LCD typically incorporate corrosion-resistant materials such as specialized alloys or polymers to handle acidic and reactive exhaust streams. The durability of these components directly affects maintenance frequency, replacement cycles, and overall system availability. In high-uptime environments, the choice of construction materials and the robustness of thermal management design can determine whether a scrubber functions as a stable backbone of the emission control infrastructure or becomes a recurring source of downtime and unplanned service spend.
On the demand side, increasing LCD and display panel production drives demand for reliable point-of-use and central abatement systems, including heat wet scrubbers, to manage process emissions. This production-driven demand is not uniform across regions or line generations, and procurement strategies must account for varying deployment intensities, local sourcing considerations, and integration requirements with existing sub-fab and exhaust infrastructure. Supply chain resilience also matters as manufacturers evaluate lead times, component availability, and the ability of suppliers to support rapid installation schedules aligned with line build-outs or upgrade cycles.
What the Analysis Delivers: Operational Intelligence for 2026
This research report is built to convert market complexity into executable intelligence. It provides a detailed mapping of historical performance and forecast trajectories, enabling executives to benchmark current procurement assumptions against macro growth patterns and identify periods of likely demand acceleration. The analysis examines segmentation architecture across product types and application generations, allowing strategy teams to evaluate which configurations are gaining traction, where capacity is expanding, and how line generational shifts influence equipment preferences. Regional deployment patterns are assessed to clarify where concentration is highest, where growth is emerging, and how geographic factors shape sourcing, installation, and service logistics.
Beyond market sizing, the report delivers a competitive benchmarking framework that evaluates the positioning of leading equipment providers, including their technology portfolios, application focus, and strategic movement patterns. It integrates the impact of recent product portfolio expansions and regulatory developments into an actionable context, helping procurement and engineering teams anticipate vendor evolution and align vendor selection with long-range compliance and capacity plans. The study also incorporates material and design considerations relevant to heat wet scrubber performance in LCD environments, linking corrosion-resistant construction, thermal treatment efficiency, and system integration choices to total cost of ownership and operational risk.
For 2026 decision-making, the report functions as a strategic filter. It helps leadership teams prioritize capital allocation, evaluate make-versus-buy considerations for abatement infrastructure, prepare for generation transitions in LCD production, and develop vendor engagement strategies that account for market concentration and ongoing product innovation. The objective is not to provide a static snapshot, but to equip decision-makers with the structural understanding required to anticipate change rather than merely react to it.
Worldwide Spray Scrubbers Market
Conclusion: Positioning for the Next Phase of Market Development
The worldwide heat wet scrubber market for LCD manufacturing is entering a phase defined by technological maturity, regulatory reinforcement, and evolving production architectures. Historical growth trajectories, forward forecast patterns, and the concentrated nature of the competitive field all point to a market where strategic clarity yields durable advantage. Organizations that approach abatement planning with a full understanding of product architecture, application generation shifts, regional deployment dynamics, and vendor positioning will be better prepared to manage cost, compliance, and operational continuity through 2032 and beyond.
This research study provides the depth, structure, and forward-looking analysis required to support those decisions. We invite industry leaders, engineering directors, and strategy teams to engage with the full report, where detailed segmentation insights, competition mapping, and forecast methodology are presented in complete form. The 2026 planning window demands more than surface-level market awareness; it requires the kind of structured intelligence that turns evolving market signals into confident strategic action.
Worldwide Heat Wet Scrubber for LCD Market
For detailed analysis of this topic, please visit the official page: Worldwide Heat Wet Scrubber for LCD Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com