

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Litz Wire Market to Hit $1.08B by 2032 at 6.85% CAGR, Asia Pacific Leads

Unlocking Growth in the Global Litz Wire Market: A Strategic Imperative for 2026 and Beyond
As industries accelerate their transition toward electrification, miniaturization, and high-frequency connectivity, Litz wire has evolved from a niche winding component into a foundational enabler of next-generation power and signal transmission systems. The worldwide market for this specialized conductor, engineered to mitigate skin effect and proximity losses at elevated frequencies, is experiencing a structural inflection point. For executives, procurement leaders, and strategic planners operating in 2026, understanding the underlying trajectories of demand, supply constraints, and competitive realignments is no longer optional. It is a prerequisite for capital allocation, supplier diversification, and product roadmap execution.
Worldwide Copper Litz Wire Market
The macro trajectory underscores this urgency. Between 2020 and 2025, the global market expanded steadily, reflecting consistent industrial uptake and the gradual mainstreaming of high-frequency power architectures. Looking forward, the forecast horizon from 2026 through 2032 projects a compound annual growth rate of 6.85 percent, translating historical momentum into sustained expansion. Revenue measured in millions of USD is anticipated to cross the seven hundred fifty six million threshold in 2026 and continue its upward march toward the one billion mark by the end of the decade, with further acceleration projected into 2032. These figures are not isolated statistics; they represent a measurable shift in how manufacturers, energy infrastructure developers, and medical device engineers approach conductor selection under tightening efficiency mandates and rising performance expectations.
Why These Numbers Matter for 2026 Decision-Making
The forecast period does not merely describe a continuation of past trends. It captures the convergence of multiple structural drivers that will redefine sourcing strategies, regional footprint planning, and technology investment priorities in the coming fiscal year. Automotive electrification and the rapid scaling of battery management architectures are compressing design cycles, forcing OEMs and Tier suppliers to evaluate conductor geometries that balance thermal resilience with high-frequency current handling. Simultaneously, the renewable energy and power supply sector is reengineering transformer and inverter topologies to meet grid stability requirements, creating sustained demand for precision-wound Litz configurations. Even traditionally conservative verticals such as medical instrumentation and industrial automation are prioritizing signal integrity and power density, pulling specialized wire architectures into mainstream engineering specifications.
For 2026 strategy teams, this environment demands more than superficial market sizing. It requires granular visibility into how demand vectors interact with production constraints, regulatory timelines, and raw material volatility. Decision-makers must assess which applications will absorb capacity first, how pricing architectures will adapt to input cost fluctuations, and where regional supply networks are likely to reconfigure in response to trade policy shifts. The strategic value of a comprehensive market intelligence report lies precisely in its ability to convert broad growth narratives into actionable allocation frameworks, risk mitigation pathways, and partnership evaluation criteria.
Navigating a Rapidly Evolving Competitive Landscape
The market concentration profile reveals a moderately consolidated playing field, where the top three participants collectively account for approximately thirty five percent of aggregate revenue, while the top five expand their combined share to nearly forty eight percent. This structure indicates a mature core of established manufacturers that have invested heavily in process engineering, certification portfolios, and application-specific development, alongside a periphery of agile specialists and regional producers capturing niche demand. The competitive dynamics are increasingly defined not by volume alone, but by technical differentiation, compliance readiness, and the ability to synchronize supply with fast-moving engineering programs.
Several cornerstone players illustrate the spectrum of strategic positioning shaping the market. Elektrisola, headquartered in Stolberg, Germany, maintains its stature as a global leader in enameled Litz wire production, with engineering emphasis on high-frequency inductors, transformers, and wireless charging architectures. Its recent introduction of a high-temperature Litz wire series tailored for EV wireless charging coils, certified to IATF 16949 standards, signals how incumbents are aligning product roadmaps with automotive qualification requirements and thermal stress scenarios. Across the Atlantic, MWS Wire Industries in Westlake, Ohio, continues to specialize in custom strand configurations for RF, medical, and aerospace environments. Its showcase of ultra-fine Litz wire for 5G antenna systems at CWIEME Americas highlights the sector-wide push toward miniaturized, high-efficiency signal conductors in telecommunications infrastructure.
North American manufacturing relevance is further reinforced by New England Wire Technologies, based in Lisbon, New Hampshire, which focuses on high-performance Litz wire for motors, sensors, and power electronics with an explicit emphasis on miniaturization. The firm's recent renewal of AS9100D certification for aerospace-grade production demonstrates how quality management frameworks are becoming competitive differentiators in regulated supply chains. Sam Dong Co., Ltd., operating from Gyeonggi-do, South Korea, occupies a strategically positioned role in Asian automotive ecosystems, producing Litz wire for EV chargers, inductors, and high-power applications. Its execution of a multi-year supply agreement with a major EV battery manufacturer underscores the commercial momentum linking conductor supply directly to electrified mobility scaling.
Worldwide Litz Wire Market
Global operations and high-volume production pathways are represented by Essex Furukawa, with its Fort Wayne, Indiana headquarters and worldwide operational footprint, delivering Litz wire variants for magnet wire applications in renewable energy and industrial transformers. In parallel, Ruiyuan Group, headquartered in Dongguan, China, functions as a high-volume producer serving consumer electronics and power supply markets, reflecting the scale advantages that Asian manufacturing ecosystems bring to cost-sensitive, high-throughput segments. On the application-specialist side, Cooner Wire in Chatsworth, California, provides standard and custom configurations for audio, RF, and medical device applications, while Fujikura Ltd., based in Tokyo, Japan, develops advanced Litz wire solutions for telecommunications and high-frequency components. Collectively, these organizations illustrate how competitive advantage is increasingly constructed through application-specific engineering, certification depth, and geographic supply alignment rather than commodity volume alone.
Forces Reshaping Supply, Cost, and Regional Access
The forward strategy calculus cannot be isolated from the operational realities currently pressing on production economics and trade flows. Raw material volatility remains a central consideration, with copper pricing exhibiting notable year-over-year increases as of early 2026, directly pressuring Litz wire manufacturing costs and prompting suppliers to revisit pricing architectures, alloy substitution evaluations, and inventory buffering strategies. The insulation and enamel supply chain introduces a parallel layer of complexity, as extended lead times for polyimide enamel resins reflect ongoing resin shortages that constrain production scheduling and require procurement teams to plan further ahead with qualified alternative material pathways.
Regulatory and compliance shifts add another dimension of strategic urgency. The updated EU RoHS Directive framework, mandating lower halogen content in wire insulations effective in 2026, compels manufacturers and downstream integrators to validate insulation material compatibility, re-qualify supplier portfolios, and adjust formulation specifications ahead of compliance deadlines. At the same time, geopolitical and trade dynamics are recalibrating cross-border material movement. Export controls related to high-purity copper enablers have tightened for China-bound Litz wire components, prompting regional supply chain actors to evaluate sourcing architectures, inventory localization, and second-source qualification strategies. Concurrently, customs enforcement actions imposing substantial tariffs on certain Chinese Litz wire imports have elevated the cost calculus for buyers relying on trans-Pacific procurement, reinforcing the case for regional supplier diversification and localized assembly considerations.
These intersecting forces are not isolated disruptions. They form a compound environment where cost management, regulatory readiness, and geographic access must be modeled together. Firms that continue to treat Litz wire procurement as a transactional purchasing function will face mounting exposure to lead-time variability, compliance friction, and margin compression. Those that embed the market's structural dynamics into supplier evaluation matrices, engineering specification reviews, and regional capacity planning will be better positioned to absorb volatility while preserving performance and schedule integrity.
What This Study Delivers for Strategic Teams
A rigorous market assessment must move beyond headline sizing and concentration ratios to provide the operational scaffolding required for 2026 execution. The research framework is designed to equip decision-makers with a layered view of the market, integrating historical performance baselines, forward forecast horizons, and structural segmentation that clarifies where demand is accumulating and how different product architectures are positioned. The analysis maps the interplay between conductor geometry preferences, application-driven qualification requirements, and regional demand profiles, while maintaining a disciplined focus on the variables that most directly influence sourcing, investment, and partnership strategy.
The study examines competitive positioning by synthesizing company profiles, technological emphasis, production specialization, and recent commercial milestones, enabling readers to benchmark incumbents, assess emerging entrants, and identify capability gaps that may present partnership or acquisition opportunities. It contextualizes market movements within the broader ecosystem of material availability, regulatory timelines, and trade policy evolution, offering a framework for scenario planning around cost behavior, supply continuity, and compliance adaptation. The deliverable structure supports multiple internal use cases, including procurement strategy refinement, R&D specification alignment, regional market entry evaluation, and capital allocation prioritization for high-growth application segments.
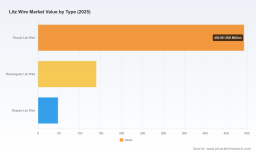
Importantly, the research preserves the granularity required for defensible planning without exposing the market to oversimplified narratives. Regional demand distributions, application-level revenue architecture, and product-type market shares are analyzed in depth to reveal the relative weight of each segment, the pacing of adoption across use cases, and the structural implications for manufacturing capacity and supplier service portfolios. This level of detail is essential for teams that need to determine where to concentrate negotiation leverage, which applications warrant accelerated engineering support, and how to sequence supply commitments in a market where timing differentials can translate directly into competitive advantage or exposure.
Positioning for the Next Wave of Electrification and High-Frequency Integration
The Litz wire market in 2026 is defined by a rare alignment of steady structural growth, accelerating application diversification, and a supply environment that rewards preparedness. The combination of a sustained growth trajectory, a moderately consolidated competitive base, and an ecosystem shaped by material constraints, regulatory updates, and trade realignments creates both opportunity and complexity. Organizations that approach this landscape with disciplined market intelligence will be able to prioritize the right applications, qualify the right partners, and build sourcing architectures that can withstand short-term volatility while capturing long-term demand.
The full Worldwide Litz Wire Market research study expands each of these dimensions into a comprehensive, decision-ready intelligence package. It provides the segmented market architecture, regional and application-level analysis, competitive profiling, and scenario-oriented context necessary to translate broad industry momentum into concrete strategic action. For executives preparing capital plans, procurement roadmaps, and technology investment decisions for the 2026 to 2032 horizon, the complete study offers the depth, structure, and current intelligence required to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: Worldwide Litz Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com