

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts Aluminium‑Scandium Market to Grow at a 6.8% CAGR, Signaling Strong Upside
By pmarketresearch, 2026-06-30
Aluminium-Scandium Market: Strategic Outlook for 2026 — PW Consulting Industry Brief
Executive summary
PW Consulting’s Aluminium-Scandium Market report (base year 2025) frames a fast-evolving specialty-metal landscape that is moving from niche R&D towards early-stage commercialisation. Our analysis shows the market expanding from an estimated USD 52.72 Million in 2020 to USD 73.19 Million in 2025, and — under central-case assumptions — tracking to approximately USD 114.85 Million by 2032, representing a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. This trajectory is driven by concurrent technological readiness in powder metallurgy and additive manufacturing, shifts in defence and aerospace procurement, and policy measures targeting critical minerals.
Aluminium-Scandium Market
This industry brief distils the report’s strategic value for corporate decision-makers in 2026: it highlights where near-term commercial opportunities exist, what supply-side risks deserve immediate attention, and which organisational choices will determine whether companies capture disproportionate upside as the market commercialises.
Aluminium-Scandium Market
Why this matters for 2026 corporate strategy
-
Timing matters: The sector is at an inflection point where lab-scale advantages can translate into commercial differentiation. Early commercial entrants that lock supply or secure preferred manufacturing pathways can establish cost and capability advantages that are difficult to erode later.
Aluminium-Scandium Market -
Cost and input risk are material: Industry data point to significant raw-material cost pressure, with scandium oxide pricing substantially elevated. These input dynamics amplify the importance of procurement strategy, long-term contracts, and alternative sourcing or recycling pathways.
-
Policy-driven demand: Scandium’s designation as a critical mineral in key markets is already reshaping incentives and permitting pathways, creating distinct advantages for companies positioned to capitalise on domestic-production incentives and supply-chain de‑risking programmes.
-
Technology bifurcation: Two technology trajectories are emerging — high-scandium feedstocks enabling specialised high-performance components, and low-scandium alloys and master-alloy routes focused on cost-effective property enhancement. Each route implies different business models and commercial partners.
-
Consolidation window: Market structure shows a small set of capable suppliers and an expanding group of specialised producers. The next two years are likely to see alliance activity, capacity investments, and selective M&A as incumbents and new entrants pursue scale and vertical integration.
What the full report delivers (practical content for executives)
-
Transparent market sizing and forecasting models calibrated to 2020–2025 historicals and projecting through 2032; downloadable, model-ready files for CFOs and strategy teams to stress-test assumptions against their own scenarios.
-
Supply-chain mapping that identifies mining, by-product recovery, master-alloy production, powder manufacturing, and downstream fabrication nodes — with risk scores and mitigation playbooks for each node.
-
Go-to-market playbooks for manufacturers and component suppliers, including cost-to-serve templates, partnership archetypes for powder and casting suppliers, and commercial pilot guidance for additive manufacturing (AM) adoption.
-
Investment-grade vendor due diligence frameworks that evaluate metallurgy readiness, production scalability, quality controls, and IP risks — actionable checklists that accelerate vendor selection cycles.
-
Regulatory and incentives digest that synthesises critical-mineral policies and financial incentives across major jurisdictions, and their likely impact on project economics and sourcing strategies.
-
Scenario-based pricing and profitability models, including sensitivity to scandium-oxide price shocks, alloy formulation choices, and differing adoption rates across core end markets.
Competitive landscape — key players and strategic implications
Our competitive analysis focuses on a mix of technology innovators, specialised alloy producers, and upstream scandium suppliers. Rather than presenting exhaustive scorecards in this brief, the following highlights the strategic positioning of select companies that are shaping the market dynamics.
-
Metalysis (United Kingdom) — Metalysis has signalled a step-change by moving into commercial production of high-scandium-loading aluminium-scandium powder, with technical capability to deliver very high scandium content feedstock. For corporate buyers focused on semiconductor, aerospace, and defence applications, Metalysis represents a potential strategic partner for high‑value, performance‑critical parts. Their entry accelerates the timeline for advanced applications where scandium’s property improvements are mission‑critical.
-
NioCorp Developments Ltd. (United States) — NioCorp’s recent casting milestone with a US foundry demonstrates commercial-readiness for low-scandium castings. This development is important for OEMs contemplating component-level substitution that balances cost with property gains. NioCorp’s pathway underlines the practical viability of master-alloy and casting routes as near-term commercial options.
-
IBC Advanced Alloys (United States) — Foundry and casting capabilities paired with additive-manufacturing services place IBC as an integrator for customers seeking component prototyping and qualification. Their role emphasises the importance of collaboration between powder producers and fabricators.
-
Stanford Advanced Materials, AEM REE, Edge Tech Industries, Scandium International Mining Corp. — These suppliers together illustrate the global patchwork of alloy providers and upstream master-alloy producers. Their varying geographic footprints and product ranges create opportunities for buyers to optimise cost, lead time, and technical fit — but they also require robust supplier assessment given heterogeneous quality standards and capacity constraints.
Recent industry developments underscore the move from demonstration to commercial application: successful low‑scandium casting initiatives and the start of high‑scandium powder production are tangible signals that both price‑sensitive and performance‑driven value chains are preparing to scale. For strategists, the implication is clear — partnerships and offtake agreements signed in 2026 will materially influence commercial access and margin profiles over the next three to five years.
Supply dynamics, pricing pressure, and strategic responses
-
Input exposure: Scandium oxide pricing is high relative to other alloying elements, and primary supply remains constrained because much of global scandium supply emerges as a by‑product of nickel laterite processing. This combination increases the probability of price spikes and supply interruptions, necessitating procurement strategies that go beyond spot buying.
-
Mitigation levers: Executives should evaluate a portfolio of responses — long‑dated offtake agreements, equity stakes in upstream recovery projects, offtake‑plus‑processing partnerships with master-alloy producers, and investment in recycling streams to recapture scandium from end-of-life components.
-
Cost engineering: Alloy design and process optimisation can materially influence per‑part scandium consumption. R&D investments into lower‑content alloys that retain critical property benefits, or into deposition and powder‑usage efficiencies in AM, can reduce sensitivity to raw‑material price volatility.
Commercial and investment playbook for 2026
Companies considering entry or expansion into aluminium‑scandium value chains should prioritise a compact set of actions for 2026 that align operating choices with the projected market growth profile:
-
Fast-track commercial pilots with both high‑scandium and low‑scandium suppliers to understand processing tolerances, qualification timelines, and total landed cost across candidate supply chains.
-
Secure a dual sourcing architecture that blends a high‑purity powder supplier for performance-critical parts with master-alloy or casting partners for higher-volume, lower-cost components.
-
Embed price‑and‑supply stress tests into capital expenditure cases. Given the market’s projected CAGR and size profile, small changes in input cost can swing margin outcomes for early movers.
-
Pursue selective vertical integration or strategic equity positions in upstream recovery projects where incentives and national policy support make domestic supply more bankable.
-
Prioritise qualification pathways for aerospace and defence customers, as these sectors often act as technology validators whose adoption accelerates broader commercial acceptance.
How PW Consulting supports executive action
Our full report is structured as an execution playbook for 2026 decisions. We provide executive-ready deliverables including:
-
Interactive financial models and scenario tools that let you test price, adoption, and technology pathways against corporate KPIs.
-
Supplier due diligence templates, quality‑assurance checklists, and contract term recommendations calibrated to scandium risk profiles.
-
Commercial pilot roadmaps and benchmarking matrices for additive and casting workflows, including recommended timelines for qualification and scaling.
-
M&A and partnership advisory support — from target screening through negotiation and integration planning — informed by our proprietary market-sizing and competitive-intensity analytics.
Next steps and call to action
For executives preparing capital and commercial plans in 2026, the window to secure advantaged positions in the aluminium‑scandium value chain is immediate and finite. PW Consulting’s Aluminium‑Scandium Market report packages the market intelligence, risk frameworks, and execution templates you need to move decisively while protecting downside.
To access the full dataset, vendor scorecards, and the downloadable scenario model, please visit our report page where you can request the complete study and bespoke advisory support tailored to your organisation’s strategy.
For detailed analysis of this topic, please visit the official page: Aluminium-Scandium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Fluorosilicate Market Forecast to Reach USD 277.3 Million by 2032, Growing at a 5.25% CAGR
By pmarketresearch, 2026-06-30
Sodium Fluorosilicate Market — Strategic Outlook 2026: What Every Executive Needs Before Locking 2026 Plans
PW Consulting’s new Sodium Fluorosilicate Market report (base year 2025, historical 2020–2025, forecast 2026–2032) delivers a focused, decision-grade view designed to inform procurement, operations, regulatory and M&A choices through 2026 and beyond. Measured in USD Million, the underlying market expanded from roughly 140 million in 2020 to about 185 million in 2025 and — under our central scenario — is projected to reach approximately 277 million by 2032, growing at a compound annual growth rate of 5.25% over the forecast. This release is a strategic “teaser”: it demonstrates the analytic depth we used to reach those conclusions while preserving the proprietary sub-segmentation and supplier-level data that we make available in the full report.
Sodium Fluorosilicate Market
Why this matters for 2026 decision-makers
-
Planning Horizon Alignment: As the market trajectory shifts from recovery to steady expansion, capital allocation for capacity upgrades, product reformulation and inventory strategy should be synchronized with a multi-year forecast rather than short-term spot behavior.
Sodium Fluorosilicate Market -
Procurement & Cost Management: Input-cost volatility — notably sharp fluorspar price moves in 2023–2024 — has altered the effective cost curve for sodium fluorosilicate producers. Procurement teams must combine forward-looking price modelling with contracting flexibility to avoid margin erosion.
Sodium Fluorosilicate Market -
Regulatory Risk & Compliance: Certification and handling rules (notably NSF/ANSI Standard 60 and relevant AWWA guidance) are not mere compliance checkboxes; they determine market access for municipal water-fluoridation supply chains and influence allowable product formats in several jurisdictions.
-
Operational Resilience: Recent geopolitical-linked supply interruptions that temporarily reduced fluoride dosing in some U.S. water systems underline the need for resilience planning across feedstock sourcing, production safety stocks and rapid-response logistics.
Key market dynamics shaping strategy in 2026
-
Raw material and logistics shocks. During 2023–2024, fluorspar feedstock costs rose substantially in some regions due to constrained supply and logistics bottlenecks. The effect persisted into 2025 and has become a core driver of margin pressure and supplier consolidation discussions.
-
Regulatory tightening and product formats. Industry standards such as NSF/ANSI Standard 60 and AWWA references remain decisive for municipal business. Additionally, some state-level rules now restrict certain product handling approaches (for example, recent state regulations prohibit the use of slurries in drinking-water dosing in selected jurisdictions), making format flexibility a commercial differentiator.
-
Product innovation reducing OPEX and HSE risk. Late‑2025 saw the market introduction of low-dust granulated formulations that reduce airborne particulates by nearly half compared with conventional powders — a development with direct implications for occupational health, downstream handling costs, and community acceptance.
-
Geopolitical exposure. Supply chain interruptions linked to regional conflicts have manifested as episodic shortfalls for municipal systems; these events emphasize the need for scenario planning and multi-source strategies.
What the PW Consulting report delivers (practical, actionable content)
-
Integrated market-sizing and forecasting model: transparent assumptions, scenario toggles (price shocks, regulatory closures, feedstock disruptions) and downloadable worksheets that allow executives to stress-test plans under alternative futures.
-
Procurement playbook and price‑curve analytics: supplier cost-driver decomposition, break-even maps for different product formats, and recommended contracting structures (including indexed contracts, optionality clauses and strategic stock levels).
-
Regulatory impact assessment: jurisdictional risk matrix, compliance timetables, and playbook for securing NSF/AWWA approvals or designing product formats to circumvent locally prohibited handling methods.
-
Competitive and supplier benchmarking: non-attributable performance bands for capacity, certification status, product portfolios and service models — enabling buyers to prioritize qualified sources without revealing the confidential supplier-level metrics reserved for full subscribers.
-
Investment and M&A decision support: capital-cost-to-output models, simple payback and NPV templates, plus risk-adjusted valuation heuristics for upstream feedstock integration or bolt-on specialty-capacity acquisitions.
-
Operational resilience toolkit: inventory policy recommendations (safety stock, reorder points), dual-sourcing frameworks, logistics playbooks for rapid re-routing, and a decision tree for temporary demand suppression scenarios triggered by regulatory or community actions.
Competitive landscape: what leading suppliers are prioritizing
Our qualitative competitive review highlights a mix of global chemical players, regional specialists, and manufacturers that compete on certification, packaging, and purity. Several recurring strategic postures emerged from public disclosures and industry interviews:
-
Certification-first incumbents: some producers combine NSF-60/AWWA approvals with municipal-focused supply chains. For buyers of water-quality products, verified certifications and demonstrated municipal-service capabilities materially reduce onboarding friction.
-
Byproduct and integrated producers: firms that derive sodium fluorosilicate from existing phosphoric-acid or fluoride-processing streams can offer competitive cost structures but remain sensitive to the economics of parent processes and feedstock swings.
-
Specialty and purity differentiation: a group of manufacturers focuses on high-purity grades for specialty chemicals and industrial uses, supporting premium pricing and niche contractual relationships.
-
Packaging and handling innovators: suppliers investing in alternative packaging (big bags, tanker-ready formats) and low-dust granulations are translating product innovations into tangible downstream savings and compliance advantages.
Representative examples (high-level): KC Industries operates a large capacity, NSF‑approved facility and is positioned for municipal channels; European producers leverage integrated chemical platforms and diverse packaging capabilities; several Chinese manufacturers compete on high-purity specs and industrial channels. Each archetype implies different counterparty risk, margin profile and strategic fit for buyers or investors.
2026 Strategic Playbook — Five priority moves
-
Lock in certified supply for critical municipal contracts. Prioritize suppliers with current NSF/AWWA evidence and documented municipal service histories; where certification gaps exist, plan for lead times and testing costs.
-
Hedge feedstock exposure through contracts and vertical options. Consider indexed short-to-medium term contracts for fluorspar-linked inputs, blended sourcing strategies and due diligence on upstream integration targets.
-
Adopt product-format flexibility to insulate operations. Evaluate transitioning to low-dust granulations or alternative packaging to reduce occupational health costs, lower handling losses, and ensure compliance with local handling prohibitions.
-
Stress-test logistics and build contingency capacity. Create rapid-swap supplier lists, establish transfer arrangements across regions, and maintain scenario-modeled safety stocks for municipal-critical volumes to avoid service disruptions.
-
Embed regulatory monitoring into commercial cadence. Create a regulatory tracker for state and municipal rules that impact allowed product formats, dosing approaches and certification requirements; couple it with a community-engagement playbook to defuse local opposition quickly.
How executives should use this report in 2026
Use the PW Consulting model as an operational tool, not an architectural curiosity. Procurement officers should pair the report’s price and supplier-risk modules with live tender strategies; operations teams should use the product-format and packaging analyses to prioritize modest CAPEX that reduces OPEX and regulatory friction; corporate development teams should apply our valuation templates to screen target opportunities rapidly. Finance teams will find the scenario-based revenue and margin outputs especially useful for budgeting under stress cases that include feedstock shocks or temporary regulatory closures.
Final note and next steps
Sodium fluorosilicate remains a technically mature but strategically nuanced market: modest compound growth masks concentrated operational and regulatory tail risks that can upend supply relationships in months, not years. PW Consulting’s full report provides the proprietary segmentation, supplier scorecards, and downloadable models needed to move from strategy to execution. For executives preparing 2026 budgets, procurement cycles, or M&A screening lists, this analysis is designed to be the basis for immediate decisions — with the granular levers packaged behind the report’s gated intelligence.
To access the full dataset, supplier-level benchmarking and interactive forecasting models, please refer to the PW Consulting report page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Sodium Fluorosilicate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mass Transfer (Distillation) Market to Expand at 6.98% CAGR (2026–2032), Rising from USD 1,549.0 Million in 2025 to USD 2,481.0 Million — North America, Column Internals and Petroleum Industrial Lead (CR3 58%, CR5 68%)
By pmarketresearch, 2026-06-30
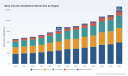
Mass Transfer (Distillation) Market: Strategic Signals for 2026 Decision-Making
Executive snapshot
As PW Consulting releases its Mass Transfer (Distillation) Market study, we present a focused briefing on the strategic implications senior executives must weigh in 2026. The market has expanded steadily from an estimated USD 1,150 million in 2020 to about USD 1,549 million in 2025, and PwC-style forecasting (2026–2032) points to continued expansion at a compound annual growth rate (CAGR) of approximately 6.98%. By the end of the forecast window, the market is expected to approach the mid‑billion-dollar range. Market concentration is meaningful but not monopolistic: the top three players account for roughly 58% of industry revenue while the top five reach about 68%, leaving room for specialist entrants and regional champions.
Mass Transfer (Distillation) Market
Why this report matters for 2026 planning
-
Macro clarity for capex allocation: Our sizing and trend analysis provide finance and strategy teams a defensible basis to prioritize capital investments in distillation assets, internals and energy‑efficiency retrofits during 2026 budget cycles.
Mass Transfer (Distillation) Market -
Procurement and vendor selection: The vendor landscape analysis, combined with scenario modeling for energy price swings and regulatory tightening, equips procurement with a shortlisting framework that balances performance, total cost of ownership (TCO) and supply resilience.
Mass Transfer (Distillation) Market -
Technology-roadmap alignment: Engineers and R&D leaders can benchmark investment timing for electrified and hybrid distillation solutions against adoption curves and commercial deployments captured in the report.
-
M&A and partnership targeting: Corporate development teams can use our concentration and capability overlays to identify bolt‑on targets and strategic alliances that accelerate entry into adjacent separation technologies.
Market dynamics: drivers, constraints, and inflection points
The distillation value chain is being reshaped by three intersecting forces: regulatory pressure, energy and sustainability imperatives, and technology innovation. Regulation remains a consistent driver—programs focused on solvent recovery and emissions control are increasingly enforced, prompting operators to upgrade or replace legacy distillation systems. For example, enhanced solvent recovery requirements under key air quality programs are driving demand for higher‑efficiency column internals and integrated recovery units.
On the energy and sustainability front, feedstock and fuel specifications continue to evolve (e.g., tighter sulfur limits and cleaner fuel mandates), creating technical demand for refined separation solutions and process optimization. Simultaneously, electrified distillation and other process electrification concepts—already in commercial pilots and early plant rollouts—offer a pathway to reduce indirect emissions and, in some cases, lower operating expense through improved thermal integration. These emergent technologies (including proprietary implementations from incumbent suppliers) are altering retrofit economics and lifecycle assessments.
Technological progress is visible across internals, packings and tray designs, with emphasis on improving mass transfer per unit pressure drop, increasing turndown capability, and easing maintenance. Incremental hardware advances are being complemented by digital optimization—advanced control strategies, model predictive control, and condition-based maintenance are materially extending asset life and performance.
Report coverage and practitioner tools
PW Consulting’s Mass Transfer (Distillation) Market report is designed as an operationally actionable toolkit for executives, plant managers and corporate strategists. Key inclusions:
-
Comprehensive market sizing and historical trend analysis (2020–2025 base) with forward projections to 2032, employing bottom‑up and top‑down triangulation methods.
-
Segmentation across product types, applications, and regions, coupled with scenario analyses that stress‑test demand under different regulatory and energy price pathways. (Note: our public summary hides detailed segment-level figures to protect the competitive integrity of the primary data set—subscribers can access full granular tables and dashboards on the report portal.)
-
Vendor profiles and capability matrices covering design, manufacturing footprint, aftermarket services and innovation pipelines.
-
Practical decision frameworks—capex prioritization templates, retrofit business‑case models, procurement scorecards and a tender playbook optimized for complex separation projects.
-
Supply‑chain risk heatmaps and contingency planning guidelines addressing critical raw material availability, manufacturing lead times and geopolitical exposures.
Competitive landscape: what incumbents are doing
The industry is shaped by well-established engineering suppliers and a cohort of specialized fabricators and service providers. Several players are noteworthy for their strategic positioning:
-
Sulzer Ltd (Winterthur, Switzerland) — Strengths: deep product portfolio in column internals, active R&D in energy‑saving technologies, and growing commercial traction for electrified distillation concepts. Recent company disclosures indicate robust 2025 results and a continued emphasis on distillation and absorption technologies, underlining Sulzer’s role as a technology leader and a bellwether for advanced separation adoption.
-
Koch‑Glitsch (Wichita, USA) — Strengths: global engineering reach, integrated tower internals and phase‑separation solutions, and a history of project delivery for large refining and petrochemical clients. Their toolset is frequently chosen where scale and complete‑scope responsibility are required.
-
RVT Process Equipment GmbH (Marktrodach, Germany) — Strengths: European fabrication excellence and custom internals and tray manufacturing, serving clients needing engineered, high‑precision internals with tight quality and delivery specifications.
-
De Dietrich Process Systems (Niederbronn, France) — Strengths: engineered columns, turnkey systems and strong presence in chemical processing applications. Their exhibition plans at chemicals trade events highlight ongoing efforts to showcase integrated process equipment and to deepen market visibility.
-
Chane Terminal Botlek B.V. (Rotterdam, Netherlands) — Strengths: terminal operator with project capabilities for petrochemical processing and toll distillation services. Recent expansion projects focused on sustainable aviation fuel capacity signal an operational pivot to renewable fuel processing and hub services.
-
Sepco Process Inc. (Conroe, Texas, USA) — Strengths: vendor of random packings and separation media with a focus on competitive pricing, aftermarket supply continuity and specialty packing solutions for retrofit and newbuild columns.
These incumbents illustrate a mix of technology leadership, regional manufacturing density and service depth. The CR3/CR5 concentration metrics cited earlier reflect a market where a few firms capture scale advantages while a long tail of specialists compete on niche performance, cost or local presence.
Strategic implications and recommended actions for 2026
-
Prioritize retrofits that deliver near‑term OPEX reductions: Use the report’s retrofit TCO models to rank candidate columns by payback under varying energy price and carbon cost scenarios. Focus on internals and packing upgrades with short payback horizons to de‑risk CAPEX.
-
Evaluate electrified distillation pilots selectively: For sites with constrained thermal integration or access to low‑carbon electricity, run structured pilots with clear performance KPIs. Use supplier partnerships to offload technical uncertainty and integrate learnings into a cross‑site deployment roadmap.
-
Embed regulatory forward‑scanning in project gating: Given tightening solvent recovery and emissions standards, ensure that new projects and major revamps include compliance thresholds that exceed current minimums to avoid stranded assets.
-
Leverage procurement playbooks to shorten supplier selection cycles: Apply the report’s scorecard to balance technical fit, delivery risk and aftermarket service terms—this is especially important given lead‑time volatility and the strategic nature of internals supply.
-
Scan M&A selectively: Identify small, high‑performance suppliers or service providers whose technology or market access would accelerate the buyer’s entry into high‑growth niches, while being mindful of integration complexity and dilution of focus.
Next steps and how to use this briefing
This briefing highlights the strategic vantage points PW Consulting’s full Mass Transfer (Distillation) Market report provides. Leaders preparing 2026 budgets should treat the report as both a diagnostic and an implementation playbook: it combines market sizing and competitive benchmarking with contract templates, retrofit calculators and scenario analyses calibrated to realistic regulatory and energy trajectories.
To preserve the competitive integrity of our primary research and to respect client confidentiality, this release intentionally omits detailed segment tables and region‑level allocations. Subscribers to the full report receive interactive dashboards, downloadable datasets and supplier scorecards that unlock those insights for transaction support, capital planning and engineering decision‑making.
Conclusion: signal or noise?
The mass transfer sector is transitioning from incremental hardware improvements to a phase where system‑level integration, electrification and regulatory alignment will determine winners and losers. Market scale is growing at a mid‑single‑digit CAGR, incumbents are reinforcing position through technology and project wins, and new‑generation solutions are beginning to shift the economic calculus for retrofits and newbuilds. For 2026, the most valuable decisions will be those that convert market visibility into prioritized, measurable pilot and retrofit programs—supported by disciplined procurement and an eye toward regulatory resilience.
For full access to the granular segment tables, company profiles, and the implementation toolkit referenced above, visit the PW Consulting report page to download the full Mass Transfer (Distillation) Market report and associated datasets.
For detailed analysis of this topic, please visit the official page: Mass Transfer (Distillation) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PODE Market to Grow from USD 215.0 Million in 2025 to USD 344.8 Million by 2032 at a 5.56% CAGR
By pmarketresearch, 2026-06-30
Polyoxymethylene Dimethyl Ethers (PODE) Market Outlook: Strategic Intelligence for 2026 Decision-Makers
As global energy markets enter a phase of pragmatic decarbonization, Polyoxymethylene Dimethyl Ethers (PODE) is emerging from niche chemistry into a strategically important fuel-additive class. PW Consulting’s latest market study—anchored on a 2025 base year and a 2026–2032 forecasting horizon—maps the commercial trajectory of PODE and translates that trajectory into concrete decisions for companies planning investments, supply agreements, and go-to-market activity in 2026. The study projects the market to expand from an assessed USD 215.0 Million in 2025 toward a materially larger addressable pool by 2032 (our long‑term model yields USD 344.8 Million), tracking a compounded annual growth rate (CAGR) of 5.56% over the forecast period. These headline metrics set the strategic frame; the substance of competitive advantage will be determined by how organizations operationalize insights in the coming 12–18 months.
Polyoxymethylene Dimethyl Ethers (PODE) Market
Why 2026 Is a Strategic Inflection Point
-
Transitional demand dynamics: Regulatory tightening on particulate matter and lifecycle carbon intensity is pushing refiners, fleet operators, and fuel blenders to evaluate solutions that can deliver immediate emissions benefits without wholesale engine redesigns. PODE’s role as a clean-diesel blending component positions it as a pragmatic mitigation lever—one that portfolios need to evaluate now rather than later.
Polyoxymethylene Dimethyl Ethers (PODE) Market -
Supply-side consolidation and capacity cycles: Our analysis shows that a small set of producers currently account for a dominant share of commercial supply. When combined with feedstock constraints and conversion economics, this concentration creates windows for value capture by suppliers and strategic exposure for buyers—particularly during capacity ramp phases and feedstock-price shocks.
Polyoxymethylene Dimethyl Ethers (PODE) Market -
Commercial readiness: Several producers already operate at commercial scale with integrated downstream capability. For buyers and investors, 2026 represents a narrow timeframe to secure offtakes, pilot integrations, and collaborative R&D before broader market diffusion increases competition for premium placement.
What the Report Delivers (Practical, Execution-Focused)
-
Proprietary market sizing and trend models: multi-scenario build that reconciles historical 2020–2025 performance with our 2026–2032 forecast, enabling users to run sensitivity analyses against alternative regulatory and oil-price pathways.
-
Techno‑economic playbooks: step‑by‑step cost, margin, and CAPEX/OPEX models for greenfield and brownfield PODE production, with configurable inputs (feedstock mix, plant scale, utility costs) to produce customized project IRR and payback profiles.
-
Supply‑chain and logistics maps: integrated supplier-distributor-customer flows and choke‑point identification, highlighting where inventory strategies, local storage, and blending infrastructure materially alter commercial outcomes.
-
Regulatory and certification matrix: country- and application-level checkpoints (emissions credits, fuel standards, fuel swap approvals) that inform certification timelines and go‑to‑market sequencing.
-
Commercial templates and negotiation playbooks: standardized offtake frameworks, quality specifications, escrow and escrow‑release clauses, plus recommended contract tenors and indexation schemes for buyers and sellers.
-
Interactive dashboards and scorecards: supplier health, technology readiness levels, and buyer adoption curves that translate raw data into prioritised action lists for executives running 12‑week planning sprints.
Competitive Landscape: Strategic Implications of Current Players
The PODE supply landscape is characterized by a set of established suppliers that combine feedstock integration, downstream capability, and early commercial traction. Notable players profiled in the study include major Chinese producers that have leveraged methanol-based value chains to bring PODE to market in commercial volumes. These suppliers demonstrate three recurring strategic archetypes: scale integrators, specialized niche suppliers, and technology-as-differentiator players.
-
Scale integrators (e.g., integrated methanol-to-PODE platforms): leverage feedstock integration to compress production cost and secure long-term offtake margins. Their advantage is structural—control of upstream feedstock gives them defensible cost curves during volatile commodity cycles.
-
Specialized niche suppliers: smaller producers focus on product-quality specialization (specific oligomer distributions), rapid customer response, and tailored blending solutions for strategic fleet customers. These players are attractive M&A targets for larger refiners seeking product differentiation.
-
Technology and application specialists: entities that position PODE not only as a fuel additive but also as an environment‑friendly solvent and industrial intermediate. This dual-use strategy diversifies revenue and reduces exposure to cyclical fuel demand swings.
From a market structure perspective, concentration metrics indicate that the top-three firms control a large portion of the market, while the top-five extend that dominance further. For strategic planners, this implies two things: first, price leadership can emerge quickly during supply tightness; second, new entrants must focus on niche advantages (quality, carbon profile, local logistics) or partner with incumbents to scale.
Priority Strategic Moves for 2026
-
Secure feedstock and offtake flexibility: lock-in diversified methanol sourcing while negotiating offtake clauses with staged volume ramps. Build optionality into contracts to adjust to feedstock price swings and regulatory shifts.
-
Targeted commercial pilots with fleet operators and refiners: deploy limited-scope pilots that generate measurable emissions and performance data. Use pilots to accelerate certification and to create reference installations that lower buyer adoption friction.
-
Invest in low-carbon pathways: prioritize projects and partners that enable lower lifecycle carbon intensity (e.g., renewable methanol feedstock, carbon capture at upstream facilities). These projects are increasingly valuable as jurisdictions tighten fuel carbon specifications.
-
Negotiate strategic partnerships or bolt-on acquisitions: for companies lacking scale, partner with local producers or acquire specialized suppliers to access existing distribution and technical capabilities rather than building from scratch.
-
Operationalize risk management: integrate price-hedging, inventory buffers, and multi-modal logistics to mitigate short-term shocks while maintaining commercial agility.
Risk Matrix and Mitigations
-
Feedstock volatility: methanol price shocks can compress margins rapidly. Mitigation: flexible feedstock contracts, index-linked pricing, and hedging models integrated into commercial agreements.
-
Regulatory uncertainty: evolving fuel standards can both accelerate demand and create compliance hurdles. Mitigation: advance certification pilots in priority markets and engage with regulators to accelerate approvals.
-
Quality and compatibility risks: PODE grades differ and may interact with engine technologies differently. Mitigation: invest in lab validation and co-engineering sessions with OEMs and major fleet operators.
-
Concentration risk: reliance on a few large suppliers exposes buyers to single‑source disruption. Mitigation: diversify supplier base, maintain contingency inventory, and structure supply agreements with fallback arrangements.
How to Deploy the Report in 90–120 Days
-
Week 1–4: Use the report’s scenario templates to stress-test your base business case under three market outcomes (accelerated regulation, commodity shock, and slow adoption). Prioritize near-term gating factors the models identify.
-
Week 5–8: Run supplier scorecards and initiate NDA-level conversations with prioritized producers to shape pilot offtake terms and trial specifications.
-
Week 9–12: Finalize pilot design, secure regulatory checkpoints, and lock interim logistics. Parallel workstreams should engage R&D/OEM partners to close performance validation protocols.
-
Week 13–16: Review pilot outcomes, calibrate commercial pricing and contract structures, and execute the first commercial offtake or expansion decision informed by the report’s financial templates.
Conclusion — The Strategic Premium of Timely Intelligence
PODE represents more than a chemical market expansion: it is a case study in how transitional fuels can deliver immediate emissions reductions while creating new value pools for incumbents and new entrants alike. With a 2025 base-year market of USD 215.0 Million and a forecast path to USD 344.8 Million by 2032 (CAGR 5.56%), the opportunity is real—but time-sensitive. Companies that move into 2026 with a playbook—secured feedstock optionality, validated commercial pilots, and partnerships with existing commercial-scale producers—will capture a disproportionate share of early value.
PW Consulting’s PODE study provides the empirical models, operational templates, and supplier intelligence required to act confidently. The report intentionally reserves granular regional and application-level split tables within our subscriber portal so that executives and transaction teams can access raw segment data behind a secure consent flow. For leaders preparing investment memos, commercial negotiations, or regulatory roadmaps in 2026, the study is designed to be the single executable source for decision-ready intelligence.
To access the full interactive dataset, supplier scorecards, and the commercial playbooks referenced in this brief, visit our report page or contact PW Consulting’s industry desk for an executive walk-through.
For detailed analysis of this topic, please visit the official page: Polyoxymethylene Dimethyl Ethers (PODE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vanilla Market Poised for Robust Expansion — 5.69% CAGR Forecast Through 2032
By pmarketresearch, 2026-06-30
Vanilla Market 2026: Strategic Imperatives from PW Consulting’s Vanilla Market Report (Base Year 2025)
Executive summary
PW Consulting’s Vanilla Market report, anchored on a 2025 base and projecting through 2032, provides a compact, action-oriented intelligence package for C-suite leaders, procurement heads, R&D executives, and M&A teams. The global vanilla market — measured in USD million — is on a clear upward trajectory, expanding at a compound annual growth rate (CAGR) of 5.69% across our 2026–2032 forecast window. From a market size of USD 3,850 million in 2025, our modeling anticipates growth to roughly USD 5,810 million by 2032. This growth momentum, however, sits atop a complex mix of supply-side normalization, price volatility, regulatory shifts, and strategic moves by ingredient houses and global flavor houses. The report is structured to help executives translate these dynamics into confident 2026 decisions — from sourcing and hedging to product formulation and partnership strategies.
Vanilla Market
Why this report matters for 2026 decisions
-
Timing and clarity: 2026 is a pivot year where structural changes in origin markets and buyer strategies converge. The report decodes the near-term implications of origin policy shifts, pricing normalization and raw-material availability — enabling procurement teams to move from reactive buying to strategic contracting.
Vanilla Market -
Investment read-across: For investors and M&A teams, the market’s steady mid-single-digit CAGR combined with a low-to-moderate concentration profile indicates pockets of consolidation opportunity, particularly among origin-integrated processors and premium natural players. The report provides a practical framework to size targets and validate growth synergy assumptions without exposing proprietary subsegment metrics.
Vanilla Market -
Product strategy: For product and R&D leaders, the intelligence translates macro supply trajectories into formulation scenarios that respect label trends (natural, organic, fair-trade) while buffering margin impacts from commodity swings.
Market trajectory and headline numbers
Using 2025 as the base year, our topline market sizing shows an ascent from USD 3,850 million (2025) to an estimated USD 5,810 million by 2032, driven by steady consumption growth, premiumization in food and beverage segments, and expanded use in adjacent applications. The forecast period — 2026 to 2032 — reflects a modeled CAGR of 5.69%, calibrated against historical trends from 2020–2025 and stress-tested under multiple origin-price and demand scenarios. These high-level projections are intended to guide strategic planning and scenario modeling; the report itself contains the detailed models and sensitivity runs that subscribers can use to align procurement windows, price corridors, and product roadmaps.
Supply-side dynamics: what is changing at origin
-
Origin pricing normalization: After several years of extreme price volatility, export prices from leading originating countries retreated in 2025 to a wider range. Coupled with a dismantling of certain export levies and liberalization measures, these moves are restoring transactional transparency but also introduce new short-term pricing floors and ceilings for buyers to manage.
-
Harvest and inventory context: The 2025 harvest outlook from primary producing regions returned notable volumes, contributing to a global supply pool that, at a headline level, outpaced near-term demand and created a measurable oversupply. This has immediate implications for inventory strategy — firms that can flexibly scale storage and roll-over commitments will gain negotiating leverage in 2026.
-
Trade and tariff shifts: Recent tariff policy adjustments — including reductions in reciprocal tariffs by major importers — have improved cross-border flows and reduced landed cost uncertainty for certain buyer groups. Buyers should reassess landed-cost models and origin diversification plans in light of these trade policy changes.
Market dynamics in context — datapoints that matter
-
US import flows: US imports from key origins remain sizable and, in 2025, posted notable import values that reflect both industrial-scale demand and retail channel restocking patterns. This underlines the United States’ continued strategic weight for global vanilla flows and the need for global suppliers to maintain robust North American distribution strategies.
-
Price band volatility: Export price ranges observed in 2025 demonstrate that commodity-grade vs. premium-grade differentials remain pronounced. Supply agreements should therefore be structured with grade-linked indexing or blended supply clauses to avoid margin erosion.
-
Origin policy shifts: Some producing-country reforms in 2025 removed fixed export fees and introduced market reference benchmarks. These policy moves reduce distortions but increase the need for on-the-ground market intelligence — a capability many global buyers are strengthening via direct sourcing partnerships.
Competitive landscape — who matters and why
The vanilla market remains fragmented relative to many other flavors and botanicals. Our concentration analysis shows a top-three share (CR3) in the low twenties and a top-five share (CR5) in the high twenties — signaling meaningful room for mid-market specialists and origin-integrated players to sustain differentiated growth.
-
Nielsen-Massey Vanillas — A legacy specialist focused on pure extracts, pastes and flavors with strong brand recognition in premium retail and culinary channels. Their emphasis on organic and sustainably sourced offerings positions them well for value-seeking premium consumers.
-
Heilala Vanilla — An origin-specialist with strong Pacific sourcing credentials; its focus on sustainable production and awards-based product positioning supports targeted premium playbooks.
-
Eurovanille — Long-standing European player serving professional chefs and food manufacturers; the firm’s premium bean and powder capabilities remain a trusted supply point for high-margin applications.
-
McCormick & Company — Global scale and retail reach with diversified spice and extract portfolios; McCormick’s integration across channels makes it a keystone competitor for branded and private-label offerings.
-
Givaudan, Symrise, IFF, ADM — These global ingredient houses combine R&D, origin programs and sustainability initiatives. They are rapidly investing in origin infrastructure, science-led flavor development, and forward contracts to secure differentiated supply. Recent capital deployments and innovation center openings at origin illustrate a strategic shift toward on-the-ground, climate-resilient sourcing partnerships.
Notably, in May 2026 a leading global flavor house opened a Vanilla Innovation Center in Madagascar — an example of origin-proximate investment intended to accelerate quality improvement, climate adaptation and applied R&D. Such moves raise the bar on vertical integration and speed to market for novel natural solutions.
Report contents — what you will find (and what we deliberately withhold in this summary)
-
Proprietary market model: Topline and scenario-driven forecasts (2026–2032) with downloadable model files for buyer-specific scenario stress tests.
-
Supply-chain maps: Origin-to-consumer flow diagrams, cost-to-serve benchmarks, and validated supplier scorecards to accelerate vendor selection.
-
Procurement playbooks: Practical contract structures, hedging templates, and inventory optimization matrices tailored to vanilla’s grade and quality profiles.
-
Commercial playbooks: Go-to-market approaches for premiumization, clean-label reformulation strategies, and channel-specific margin models.
-
Risk register & early-warning indicators: A prioritized list of origin, climate, regulatory and logistics signals that should trigger immediate buyer action.
-
Competitive dossiers: Strategic profiles and capability maps for incumbent players and potential challengers. (Note: detailed subsegment tables and granular regional/application splits are reserved for the full report to preserve proprietary benchmarking integrity.)
Practical strategic recommendations for 2026
-
Move from ad-hoc spot buying to layered contracting: Use a blended approach of short-term spot, medium-term fixed-price windows and origin-linked indexed contracts to capture price troughs while ensuring continuity.
-
Invest in origin partnerships: Work with suppliers and international ingredient houses that demonstrate origin presence and climate-resilience programming, including farmer training and traceability systems.
-
Design product-level margin buffers: For higher-risk premium formulations, build flexible formulations and alternative flavor blends to protect margin when primary-origin premiums spike.
-
Operationalize early-warning indicators: Integrate the report’s risk indicators into procurement dashboards so that harvest, trade policy, and price-band signals automatically adjust reorder points and hedging triggers.
-
Consider strategic M&A or JV: Given moderate market concentration and differentiated capabilities across origin integrators and flavor houses, small, focused acquisitions can provide access to origin supply, proprietary extracts and enhanced sustainability credentials.
How to use this intelligence in your 2026 planning cycle
-
Procurement: Re-run the included forecast scenarios against your current contract book to derive an optimal mix of spot vs. contracted volumes for H1 and H2 2026.
-
R&D and Marketing: Use the formulation playbooks to prioritize SKU rationalization and to design label claims that align with evolving retail and regulatory expectations.
-
Corporate Strategy & M&A: Apply the competitive mapping and valuation heuristics to shortlist acquisition targets and JV opportunities with quick wins in origin control or premium product channels.
Final note — the trailer principle in action
This article surfaces the strategic themes, headline numbers and the operational levers that will matter in 2026. PW Consulting’s full Vanilla Market report contains the complete dataset, sensitivity models, supplier scorecards and granular regional/application breakouts that are essential for execution. We have intentionally withheld fine-grained subsegment figures and proprietary tables from this press release to preserve the actionable advantage subscribers receive. Visit our report page to access the full intelligence package, licensing options, and a customized briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Vanilla Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Massage Chair Market Poised to Grow at 5.6% CAGR (2026–2032), Rising from USD 429.0 Million in 2025 to USD 621.6 Million by 2032
By pmarketresearch, 2026-06-30
PW Consulting: Luxury Massage Chair Market — Strategic Imperatives for 2026
PW Consulting today releases an executive briefing from our full Luxury Massage Chair Market research package, providing senior leaders with the strategic context they need to make high‑stake decisions in 2026. Built on a base year of 2025 and drawing from a five‑year historical window (2020–2025) and a 2026–2032 forecast horizon, our analysis shows the market continuing to expand at a compound annual growth rate (CAGR) of 5.6%. The market size, measured in USD Million, recorded steady growth from the early 2020s and reached approximately USD 429.0 Million in 2025, with our baseline projection for 2026 at roughly USD 460.1 Million and a 2032 projection approaching USD 622 Million under the central scenario.
Luxury Massage Chair Market
Why this briefing matters to executives in 2026
-
Investment prioritization: The 5.6% CAGR and the projected step‑up in absolute market value between 2025 and 2026 highlight where marginal investments in R&D, channel expansion, and service infrastructure are most likely to compound value.
Luxury Massage Chair Market -
Regulatory readiness: Recent regulatory shifts (including the FDA’s May 2025 clearance for heat therapy in luxury massage chairs) change clinical and marketing pathways and create immediate product compliance and evidence‑generation requirements.
Luxury Massage Chair Market -
M&A and partnership timing: A market with moderate concentration (CR3 ~35%; CR5 ~55%) presents both consolidation opportunities and room for fast followers to acquire technology or scale quickly — particularly companies backed by fresh venture capital.
-
Commercial model optimization: Our work identifies where premiumization, subscription services, and DME (Durable Medical Equipment) reimbursement converge, informing pricing and channel strategies for 2026.
Key market dynamics shaping 2026 strategy
The luxury massage chair market is being reshaped by intersecting forces — technological innovation, regulatory developments, and evolving consumer wellness preferences. Technology cycles are accelerating around 4D mechanics, advanced body‑scanning, AI‑driven personalization, and integrated therapies such as heat and hydrotherapy. On the regulatory front, FDA and payer guidance issued in 2025 opens new product claims and reimbursement pathways but raises the bar for clinical evidence and post‑market surveillance.
Cost-side pressures persist: manufacturers are balancing higher‑grade mechanical components (reinforced track systems, premium upholstery) against pushback on retail prices. Simultaneously, funding for product innovation is increasing; for example, a 2024–2025 wave of venture and growth capital supports companies adding AI, biometric monitoring, and 4D capabilities. Supply‑chain and labor cost volatility is a persistent operational risk that requires scenario planning in procurement and production footprints.
Competitive landscape — who is shaping the premium tier
Our competitive review focuses on established brands and new entrants whose product roadmaps and strategic moves will matter most in 2026:
-
Infinity Massage Chairs (Seabrook, NH): US‑designed systems such as Syner‑D and recent launches like the iMaster Deluxe 4S demonstrate a playbook centered on modular upgrades (4D systems, flexible track designs) and AI‑driven program personalization.
-
Furniture For Life (Colorado): Through OHCO and The World’s Best Massage Chairs® branding, the firm is consolidating a legacy premium position with ultra‑premium 4D Shiatsu and integrated heat therapy models aimed at affluent consumers and boutique hospitality placements.
-
Human Touch LLC (Florida): Focused on ergonomic solutions (Perfect Chair series) and passive stretching technologies, the company occupies a hybrid wellness/medical positioning with an emphasis on comfort and clinical adjunct use.
-
Osaki USA: The Osaki and Titan lines deploy SL‑Track mechanics, 4D options, and body‑scan functionality; recent strategic partnerships signal an intention to blend hydrotherapy elements and differentiated materials into luxury SKUs.
-
Beurer GmbH (Germany): With Shiatsu‑focused deluxe models and advanced scanning systems, Beurer is competitive across premium retail and medical‑adjacent channels in Europe and beyond.
-
Bodyfriend (South Korea): High‑engineering content (patented walking legs, robotic elements, integrated heat and airbag systems) positions Bodyfriend as a technology leader within the premium consumer and hospitality segments.
These firms vary in distribution strategy, R&D intensity, and channel focus — from direct‑to‑consumer, luxury retailers, and wellness spas to medical device pathways. Our report maps competing value propositions and identifies relative strengths in product depth, after‑sales service, and brand equity.
Recent developments to watch
-
Capital flows and product expansion: BodyCraft Massage Chairs’ funding round in 2024/2025 enabled rapid expansion of 4D and AI‑integrated SKUs — a pattern we expect to continue among growth‑stage innovators.
-
Strategic partnerships: Osaki’s collaboration to integrate hydrotherapy into chair platforms illustrates how adjacent therapy technologies are being bundled to broaden consumer appeal.
-
Product launches and advanced claims: Infinity’s iMaster Deluxe 4S and similar premium introductions show that manufacturers are competing on software personalization as much as on mechanical hardware.
-
Regulatory and clinical tooling: The FDA’s May 2025 clearance for heat therapy and new biometric monitoring suites (released by vendors in late 2025) create both opportunity and compliance obligations for product teams.
-
Payer environment: When clinically prescribed, luxury chairs can be eligible under DME categories — an under‑leveraged reimbursement channel that requires robust clinical evidence and provider engagement strategies.
What the full report delivers (practical, executable deliverables)
-
Proprietary market model (USD Million basis) with base year 2025, historical series 2020–2025, and 2026–2032 forecast scenarios under base, upside, and downside assumptions.
-
Competitive scorecards and product benchmarking that rank players on technology, materials, service, distribution, and regulatory readiness.
-
Supply chain and cost‑build templates showing component sensitivity (tracks, motors, upholstery) and labor scenarios to inform sourcing decisions.
-
Go‑to‑market playbooks for premium and medical channels, including pricing ladders, dealer economics, and DME capture strategies.
-
M&A target shortlists and partnership frameworks tied to integration risk and time‑to‑market for incremental technologies (AI, hydrotherapy, biometric monitoring).
-
Regulatory tracker and clinical evidence roadmap to support product claims and reimbursement submissions.
Note: this public briefing intentionally omits the granular segmentation tables (region, type, application) that we use in our proprietary modelling. Those detailed splits — which are critical to precise channel and SKU decisions — are available in the full report and data appendices.
Actionable recommendations for 2026
-
Accelerate integration of heat therapy and biometric features into flagship SKUs, but pair product claims with a targeted clinical evidence plan to secure both regulatory endorsements and payer pathways.
-
Prioritize modular product architectures that enable rapid software updates (AI personalization) and hardware upgrades (4D actuators) to extend product lifecycles and margin capture.
-
Consider bolt‑on acquisitions or minority investments in firms with proven AI or hydrotherapy capabilities to shorten time‑to‑market and avoid costly internal R&D cycles.
-
Recalibrate channel mixes: expand direct service and warranty programs to support premium pricing while protecting margins through selective retail partnerships where brand signaling matters.
-
De‑risk supply chains by qualifying alternate suppliers for high‑value mechanical subassemblies and locking long‑lead contracts for premium upholstery and reinforced tracks.
Methodology and access
The analysis in this briefing is derived from PW Consulting’s comprehensive market model and primary research program. Key inputs include vendor financials, product specifications, patent and regulatory filings, caregiver and buyer interviews, and shipment data. The base year is 2025, the historical window is 2020–2025, and the forecast period extends from 2026 through 2032. All monetary values are reported in USD (Million). Market concentration metrics referenced above (CR3 ≈ 35%; CR5 ≈ 55%) reflect revenue aggregation across leading manufacturers.
To review the full dataset, vendor scorecards, and the segmented tables that underlie our guidance — including downloadable spreadsheets, scenario models, and an executive workshop package — please consult the PW Consulting report access page. This briefing is designed to surface the strategic highlights and immediate actions; the full intelligence suite contains the granular splits and numeric detail necessary for transaction diligence and product portfolio optimization.
Contact PW Consulting to schedule a tailored executive briefing or to request the full Luxury Massage Chair Market report and data annex. Our advisors are prepared to translate the forecast and competitive insights into a bespoke 90‑day action plan for your leadership team.
For detailed analysis of this topic, please visit the official page: Luxury Massage Chair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Ships Turbocharger Market to Expand at a 5.3% CAGR, New Insight Reveals
By pmarketresearch, 2026-06-30
Ships Turbocharger Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s new Ships Turbocharger Market report (base year 2025) delivers the strategic market intelligence that executives, product leaders, and corporate development teams need as they set priorities for 2026. The global ships turbocharger market was valued at USD 939.38 Million in 2025 and, under our central forecast, is expected to expand at a 5.3% CAGR through the 2026–2032 period, reaching approximately USD 1,369.93 Million by 2032. This briefing summarizes the report’s strategic implications and highlights the practical, decision-ready outputs that the full study delivers—while intentionally reserving the granular splits and proprietary scenario tables for report subscribers.
Ships Turbocharger Market
Why this market matters now — context for 2026 strategy
- Regulatory tightening is a growth engine and a risk filter. IMO Tier III, MARPOL Annex VI provisions, US EPA alignments, EU equipment type-approval rules and USCG requirements are forcing integration of after-treatment strategies with turbocharger designs. Companies that embed compliance into product roadmaps will convert regulation from a cost center into a barrier to entry for competitors.
- Steady, predictable growth enables differentiated plays. A mid-single-digit CAGR makes capex-intensive initiatives (new product lines, factory upgrades, after-sales networks) financially justifiable when prioritized against high-return retrofit and service segments.
- Service and lifecycle revenue are strategic priorities. Turbocharger manufacturers are moving beyond OEM sales toward service contracts, digital predictive maintenance and retrofit solutions—models that improve margin visibility and customer stickiness.
- Technology convergence is reshaping product requirements. Demands for lower emissions, higher fuel flexibility (including e-fuels), and tighter integration with engine control/connectivity systems are changing turbocharger design trade-offs—favoring modular, serviceable, and software-enabled products.
Data-driven signals that should guide 2026 choices
- Scale plus specialization wins. The market’s overall trajectory is clear: steady expansion from 2026 onward. However, market concentration metrics show room for specialist players—CR3 stands at 30% and CR5 at 45%—indicating a competitive environment where global platform leaders coexist with high-margin niche suppliers. Strategic implication: pursue either scale-driven efficiency or technical differentiation (not a middle-of-the-road position).
- Aftermarket and services are the margin engine. Our demand modelling indicates aftermarket activities—maintenance, spares, upgrades, and service contracts—drive disproportionately higher margin and predictable revenue compared with initial OEM sales. For 2026 planning, invest in field service networks, digital condition monitoring, and bundled service offers.
- Retrofit demand will be a near-term catalyst. Emissions-driven retrofits, plus conversion opportunities tied to fuel transitions, present higher-margin, lower-capex growth levers than newbuild cycles alone. Companies with retrofit product portfolios and retrofit-capable certifications will capture outsized share of the early-adopter retrofit installs.
- Regulatory approvals and OEM certifications are commercially decisive. Recent approvals and type-endorsements materially shorten procurement cycles and enable entry into key fleets. Certification strategy must be front-loaded in product launch roadmaps to avoid missed revenue windows in 2026–2027.
Competitive landscape — what the report reveals (high-level)
The competitive map combines capability profiles, go-to-market footprints, and recent tactical moves to indicate where supplier advantage is developing. The market is balanced between legacy engine-system integrators, specialist turbocharger builders, and power-systems conglomerates pursuing vertical integration.
Ships Turbocharger Market
- Accelleron / ABB-linked expertise (Switzerland). Accelleron remains highly active—documented product approvals for auxiliary-engine MXP series, a new low-speed ACCX300-L launch, and milestone order volumes for A100-L/A200-L series. These moves underpin a dual strategy: defend core low- and medium-speed turbo business while monetizing aftermarket services and digital care packages. Their recent multi-year service agreements demonstrate a deliberate shift to recurring revenue.
- Mitsubishi Heavy Industries (MET series, Japan). MHI’s MET line continues to benefit from licensing and local production arrangements that expand reach into regional shipbuilding clusters. Licensing is a lower-capex route to share technology while preserving incremental service spares and retrofit opportunities.
- MAN Energy Solutions (Germany). MAN’s cross-domain capability—covering low-, medium-, and high-speed diesel and gas engines—gives it advantages in systems integration and aftermarket service bundling. For companies planning platform plays, MAN exemplifies how engine-turbo integration can be leveraged to protect installed-base revenues.
- IHI and Everllence (Japan/Germany). These specialists emphasize reliability and maintainability in marine conditions, tailoring offerings toward fleets with high uptime demands. Their focus on ease-of-service and flexible maintenance contracts makes them credible alternatives for operators prioritizing operational continuity.
- Cummins (USA). Cummins leverages engine-turbo synergies and genset integrations to capture propulsion and auxiliary power needs—especially in niches where integrated propulsion/genset packages are procured.
Strategic takeaway: incumbents with certification depth and aftermarket coverage will continue to capture premium share, but mid-sized specialists with retrofit capabilities and rapid type-approval strategies can outpace larger rivals in targeted segments.
Ships Turbocharger Market
Regulatory and technological tailwinds — practical implications
- Integration with after-treatment is non-negotiable. Because IMO Tier III and related rules mandate after-treatment for many marine engines, turbocharger designs must be optimized for exhaust system integration. Product design teams must prioritize thermodynamic compatibility and pressure-drop minimization while ensuring serviceability.
- Type-approval timelines are strategic milestones. EU Medical Approval-style processes (e.g., Marine Equipment Directive) and USCG/EPA alignments can extend time-to-market. Firms must plan certification campaigns in Q1–Q2 2026 to align commercial launches with buying cycles.
- Fuel diversity requires flexible architectures. As fleets evaluate low-carbon fuels and e-fuels, turbochargers must accommodate broader operating envelopes. Modular turbine and compressor mapping, paired with adaptable control software, will be differentiators.
What PW Consulting’s report delivers — actionable contents
The full report is built as a toolkit for executives making 2026 commitments. Key deliverables include:
- Market model and forecasts (2020–2025 historical base; 2026–2032 scenarios) with sensitivity analyses for slow/fast decarbonization pathways.
- Competitive scorecards covering product portfolios, certification status, aftermarket reach, and strategic initiatives for leading suppliers.
- Regulatory impact matrix linking regional rule sets to product design and certification needs, with timelines to prioritize approvals in 2026.
- Go-to-market playbooks for OEMs, aftermarket specialists, and new entrants—detailing pricing strategies, service-pack design, retrofit sales sequences, and platform partnerships.
- Supply-chain risk assessment and mitigation options (contract manufacturing, dual-sourcing, critical raw-material exposure), including quantified lead-time and margin impacts under alternate sourcing scenarios.
- Deal-sourcing shortlist and valuation heuristics for acquisition targets that deliver immediate service network access, certification portfolios or retrofit product lines.
- Implementation checklists for product managers: certification milestones, type-approval sequencing, and launch budget templates.
To preserve the strategic value of the dataset, the report reserves granular regional, type and application-level revenue splits and pricing benchmarks for subscribers. Those details include the differentiated revenue pools and retrofit addressable market metrics that materially influence go/no-go investment decisions; they are essential inputs to any acquisition or product-capex model.
Immediate recommendations for 2026 planning
- Prioritize certification and retrofit product readiness. Time-to-approval will determine 2026–2027 revenue windows—start certification workstreams now.
- Rebalance spend toward aftermarket and digital services. Allocate a higher proportion of marketing and field-engineering budgets to service conversion programs where payback is most rapid.
- Pursue targeted partnerships rather than broad-scale M&A. Licensing, regional manufacturing agreements and service alliances can deliver market access with lower capital outlay and faster execution than full acquisitions in 2026.
- Stress-test supply chains for material and lead-time shocks. Build contingency plans for critical components and consider contractual safeguards with key suppliers.
Conclusion — the strategic edge PW Consulting offers
With the ships turbocharger market on a steady mid-single-digit growth path and regulatory forces raising technical thresholds for entry, 2026 is a pivotal year for strategic positioning. PW Consulting’s Ships Turbocharger Market report equips decision-makers with a blend of quantitative forecasting, certification-timeline intelligence, supplier benchmarking, and transaction-ready recommendations. The study is designed to convert market signals into executable corporate priorities—while the full, subscriber-only datasets provide the segmented revenue breakdowns and scenario tables required to finalize budgets, acquisition models, and product roadmaps.
For companies aiming to convert regulatory change into commercial advantage in 2026, the time to act is now. Access the full report and the proprietary data tables on the PW Consulting website to obtain the granular intelligence needed to finalize strategic commitments.
For detailed analysis of this topic, please visit the official page: Ships Turbocharger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aluminum Nitride Ceramic Heaters Market to Reach USD 401.9 Million by 2032, Expanding at a 7.2% CAGR (2026–2032)
By pmarketresearch, 2026-06-30
Aluminum Nitride (AlN) Ceramic Heaters Market — PW Consulting Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming in-depth market research on the Aluminum Nitride (AlN) Ceramic Heaters market. Built on a rigorous assessment of the historical window (2020–2025) and forward-looking forecasts for 2026–2032, this analysis is designed as a practical decision-support tool for executives, procurement leaders, R&D heads and corporate strategists preparing plans for 2026. The market is sized and modeled in USD Million; our base year is 2025.
Aluminum Nitride Ceramic Heaters Market
Executive snapshot
- Market trajectory: Our bottom-up model shows the global AlN ceramic heaters market growing at a compound annual growth rate (CAGR) of approximately 7.2% over the forecast window. In USD Million terms the market expands from a 2025 base of roughly 247.2 to an estimated 401.9 by 2032, reflecting continuing demand from high‑precision thermal-management applications.
- Competitive posture: The supplier landscape remains fragmented relative to many semiconductor-related supply chains — the leading firms do not yet dominate in a way that precludes strategic entry, investment or consolidation plays.
- Strategic imperative: For organizations with exposure to semiconductor equipment, advanced packaging, medical devices, and high-temperature power electronics, the coming 18–24 months will be decisive for supplier qualification, capacity alignment and product-roadmap choices.
Why this report matters to 2026 strategic planning
- Actionable forecasting: The report translates growth trajectories into purchase‑level scenarios and capacity stress tests that help procurement and operations teams size buffer stocks, rework lead‑time assumptions, and prioritize second-source qualifications.
- Investment clarity: Corporate development and finance teams receive an invest-or-wait framework calibrated to AlN-specific R&D costs, expected margin dynamics, and market concentration trends — enabling disciplined capex and M&A screening for 2026 budgets.
- Risk-to-opportunity mapping: We map the upstream supply risks (feedstock availability, sintering capacity, multi-zone module complexity) into tangible mitigation options and commercial approaches — for example, how to partition sourcing between high‑conductivity suppliers and flexible custom-component shops.
- Technology roadmap alignment: Product and process teams gain a view of which heater architectures (multi‑zone, embedded sensors, thick‑film patterns) are passing from niche to mainstream, and how that evolution should affect validation programs and product launch timing.
Headline findings (selective, non‑exhaustive)
- Sustained mid-single-digit growth: Demand is driven by capital spending cycles in semiconductor fab equipment and by increasing thermal management needs in next‑gen power electronics and medical devices. The model’s 7.2% CAGR embeds scenarios for cyclical semiconductor demand as well as secular growth from adjacent spaces.
- Near-term capacity shifts matter: Capacity expansions announced and completed by established ceramic manufacturers materially change lead-time and price elasticity in the short term; buyers who act early can lock favorable terms or secure priority allocations.
- Modular, sensor‑integrated heaters are ascending: Designs that integrate multi‑zone control and embedded temperature sensing reduce process cycle variability and are being adopted faster in advanced node and ALD/PECVD toolsets.
- Fragmentation creates both risk and optionality: A market without a handful of overwhelming incumbents means opportunities for supply diversification and M&A, but it also increases the need for rigorous supplier qualification and quality assurance processes.
Report contents — the practical toolkit inside
To equip decision-makers for 2026, the full report is organized as an operational playbook rather than a high-level summary. Highlights include:
Aluminum Nitride Ceramic Heaters Market
- Methodology and market-sizing mechanics: detailed assumptions, primary interview framework and sensitivity analyses so you can replicate or update the model for bespoke scenarios.
- Demand segmentation framework: demand drivers by end-market and heater architecture, with scenario variants tied to semiconductor capex cycles, medical device adoption rates and power-electronics conversion timelines.
- Supply-chain map and capacity tracker: verified supplier capabilities, manufacturing methods, typical lead times, and a framework to evaluate single‑sourced vs diversified supply strategies.
- Competitive benchmarking: comprehensive profiles of active suppliers, innovation focus, manufacturing strengths, and recent capacity or product announcements—scored for fit against different buyer personas.
- Pricing and margin model: indexed price curves by heater complexity with a stress-testing feature for raw-material and energy-cost shocks.
- Commercial playbooks: supplier selection scorecards, qualification roadmaps, procurement contract templates and negotiation levers customized to AlN heaters.
- M&A and partnership screeners: high‑probability target profiles, valuation multiples observed in analogous ceramic and thermal‑management transactions, and a short-listing methodology for bolt-ons or strategic JV partners.
- Implementation appendices: sample test protocols, cleanroom integration checklists, and regulatory considerations specific to semiconductor and medical environments.
Competitive landscape — interpreting supplier moves
The report dissects the supplier ecosystem and profiles the market’s most consequential participants — from legacy ceramic specialists to niche technology suppliers. While the space remains fragmented (enabling buyers to assemble multi‑source networks), several firms stand out for distinct capabilities that shape strategy:
Aluminum Nitride Ceramic Heaters Market
- Leading ceramic specialists with deep high‑purity AlN expertise — strong in multi‑zone, custom heater modules for CVD/ALD applications and high-volume fab qualification programs.
- Global manufacturers investing in capacity expansion for larger wafer formats and higher throughput, which affects availability and qualification timelines for 300 mm and advanced packaging lines.
- Component-focused firms delivering differentiated approaches — hot‑pressed vs direct‑sintered production, thick‑film patterning, and embedded sensor integration — each technology path introduces different cost, lead time and performance trade-offs.
- Regional and emerging suppliers who provide nimble customization and favorable lead times for small‑batch needs, but require tighter incoming quality controls when integrated into critical process tools.
Our company-by-company analysis highlights where each supplier plays to win — for example, who is prioritizing high‑thermal‑conductivity substrates, who has scale for large‑format plates, and which firms are building embedded‑sensor heater lines. These profiles include operational footprints, recent capacity moves, and technology roadmaps to support supplier selection and partnership decisions.
Strategic implications — a focused 90‑day playbook for 2026
- Immediate (0–30 days): run a supplier risk assessment using our template; identify single-source exposures and flag critical long‑lead items for expedited qualification.
- Near term (30–90 days): initiate parallel qualification programs with a high‑conductivity incumbent and a nimble regional manufacturer; negotiate optionality in pricing and capacity commitments tied to milestone triggers.
- Medium term (90–180 days): evaluate M&A or strategic partnerships for upstream control of specialty AlN processing or for access to proprietary multi‑zone module designs that shorten customer qualification cycles.
- Cross‑functional: align procurement, R&D and operations on a single set of heater-performance KPIs, incorporating thermal uniformity, drift, and embedded-sensor fidelity into acceptance criteria to reduce iteration during tool integration.
Who should read this report
- CEOs and business-unit leaders planning market-entry, capacity or M&A moves in thermal management or semiconductor suppliers.
- Procurement and supply‑chain executives needing a clear, actionable qualification and sourcing plan for high‑reliability heater components.
- R&D and product teams seeking insight into which heater architectures will become standard in next‑gen tools and how to align validation timelines.
- Private equity and corporate development teams screening targets in advanced ceramics, thermal‑management components, or specialty manufacturing assets.
Why PW Consulting
PW Consulting’s research combines primary interviews with suppliers, OEMs and fab tool integrators, a rigorous bottom‑up sizing methodology, and scenario stress‑testing for capital and operational risks. Our objective is not only to quantify market momentum (the aggregated market model summarized earlier) but to convert that intelligence into executable commercial and technical plans that buyers and investors can apply immediately.
Next steps and how to access the full intelligence
This release is a strategic preview intended to demonstrate the report’s depth and relevance while preserving the proprietary segmentation tables, supplier scorecards, and primary‑data appendices that underpin 2026 decision-making. The full report contains the granular regional, application and product‑type breakdowns, company financial overlays, price‑by‑architecture models and primary interview transcripts required to operationalize the insights above.
To obtain the full Aluminum Nitride Ceramic Heaters Market report, including downloadable models and supplier benchmarking tools, please visit our report page or contact PW Consulting’s commercial team for a briefing and sample extracts tailored to your use case.
For detailed analysis of this topic, please visit the official page: Aluminum Nitride Ceramic Heaters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com