

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Aluminium‑Scandium Market to Grow at a 6.8% CAGR, Signaling Strong Upside

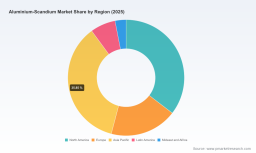
Aluminium-Scandium Market: Strategic Outlook for 2026 — PW Consulting Industry Brief
Executive summary
PW Consulting’s Aluminium-Scandium Market report (base year 2025) frames a fast-evolving specialty-metal landscape that is moving from niche R&D towards early-stage commercialisation. Our analysis shows the market expanding from an estimated USD 52.72 Million in 2020 to USD 73.19 Million in 2025, and — under central-case assumptions — tracking to approximately USD 114.85 Million by 2032, representing a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. This trajectory is driven by concurrent technological readiness in powder metallurgy and additive manufacturing, shifts in defence and aerospace procurement, and policy measures targeting critical minerals.
Aluminium-Scandium Market
This industry brief distils the report’s strategic value for corporate decision-makers in 2026: it highlights where near-term commercial opportunities exist, what supply-side risks deserve immediate attention, and which organisational choices will determine whether companies capture disproportionate upside as the market commercialises.
Aluminium-Scandium Market
Why this matters for 2026 corporate strategy
-
Timing matters: The sector is at an inflection point where lab-scale advantages can translate into commercial differentiation. Early commercial entrants that lock supply or secure preferred manufacturing pathways can establish cost and capability advantages that are difficult to erode later.
Aluminium-Scandium Market -
Cost and input risk are material: Industry data point to significant raw-material cost pressure, with scandium oxide pricing substantially elevated. These input dynamics amplify the importance of procurement strategy, long-term contracts, and alternative sourcing or recycling pathways.
-
Policy-driven demand: Scandium’s designation as a critical mineral in key markets is already reshaping incentives and permitting pathways, creating distinct advantages for companies positioned to capitalise on domestic-production incentives and supply-chain de‑risking programmes.
-
Technology bifurcation: Two technology trajectories are emerging — high-scandium feedstocks enabling specialised high-performance components, and low-scandium alloys and master-alloy routes focused on cost-effective property enhancement. Each route implies different business models and commercial partners.
-
Consolidation window: Market structure shows a small set of capable suppliers and an expanding group of specialised producers. The next two years are likely to see alliance activity, capacity investments, and selective M&A as incumbents and new entrants pursue scale and vertical integration.
What the full report delivers (practical content for executives)
-
Transparent market sizing and forecasting models calibrated to 2020–2025 historicals and projecting through 2032; downloadable, model-ready files for CFOs and strategy teams to stress-test assumptions against their own scenarios.
-
Supply-chain mapping that identifies mining, by-product recovery, master-alloy production, powder manufacturing, and downstream fabrication nodes — with risk scores and mitigation playbooks for each node.
-
Go-to-market playbooks for manufacturers and component suppliers, including cost-to-serve templates, partnership archetypes for powder and casting suppliers, and commercial pilot guidance for additive manufacturing (AM) adoption.
-
Investment-grade vendor due diligence frameworks that evaluate metallurgy readiness, production scalability, quality controls, and IP risks — actionable checklists that accelerate vendor selection cycles.
-
Regulatory and incentives digest that synthesises critical-mineral policies and financial incentives across major jurisdictions, and their likely impact on project economics and sourcing strategies.
-
Scenario-based pricing and profitability models, including sensitivity to scandium-oxide price shocks, alloy formulation choices, and differing adoption rates across core end markets.
Competitive landscape — key players and strategic implications
Our competitive analysis focuses on a mix of technology innovators, specialised alloy producers, and upstream scandium suppliers. Rather than presenting exhaustive scorecards in this brief, the following highlights the strategic positioning of select companies that are shaping the market dynamics.
-
Metalysis (United Kingdom) — Metalysis has signalled a step-change by moving into commercial production of high-scandium-loading aluminium-scandium powder, with technical capability to deliver very high scandium content feedstock. For corporate buyers focused on semiconductor, aerospace, and defence applications, Metalysis represents a potential strategic partner for high‑value, performance‑critical parts. Their entry accelerates the timeline for advanced applications where scandium’s property improvements are mission‑critical.
-
NioCorp Developments Ltd. (United States) — NioCorp’s recent casting milestone with a US foundry demonstrates commercial-readiness for low-scandium castings. This development is important for OEMs contemplating component-level substitution that balances cost with property gains. NioCorp’s pathway underlines the practical viability of master-alloy and casting routes as near-term commercial options.
-
IBC Advanced Alloys (United States) — Foundry and casting capabilities paired with additive-manufacturing services place IBC as an integrator for customers seeking component prototyping and qualification. Their role emphasises the importance of collaboration between powder producers and fabricators.
-
Stanford Advanced Materials, AEM REE, Edge Tech Industries, Scandium International Mining Corp. — These suppliers together illustrate the global patchwork of alloy providers and upstream master-alloy producers. Their varying geographic footprints and product ranges create opportunities for buyers to optimise cost, lead time, and technical fit — but they also require robust supplier assessment given heterogeneous quality standards and capacity constraints.
Recent industry developments underscore the move from demonstration to commercial application: successful low‑scandium casting initiatives and the start of high‑scandium powder production are tangible signals that both price‑sensitive and performance‑driven value chains are preparing to scale. For strategists, the implication is clear — partnerships and offtake agreements signed in 2026 will materially influence commercial access and margin profiles over the next three to five years.
Supply dynamics, pricing pressure, and strategic responses
-
Input exposure: Scandium oxide pricing is high relative to other alloying elements, and primary supply remains constrained because much of global scandium supply emerges as a by‑product of nickel laterite processing. This combination increases the probability of price spikes and supply interruptions, necessitating procurement strategies that go beyond spot buying.
-
Mitigation levers: Executives should evaluate a portfolio of responses — long‑dated offtake agreements, equity stakes in upstream recovery projects, offtake‑plus‑processing partnerships with master-alloy producers, and investment in recycling streams to recapture scandium from end-of-life components.
-
Cost engineering: Alloy design and process optimisation can materially influence per‑part scandium consumption. R&D investments into lower‑content alloys that retain critical property benefits, or into deposition and powder‑usage efficiencies in AM, can reduce sensitivity to raw‑material price volatility.
Commercial and investment playbook for 2026
Companies considering entry or expansion into aluminium‑scandium value chains should prioritise a compact set of actions for 2026 that align operating choices with the projected market growth profile:
-
Fast-track commercial pilots with both high‑scandium and low‑scandium suppliers to understand processing tolerances, qualification timelines, and total landed cost across candidate supply chains.
-
Secure a dual sourcing architecture that blends a high‑purity powder supplier for performance-critical parts with master-alloy or casting partners for higher-volume, lower-cost components.
-
Embed price‑and‑supply stress tests into capital expenditure cases. Given the market’s projected CAGR and size profile, small changes in input cost can swing margin outcomes for early movers.
-
Pursue selective vertical integration or strategic equity positions in upstream recovery projects where incentives and national policy support make domestic supply more bankable.
-
Prioritise qualification pathways for aerospace and defence customers, as these sectors often act as technology validators whose adoption accelerates broader commercial acceptance.
How PW Consulting supports executive action
Our full report is structured as an execution playbook for 2026 decisions. We provide executive-ready deliverables including:
-
Interactive financial models and scenario tools that let you test price, adoption, and technology pathways against corporate KPIs.
-
Supplier due diligence templates, quality‑assurance checklists, and contract term recommendations calibrated to scandium risk profiles.
-
Commercial pilot roadmaps and benchmarking matrices for additive and casting workflows, including recommended timelines for qualification and scaling.
-
M&A and partnership advisory support — from target screening through negotiation and integration planning — informed by our proprietary market-sizing and competitive-intensity analytics.
Next steps and call to action
For executives preparing capital and commercial plans in 2026, the window to secure advantaged positions in the aluminium‑scandium value chain is immediate and finite. PW Consulting’s Aluminium‑Scandium Market report packages the market intelligence, risk frameworks, and execution templates you need to move decisively while protecting downside.
To access the full dataset, vendor scorecards, and the downloadable scenario model, please visit our report page where you can request the complete study and bespoke advisory support tailored to your organisation’s strategy.
For detailed analysis of this topic, please visit the official page: Aluminium-Scandium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com