

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Ships Turbocharger Market to Expand at a 5.3% CAGR, New Insight Reveals

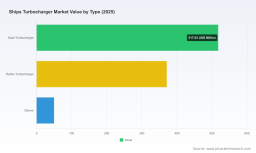
Ships Turbocharger Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s new Ships Turbocharger Market report (base year 2025) delivers the strategic market intelligence that executives, product leaders, and corporate development teams need as they set priorities for 2026. The global ships turbocharger market was valued at USD 939.38 Million in 2025 and, under our central forecast, is expected to expand at a 5.3% CAGR through the 2026–2032 period, reaching approximately USD 1,369.93 Million by 2032. This briefing summarizes the report’s strategic implications and highlights the practical, decision-ready outputs that the full study delivers—while intentionally reserving the granular splits and proprietary scenario tables for report subscribers.
Ships Turbocharger Market
Why this market matters now — context for 2026 strategy
- Regulatory tightening is a growth engine and a risk filter. IMO Tier III, MARPOL Annex VI provisions, US EPA alignments, EU equipment type-approval rules and USCG requirements are forcing integration of after-treatment strategies with turbocharger designs. Companies that embed compliance into product roadmaps will convert regulation from a cost center into a barrier to entry for competitors.
- Steady, predictable growth enables differentiated plays. A mid-single-digit CAGR makes capex-intensive initiatives (new product lines, factory upgrades, after-sales networks) financially justifiable when prioritized against high-return retrofit and service segments.
- Service and lifecycle revenue are strategic priorities. Turbocharger manufacturers are moving beyond OEM sales toward service contracts, digital predictive maintenance and retrofit solutions—models that improve margin visibility and customer stickiness.
- Technology convergence is reshaping product requirements. Demands for lower emissions, higher fuel flexibility (including e-fuels), and tighter integration with engine control/connectivity systems are changing turbocharger design trade-offs—favoring modular, serviceable, and software-enabled products.
Data-driven signals that should guide 2026 choices
- Scale plus specialization wins. The market’s overall trajectory is clear: steady expansion from 2026 onward. However, market concentration metrics show room for specialist players—CR3 stands at 30% and CR5 at 45%—indicating a competitive environment where global platform leaders coexist with high-margin niche suppliers. Strategic implication: pursue either scale-driven efficiency or technical differentiation (not a middle-of-the-road position).
- Aftermarket and services are the margin engine. Our demand modelling indicates aftermarket activities—maintenance, spares, upgrades, and service contracts—drive disproportionately higher margin and predictable revenue compared with initial OEM sales. For 2026 planning, invest in field service networks, digital condition monitoring, and bundled service offers.
- Retrofit demand will be a near-term catalyst. Emissions-driven retrofits, plus conversion opportunities tied to fuel transitions, present higher-margin, lower-capex growth levers than newbuild cycles alone. Companies with retrofit product portfolios and retrofit-capable certifications will capture outsized share of the early-adopter retrofit installs.
- Regulatory approvals and OEM certifications are commercially decisive. Recent approvals and type-endorsements materially shorten procurement cycles and enable entry into key fleets. Certification strategy must be front-loaded in product launch roadmaps to avoid missed revenue windows in 2026–2027.
Competitive landscape — what the report reveals (high-level)
The competitive map combines capability profiles, go-to-market footprints, and recent tactical moves to indicate where supplier advantage is developing. The market is balanced between legacy engine-system integrators, specialist turbocharger builders, and power-systems conglomerates pursuing vertical integration.
Ships Turbocharger Market
- Accelleron / ABB-linked expertise (Switzerland). Accelleron remains highly active—documented product approvals for auxiliary-engine MXP series, a new low-speed ACCX300-L launch, and milestone order volumes for A100-L/A200-L series. These moves underpin a dual strategy: defend core low- and medium-speed turbo business while monetizing aftermarket services and digital care packages. Their recent multi-year service agreements demonstrate a deliberate shift to recurring revenue.
- Mitsubishi Heavy Industries (MET series, Japan). MHI’s MET line continues to benefit from licensing and local production arrangements that expand reach into regional shipbuilding clusters. Licensing is a lower-capex route to share technology while preserving incremental service spares and retrofit opportunities.
- MAN Energy Solutions (Germany). MAN’s cross-domain capability—covering low-, medium-, and high-speed diesel and gas engines—gives it advantages in systems integration and aftermarket service bundling. For companies planning platform plays, MAN exemplifies how engine-turbo integration can be leveraged to protect installed-base revenues.
- IHI and Everllence (Japan/Germany). These specialists emphasize reliability and maintainability in marine conditions, tailoring offerings toward fleets with high uptime demands. Their focus on ease-of-service and flexible maintenance contracts makes them credible alternatives for operators prioritizing operational continuity.
- Cummins (USA). Cummins leverages engine-turbo synergies and genset integrations to capture propulsion and auxiliary power needs—especially in niches where integrated propulsion/genset packages are procured.
Strategic takeaway: incumbents with certification depth and aftermarket coverage will continue to capture premium share, but mid-sized specialists with retrofit capabilities and rapid type-approval strategies can outpace larger rivals in targeted segments.
Ships Turbocharger Market
Regulatory and technological tailwinds — practical implications
- Integration with after-treatment is non-negotiable. Because IMO Tier III and related rules mandate after-treatment for many marine engines, turbocharger designs must be optimized for exhaust system integration. Product design teams must prioritize thermodynamic compatibility and pressure-drop minimization while ensuring serviceability.
- Type-approval timelines are strategic milestones. EU Medical Approval-style processes (e.g., Marine Equipment Directive) and USCG/EPA alignments can extend time-to-market. Firms must plan certification campaigns in Q1–Q2 2026 to align commercial launches with buying cycles.
- Fuel diversity requires flexible architectures. As fleets evaluate low-carbon fuels and e-fuels, turbochargers must accommodate broader operating envelopes. Modular turbine and compressor mapping, paired with adaptable control software, will be differentiators.
What PW Consulting’s report delivers — actionable contents
The full report is built as a toolkit for executives making 2026 commitments. Key deliverables include:
- Market model and forecasts (2020–2025 historical base; 2026–2032 scenarios) with sensitivity analyses for slow/fast decarbonization pathways.
- Competitive scorecards covering product portfolios, certification status, aftermarket reach, and strategic initiatives for leading suppliers.
- Regulatory impact matrix linking regional rule sets to product design and certification needs, with timelines to prioritize approvals in 2026.
- Go-to-market playbooks for OEMs, aftermarket specialists, and new entrants—detailing pricing strategies, service-pack design, retrofit sales sequences, and platform partnerships.
- Supply-chain risk assessment and mitigation options (contract manufacturing, dual-sourcing, critical raw-material exposure), including quantified lead-time and margin impacts under alternate sourcing scenarios.
- Deal-sourcing shortlist and valuation heuristics for acquisition targets that deliver immediate service network access, certification portfolios or retrofit product lines.
- Implementation checklists for product managers: certification milestones, type-approval sequencing, and launch budget templates.
To preserve the strategic value of the dataset, the report reserves granular regional, type and application-level revenue splits and pricing benchmarks for subscribers. Those details include the differentiated revenue pools and retrofit addressable market metrics that materially influence go/no-go investment decisions; they are essential inputs to any acquisition or product-capex model.
Immediate recommendations for 2026 planning
- Prioritize certification and retrofit product readiness. Time-to-approval will determine 2026–2027 revenue windows—start certification workstreams now.
- Rebalance spend toward aftermarket and digital services. Allocate a higher proportion of marketing and field-engineering budgets to service conversion programs where payback is most rapid.
- Pursue targeted partnerships rather than broad-scale M&A. Licensing, regional manufacturing agreements and service alliances can deliver market access with lower capital outlay and faster execution than full acquisitions in 2026.
- Stress-test supply chains for material and lead-time shocks. Build contingency plans for critical components and consider contractual safeguards with key suppliers.
Conclusion — the strategic edge PW Consulting offers
With the ships turbocharger market on a steady mid-single-digit growth path and regulatory forces raising technical thresholds for entry, 2026 is a pivotal year for strategic positioning. PW Consulting’s Ships Turbocharger Market report equips decision-makers with a blend of quantitative forecasting, certification-timeline intelligence, supplier benchmarking, and transaction-ready recommendations. The study is designed to convert market signals into executable corporate priorities—while the full, subscriber-only datasets provide the segmented revenue breakdowns and scenario tables required to finalize budgets, acquisition models, and product roadmaps.
For companies aiming to convert regulatory change into commercial advantage in 2026, the time to act is now. Access the full report and the proprietary data tables on the PW Consulting website to obtain the granular intelligence needed to finalize strategic commitments.
For detailed analysis of this topic, please visit the official page: Ships Turbocharger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com