

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vanilla Market Poised for Robust Expansion — 5.69% CAGR Forecast Through 2032

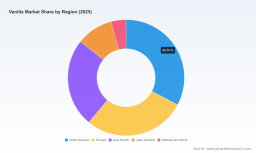
Vanilla Market 2026: Strategic Imperatives from PW Consulting’s Vanilla Market Report (Base Year 2025)
Executive summary
PW Consulting’s Vanilla Market report, anchored on a 2025 base and projecting through 2032, provides a compact, action-oriented intelligence package for C-suite leaders, procurement heads, R&D executives, and M&A teams. The global vanilla market — measured in USD million — is on a clear upward trajectory, expanding at a compound annual growth rate (CAGR) of 5.69% across our 2026–2032 forecast window. From a market size of USD 3,850 million in 2025, our modeling anticipates growth to roughly USD 5,810 million by 2032. This growth momentum, however, sits atop a complex mix of supply-side normalization, price volatility, regulatory shifts, and strategic moves by ingredient houses and global flavor houses. The report is structured to help executives translate these dynamics into confident 2026 decisions — from sourcing and hedging to product formulation and partnership strategies.
Vanilla Market
Why this report matters for 2026 decisions
-
Timing and clarity: 2026 is a pivot year where structural changes in origin markets and buyer strategies converge. The report decodes the near-term implications of origin policy shifts, pricing normalization and raw-material availability — enabling procurement teams to move from reactive buying to strategic contracting.
Vanilla Market -
Investment read-across: For investors and M&A teams, the market’s steady mid-single-digit CAGR combined with a low-to-moderate concentration profile indicates pockets of consolidation opportunity, particularly among origin-integrated processors and premium natural players. The report provides a practical framework to size targets and validate growth synergy assumptions without exposing proprietary subsegment metrics.
Vanilla Market -
Product strategy: For product and R&D leaders, the intelligence translates macro supply trajectories into formulation scenarios that respect label trends (natural, organic, fair-trade) while buffering margin impacts from commodity swings.
Market trajectory and headline numbers
Using 2025 as the base year, our topline market sizing shows an ascent from USD 3,850 million (2025) to an estimated USD 5,810 million by 2032, driven by steady consumption growth, premiumization in food and beverage segments, and expanded use in adjacent applications. The forecast period — 2026 to 2032 — reflects a modeled CAGR of 5.69%, calibrated against historical trends from 2020–2025 and stress-tested under multiple origin-price and demand scenarios. These high-level projections are intended to guide strategic planning and scenario modeling; the report itself contains the detailed models and sensitivity runs that subscribers can use to align procurement windows, price corridors, and product roadmaps.
Supply-side dynamics: what is changing at origin
-
Origin pricing normalization: After several years of extreme price volatility, export prices from leading originating countries retreated in 2025 to a wider range. Coupled with a dismantling of certain export levies and liberalization measures, these moves are restoring transactional transparency but also introduce new short-term pricing floors and ceilings for buyers to manage.
-
Harvest and inventory context: The 2025 harvest outlook from primary producing regions returned notable volumes, contributing to a global supply pool that, at a headline level, outpaced near-term demand and created a measurable oversupply. This has immediate implications for inventory strategy — firms that can flexibly scale storage and roll-over commitments will gain negotiating leverage in 2026.
-
Trade and tariff shifts: Recent tariff policy adjustments — including reductions in reciprocal tariffs by major importers — have improved cross-border flows and reduced landed cost uncertainty for certain buyer groups. Buyers should reassess landed-cost models and origin diversification plans in light of these trade policy changes.
Market dynamics in context — datapoints that matter
-
US import flows: US imports from key origins remain sizable and, in 2025, posted notable import values that reflect both industrial-scale demand and retail channel restocking patterns. This underlines the United States’ continued strategic weight for global vanilla flows and the need for global suppliers to maintain robust North American distribution strategies.
-
Price band volatility: Export price ranges observed in 2025 demonstrate that commodity-grade vs. premium-grade differentials remain pronounced. Supply agreements should therefore be structured with grade-linked indexing or blended supply clauses to avoid margin erosion.
-
Origin policy shifts: Some producing-country reforms in 2025 removed fixed export fees and introduced market reference benchmarks. These policy moves reduce distortions but increase the need for on-the-ground market intelligence — a capability many global buyers are strengthening via direct sourcing partnerships.
Competitive landscape — who matters and why
The vanilla market remains fragmented relative to many other flavors and botanicals. Our concentration analysis shows a top-three share (CR3) in the low twenties and a top-five share (CR5) in the high twenties — signaling meaningful room for mid-market specialists and origin-integrated players to sustain differentiated growth.
-
Nielsen-Massey Vanillas — A legacy specialist focused on pure extracts, pastes and flavors with strong brand recognition in premium retail and culinary channels. Their emphasis on organic and sustainably sourced offerings positions them well for value-seeking premium consumers.
-
Heilala Vanilla — An origin-specialist with strong Pacific sourcing credentials; its focus on sustainable production and awards-based product positioning supports targeted premium playbooks.
-
Eurovanille — Long-standing European player serving professional chefs and food manufacturers; the firm’s premium bean and powder capabilities remain a trusted supply point for high-margin applications.
-
McCormick & Company — Global scale and retail reach with diversified spice and extract portfolios; McCormick’s integration across channels makes it a keystone competitor for branded and private-label offerings.
-
Givaudan, Symrise, IFF, ADM — These global ingredient houses combine R&D, origin programs and sustainability initiatives. They are rapidly investing in origin infrastructure, science-led flavor development, and forward contracts to secure differentiated supply. Recent capital deployments and innovation center openings at origin illustrate a strategic shift toward on-the-ground, climate-resilient sourcing partnerships.
Notably, in May 2026 a leading global flavor house opened a Vanilla Innovation Center in Madagascar — an example of origin-proximate investment intended to accelerate quality improvement, climate adaptation and applied R&D. Such moves raise the bar on vertical integration and speed to market for novel natural solutions.
Report contents — what you will find (and what we deliberately withhold in this summary)
-
Proprietary market model: Topline and scenario-driven forecasts (2026–2032) with downloadable model files for buyer-specific scenario stress tests.
-
Supply-chain maps: Origin-to-consumer flow diagrams, cost-to-serve benchmarks, and validated supplier scorecards to accelerate vendor selection.
-
Procurement playbooks: Practical contract structures, hedging templates, and inventory optimization matrices tailored to vanilla’s grade and quality profiles.
-
Commercial playbooks: Go-to-market approaches for premiumization, clean-label reformulation strategies, and channel-specific margin models.
-
Risk register & early-warning indicators: A prioritized list of origin, climate, regulatory and logistics signals that should trigger immediate buyer action.
-
Competitive dossiers: Strategic profiles and capability maps for incumbent players and potential challengers. (Note: detailed subsegment tables and granular regional/application splits are reserved for the full report to preserve proprietary benchmarking integrity.)
Practical strategic recommendations for 2026
-
Move from ad-hoc spot buying to layered contracting: Use a blended approach of short-term spot, medium-term fixed-price windows and origin-linked indexed contracts to capture price troughs while ensuring continuity.
-
Invest in origin partnerships: Work with suppliers and international ingredient houses that demonstrate origin presence and climate-resilience programming, including farmer training and traceability systems.
-
Design product-level margin buffers: For higher-risk premium formulations, build flexible formulations and alternative flavor blends to protect margin when primary-origin premiums spike.
-
Operationalize early-warning indicators: Integrate the report’s risk indicators into procurement dashboards so that harvest, trade policy, and price-band signals automatically adjust reorder points and hedging triggers.
-
Consider strategic M&A or JV: Given moderate market concentration and differentiated capabilities across origin integrators and flavor houses, small, focused acquisitions can provide access to origin supply, proprietary extracts and enhanced sustainability credentials.
How to use this intelligence in your 2026 planning cycle
-
Procurement: Re-run the included forecast scenarios against your current contract book to derive an optimal mix of spot vs. contracted volumes for H1 and H2 2026.
-
R&D and Marketing: Use the formulation playbooks to prioritize SKU rationalization and to design label claims that align with evolving retail and regulatory expectations.
-
Corporate Strategy & M&A: Apply the competitive mapping and valuation heuristics to shortlist acquisition targets and JV opportunities with quick wins in origin control or premium product channels.
Final note — the trailer principle in action
This article surfaces the strategic themes, headline numbers and the operational levers that will matter in 2026. PW Consulting’s full Vanilla Market report contains the complete dataset, sensitivity models, supplier scorecards and granular regional/application breakouts that are essential for execution. We have intentionally withheld fine-grained subsegment figures and proprietary tables from this press release to preserve the actionable advantage subscribers receive. Visit our report page to access the full intelligence package, licensing options, and a customized briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Vanilla Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com