

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Scent Machines Market Poised for a Robust 14.3% CAGR Through 2032
By pmarketresearch, 2026-06-30
PW Consulting: Strategic Brief — Scent Machines Market Outlook (Base Year 2025) and Why This Matters for 2026 Decision-Making
PW Consulting today publishes a strategic briefing on the global Scent Machines market designed for executive teams preparing 2026 portfolios, product roadmaps, and go-to-market plays. Anchored on a comprehensive base year (2025) analysis and a proprietary forecasting framework covering 2026–2032, the brief synthesizes macro performance, competitive motion, regulatory headwinds, and practical playbooks that enterprises can deploy immediately. The market’s robust compound annual growth rate (CAGR) of 14.3% underpins a multi-year opportunity: the sector expanded from roughly USD 603 million in 2020 to USD 1,132 million in 2025, is projected to exceed USD 1,336 million in 2026 and is modeled to approach USD 2,868 million by 2032. This trajectory creates clear inflection points for investment, partnership, and product differentiation in 2026.
Scent Machines Market
Why this briefing is strategically relevant for 2026
- Decisive timing: 2026 sits at the junction between recovery-driven purchases and a technology-driven second wave of adoption—executives who act this year can secure channel positions and technological IP that will compound over the forecast window.
- Scale and velocity: With a mid-teens CAGR, the market is not only expanding but doing so quickly enough that first-mover advantages in software-enabled features, compliance-ready product lines, and channel exclusives will yield durable returns.
- Cross-functional impact: Decisions in R&D, procurement, compliance, and commercial strategy reverberate across operating models—this briefing translates those interdependencies into an executable 12- to 36-month roadmap.
Top strategic plays for 2026
- Product bifurcation: platform vs. consumable. Prioritize development of scent-delivery platforms that lock-in recurring consumable revenue (refills, fragrance cartridges, maintenance contracts) while keeping a modular hardware platform to accelerate upgrades and reduce customer switching costs.
- Embed software and services. Deploy or partner for app controls, usage analytics, and subscription management. Smart features increase wallet-share in both commercial and residential channels and create data assets that improve SKU economics.
- HVAC and systems integration. For B2B vendors, invest in compatible HVAC integration kits and certified installation programs—these increase ASPs and establish service revenue lines that outlast single-unit sales.
- Compliance-by-design. Reengineer formulations and materials to preempt tightening VOC regulations, particularly in major regulatory jurisdictions. Compliance can be a market differentiator and reduce go-to-market friction for large institutional customers.
- Supply-chain hedging for fragrance inputs. Essential oils and fragrance compounds are commodity-exposed. Secure diversified supplier contracts and consider financial hedges or strategic inventory positions to buffer margins in 2026–2027 when volatility is most acute.
- Labor strategy: certify and scale technician networks. Specialized installation and maintenance skills command premium wages. Build certified installer programs to control service quality and cost, and to present an attractive channel proposition to enterprise buyers.
- M&A and partnership filters. Target bolt-on acquisitions that accelerate digital control, proprietary fragrance IP, or channel access in hospitality and healthcare—sectors where demonstrable ROI can justify a premium.
What’s inside the full PW Consulting report (practical and operational modules)
Beyond headline forecasting, the report contains tools and playbooks designed for direct operational use by executives and strategy teams:
Scent Machines Market
- Interactive financial model (Excel): Base-year (2025) calibrated model with scenario switches for growth, price, and margin levers across 2026–2032 to stress-test investment cases.
- Go-to-market playbook: Channel mixes, pricing archetypes, and contract structures for commercial, hospitality, healthcare, and residential segments—what to pilot first and how to scale without eroding margin.
- Supplier risk matrix: Mapping of critical raw-material exposure, alternative sourcing options, and cost-sensitivity thresholds.
- Regulatory compliance checklist: Actionable steps to achieve compliance in major jurisdictions and design choices that minimize product rework cycles.
- Installation & service blueprint: Certification pathways and cost-to-serve models for building a profitable service arm at scale.
- Competitive playbook: Tactical options for incumbent defense, challenger disruption, and white-label OEM strategies (summary qualitative analysis included; full competitive matrices available in the premium report).
Competitive landscape — what the field looks like entering 2026
The Scent Machines market is a mix of established commercial incumbents, nimble consumer-tech challengers, and specialized regional players. Key firms to watch include:
Scent Machines Market
- ScentAir Technologies, LLC (Charlotte, NC) — A long-standing player focused on commercial and hospitality deployments, HVAC-integrated solutions, and proprietary fragrance portfolios. Their recent milestone anniversary underscores sustained distribution reach and brand trust among enterprise buyers.
- Aroma Retail LLC (Las Vegas, NV) — A consumer- and small-business-oriented innovator prioritizing smart app-controlled machines and waterless diffusers; recent catalog updates signal continued investment in connected features and fragrance variety for the home market.
- MScents Pte Ltd (Singapore) — Concentrated on ultrasonic and HVAC diffusers for larger commercial spaces; new model introductions indicate a push to capture enterprise-scale deployments across APAC and beyond.
- Air-Scent International (United States) — Focuses on ambient diffusion and odor-control formulations; product breadth and formulation IP are their core competitive assets for retail and facility-management channels.
- AERON Lifestyle Technology, Inc. (Fairfield, IA) — Specializes in automotive and ergonomic scent diffusion, with recent patent grants reinforcing a competitive edge in vehicle and ergonomic applications.
Recent market moves — model launches, patents, and catalog refreshes — point to a bifurcated market: one track dominated by commercial solutions (scale, service, and compliance) and another driven by consumer/SMB innovation (connectivity, design, and convenience). This creates clear acquisition and partnership opportunities for companies seeking to cross from one track into the other.
Market dynamics and the risk-management playbook
Our analysis highlights four dynamics that materially affect 2026 decisions and require active mitigation:
- Raw material volatility: Fragrance and essential-oil pricing are exposed to macro commodity swings. Mitigation: diversify suppliers, negotiate index-linked contracts, and maintain critical safety stock for high-turn SKUs.
- Regulatory tightening: Emerging VOC restrictions and indoor-air-quality policies are reshaping allowable formulations in certain jurisdictions. Mitigation: adopt a compliance-by-design approach, invest in low-VOC formulations, and develop transparent safety data sheets to shorten procurement cycles with institutional buyers.
- Reimbursement and ROI-driven procurement: Healthcare and hospitality buyers increasingly monetize indoor-environment improvements. Mitigation: produce case studies and measurement frameworks that quantify outcomes (e.g., guest satisfaction, reduced complaints, potential reimbursement) to accelerate enterprise contracts.
- Skilled labor and installation costs: Certified technicians for HVAC-integrated systems command premium pay. Mitigation: create tiered service offerings, invest in remote diagnostics, and explore certified-partner networks to control fixed labor costs.
How different corporate functions should use this briefing in 2026
- CEO / Board: Use the forecast and sensitivity model to set strategic investment cadence—prioritize platform-to-consumable paths and targeted M&A.
- Product & R&D: Accelerate low-VOC formulations and modular hardware that supports SaaS-enabled upgrades; prioritize interoperability with HVAC systems and voice/app ecosystems.
- Commercial & Sales: Pilot bundled subscriptions with hospitality groups and healthcare systems that can be scaled nationally.
- Procurement: Secure multi-year supply agreements with price-adjustment clauses and onboarding alternative suppliers for critical fragrances.
- Compliance & Legal: Implement a regulatory watch program around VOC restrictions and develop a rapid-response product remediation protocol.
90/180/365 day activation roadmap
- 0–90 days: Run a rapid diagnostic using the report’s assessment templates—identify highest-value product lines and immediate supplier risks.
- 90–180 days: Launch 1–2 market pilots (one commercial, one consumer) emphasizing connected features and compliance-ready formulations; begin certification of installer partners.
- 180–365 days: Scale successful pilots, negotiate strategic supply and channel partnerships, and evaluate targeted M&A to fill capability gaps.
Conclusion — what you gain and where to go next
PW Consulting’s Scent Machines briefing offers a combination of market-calibrated forecasts and immediately actionable playbooks tailored for companies that need to turn 2026 strategic intent into operational reality. The market’s trajectory—growing from about USD 603 million in 2020 to USD 1,132 million in 2025 and modeled to surpass USD 1,336 million in 2026, with a 14.3% CAGR toward an approximate USD 2,868 million by 2032—creates both urgency and opportunity.
In keeping with the “trailer” principle, this release surfaces the critical strategic implications and practical frameworks that senior leaders require, while reserving the detailed segment-level tables, full competitive matrices, and downloadable financial model for the full report. To access the complete analysis, proprietary models, and the operational toolkits referenced here, visit PW Consulting’s Scent Machines report landing page or contact our industry team for a one-on-one briefing and tailored scenario run for your business.
For detailed analysis of this topic, please visit the official page: Scent Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: A.V. Fistula Needles Market Forecast to Reach USD 460.01 Million by 2032 at a 7.15% CAGR
By pmarketresearch, 2026-06-30
A.V. Fistula Needles Market: Strategic Imperatives for 2026 — PW Consulting Report Snapshot
Executive summary
The A.V. Fistula Needles market is at an inflection point. PW Consulting’s latest market study (base year 2025, historical window 2020–2025, forecast 2026–2032) quantifies a steady recovery and structural expansion: the global market expanded from approximately USD 200.0 Million in 2020 to USD 285.0 Million in 2025 and is forecast to grow to roughly USD 460.0 Million by 2032, implying a compound annual growth rate (CAGR) of 7.15% over the forecast period. These macro dynamics are driven by a confluence of clinical, regulatory, and route-to-market shifts that will shape competitive tactics and capital allocation decisions throughout 2026.
A.V. Fistula Needles Market
Why this matters for 2026 decision-makers
-
Investment timing: A predictable mid-single-digit-plus CAGR creates windows for growth-stage investments, greenfield manufacturing, and bolt-on acquisitions focused on safety- and usability-led differentiation.
A.V. Fistula Needles Market -
Portfolio prioritization: Product features that materially reduce vascular complications, lower needlestick risk, or enable home-based dialysis are showing outsized strategic value compared with traditional commodity attributes.
A.V. Fistula Needles Market -
Risk management: Supply chain and sterilization protocols (including gamma sterilization) are becoming competitive levers; manufacturers that secure validated sterilization capacity and stable raw-material supply will protect margins and market access.
-
Reimbursement and procedure economics: Changes in procedure coding and reimbursement rates directly influence clinical adoption of higher-priced safety technologies; commercial strategies that align clinical and economic value will capture disproportionate share.
What this report delivers (practical, actionable content)
-
Holistic market sizing and trend analysis anchored to a 2020–2025 historical baseline and a 2026–2032 forecast model. The briefing articulates demand drivers, adoption curves, and sensitivity scenarios that can be ported directly into financial planning models.
-
An actionable competitive playbook: product feature maps, differentiation matrices, and a prioritized list of clinical and commercial experiments to run in 2026 that help de-risk launches or premium repositioning.
-
Regulatory, reimbursement, and procurement tracker: clear implications and go/no-go decision criteria for product launches across major regulatory regimes—crafted for commercial and regulatory leads to operationalize.
-
Manufacturing and supply-chain playbooks: capacity planning templates, sterilization pathway assessments, and supplier risk heat maps that can be adopted by operations teams to secure uninterrupted supply.
-
Commercial templates and contracting levers: segmented value-propositions for dialysis centers, home-care providers, and integrated renal networks—ready to be localized through your pricing and contracting teams.
-
Financial and M&A guidance: valuation sensitivity tables, acquisition target screening criteria, and integration checklists designed for corporate development teams considering consolidation or capability buys.
-
Note: This release demonstrates the report’s strategic depth while intentionally withholding the granular segment-by-segment tables and model files; PW Consulting’s full report and downloadable models provide the detailed splits and underlying assumptions.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three firms control just over half of the market (CR3 ~52%), and the top five capture a clear majority (CR5 ~65%). This structure favors incumbent firms with scale in manufacturing, sterilization, and clinical support, but it still leaves attractive niches for challengers who can deploy safety- and outcome-driven innovations.
-
Nipro Corporation (Japan) — Nipro has focused the product narrative around reduced vascular access complications through dedicated designs in their STANDARD and SAFETOUCH™ series. Their clinical positioning emphasizes fewer vascular incidents and practical cannulation ergonomics, which resonates with hospital purchasers focused on complication avoidance.
-
B. Braun Melsungen AG (Germany) — B. Braun bridges product safety and worker protection with solutions featuring anti-stick needle protection systems. Their MasterGuard® Plus-style devices address both clinician safety and institutional HS&E (health, safety & environment) priorities, which are increasingly mandated in procurement policies.
-
SB-Kawasumi Laboratories, Inc. (Japan) — SB-Kawasumi advances a manufacturing and clinical story that leans on sterilization (gamma processes) and bevel engineering to minimize tissue trauma. This technical differentiation supports premium positioning in clinical pathways that prioritize patient comfort and reduced local complications.
-
Asahi Kasei Corporation (Japan) — Asahi Kasei’s approach is systems-oriented, pairing needle sets with compatible tubing and clear lineup choices, targeting smooth integration into existing hemodialysis workflows and procurement bundles.
-
JMS Co., Ltd. (Japan) — JMS emphasizes reliable performance in buttonhole access and conventional hemodialysis scenarios; their product strategy is operationally focused, appealing to centers managing diverse access-site profiles.
Market dynamics and regulatory context
-
Patient and clinician safety drives product premiumization. Anti-stick needle protectors and safety-engineered designs are moving from “nice-to-have” to “procurement must-have” in many facilities. Documentation from manufacturers highlights safety mechanisms that directly reduce needlestick risk and downstream infection concerns.
-
Sterilization and bevel engineering matter. Gamma sterilization and refined bevel geometries are both clinical differentiators and manufacturing constraints. Providers increasingly look for validated sterilization pathways as part of their supplier selection criteria to reduce post-market risk.
-
Procedure economics are relevant at the tactical level. Updated CPT coding and regional fee-schedule changes alter the economics of certain access procedures; for example, changes in reimbursement for AV fistula interventions have immediate implications for hospital purchasing and service-line profitability.
-
Procurement behavior is shifting. Integrated renal networks, consolidation among dialysis providers, and the move toward value-based care mean buying decisions are less transactional and more outcome-oriented—favoring suppliers that can quantify complication avoidance and total cost of care improvements.
Opportunities and strategic plays for 2026
-
Product-led differentiation: Accelerate development and clinical validation of safety-enabled needle systems (e.g., anti-stick features, reduced-trauma bevels, lubricious coatings) and package these with outcome data to support premium pricing.
-
Clinical evidence strategy: Prioritize randomized or observational registries linking needle design to complication rates, cannulation success, and patient-reported comfort. These data sets unlock procurement pathways and justify higher ASPs (average selling prices).
-
Reimbursement intelligence: Map regional coding and fee-schedule changes to adoption scenarios. Commercial teams should craft playbooks that show hospital CFOs and procurement committees how device selection influences per-procedure economics.
-
Operational resilience: Secure validated sterilization capacity (including third-party gamma sterilization contracts) and insulate supply chains for polymers and manufacturing inputs that have historically shown volatility.
-
Commercial models for home dialysis: Build targeted portfolios and bundled offers for the growing home-dialysis segment, aligning product ergonomics, training, and service to enable adoption outside the center.
-
M&A and partnerships: Consider bolt-on acquisitions to shore up niche technology (e.g., safety shields, lubricious coatings) or to add sterilization bandwidth. Partnerships with clinical research organizations will accelerate evidence generation.
-
Pricing and contracting: Use outcome-based contracting pilots with large renal networks to create reference cases that can be scaled. Design pilot KPIs to include complication rates, cannulation time, and clinician satisfaction.
How to use PW Consulting’s full report in 2026 planning
-
Executive teams: Use the market scenarios and sensitivity analyses to stress-test strategic plans, capital allocation, and acquisition pipelines under alternative growth and price-pressure assumptions.
-
Commercial leaders: Adopt our segmentation frameworks and value-proposition templates to tailor sales plays for hospital systems, in-center dialysis operators, and home-care providers.
-
R&D and regulatory: Implement the device design checklists and compliance maps to accelerate time-to-market while minimizing post-market risk.
-
Operations and supply chain: Incorporate the capacity planning tools and sterilization risk assessments into 2026 production and supplier strategies.
-
Note: the report preview presented here intentionally omits the granular split tables and downloadable financial models—these are included in the full report package, which provides a complete view of regional, product-type and application-level segmentation alongside the raw Excel models used for our forecasts.
Conclusion
For executives shaping 2026 strategy, the A.V. Fistula Needles market presents an informed growth opportunity: steady top-line expansion, measurable levers for premiumization, and specific operational risks that are amenable to mitigation. PW Consulting’s full report converts these macro trends into executable actions—equipping leadership with the evidence, scenarios, and toolkits to win in a market where clinical outcomes and safety features increasingly determine commercial success. To access the complete segmentation tables, financial models, and playbooks needed to operationalize these insights, please consult the PW Consulting report page and supporting materials.
For detailed analysis of this topic, please visit the official page: A.V. Fistula Needles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Furniture Market to Hit USD 37.47 Billion by 2032 as Premium Demand Strengthens
By pmarketresearch, 2026-06-30
Luxury Furniture Market — 2026 Strategic Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to present a concise intelligence brief drawn from our new Luxury Furniture Market research (base year 2025, historical 2020–2025, forecast 2026–2032). The market has expanded from approximately USD 16.3 Billion in 2020 to USD 25.28 Billion in 2025 and is projected to reach roughly USD 37.47 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.74% across the 2026–2032 forecast window. This growth trajectory—combined with a market concentration profile where the top three players hold about 25% and the top five about 35%—creates a strategic inflection point for incumbents and new entrants alike.
Luxury Furniture Market
Why this report matters for 2026 corporate decisions
-
Decision clarity in a growth market: The luxury furniture sector is large and expanding at a steady mid-single-digit CAGR. That trajectory supports both organic premiumization strategies and targeted inorganic growth, but it also raises the stakes for capital allocation—where you place development, manufacturing, and channel investment in 2026 will shape returns over the full forecast horizon.
Luxury Furniture Market -
Concentration and consolidation opportunity: Moderate market concentration signals both enduring brand power and room for consolidation. Buyers and investors can expect attractive arbitrage where scale, distribution, or design IP can be integrated to accelerate margin expansion.
Luxury Furniture Market -
Regulatory and trade volatility: A cluster of recent policy actions and legal decisions has created near-term uncertainty for cross-border supply chains and pricing. Executives making sourcing and pricing commitments in 2026 must bake in tariff scenarios and trade-policy contingency plans.
-
Sustainability as a commercial lever: Market leaders are already moving beyond compliance into product redesign and circular models. Firms that embed verified circularity and durable value propositions in 2026 can capture premium positioning and reduce long-term cost volatility.
What the PW Consulting Luxury Furniture Market report delivers
-
Decision-ready executive dashboard: a consolidated view of historical performance (2020–2025) and forward scenarios (2026–2032) with scenario toggles for key variables—tariffs, raw material inflation, and premiumization speed.
-
Commercial playbooks: tailored GTM and pricing strategies for premium residential and commercial segments, including channel mix optimization (flagship retail, wholesale, contract, and digital direct-to-consumer) and experiential retail investments.
-
Supply-chain and sourcing frameworks: actionable sourcing maps and nearshoring/reshoring decision matrices to mitigate tariff and logistics exposure without eroding brand authenticity.
-
Competitive scorecards: non-proprietary strategic profiles and capability matrices for leading incumbents with implications for partnership, licensing, and M&A opportunities.
-
Sustainability toolkit: compliance checklists, circular-design roadmaps, and value-capture templates to convert sustainability investments into price premium and retention gains.
-
Financial and M&A models: sector-normalized cost and margin ranges, deal screening criteria, and integration playbooks to accelerate post-acquisition value realization.
-
Scenario and stress-testing templates: Excel-based models that let commercial and finance teams stress-test unit economics across tariff regimes, raw material shocks, and demand shifts.
Competitive landscape — strategic takeaways
We examined the positioning and recent strategic moves of established and specialist players, and distilled implications for market participants:
-
Legacy Italian maisons (e.g., Poltrona Frau, B&B Italia, Minotti, Cassina) remain powerful carriers of craftsmanship, design authorship, and licensing-led distribution. Their advantage lies in designer collaborations, deep brand equity, and premium pricing. For rivals, partnership, co-branding, or targeted acquisition of design IP are viable routes to accelerate brand sophistication.
-
French design houses (e.g., Roche Bobois) continue to leverage high-fashion positioning and showrooms as experience theaters. The strategic challenge for competitors is building comparable experiential assets without equal capex—digital showrooming and hybrid retail formats are pragmatic alternatives.
-
US firms (e.g., Knoll, Herman Miller, Restoration Hardware, Kimball International, Baker) demonstrate a range of approaches: Knoll and Herman Miller lean into design heritage and contract-market relationships; Restoration Hardware has pursued a vertically integrated, experience-first retail model; Kimball and Baker address contract and bespoke high-end residential niches. Each US approach offers different templates for scale, margin management, and channel control.
-
Newer entrants and standards-setters (e.g., DreamSofa’s May 2026 launch of a Sustainability Standard) are accelerating the shift from incremental sustainability claims to formalized circular product standards. This development will pressure legacy brands to articulate verifiable lifecycle impacts or risk ceding premium-share to credible newcomers.
Regulatory and trade context — why 2026 decisions must be scenario-based
-
Trade policy dynamics have real commercial consequences. Recent administrative delays to proposed tariff changes, proposed retaliatory tariffs on exports, and judicial rulings affecting reciprocal duties create asymmetric timing risks across supply chains and channels.
-
For 2026 planning, firms must adopt a multi-scenario approach to procurement, pricing, and inventory policies: immediate hedges for short-term duty continuations; contingent nearshoring if tariffs are enacted; and contractual protections for long-lead bespoke manufacturing.
Strategic imperatives for executives in 2026
-
Embed circularity into product DNA: Move from marketing claims to audited circular-design, repairability programs, and buy-back models. Use pilot collections to validate unit economics in 2026 and scale successful variants into core assortments.
-
Operationalize tariff scenarios: Establish a tariff war room with procurement, legal, and commercial leads. Implement flexible supply contracts and dual-sourcing strategies to reduce single-point exposure.
-
Prioritize channel mix efficiency: Rebalance retail footprint toward omnichannel experiences where physical spaces play discovery and experience roles while digital channels capture conversion and personalization.
-
Pursue selective M&A and strategic partnerships: Seek targets that deliver immediate capability uplift—design IP, nearshore capacity, or digital-first distribution—rather than only scale.
-
Invest in data and personalization: Deploy customer-level data platforms to allow configuration, customization, and integrated aftercare—these create recurring revenue and higher lifetime value in premium segments.
-
Reassess manufacturing footprints: Use a total-cost-of-ownership lens (including duties, logistics, lead time, and inventory carrying costs) to determine where to nearshore or automate.
-
Strengthen brand authenticity and provenance: For luxury buyers, verifiable craftsmanship, traceability, and service are part of the value proposition—invest in transparent storytelling supported by certifications.
-
Run 90–180 day pilots: Before large-scale rollouts, test pricing, circular services, and channel mixes via rapid pilots that feed back into strategic financing and full-launch decisions.
KPIs and governance to track through 2026
-
Customer acquisition cost and payback period by channel
-
Gross margin by configuration and bespoke vs. standard products
-
Returns and refurbishment yield for circular programs
-
Supply-chain lead-time volatility and tariff-cost delta
-
Share of orders routed through digital channels and percentage of repeat buyers
Conclusion — immediate next steps
2026 will be a pivotal year for executives in the luxury furniture sector: the market’s expansion and moderate concentration create both runway and competitive pressure. Those who combine disciplined scenario planning, targeted capability acquisition, and rigorous sustainability implementation will convert structural growth into enduring margin and brand advantage.
PW Consulting’s full Luxury Furniture Market report contains the granular regional, type, and application breakdowns, vendor market shares, pricing elasticity matrices, supplier cost curves, and executable playbooks (including downloadable financial models and scenario templates) that corporate strategy, M&A, and commercial teams need to act decisively in 2026. For access to the full datasets and strategic tools, please visit the PW Consulting report page or contact our industry team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Luxury Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Scopolamine Market to Reach USD 658 Million by 2032
By pmarketresearch, 2026-06-30
Scopolamine Market 2026 Outlook: Strategic Imperatives for Manufacturers, Buyers and Investors
PW Consulting’s latest Scopolamine Market report (base year 2025) arrives at a pivotal moment for stakeholders navigating supply complexity, pricing pressure and shifting clinical demand. Our proprietary model shows the global market expanding from an industry size of USD 444.0 Million in 2025 to an estimated USD 658.0 Million by 2032, representing a compound annual growth rate (CAGR) of 5.8% across the 2026–2032 forecast window. This press release summarizes the report’s strategic value for corporate decision-makers in 2026, highlights the competitive landscape and underscores the tactical actions that will separate resilient players from those at risk.
Scopolamine Market
Why 2026 Is a Strategic Inflection Point
Two converging trends elevate the stakes this year. First, a steady recovery from pandemic-era distribution disruptions is coinciding with renewed medical demand in key applications. Second, regulatory enforcement and procurement policy shifts are reshaping supplier economics and access to critical APIs and finished forms. Our scenario analysis shows that even modest changes in availability or reimbursement can cascade through supply chains, materially affecting margins and market share.
Scopolamine Market
-
Market momentum. The market trajectory (USD 340.0 Million in 2020 → USD 444.0 Million in 2025 → USD 658.0 Million in 2032) signals durable demand growth that justifies targeted capacity investments and product lifecycle management prioritization.
Scopolamine Market -
Concentration and supplier risk. The market exhibits moderate concentration: our CR3 and CR5 indicators point to a market where a handful of suppliers control a meaningful share of available capacity, amplifying the impact of any supply-side disruption or enforcement action.
-
Policy and procurement shocks. Recent regulatory actions and plan-level formulary shifts are creating localized demand displacement and pricing volatility—factors every procurement and commercial team must model into 2026 budgets.
Key Industry Dynamics Affecting 2026 Decisions
Stakeholders should plan around three dynamics that our report analyzes in depth: supply-base fragility, formulation- and route-of-administration competition, and regulatory enforcement. Below are the elements executives need to track this year.
-
Supply fragility and API provenance. A compact supplier universe for scopolamine APIs and finished forms means that quality, regulatory standing and trade restrictions are immediate business risks. The industry has seen both supplier exits and legal enforcement in recent cycles, emphasizing the need for supplier diversification and continuous compliance monitoring.
-
Formulation competition. The transdermal delivery format continues to be a strategic battleground, with branded products and generics vying for formulary positioning. Manufacturers who can pair differentiated delivery systems with robust regulatory dossiers will have the upper hand in tendering environments.
-
Regulatory enforcement and procurement policy. Enforcement actions and formulary decisions at payor and national levels can shift volumes rapidly. Companies must integrate a regulatory risk overlay into commercial forecasts to avoid overexposure to single-supplier or single-country production nodes.
Competitive Landscape: Practical Implications
Our report provides a granular, actionable view of the competitive map—profiles, regulatory footprints, and commercial capabilities of active suppliers and generic manufacturers. Below we summarize the strategic positioning of the leading participants and the operational signals buyers and investors should interpret.
-
API-focused suppliers (India, China, Australia). Several established suppliers continue to support global supply of scopolamine API and hydrobromide salts. Their portfolios typically include finished supply relationships and regulatory filings that make them first-line partners for formulators. For procurement teams, understanding each supplier’s active regulatory filings and capacity cadence is a prerequisite to building resilient sourcing strategies.
-
Specialized European and multinational players. European suppliers and trade-focused firms maintain differentiated value through regulatory pack-outs and regional registration support. These capabilities become decisive in markets where regulatory dossiers and release testing are non-negotiable.
-
Generic transdermal producers. A subset of established generics manufacturers competes aggressively in the transdermal patch segment. Their strategic advantage lies in scale manufacturing of combination device-drug products and commercial reach in institutional formularies.
Notable market incidents in 2025–2026 have illustrated how supplier conduct and policy choices materially influence market dynamics. For example, enforcement action by a European authority in mid‑2025 resulted in significant fines for a supplier found participating in anti-competitive behaviour related to an API; separately, a regional health plan moved to prefer generic transdermal options in response to distribution delays of a brand product. These events are not isolated—they are symptomatic of a market where regulatory scrutiny and procurement levers can quickly reallocate volume.
Report Contents — What Practitioners Will Use
PW Consulting’s Scopolamine Market report is designed for immediate operationalization. The deliverables include:
-
An authoritative market model projecting annual market value and growth through 2032 (base year 2025), with sensitivity scenarios that quantify the impact of supply interruptions, pricing shifts and route-of-administration substitution.
-
A supplier risk matrix that combines commercial capacity, regulatory dossier status, geographic exposure and historical compliance signals—enabling buyers to build diversification and contingency plans.
-
Regulatory tracker and enforcement log that captures active DMF/USDMF listings, recent fines and policy shifts that could affect market access and tender outcomes.
-
Clinical and channel demand mapping that aligns therapeutic use-cases with procurement channels, hospital formulary dynamics and retail substitution risk.
-
Go-to-market playbooks for manufacturers considering entry into specific dosage forms, including product development checklists, regulatory filing timelines and commercial USP frameworks.
-
Actionable procurement templates: multi-supplier contract structures, inventory hedging thresholds and supplier audit protocols tailored to scopolamine’s manufacturing and cold‑chain characteristics where relevant.
The report intentionally provides in-depth analytical tables and downloadable models behind a gated access point. This “trailer” approach demonstrates methodological rigor while directing readers who require segment-level numbers, region splits and supplier-level volume estimates to the full report repository.
Strategic Recommendations for 2026
Based on our modeling and supplier due diligence, PW Consulting recommends four immediate actions for executive teams this year.
-
Operationalize supplier diversification. Implement a prioritized dual-sourcing policy for API and finished forms, with at least one supplier outside the primary manufacturing geography. Use the supplier risk matrix to select partners for qualification in 2026.
-
Invest in regulatory readiness. Accelerate Type II DMF/USDMF maintenance and regional dossier updates. Companies with active regulatory filings will convert tender opportunities faster and reduce time-to-market for generics and device-associated products.
-
Reassess product mix and pricing strategy. Given continued momentum in transdermal and alternate delivery formats, evaluate pipeline prioritization and lifecycle investments with an eye to formulary capture and institutional contracts.
-
Develop shortage-mitigation playbooks. Create a short-cycle response plan including strategic stockpiles, cross-licensing options and transparent communication templates for payors and hospitals to reduce the commercial fallout from unexpected supplier actions or recalls.
How the Report Supports M&A, Sourcing and Commercial Decisions
For investors and corporate development teams, our scenario-driven valuation overlays reveal where acquisition can unlock vertical integration or margin expansion—particularly where targets own regulatory dossiers or differentiated delivery technologies. For procurement and supply chain leaders, the report supplies executable templates to quantify and hedge against the most likely disruption scenarios over the 2026 planning horizon. Commercial teams receive competitor dossier intelligence and tenderscape analysis to reframe launch sequencing and pricing tactics.
Next Steps
PW Consulting’s Scopolamine Market report is available now to licensed subscribers. The document contains the full market model, supplier profiles, and downloadable tools referenced here. For teams seeking a tailored briefing, we offer a short, paid advisory engagement that maps the report’s insights directly onto your supply base, commercial plan and regulatory exposures.
To obtain the full intelligence package and the data tables supporting our market model, visit the PW Consulting report page or contact our Scopolamine sector lead for a customized executive briefing.
For detailed analysis of this topic, please visit the official page: Scopolamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Bearings for Steel Industry Market Set to Climb from USD 215.0 Million in 2025 to USD 344.8 Million by 2032 (6.98% CAGR)
By pmarketresearch, 2026-06-30
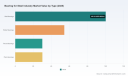
Bearing for Steel Industry Market — Strategic Outlook 2026: Navigating Growth, Supply Constraints, and Service Transformation
Executive summary
PW Consulting’s latest market research report on the Bearing for Steel Industry Market provides a forward-looking playbook for executives planning capital allocation, procurement strategy, and aftermarket transformation in 2026. Built on a 2020–2025 historical foundation and projecting through 2026–2032, the study shows the market expanding at a compound annual growth rate (CAGR) of 6.98%. In monetary terms, the global market reached about USD 215 million in our 2025 base year and is forecast to approach roughly USD 345 million by 2032 — underscoring sustained demand driven by steel industry investment cycles, modernization of rolling mill assets, and shifting OEM service models.
Bearing for Steel Industry Market
Why 2026 is a strategic inflection point
- Capital replacement vs. efficiency investment: Steelmakers face a binary choice in 2026 — invest in incremental capacity and classic rolling assets, or prioritize retrofits and asset-intensification programs that maximize throughput per installed base. Bearings are a leverage point in either path.
- Aftermarket monetization: OEMs and suppliers are accelerating moves from transactional sales to lifecycle and service contracts. Early pilots (including multi-site verification programs for reconditioning) signal a structural shift in how value is captured across the bearing lifecycle.
- Materials and certification pressure: Advances in bearing-grade steels and coating systems are increasing qualification complexity for steel-industry bearings. Suppliers that can marry metallurgy, coating technology and certified manufacturing traces will command premium placement.
Market trajectory and what the numbers mean for decisions
Our modeled trajectory — from a USD 215 million market in 2025 to an estimated USD 345 million in 2032 at a 6.98% CAGR — is not just arithmetic. It encodes three operational realities for 2026 decision-makers:
Bearing for Steel Industry Market
- Moderate, predictable demand growth allows procurement teams to negotiate multi-year supplier agreements with indexed pricing rather than spot-market exposure.
- Investments in condition monitoring and predictive maintenance yield outsized returns during the forecast window because replacement-cycle volumes rise steadily; capturing aftermarket share will increasingly drive profitability compared with sole-component sales.
- Fragmentation remains a core feature of the competitive landscape: the top-tier manufacturers do not yet control the majority of market volume, creating windows for specialized players, materials specialists, and service-focused entrants to scale rapidly through targeted partnerships.
Competitive landscape — who matters and why
The competitive map is composed of global bearing specialists, regional producers, metallurgy suppliers and vertically integrated steelmakers that either supply bearing-grade steel or serve as strategic allies. Our report profiles incumbent leaders and influential challengers with actionable implications for sourcing and alliance strategy:
Bearing for Steel Industry Market
- SKF Group (Stockholm, Sweden) — continues to invest in higher-performance steels and tailored bearing solutions optimized for heavy industrial environments. Recent product introductions emphasize metallurgy and system-level integration rather than commoditized SKU competition.
- NSK Ltd. (Tokyo, Japan) — piloting verification programs for bearing reconditioning and reuse at large steel works, signaling a push into circular-service propositions and a potential reduction in lifecycle material demand for replacement parts.
- The Timken Company (North Canton, Ohio, USA) — maintains a disciplined focus on engineered bearings and industrial motion solutions, leveraging financial strength to support long-term industrial contracts across heavy sectors including steel.
- Schaeffler Group (Herzogenaurach, Germany) — expanding manufacturing of large-size spherical roller bearings in strategic geographies, responding to rising demand for certified, heavy-duty components with advanced surface treatments.
- JTEKT, NTN, Nachi-Fujikoshi, RBC Bearings and others — these manufacturers continue to play strategic roles in specific geographies, technical niches or material specializations; their agility often makes them preferred partners for retrofit pilots and regional aftermarket programs.
- Materials and specialty steel players — firms supplying bearing-grade steels and advanced coatings are increasingly influential because material systems now constitute a meaningful portion of performance differentiation for heavy-duty bearings.
Collectively, the market concentration indicators reflect a moderately fragmented market where the largest three to five players capture well under one-third of total volume. For buyers and investors this fragmentation creates choice but also the need for rigorous supplier due diligence and capability mapping.
Recent industry signals that will shape 2026 choices
- Material innovation: New bearing-grade steel formulations and specialized coatings introduced by leading suppliers are shortening qualification cycles for high-performance applications while raising the bar for supplier quality systems.
- Service models: Verification trials for bearing reconditioning and reuse show the early economics of circular models — reducing lifecycle cost for operators and offering new recurring-revenue streams for suppliers.
- Localized scale-up: Strategic manufacturing expansions and product lines targeted at heavy-duty, large-diameter bearings are enabling shorter lead times and alternative sourcing routes outside traditional hubs.
- Financial discipline: Public reporting from major vendors highlights a tilt toward engineered products and services rather than pure volume plays, which will further bifurcate suppliers into premium-system providers and low-cost component makers.
What the PW Consulting report delivers — operationally actionable components
This report was drafted to be directly usable in 2026 boardrooms and procurement negotiations. Key deliverables include:
- A validated market-sizing model (2020–2032) with scenario-adjusted forecasts that can be re-run with client-specific input assumptions.
- Risk mapping and supply continuity analysis covering raw-material exposure, regulatory qualifications, and geographic manufacturing concentration.
- An actionable supplier scorecard framework that integrates capability, scalability, certification maturity, and lifecycle-service competence — designed for rapid supplier segmentation and panel formation.
- Lifecycle cost models and decision trees for repair vs. replace vs. recondition choices across common steel-industry asset classes.
- M&A and partnership heatmaps identifying targets and value-capture levers for strategic buyers and private-equity sponsors seeking exposure to the aftermarket and specialty-steel value chain.
- Regulatory and qualification playbook outlining steps to accelerate component approval given the sector’s strict cleanliness and consistency standards.
Strategic recommendations for 2026
Based on our integrated market, competitive and materials analysis, PW Consulting recommends three prioritized moves for industry leaders in 2026:
- Rebalance procurement toward outcome contracts: Negotiate multi-year agreements that combine supply, condition monitoring, and defined service levels. This reduces unit-cost volatility and aligns supplier incentives with uptime.
- Invest selectively in reconditioning capability: Establish test-and-learn sites for bearing reuse and reconditioning in partnership with certified vendors. Pilot programs will identify true lifecycle savings and create proprietary service IP.
- Secure material and certification pipelines: Lock in access to qualified bearing-grade steel and coating systems through partnerships with integrated steelmakers and specialty suppliers, while accelerating in-house qualification processes to shorten downtime for new part introductions.
How to use the report in procurement, engineering and board decisions
Procurement teams can use the supplier scorecard and scenario model to convert forecast volatility into contract clauses (index mechanisms, delivery windows, penalty frameworks). Engineering and maintenance functions will find immediate value in the lifecycle cost models and reconditioning decision trees that translate bearing performance into CAPEX deferral opportunities. Boards and corporate development teams should employ the M&A heatmaps and competitive benchmarking to evaluate inorganic avenues to aftermarket capture.
Methodology and confidence
The study synthesizes proprietary surveys of OEM and steel-plant maintenance managers, primary interviews with bearing manufacturers, and triangulation against public financial filings and press disclosures. Forecasts incorporate baseline demand drivers, technology adoption curves, and two stress-test scenarios for material-supply disruptions and accelerated circular adoption. While we disclose headline market values and growth rates to inform executive-level decisions, granular segment tables and supplier-level market shares are reserved for the full report to preserve the investigative integrity of client-grade analysis.
Next steps — for executives who must act in 2026
- Schedule a short-team workshop with PW Consulting to overlay your asset register on our baseline demand model — this will produce a bespoke procurement and service roadmap in 48–72 hours.
- Implement a three-site reconditioning pilot with an incumbent and a regional challenger to compare total cost of ownership outcomes within one operational quarter.
- Initiate strategic dialogues with material-supply partners to secure qualification slots and pre-empt lead-time inflation tied to specialty-steel availability and coating capacity.
Accessing the full analysis
This press release outlines the strategic dimensions and core implications of the Bearing for Steel Industry Market report. For an executive downloadable version that includes the full segment breakdowns, supplier matrices, scenario models and confidential appendices — and to request a bespoke model run tailored to your asset base — please visit PW Consulting’s market intelligence portal. The full report contains the specific regional and application splits, granular supplier shares, and the appendices you will need to execute decisive 2026 strategies.
PW Consulting — equipping steel-industry leaders with actionable intelligence to convert bearing strategy into competitive advantage.
For detailed analysis of this topic, please visit the official page: Bearing for Steel Industry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Strontium Carbonate Market Poised for 4.1% CAGR Expansion
By pmarketresearch, 2026-06-30
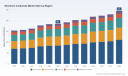
Strontium Carbonate Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest market intelligence—our 2025-base-year Strontium Carbonate Market report—frames a clear decision-making pathway for corporate leaders, procurement teams, and investors preparing for 2026. This preview outlines the strategic value of the report, the macro-trends shaping the market, and the practical playbooks included in the full deliverable. It deliberately highlights the insights that matter for near-term action while reserving the granular segmentation tables and proprietary model outputs for subscribers and report purchasers.
Strontium Carbonate Market
Executive snapshot
-
Market evolution: The global strontium carbonate market expanded steadily through the 2020–2025 historical period and was valued at USD 185.0 Million in 2025 (base year).
Strontium Carbonate Market -
Near-term trajectory: Our modeling indicates an expected compound annual growth rate (CAGR) of approximately 4.1% over the 2026–2032 forecast window, with the market projected to reach USD 244.0 Million by 2032 under the baseline scenario.
Strontium Carbonate Market -
Competitive structure: The market exhibits moderate concentration—our concentration ratios show the top three players controlling a significant share of production, with the top five further extending that share—an important dynamic for negotiating supply and planning investment.
Why this matters for 2026 decisions
Strontium carbonate sits at the intersection of several value chains—electronics, glass and ceramics, pyrotechnics, and specialty industrial applications. That intersection creates both opportunity and fragility. The market’s steady growth trajectory masks localized supply shocks and regulatory accelerants that will materially affect procurement, pricing, and capacity planning in 2026.
-
Regulatory-driven supply-side tightening: In 2025, Chinese authorities published mandates targeting obsolete hazardous chemical production processes, requiring upgrades or cessation of intermittent carbonization facilities within tight timeframes. Several producers responded by temporarily reducing or halting output to comply.
-
Geographic supply realities: Domestic production in some developed markets has been absent for years, increasing reliance on cross-border supply chains and elevating exposure to trade, logistics, and localized regulation risk.
-
Product-grade differentiation: Demand growth is not uniform; higher-purity and electronic-grade materials can command strategic importance and margin premiums, altering where companies should target product development and procurement efforts.
What the full report delivers — practical, decision-focused content
The full PW Consulting report is built as an operational tool for 2026 planning rather than a purely descriptive study. Key deliverables include:
-
Demand and supply models: Dynamic forecasts across the 2026–2032 horizon, with scenario toggles for regulatory tightening, accelerated electronics uptake, and raw-material volatility. These models are delivered in editable spreadsheets so teams can re-run scenarios with their own assumptions.
-
Regulatory impact matrix: A jurisdiction-by-jurisdiction assessment of near-term compliance risks and capex requirements, including quantification of the potential production capacity affected by recent policy actions and the likely timeline for recovery.
-
Supplier and plant-level map: A geospatial synthesis of producer footprints, technology profiles, and grade capabilities, designed to support supplier segmentation and dual-sourcing decisions (note: granular split tables are available in the premium dataset).
-
Commercial playbooks: Contract templates, inventory optimization heuristics, and price-indexing approaches calibrated to the commodity’s demand cycles and grade differentials.
-
M&A and partnership templates: Scoring matrices for acquisition targets and joint-venture candidates that incorporate technical suitability, environmental-compliance risk, and integration complexity.
-
Innovation tracker: A concise assessment of process technologies, potential substitutes, and opportunities for closed-loop material recovery that could reshape cost curves over the forecast period.
Competitive landscape: who matters and why
The market is shaped by a mix of large, specialized producers and regional operators. PW Consulting’s competitive analysis focuses on capability, product breadth, export orientation, and regulatory exposure. Representative players profiled in the report include:
-
Kandelium GmbH (Bad Hönningen, Germany) — Positioned as one of the world’s largest integrated producers, with capabilities in calcined granules and sulfide-free and high-purity grades. Its scale and product breadth make it a pivotal counterparty for buyers seeking stability and higher-purity material.
-
Química del Estroncio S.A. (Cartagena, Spain) — A regionally integrated producer leveraging local celestite resources to serve glass, ceramics, pigments, and pyrotechnic markets. Their integration into raw-material sources provides resilience against upstream supply swings.
-
Hebei Xinji Chemical Group (Shijiazhuang, China) — A significant exporter of standard-grade powder products; recently impacted by regulatory-driven technical upgrades that have compressed near-term output—an important signal for supply planning.
-
Sakai Chemical Industry Co., Ltd. (Osaka, Japan) — Focused on a portfolio of grades including high-purity electronic materials; well-positioned to capture premium segments in electronics and ferrite magnet supply chains.
-
Chemical Products Corporation (Cartersville, Georgia, USA) — A North American-focused producer providing barium/strontium compounds; strategic for regional buyers seeking shorter lead times and diversified sources.
For procurement teams, these firm-level profiles inform a tiered-supplier strategy: anchor supply with large, diversified producers; hedge supply with regional specialists; and maintain optionality for premium-grade requirements through strategic offtakes or tolling agreements.
Regulatory and raw-material dynamics to monitor in 2026
-
Compliance-driven capex: The 2025 Chinese catalog of obsolete chemical processes has already forced capacity rationalization in some producer cohorts. Expect further compliance-related downtime and consolidation risks as deadlines and inspections are enforced.
-
REACH and export controls: European regulatory regimes maintain high standards for chemical substances—compliance investments are non-negotiable for producers targeting EU customers and can be a differentiator for market access.
-
Raw-material sourcing: Domestic production in some markets ceased years ago; imports dominate. This structural reality increases supply-chain sensitivity to shipping disruptions, trade policy shifts, and concentration at upstream deposits.
How to use this report in 2026: tactical recommendations
PW Consulting advises commercial and executive teams to take the following actions in Q1–Q2 2026, using the full report as the operational playbook:
-
Immediate supply assessment: Run the report’s supplier-risk dashboard against your current contracts. Identify single-source exposures and quantify short-term replacement costs under our elevated-risk scenarios.
-
Contract redesign: Move to shorter-price-reset windows or include quality-differentiated pricing ladders for premium grades. Consider addenda that allow for force-majeure adjustments tied to documented regulatory shutdowns.
-
Strategic inventory: For critical grades, deploy a layered inventory policy—safety stock held in-market plus a small strategic reserve in low-cost bonded facilities—minimizing cash drag while protecting operations.
-
Capex timing for producers: If you are a producer, prioritize compliance capex and upgrade projects to meet regulatory deadlines early. Delaying upgrades increases the risk of forced shutdowns and value-destructive distress sales.
-
M&A and JV scouting: Use our acquisition-scoring tool to identify targets that offer raw-material access, regulatory-compliant capacity, or specialty-grade manufacturing—each a multiplier for strategic positioning.
-
R&D focus: Invest selectively in higher-purity and low-impurity grades used in electronics and magnetics where demand and margins are forecast to diverge from commodity-grade trajectories.
Scenario planning included
The report supplies three scenario families to stress-test strategies:
-
Baseline: Continuation of recent policies and demand trends, aligning with the 4.1% CAGR baseline to 2032.
-
Regulatory-tightening: Accelerated compliance enforcement and additional capacity attrition in certain jurisdictions—useful for contingency planning on supply interruptions.
-
Demand-acceleration: Upside scenarios driven by a faster-than-expected ramp in electronics and magnetic-materials demand, which would disproportionately favor high-purity grades.
Conclusion and call to action
PW Consulting’s Strontium Carbonate Market report is configured to be a working resource for the 2026 planning cycle: a set of calibrated models, practical commercial playbooks, and supplier-level intelligence that convert market signals into operational choices. This preview surfaces the macro context—historic expansion to USD 185.0 Million in 2025, an expected 4.1% CAGR through 2032, and a projected market approaching USD 244.0 Million by the end of the forecast horizon—while reserving the detailed segmentation, plant-level economics, and proprietary scenario outputs for the full report package.
To obtain the full dataset, editable models, and the supplier-risk map that support tactical execution, please consult the report landing page or contact PW Consulting’s Industry Intelligence team. The deeper intelligence therein is engineered to translate the industry’s trends into concrete actions for procurement, operations, and corporate development in 2026.
For detailed analysis of this topic, please visit the official page: Strontium Carbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SOH Market Set to Expand at a 7.25% CAGR as Semiconductor Manufacturing Drives Demand
By pmarketresearch, 2026-06-30
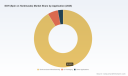
Spin-on Hardmasks (SOH) Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s latest SOH (Spin on Hardmasks) Market report delivers a concise, action-oriented intelligence package designed to influence boardroom decisions and engineering roadmaps in 2026. As semiconductor manufacturers, materials suppliers, and private investors confront accelerating EUV node transitions and geopolitical-driven fab investments, this briefing articulates the strategic levers that matter—while reserving full segment-level detail for the comprehensive report.
SOH (Spin on Hardmasks) Market
Market Snapshot: Macro Trajectory and Near-Term Momentum
At a global scale, the SOH market reached an estimated 175.0 USD Million in our base year (2025). Our forecast model—anchored on historical performance through 2020–2025 and validated vendor qualification trajectories—projects a compound annual growth rate (CAGR) of 7.25% over the 2026–2032 forecast horizon. Under these assumptions, the market expands to approximately 190.7 USD Million in 2026 and approaches 284.0 USD Million by 2032.
SOH (Spin on Hardmasks) Market
This expansion reflects two reinforcing dynamics: (1) increased adoption of spin-on alternatives to CVD hardmasks for specific pattern-transfer steps, particularly where throughput and cost-per-wafer improvements are attainable; and (2) capacity growth driven by supportive industrial policy and foundry-led node migration. The market’s pace is substantive enough that procurement, R&D, and corporate development teams must make definitive commitments in 2026 to capture the earliest waves of value.
SOH (Spin on Hardmasks) Market
Key Dynamics Shaping 2026 Choices
- Technology Roadmap: EUV and High-NA Readiness
Next‑generation hardmask chemistries are converging on EUV and High‑NA EUV compatibility, with initial customer engagements accelerating through 2026–2027. Early qualifiers and pilot runs are shifting from exploratory lab validation to foundry-level process qualification, making 2026 a pivotal year to align product roadmaps with High‑NA timelines.
- Supply-Chain & Material Risk
Procurement teams face volatile specialty chemical pricing and heightened environmental scrutiny. Fluctuating raw-material costs increase the importance of dual-sourcing strategies and long‑term supply agreements. Firms that secure stable precursor streams and put traceability/ESG clauses in procurement contracts will realize lower qualification friction and fewer process interruptions.
- Regulatory and Policy Tailwinds
Public incentives—such as the U.S. CHIPS and Science Act and the European Chips Act—continue to unlock fab capacity expansions in key geographies. These policies are translating into near-term demand visibility for materials suppliers, but they also raise the bar for local content, environmental compliance, and demonstrated supply resilience.
- Fragmented Competitive Structure
Market concentration metrics indicate a relatively fragmented supplier base, with the top three and five vendors accounting for low-to-mid double-digit shares. This dispersion creates both opportunity and complexity: buyers can play suppliers against one another for terms, while scale-seeking suppliers must pursue differentiation through performance, qualification speed, and foundry relationships.
- Qualification Momentum
Several industry players reported multiple new product qualifications at Tier‑1 foundries in 2025 and early 2026, signaling that the pace of adoption is accelerating from lab proofs to manufacturing-readiness. This raises the cost of entry for late movers and heightens the value of pre‑emptive qualification engagements in 2026.
Competitive Landscape: Who Matters and Why
The competitive map is populated by specialty chemical leaders, lithography innovators, and select materials start-ups. Key players we assessed include:
- Samsung SDI (Seoul, South Korea) — Provides SOH coating materials aimed at replacing select CVD steps to streamline production. ( https://www.samsungsdi.com/)
- Merck Group (Darmstadt, Germany) — Offers spin‑on carbon hardmask chemistries and thin film hardmasks for wafer patterning and etch processes. ( https://www.merckgroup.com/)
- JSR Corporation (Tokyo, Japan) — Focused on carbon‑rich SOC formulations with low outgassing and high planarization, positioned for EUV lithography uses. ( https://www.jsr.co.jp/)
- Shin‑Etsu Chemical (Tokyo, Japan) — Manufactures spin‑on under‑ and middle‑layer hardmasks for nanofabrication and semiconductor fabs. ( https://www.shinetsu.co.jp/)
- Brewer Science (Rolla, Missouri, USA) — Developer of OptiStack multilayer systems incorporating spin‑on carbon and silicon hardmask layers for advanced pattern transfer. ( https://www.brewerscience.com/)
- Pibond Oy (Helsinki, Finland) — Specializes in liquid spin‑on metal oxide hardmasks targeted at advanced nodes, 2.5/3D‑IC, and MEMS. ( https://www.pibond.com/)
- Nano‑C (Los Alamos, New Mexico, USA) — Supplies fullerene‑based SOC materials designed to improve photoresist etch selectivity. ( https://nano-c.com/)
These vendors exhibit distinct go‑to‑market plays: incumbents leverage foundry relationships and scale to accelerate qualifications, whereas smaller specialists compete on niche performance attributes (e.g., planarization, etch selectivity) and faster co‑development cycles. Recent technology validation (e.g., a March 2026 multi‑project wafer validation of silicon organic hybrid modulator compatibility on a high‑volume silicon photonics platform) illustrates how cross‑domain partnerships can accelerate adoption curves beyond traditional logic and memory fabs.
2026 Strategic Imperatives — What Executives Should Do Now
- Embed Materials Strategy in Node Roadmaps
Product and process leaders must fold SOH qualification timelines into device roadmaps now. Waiting for post‑2026 validation will create 12–18 month lag risks as foundries move from evaluation to production.
- Pursue De‑Risked Qualification Partnerships
Prioritize supplier partnerships that offer co‑development, joint pilot lines, and shared process characterization data. Early engagement can shorten qualification cycles and reduce ramp variability.
- Hedge Supply and Cost Exposure
Negotiate staggered supply contracts, lock in critical precursor pricing where possible, and include ESG and traceability provisions. Specialty chemical price spikes can materially change total cost of ownership on contracted wafer volumes.
- Invest in Integration & Test Infrastructure
Allocating 2026 capex for in‑house pilot spin‑coating and etch characterization will pay dividends in qualification speed and IP protection. Small, targeted investments materially reduce vendor dependency during early production phases.
- Scan for M&A and JV Opportunities
The fragmented market creates roll‑up potential for players seeking scale, while IP‑rich start‑ups and materials specialists remain attractive targets for foundries and chemical majors aiming to own critical stack elements.
- Align with Policy & Local Content Expectations
Firms participating in subsidized fab programs need to demonstrate supply continuity and local capability; 2026 procurement strategies should incorporate regional compliance and content assessment criteria.
What the PW Consulting Report Delivers (Practical, Executable Content)
The full SOH Market report is designed as a decision-support toolkit. Highlights include:
- Proven financial models and sensitivity analyses that translate market growth and material-cost scenarios into EBITDA and payback timelines for supplier selection, JV formation, and M&A.
- Qualification playbooks and process‑level checklists for foundry and IDM engagements, covering test-matrix design, failure-mode expectations, and typical timeline milestones.
- Supply‑chain maps with critical‑path resilience recommendations, dual‑sourcing templates, and ESG/compliance checklists tailored to 2026 subsidy regimes.
- Technology readiness matrices and vendor scorecards that quantify fit-for-purpose across EUV, High‑NA, and multi‑patterning use cases.
- Negotiation frameworks for long‑lead precursors, including contract clause templates and risk‑allocation exemplars.
Note: to preserve competitive value for subscribers and partners, the public summary intentionally omits granular regional, application, and type-level breakdowns. The full report provides comprehensive segmentation tables, interactive dashboards, and downloadable spreadsheets required for transaction due diligence and operational planning.
Why 2026 Is a Pivotal Year
Between accelerated High‑NA proof points, multiple vendor qualifications at Tier‑1 foundries, and policy-driven fab expansions, 2026 represents a strategic inflection point. Companies that codify SOH strategies into their product roadmaps, secure resilient precursor supply, and invest in co‑development will be positioned to capture disproportionate value through the early production wave. Conversely, hesitation risks late-stage qualification bottlenecks and higher total cost of ownership as material premiums and environmental compliance costs intensify.
Next Steps
PW Consulting’s SOH Market report is available with subscriber-only appendices that include the complete segmentation datasets, vendor scorecards, and financial model templates. For teams preparing capital budgets, supplier RFPs, or integration roadmaps in 2026, this report is a practical toolkit to move from strategy to execution.
To obtain the full analysis, segmentation details, and proprietary decision-support models, please visit the PW Consulting report landing page (full access is required for downloadable datasets and vendor benchmarking tools).
For detailed analysis of this topic, please visit the official page: SOH (Spin on Hardmasks) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Materials Market Poised for Strong Growth with a 5.8% CAGR, Driven by Prosthetics and Implant Demand
By pmarketresearch, 2026-06-30
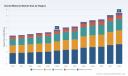
Dental Material Market 2026 Strategic Outlook: A PW Consulting Executive Brief
Executive Snapshot
PW Consulting’s latest Dental Material Market report (base year 2025) delivers a data‑driven, decision‑ready view of an expanding global market. After growing from USD 4.7 Billion in 2020 to USD 5.7 Billion in 2025, the market is forecast to reach approximately USD 8.5 Billion by 2032 at a 5.8% CAGR across the 2026–2032 horizon. Market concentration remains moderate — with the top three firms accounting for roughly 45% and the top five roughly 58% of revenues — creating a landscape that favors both scale advantages and focused differentiation.
Dental Material Market
Why this report matters for 2026 planning
-
Strategic clarity for 2026 budget cycles: The report translates macro momentum into actionable priorities for R&D, commercial rollout, and supply‑chain investment during a pivotal post‑pandemic recovery window.
Dental Material Market -
Regulatory and reimbursement foresight: With multiple standards and code updates coming into effect in 2026, our analysis equips executives to align product development and market access plans with shifting compliance and payment realities.
Dental Material Market -
M&A and partnership playbook: We identify where scale is winning, where niches are opening, and how mid‑cap players can position for acquisition or profitable specialization.
-
Digital transformation guidance: The report puts dental 3D printing, resin innovation, and digital restorative workflows into a practical investment framework — helping firms set priorities across capex, IP, and go‑to‑market activities.
What the report contains (practical components)
-
Comprehensive market model: Historical series (2020–2025) and granular forecasts through 2032, with sensitivity testing across adoption, pricing, and regulatory scenarios.
-
Segment maps and demand drivers: Multi‑dimensional segmentation by region, material type, application, and end‑user — each accompanied by demand levers and tactical implications. (Note: detailed segment tables and numeric splits are available in the full report.)
-
Commercial playbooks: Go‑to‑market templates for incumbents and challengers covering channel strategy, pricing architectures, and value propositions tailored to dental labs, manufacturers, and clinics.
-
Regulatory and reimbursement tracker: An annotated timeline of standards, regulatory milestones, CDT code updates and certification programs with practical compliance checklists.
-
Competitive intelligence toolkit: Strategic profiles, capability heatmaps, patent trend snapshots, and a short list of high‑probability M&A targets.
-
Supply‑chain resilience checklist: Supplier risk scoring, nearshoring scenarios, and materials concentration analysis to mitigate disruption and cost pressure.
-
Decision support assets: Financial impact models, scenario dashboards, and executive one‑pagers to fast‑track board conversations and capital allocation choices.
Market dynamics shaping 2026 decisions
-
Steady demand growth. The market’s compound expansion to USD 8.5 Billion by 2032 reflects a combination of procedural volume recovery, demographic drivers, and higher‑value restorative and digital workflows.
-
Regulatory inflection points. Recent regulatory events have raised the bar for biocompatibility and device validation. Notably, authorities have clarified equivalence pathways for PMMA‑based temporary materials and signaled stricter compliance expectations tied to ISO biological evaluation standards. Concurrently, the ADA Forsyth Institute’s certification program will create a new quality signal for buyers starting early 2026.
-
Reimbursement realignment. CDT code updates in late 2025 have introduced a set of new and revised procedure codes that will materially affect reimbursement for restorative and surgical treatments. Manufacturers and service providers must recalibrate coding strategies to secure appropriate compensation for innovative materials and workflows.
-
Standards volatility. Recent rejection of a key ISO biocompatibility draft underscores uncertainty in global standards — a risk for firms that do not hedge product development with multiple validation pathways.
-
Technology acceleration. Additive manufacturing resins and digital materials continue to mature. Regulatory clearances for Class II resin indications and new adhesive chemistries have broadened clinical use cases and shortened time‑to‑adoption for digital restorative solutions.
Competitive landscape — how to read it
The market combines legacy incumbents with rising specialized players. Dominant multinational dental materials manufacturers retain scale advantages in distribution, regulatory depth, and channel relationships. Simultaneously, focused innovators — particularly in 3D printing resins and PMMA temporary systems — are capturing incremental share through product differentiation and regulatory wins.
-
3M Company (St. Paul, Minnesota) — Strengths: broad restorative portfolio, adhesive and resin technologies; strategic focus on nanotechnology adhesives and integrated restorative systems.
-
Dentsply Sirona (Charlotte, North Carolina) — Strengths: restorative materials and digital aligner ecosystems; recent regulatory clearances extend clinical indications across restorative and endodontic categories.
-
Kuraray Noritake Dental (Tokyo) — Strengths: advanced restorative chemistries within an integrated dental materials division focused on bonding and core restorative substrates.
-
Ivoclar Vivadent AG (Schaan) — Strengths: comprehensive restorative and bonding product lines with deep clinical adoption in prosthetic workflows.
-
GC Corporation (Tokyo), Coltene Holding AG (Altstätten), Heraeus Kulzer GmbH (Hanau), DMG (Hamburg), UltrAdent (South Jordan) — Established players with focused competencies in restorative, impression, and bonding systems.
-
SprintRay (Long Beach), Formlabs (Somerville), Taiwan Dental Materials Co., Ltd. (Taipei) — Specialists in 3D printing resins and PMMA systems; recent regulatory actions have increased their market impact and clinical acceptance.
Recent market signals and implications
-
Regulatory clearances and product launches are validating new material classes and clinical workflows. Examples include recent FDA 510(k) clearances and product introductions across PMMA and advanced resin categories.
-
New certifications and procedural codes will alter purchase drivers: clinicians and labs will increasingly favor materials with explicit conformity and reimbursement alignment.
-
Moderate concentration (CR3 ~45%, CR5 ~58%) indicates that while large players control substantial share, there is room for specialist entrants to scale via regulatory differentiation and digital channel strategies.
Strategic playbook: Five priorities for 2026
-
Prioritize regulatory‑first product roadmaps. Allocate 2026 R&D dollars to ensure compliance with both FDA equivalence requirements and the emergent ADA certification expectations. Dual‑track validation (biocompatibility + clinical performance) reduces launch risk.
-
Monetize digital workflows. Invest in materials formulated for additive manufacturing and integrated restorative systems. Bundled offerings — printer + validated resin + clinical protocols — command premium pricing and higher switching costs.
-
Reconfigure go‑to‑market for new codes. Realign sales incentives and training to leverage the late‑2025 CDT code set; educate payers and providers to capture appropriate reimbursement for advanced materials and procedures.
-
Targeted M&A or licensing to fill capability gaps. Look for bolt‑on acquisitions that deliver regulatory clearance, digital resin IP, or narrow channel access rather than broad headline buys. Our report’s shortlist and valuation scenarios help prioritize targets.
-
Harden supply‑chain risk management. Map critical raw material exposures, diversify source geographies for key chemistries, and evaluate nearshoring options to protect margins against commodity and logistics shocks.
How executives should use this report in 2026
Use the report as a tactical toolkit in board and executive forums: populate scenario planning templates with our market model to test different adoption paths, stress‑test product portfolios against regulatory scenarios, and quantify the ROI of accelerated digital investments. For business development and corporate development teams, the competitive intelligence dossiers and M&A screening models provide prioritized targets and deal rationale aligned to market dynamics.
Data integrity and methodology
Our projections combine primary interviews with clinicians, manufacturers, and payers; proprietary demand and pricing models; and public regulatory disclosures. The historical series (2020–2025) and the forecast period (2026–2032) reflect adjustments for documented regulatory events, coding changes, and observed technology adoption curves. Scenario analysis quantifies upside and downside paths to 2032 based on alternative assumptions for adoption velocity, pricing shifts, and regulatory timing.
Next steps — where to get the full intelligence
This executive brief intentionally emphasizes the report’s strategic value while withholding granular segment tables and proprietary numeric splits to preserve the decision‑support value available in the full report. To access the complete dataset (including regional/type/application/end‑user tables, price and volume assumptions, downloadable models, and the full competitive matrix), visit the PW Consulting report page or contact our client services team for a tailored briefing.
PW Consulting remains available to support immediate 2026 planning workshops, M&A diligence, and regulatory readiness programs derived from this research.
For detailed analysis of this topic, please visit the official page: Dental Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com