

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Bearings for Steel Industry Market Set to Climb from USD 215.0 Million in 2025 to USD 344.8 Million by 2032 (6.98% CAGR)

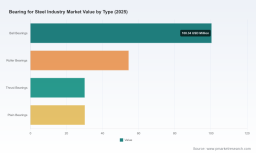
Bearing for Steel Industry Market — Strategic Outlook 2026: Navigating Growth, Supply Constraints, and Service Transformation
Executive summary
PW Consulting’s latest market research report on the Bearing for Steel Industry Market provides a forward-looking playbook for executives planning capital allocation, procurement strategy, and aftermarket transformation in 2026. Built on a 2020–2025 historical foundation and projecting through 2026–2032, the study shows the market expanding at a compound annual growth rate (CAGR) of 6.98%. In monetary terms, the global market reached about USD 215 million in our 2025 base year and is forecast to approach roughly USD 345 million by 2032 — underscoring sustained demand driven by steel industry investment cycles, modernization of rolling mill assets, and shifting OEM service models.
Bearing for Steel Industry Market
Why 2026 is a strategic inflection point
- Capital replacement vs. efficiency investment: Steelmakers face a binary choice in 2026 — invest in incremental capacity and classic rolling assets, or prioritize retrofits and asset-intensification programs that maximize throughput per installed base. Bearings are a leverage point in either path.
- Aftermarket monetization: OEMs and suppliers are accelerating moves from transactional sales to lifecycle and service contracts. Early pilots (including multi-site verification programs for reconditioning) signal a structural shift in how value is captured across the bearing lifecycle.
- Materials and certification pressure: Advances in bearing-grade steels and coating systems are increasing qualification complexity for steel-industry bearings. Suppliers that can marry metallurgy, coating technology and certified manufacturing traces will command premium placement.
Market trajectory and what the numbers mean for decisions
Our modeled trajectory — from a USD 215 million market in 2025 to an estimated USD 345 million in 2032 at a 6.98% CAGR — is not just arithmetic. It encodes three operational realities for 2026 decision-makers:
Bearing for Steel Industry Market
- Moderate, predictable demand growth allows procurement teams to negotiate multi-year supplier agreements with indexed pricing rather than spot-market exposure.
- Investments in condition monitoring and predictive maintenance yield outsized returns during the forecast window because replacement-cycle volumes rise steadily; capturing aftermarket share will increasingly drive profitability compared with sole-component sales.
- Fragmentation remains a core feature of the competitive landscape: the top-tier manufacturers do not yet control the majority of market volume, creating windows for specialized players, materials specialists, and service-focused entrants to scale rapidly through targeted partnerships.
Competitive landscape — who matters and why
The competitive map is composed of global bearing specialists, regional producers, metallurgy suppliers and vertically integrated steelmakers that either supply bearing-grade steel or serve as strategic allies. Our report profiles incumbent leaders and influential challengers with actionable implications for sourcing and alliance strategy:
Bearing for Steel Industry Market
- SKF Group (Stockholm, Sweden) — continues to invest in higher-performance steels and tailored bearing solutions optimized for heavy industrial environments. Recent product introductions emphasize metallurgy and system-level integration rather than commoditized SKU competition.
- NSK Ltd. (Tokyo, Japan) — piloting verification programs for bearing reconditioning and reuse at large steel works, signaling a push into circular-service propositions and a potential reduction in lifecycle material demand for replacement parts.
- The Timken Company (North Canton, Ohio, USA) — maintains a disciplined focus on engineered bearings and industrial motion solutions, leveraging financial strength to support long-term industrial contracts across heavy sectors including steel.
- Schaeffler Group (Herzogenaurach, Germany) — expanding manufacturing of large-size spherical roller bearings in strategic geographies, responding to rising demand for certified, heavy-duty components with advanced surface treatments.
- JTEKT, NTN, Nachi-Fujikoshi, RBC Bearings and others — these manufacturers continue to play strategic roles in specific geographies, technical niches or material specializations; their agility often makes them preferred partners for retrofit pilots and regional aftermarket programs.
- Materials and specialty steel players — firms supplying bearing-grade steels and advanced coatings are increasingly influential because material systems now constitute a meaningful portion of performance differentiation for heavy-duty bearings.
Collectively, the market concentration indicators reflect a moderately fragmented market where the largest three to five players capture well under one-third of total volume. For buyers and investors this fragmentation creates choice but also the need for rigorous supplier due diligence and capability mapping.
Recent industry signals that will shape 2026 choices
- Material innovation: New bearing-grade steel formulations and specialized coatings introduced by leading suppliers are shortening qualification cycles for high-performance applications while raising the bar for supplier quality systems.
- Service models: Verification trials for bearing reconditioning and reuse show the early economics of circular models — reducing lifecycle cost for operators and offering new recurring-revenue streams for suppliers.
- Localized scale-up: Strategic manufacturing expansions and product lines targeted at heavy-duty, large-diameter bearings are enabling shorter lead times and alternative sourcing routes outside traditional hubs.
- Financial discipline: Public reporting from major vendors highlights a tilt toward engineered products and services rather than pure volume plays, which will further bifurcate suppliers into premium-system providers and low-cost component makers.
What the PW Consulting report delivers — operationally actionable components
This report was drafted to be directly usable in 2026 boardrooms and procurement negotiations. Key deliverables include:
- A validated market-sizing model (2020–2032) with scenario-adjusted forecasts that can be re-run with client-specific input assumptions.
- Risk mapping and supply continuity analysis covering raw-material exposure, regulatory qualifications, and geographic manufacturing concentration.
- An actionable supplier scorecard framework that integrates capability, scalability, certification maturity, and lifecycle-service competence — designed for rapid supplier segmentation and panel formation.
- Lifecycle cost models and decision trees for repair vs. replace vs. recondition choices across common steel-industry asset classes.
- M&A and partnership heatmaps identifying targets and value-capture levers for strategic buyers and private-equity sponsors seeking exposure to the aftermarket and specialty-steel value chain.
- Regulatory and qualification playbook outlining steps to accelerate component approval given the sector’s strict cleanliness and consistency standards.
Strategic recommendations for 2026
Based on our integrated market, competitive and materials analysis, PW Consulting recommends three prioritized moves for industry leaders in 2026:
- Rebalance procurement toward outcome contracts: Negotiate multi-year agreements that combine supply, condition monitoring, and defined service levels. This reduces unit-cost volatility and aligns supplier incentives with uptime.
- Invest selectively in reconditioning capability: Establish test-and-learn sites for bearing reuse and reconditioning in partnership with certified vendors. Pilot programs will identify true lifecycle savings and create proprietary service IP.
- Secure material and certification pipelines: Lock in access to qualified bearing-grade steel and coating systems through partnerships with integrated steelmakers and specialty suppliers, while accelerating in-house qualification processes to shorten downtime for new part introductions.
How to use the report in procurement, engineering and board decisions
Procurement teams can use the supplier scorecard and scenario model to convert forecast volatility into contract clauses (index mechanisms, delivery windows, penalty frameworks). Engineering and maintenance functions will find immediate value in the lifecycle cost models and reconditioning decision trees that translate bearing performance into CAPEX deferral opportunities. Boards and corporate development teams should employ the M&A heatmaps and competitive benchmarking to evaluate inorganic avenues to aftermarket capture.
Methodology and confidence
The study synthesizes proprietary surveys of OEM and steel-plant maintenance managers, primary interviews with bearing manufacturers, and triangulation against public financial filings and press disclosures. Forecasts incorporate baseline demand drivers, technology adoption curves, and two stress-test scenarios for material-supply disruptions and accelerated circular adoption. While we disclose headline market values and growth rates to inform executive-level decisions, granular segment tables and supplier-level market shares are reserved for the full report to preserve the investigative integrity of client-grade analysis.
Next steps — for executives who must act in 2026
- Schedule a short-team workshop with PW Consulting to overlay your asset register on our baseline demand model — this will produce a bespoke procurement and service roadmap in 48–72 hours.
- Implement a three-site reconditioning pilot with an incumbent and a regional challenger to compare total cost of ownership outcomes within one operational quarter.
- Initiate strategic dialogues with material-supply partners to secure qualification slots and pre-empt lead-time inflation tied to specialty-steel availability and coating capacity.
Accessing the full analysis
This press release outlines the strategic dimensions and core implications of the Bearing for Steel Industry Market report. For an executive downloadable version that includes the full segment breakdowns, supplier matrices, scenario models and confidential appendices — and to request a bespoke model run tailored to your asset base — please visit PW Consulting’s market intelligence portal. The full report contains the specific regional and application splits, granular supplier shares, and the appendices you will need to execute decisive 2026 strategies.
PW Consulting — equipping steel-industry leaders with actionable intelligence to convert bearing strategy into competitive advantage.
For detailed analysis of this topic, please visit the official page: Bearing for Steel Industry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com