

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: A.V. Fistula Needles Market Forecast to Reach USD 460.01 Million by 2032 at a 7.15% CAGR

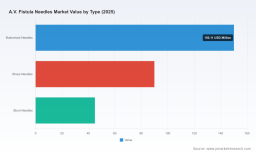
A.V. Fistula Needles Market: Strategic Imperatives for 2026 — PW Consulting Report Snapshot
Executive summary
The A.V. Fistula Needles market is at an inflection point. PW Consulting’s latest market study (base year 2025, historical window 2020–2025, forecast 2026–2032) quantifies a steady recovery and structural expansion: the global market expanded from approximately USD 200.0 Million in 2020 to USD 285.0 Million in 2025 and is forecast to grow to roughly USD 460.0 Million by 2032, implying a compound annual growth rate (CAGR) of 7.15% over the forecast period. These macro dynamics are driven by a confluence of clinical, regulatory, and route-to-market shifts that will shape competitive tactics and capital allocation decisions throughout 2026.
A.V. Fistula Needles Market
Why this matters for 2026 decision-makers
-
Investment timing: A predictable mid-single-digit-plus CAGR creates windows for growth-stage investments, greenfield manufacturing, and bolt-on acquisitions focused on safety- and usability-led differentiation.
A.V. Fistula Needles Market -
Portfolio prioritization: Product features that materially reduce vascular complications, lower needlestick risk, or enable home-based dialysis are showing outsized strategic value compared with traditional commodity attributes.
A.V. Fistula Needles Market -
Risk management: Supply chain and sterilization protocols (including gamma sterilization) are becoming competitive levers; manufacturers that secure validated sterilization capacity and stable raw-material supply will protect margins and market access.
-
Reimbursement and procedure economics: Changes in procedure coding and reimbursement rates directly influence clinical adoption of higher-priced safety technologies; commercial strategies that align clinical and economic value will capture disproportionate share.
What this report delivers (practical, actionable content)
-
Holistic market sizing and trend analysis anchored to a 2020–2025 historical baseline and a 2026–2032 forecast model. The briefing articulates demand drivers, adoption curves, and sensitivity scenarios that can be ported directly into financial planning models.
-
An actionable competitive playbook: product feature maps, differentiation matrices, and a prioritized list of clinical and commercial experiments to run in 2026 that help de-risk launches or premium repositioning.
-
Regulatory, reimbursement, and procurement tracker: clear implications and go/no-go decision criteria for product launches across major regulatory regimes—crafted for commercial and regulatory leads to operationalize.
-
Manufacturing and supply-chain playbooks: capacity planning templates, sterilization pathway assessments, and supplier risk heat maps that can be adopted by operations teams to secure uninterrupted supply.
-
Commercial templates and contracting levers: segmented value-propositions for dialysis centers, home-care providers, and integrated renal networks—ready to be localized through your pricing and contracting teams.
-
Financial and M&A guidance: valuation sensitivity tables, acquisition target screening criteria, and integration checklists designed for corporate development teams considering consolidation or capability buys.
-
Note: This release demonstrates the report’s strategic depth while intentionally withholding the granular segment-by-segment tables and model files; PW Consulting’s full report and downloadable models provide the detailed splits and underlying assumptions.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three firms control just over half of the market (CR3 ~52%), and the top five capture a clear majority (CR5 ~65%). This structure favors incumbent firms with scale in manufacturing, sterilization, and clinical support, but it still leaves attractive niches for challengers who can deploy safety- and outcome-driven innovations.
-
Nipro Corporation (Japan) — Nipro has focused the product narrative around reduced vascular access complications through dedicated designs in their STANDARD and SAFETOUCH™ series. Their clinical positioning emphasizes fewer vascular incidents and practical cannulation ergonomics, which resonates with hospital purchasers focused on complication avoidance.
-
B. Braun Melsungen AG (Germany) — B. Braun bridges product safety and worker protection with solutions featuring anti-stick needle protection systems. Their MasterGuard® Plus-style devices address both clinician safety and institutional HS&E (health, safety & environment) priorities, which are increasingly mandated in procurement policies.
-
SB-Kawasumi Laboratories, Inc. (Japan) — SB-Kawasumi advances a manufacturing and clinical story that leans on sterilization (gamma processes) and bevel engineering to minimize tissue trauma. This technical differentiation supports premium positioning in clinical pathways that prioritize patient comfort and reduced local complications.
-
Asahi Kasei Corporation (Japan) — Asahi Kasei’s approach is systems-oriented, pairing needle sets with compatible tubing and clear lineup choices, targeting smooth integration into existing hemodialysis workflows and procurement bundles.
-
JMS Co., Ltd. (Japan) — JMS emphasizes reliable performance in buttonhole access and conventional hemodialysis scenarios; their product strategy is operationally focused, appealing to centers managing diverse access-site profiles.
Market dynamics and regulatory context
-
Patient and clinician safety drives product premiumization. Anti-stick needle protectors and safety-engineered designs are moving from “nice-to-have” to “procurement must-have” in many facilities. Documentation from manufacturers highlights safety mechanisms that directly reduce needlestick risk and downstream infection concerns.
-
Sterilization and bevel engineering matter. Gamma sterilization and refined bevel geometries are both clinical differentiators and manufacturing constraints. Providers increasingly look for validated sterilization pathways as part of their supplier selection criteria to reduce post-market risk.
-
Procedure economics are relevant at the tactical level. Updated CPT coding and regional fee-schedule changes alter the economics of certain access procedures; for example, changes in reimbursement for AV fistula interventions have immediate implications for hospital purchasing and service-line profitability.
-
Procurement behavior is shifting. Integrated renal networks, consolidation among dialysis providers, and the move toward value-based care mean buying decisions are less transactional and more outcome-oriented—favoring suppliers that can quantify complication avoidance and total cost of care improvements.
Opportunities and strategic plays for 2026
-
Product-led differentiation: Accelerate development and clinical validation of safety-enabled needle systems (e.g., anti-stick features, reduced-trauma bevels, lubricious coatings) and package these with outcome data to support premium pricing.
-
Clinical evidence strategy: Prioritize randomized or observational registries linking needle design to complication rates, cannulation success, and patient-reported comfort. These data sets unlock procurement pathways and justify higher ASPs (average selling prices).
-
Reimbursement intelligence: Map regional coding and fee-schedule changes to adoption scenarios. Commercial teams should craft playbooks that show hospital CFOs and procurement committees how device selection influences per-procedure economics.
-
Operational resilience: Secure validated sterilization capacity (including third-party gamma sterilization contracts) and insulate supply chains for polymers and manufacturing inputs that have historically shown volatility.
-
Commercial models for home dialysis: Build targeted portfolios and bundled offers for the growing home-dialysis segment, aligning product ergonomics, training, and service to enable adoption outside the center.
-
M&A and partnerships: Consider bolt-on acquisitions to shore up niche technology (e.g., safety shields, lubricious coatings) or to add sterilization bandwidth. Partnerships with clinical research organizations will accelerate evidence generation.
-
Pricing and contracting: Use outcome-based contracting pilots with large renal networks to create reference cases that can be scaled. Design pilot KPIs to include complication rates, cannulation time, and clinician satisfaction.
How to use PW Consulting’s full report in 2026 planning
-
Executive teams: Use the market scenarios and sensitivity analyses to stress-test strategic plans, capital allocation, and acquisition pipelines under alternative growth and price-pressure assumptions.
-
Commercial leaders: Adopt our segmentation frameworks and value-proposition templates to tailor sales plays for hospital systems, in-center dialysis operators, and home-care providers.
-
R&D and regulatory: Implement the device design checklists and compliance maps to accelerate time-to-market while minimizing post-market risk.
-
Operations and supply chain: Incorporate the capacity planning tools and sterilization risk assessments into 2026 production and supplier strategies.
-
Note: the report preview presented here intentionally omits the granular split tables and downloadable financial models—these are included in the full report package, which provides a complete view of regional, product-type and application-level segmentation alongside the raw Excel models used for our forecasts.
Conclusion
For executives shaping 2026 strategy, the A.V. Fistula Needles market presents an informed growth opportunity: steady top-line expansion, measurable levers for premiumization, and specific operational risks that are amenable to mitigation. PW Consulting’s full report converts these macro trends into executable actions—equipping leadership with the evidence, scenarios, and toolkits to win in a market where clinical outcomes and safety features increasingly determine commercial success. To access the complete segmentation tables, financial models, and playbooks needed to operationalize these insights, please consult the PW Consulting report page and supporting materials.
For detailed analysis of this topic, please visit the official page: A.V. Fistula Needles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com