

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Luxury Furniture Market to Hit USD 37.47 Billion by 2032 as Premium Demand Strengthens

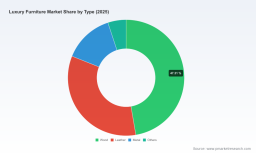
Luxury Furniture Market — 2026 Strategic Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to present a concise intelligence brief drawn from our new Luxury Furniture Market research (base year 2025, historical 2020–2025, forecast 2026–2032). The market has expanded from approximately USD 16.3 Billion in 2020 to USD 25.28 Billion in 2025 and is projected to reach roughly USD 37.47 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.74% across the 2026–2032 forecast window. This growth trajectory—combined with a market concentration profile where the top three players hold about 25% and the top five about 35%—creates a strategic inflection point for incumbents and new entrants alike.
Luxury Furniture Market
Why this report matters for 2026 corporate decisions
-
Decision clarity in a growth market: The luxury furniture sector is large and expanding at a steady mid-single-digit CAGR. That trajectory supports both organic premiumization strategies and targeted inorganic growth, but it also raises the stakes for capital allocation—where you place development, manufacturing, and channel investment in 2026 will shape returns over the full forecast horizon.
Luxury Furniture Market -
Concentration and consolidation opportunity: Moderate market concentration signals both enduring brand power and room for consolidation. Buyers and investors can expect attractive arbitrage where scale, distribution, or design IP can be integrated to accelerate margin expansion.
Luxury Furniture Market -
Regulatory and trade volatility: A cluster of recent policy actions and legal decisions has created near-term uncertainty for cross-border supply chains and pricing. Executives making sourcing and pricing commitments in 2026 must bake in tariff scenarios and trade-policy contingency plans.
-
Sustainability as a commercial lever: Market leaders are already moving beyond compliance into product redesign and circular models. Firms that embed verified circularity and durable value propositions in 2026 can capture premium positioning and reduce long-term cost volatility.
What the PW Consulting Luxury Furniture Market report delivers
-
Decision-ready executive dashboard: a consolidated view of historical performance (2020–2025) and forward scenarios (2026–2032) with scenario toggles for key variables—tariffs, raw material inflation, and premiumization speed.
-
Commercial playbooks: tailored GTM and pricing strategies for premium residential and commercial segments, including channel mix optimization (flagship retail, wholesale, contract, and digital direct-to-consumer) and experiential retail investments.
-
Supply-chain and sourcing frameworks: actionable sourcing maps and nearshoring/reshoring decision matrices to mitigate tariff and logistics exposure without eroding brand authenticity.
-
Competitive scorecards: non-proprietary strategic profiles and capability matrices for leading incumbents with implications for partnership, licensing, and M&A opportunities.
-
Sustainability toolkit: compliance checklists, circular-design roadmaps, and value-capture templates to convert sustainability investments into price premium and retention gains.
-
Financial and M&A models: sector-normalized cost and margin ranges, deal screening criteria, and integration playbooks to accelerate post-acquisition value realization.
-
Scenario and stress-testing templates: Excel-based models that let commercial and finance teams stress-test unit economics across tariff regimes, raw material shocks, and demand shifts.
Competitive landscape — strategic takeaways
We examined the positioning and recent strategic moves of established and specialist players, and distilled implications for market participants:
-
Legacy Italian maisons (e.g., Poltrona Frau, B&B Italia, Minotti, Cassina) remain powerful carriers of craftsmanship, design authorship, and licensing-led distribution. Their advantage lies in designer collaborations, deep brand equity, and premium pricing. For rivals, partnership, co-branding, or targeted acquisition of design IP are viable routes to accelerate brand sophistication.
-
French design houses (e.g., Roche Bobois) continue to leverage high-fashion positioning and showrooms as experience theaters. The strategic challenge for competitors is building comparable experiential assets without equal capex—digital showrooming and hybrid retail formats are pragmatic alternatives.
-
US firms (e.g., Knoll, Herman Miller, Restoration Hardware, Kimball International, Baker) demonstrate a range of approaches: Knoll and Herman Miller lean into design heritage and contract-market relationships; Restoration Hardware has pursued a vertically integrated, experience-first retail model; Kimball and Baker address contract and bespoke high-end residential niches. Each US approach offers different templates for scale, margin management, and channel control.
-
Newer entrants and standards-setters (e.g., DreamSofa’s May 2026 launch of a Sustainability Standard) are accelerating the shift from incremental sustainability claims to formalized circular product standards. This development will pressure legacy brands to articulate verifiable lifecycle impacts or risk ceding premium-share to credible newcomers.
Regulatory and trade context — why 2026 decisions must be scenario-based
-
Trade policy dynamics have real commercial consequences. Recent administrative delays to proposed tariff changes, proposed retaliatory tariffs on exports, and judicial rulings affecting reciprocal duties create asymmetric timing risks across supply chains and channels.
-
For 2026 planning, firms must adopt a multi-scenario approach to procurement, pricing, and inventory policies: immediate hedges for short-term duty continuations; contingent nearshoring if tariffs are enacted; and contractual protections for long-lead bespoke manufacturing.
Strategic imperatives for executives in 2026
-
Embed circularity into product DNA: Move from marketing claims to audited circular-design, repairability programs, and buy-back models. Use pilot collections to validate unit economics in 2026 and scale successful variants into core assortments.
-
Operationalize tariff scenarios: Establish a tariff war room with procurement, legal, and commercial leads. Implement flexible supply contracts and dual-sourcing strategies to reduce single-point exposure.
-
Prioritize channel mix efficiency: Rebalance retail footprint toward omnichannel experiences where physical spaces play discovery and experience roles while digital channels capture conversion and personalization.
-
Pursue selective M&A and strategic partnerships: Seek targets that deliver immediate capability uplift—design IP, nearshore capacity, or digital-first distribution—rather than only scale.
-
Invest in data and personalization: Deploy customer-level data platforms to allow configuration, customization, and integrated aftercare—these create recurring revenue and higher lifetime value in premium segments.
-
Reassess manufacturing footprints: Use a total-cost-of-ownership lens (including duties, logistics, lead time, and inventory carrying costs) to determine where to nearshore or automate.
-
Strengthen brand authenticity and provenance: For luxury buyers, verifiable craftsmanship, traceability, and service are part of the value proposition—invest in transparent storytelling supported by certifications.
-
Run 90–180 day pilots: Before large-scale rollouts, test pricing, circular services, and channel mixes via rapid pilots that feed back into strategic financing and full-launch decisions.
KPIs and governance to track through 2026
-
Customer acquisition cost and payback period by channel
-
Gross margin by configuration and bespoke vs. standard products
-
Returns and refurbishment yield for circular programs
-
Supply-chain lead-time volatility and tariff-cost delta
-
Share of orders routed through digital channels and percentage of repeat buyers
Conclusion — immediate next steps
2026 will be a pivotal year for executives in the luxury furniture sector: the market’s expansion and moderate concentration create both runway and competitive pressure. Those who combine disciplined scenario planning, targeted capability acquisition, and rigorous sustainability implementation will convert structural growth into enduring margin and brand advantage.
PW Consulting’s full Luxury Furniture Market report contains the granular regional, type, and application breakdowns, vendor market shares, pricing elasticity matrices, supplier cost curves, and executable playbooks (including downloadable financial models and scenario templates) that corporate strategy, M&A, and commercial teams need to act decisively in 2026. For access to the full datasets and strategic tools, please visit the PW Consulting report page or contact our industry team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Luxury Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com