

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dental Materials Market Poised for Strong Growth with a 5.8% CAGR, Driven by Prosthetics and Implant Demand

Dental Material Market 2026 Strategic Outlook: A PW Consulting Executive Brief
Executive Snapshot
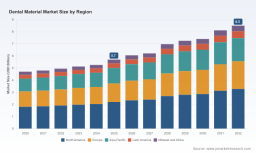
PW Consulting’s latest Dental Material Market report (base year 2025) delivers a data‑driven, decision‑ready view of an expanding global market. After growing from USD 4.7 Billion in 2020 to USD 5.7 Billion in 2025, the market is forecast to reach approximately USD 8.5 Billion by 2032 at a 5.8% CAGR across the 2026–2032 horizon. Market concentration remains moderate — with the top three firms accounting for roughly 45% and the top five roughly 58% of revenues — creating a landscape that favors both scale advantages and focused differentiation.
Dental Material Market
Why this report matters for 2026 planning
-
Strategic clarity for 2026 budget cycles: The report translates macro momentum into actionable priorities for R&D, commercial rollout, and supply‑chain investment during a pivotal post‑pandemic recovery window.
Dental Material Market -
Regulatory and reimbursement foresight: With multiple standards and code updates coming into effect in 2026, our analysis equips executives to align product development and market access plans with shifting compliance and payment realities.
Dental Material Market -
M&A and partnership playbook: We identify where scale is winning, where niches are opening, and how mid‑cap players can position for acquisition or profitable specialization.
-
Digital transformation guidance: The report puts dental 3D printing, resin innovation, and digital restorative workflows into a practical investment framework — helping firms set priorities across capex, IP, and go‑to‑market activities.
What the report contains (practical components)
-
Comprehensive market model: Historical series (2020–2025) and granular forecasts through 2032, with sensitivity testing across adoption, pricing, and regulatory scenarios.
-
Segment maps and demand drivers: Multi‑dimensional segmentation by region, material type, application, and end‑user — each accompanied by demand levers and tactical implications. (Note: detailed segment tables and numeric splits are available in the full report.)
-
Commercial playbooks: Go‑to‑market templates for incumbents and challengers covering channel strategy, pricing architectures, and value propositions tailored to dental labs, manufacturers, and clinics.
-
Regulatory and reimbursement tracker: An annotated timeline of standards, regulatory milestones, CDT code updates and certification programs with practical compliance checklists.
-
Competitive intelligence toolkit: Strategic profiles, capability heatmaps, patent trend snapshots, and a short list of high‑probability M&A targets.
-
Supply‑chain resilience checklist: Supplier risk scoring, nearshoring scenarios, and materials concentration analysis to mitigate disruption and cost pressure.
-
Decision support assets: Financial impact models, scenario dashboards, and executive one‑pagers to fast‑track board conversations and capital allocation choices.
Market dynamics shaping 2026 decisions
-
Steady demand growth. The market’s compound expansion to USD 8.5 Billion by 2032 reflects a combination of procedural volume recovery, demographic drivers, and higher‑value restorative and digital workflows.
-
Regulatory inflection points. Recent regulatory events have raised the bar for biocompatibility and device validation. Notably, authorities have clarified equivalence pathways for PMMA‑based temporary materials and signaled stricter compliance expectations tied to ISO biological evaluation standards. Concurrently, the ADA Forsyth Institute’s certification program will create a new quality signal for buyers starting early 2026.
-
Reimbursement realignment. CDT code updates in late 2025 have introduced a set of new and revised procedure codes that will materially affect reimbursement for restorative and surgical treatments. Manufacturers and service providers must recalibrate coding strategies to secure appropriate compensation for innovative materials and workflows.
-
Standards volatility. Recent rejection of a key ISO biocompatibility draft underscores uncertainty in global standards — a risk for firms that do not hedge product development with multiple validation pathways.
-
Technology acceleration. Additive manufacturing resins and digital materials continue to mature. Regulatory clearances for Class II resin indications and new adhesive chemistries have broadened clinical use cases and shortened time‑to‑adoption for digital restorative solutions.
Competitive landscape — how to read it
The market combines legacy incumbents with rising specialized players. Dominant multinational dental materials manufacturers retain scale advantages in distribution, regulatory depth, and channel relationships. Simultaneously, focused innovators — particularly in 3D printing resins and PMMA temporary systems — are capturing incremental share through product differentiation and regulatory wins.
-
3M Company (St. Paul, Minnesota) — Strengths: broad restorative portfolio, adhesive and resin technologies; strategic focus on nanotechnology adhesives and integrated restorative systems.
-
Dentsply Sirona (Charlotte, North Carolina) — Strengths: restorative materials and digital aligner ecosystems; recent regulatory clearances extend clinical indications across restorative and endodontic categories.
-
Kuraray Noritake Dental (Tokyo) — Strengths: advanced restorative chemistries within an integrated dental materials division focused on bonding and core restorative substrates.
-
Ivoclar Vivadent AG (Schaan) — Strengths: comprehensive restorative and bonding product lines with deep clinical adoption in prosthetic workflows.
-
GC Corporation (Tokyo), Coltene Holding AG (Altstätten), Heraeus Kulzer GmbH (Hanau), DMG (Hamburg), UltrAdent (South Jordan) — Established players with focused competencies in restorative, impression, and bonding systems.
-
SprintRay (Long Beach), Formlabs (Somerville), Taiwan Dental Materials Co., Ltd. (Taipei) — Specialists in 3D printing resins and PMMA systems; recent regulatory actions have increased their market impact and clinical acceptance.
Recent market signals and implications
-
Regulatory clearances and product launches are validating new material classes and clinical workflows. Examples include recent FDA 510(k) clearances and product introductions across PMMA and advanced resin categories.
-
New certifications and procedural codes will alter purchase drivers: clinicians and labs will increasingly favor materials with explicit conformity and reimbursement alignment.
-
Moderate concentration (CR3 ~45%, CR5 ~58%) indicates that while large players control substantial share, there is room for specialist entrants to scale via regulatory differentiation and digital channel strategies.
Strategic playbook: Five priorities for 2026
-
Prioritize regulatory‑first product roadmaps. Allocate 2026 R&D dollars to ensure compliance with both FDA equivalence requirements and the emergent ADA certification expectations. Dual‑track validation (biocompatibility + clinical performance) reduces launch risk.
-
Monetize digital workflows. Invest in materials formulated for additive manufacturing and integrated restorative systems. Bundled offerings — printer + validated resin + clinical protocols — command premium pricing and higher switching costs.
-
Reconfigure go‑to‑market for new codes. Realign sales incentives and training to leverage the late‑2025 CDT code set; educate payers and providers to capture appropriate reimbursement for advanced materials and procedures.
-
Targeted M&A or licensing to fill capability gaps. Look for bolt‑on acquisitions that deliver regulatory clearance, digital resin IP, or narrow channel access rather than broad headline buys. Our report’s shortlist and valuation scenarios help prioritize targets.
-
Harden supply‑chain risk management. Map critical raw material exposures, diversify source geographies for key chemistries, and evaluate nearshoring options to protect margins against commodity and logistics shocks.
How executives should use this report in 2026
Use the report as a tactical toolkit in board and executive forums: populate scenario planning templates with our market model to test different adoption paths, stress‑test product portfolios against regulatory scenarios, and quantify the ROI of accelerated digital investments. For business development and corporate development teams, the competitive intelligence dossiers and M&A screening models provide prioritized targets and deal rationale aligned to market dynamics.
Data integrity and methodology
Our projections combine primary interviews with clinicians, manufacturers, and payers; proprietary demand and pricing models; and public regulatory disclosures. The historical series (2020–2025) and the forecast period (2026–2032) reflect adjustments for documented regulatory events, coding changes, and observed technology adoption curves. Scenario analysis quantifies upside and downside paths to 2032 based on alternative assumptions for adoption velocity, pricing shifts, and regulatory timing.
Next steps — where to get the full intelligence
This executive brief intentionally emphasizes the report’s strategic value while withholding granular segment tables and proprietary numeric splits to preserve the decision‑support value available in the full report. To access the complete dataset (including regional/type/application/end‑user tables, price and volume assumptions, downloadable models, and the full competitive matrix), visit the PW Consulting report page or contact our client services team for a tailored briefing.
PW Consulting remains available to support immediate 2026 planning workshops, M&A diligence, and regulatory readiness programs derived from this research.
For detailed analysis of this topic, please visit the official page: Dental Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com