

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Smart Dog Collar Market Set to Leap from USD 490 Million in 2025 to USD 1.10 Billion by 2032 at a 12.25% CAGR
By pmarketresearch, 2026-06-30
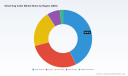
PW Consulting: Strategic Preview — Smart Dog Collar Market Outlook (Base Year 2025, Forecast 2026–2032)
PW Consulting today releases an executive preview of our forthcoming Smart Dog Collar Market report, a tactical briefing designed to inform C-suite and investment decisions in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the study models an addressable market that accelerated from approximately USD 280.5 million in 2020 to USD 490.0 million in 2025 and is projected to surpass USD 1.09 billion by 2032 under a 12.25% compound annual growth rate (CAGR). This preview summarizes the strategic takeaways, competitive dynamics, and regulatory inflection points that will shape next‑mile commercial choices — while reserving the detailed segment-level tables and exact regional/application breakdowns for the full report.
Smart Dog Collar Market
Why this matters for 2026 decision-makers
Smart dog collars have moved beyond early-adopter novelty into commercially relevant product lines for hardware vendors, software platforms, pet health players, insurers, and retail channels. The market’s double-digit CAGR reflects three converging trends: improving sensor and low-power GNSS technology, increasingly sophisticated AI-driven health analytics, and regulatory and reimbursement incentives that validate collar-sourced data as actionable in veterinary and travel contexts.
Smart Dog Collar Market
- Timing: 2026 is a window for market share moves — technologies and standards that are being finalized now will determine compliant product roadmaps into 2028–2030.
- Monetization: Recurring subscription models (connectivity, analytics, telehealth integration) and embedded services (vet alerts, insurance claims support) are the primary vectors for improving gross margins beyond unit sales.
- Risk vs. Reward: The sector is neither a winner-take-all monopoly nor fully fragmented; top-tier firms hold meaningful share but room remains for specialist entrants and channel-focused innovators.
What the report delivers (practical outputs)
PW Consulting’s report is built around operational utility. Our deliverables are structured to convert market intelligence into executable plans for product, commercial, regulatory, and corporate development teams.
Smart Dog Collar Market
- Market sizing and forecasting models (base 2025; historical 2020–2025; forecast 2026–2032), delivered as configurable Excel workbooks so you can stress-test alternate scenarios.
- Go-to-market playbooks: pricing ladder options, subscription bundling strategies, channel segmentation for retail, DTC and B2B (veterinary and insurance partnerships).
- Technology and product roadmaps: component cost curves, battery-life tradeoffs, GNSS vs. low-power location tradeoffs, and AI health analytics maturation timelines.
- Regulatory and compliance checklists tailored to the EU and North America, covering device certification, RF emissions, data protection, and travel compliance.
- Supply‑chain and manufacturing audit templates: sourcing risk maps, supplier scorecards, and cost-to-serve models for paired hardware/software products.
- M&A and partnership shortlists: screening criteria and due-diligence templates for tuck‑ins, IP purchases, and distribution agreements.
- Commercial-ready POVs: 12–24 month tactical roadmaps for incumbents and entrants, and investor memos that translate market projections into revenue and EBITDA scenarios.
To maintain the “trailer” principle of this preview, we outline themes and actionable recommendations here while preserving the detailed regional, application, and product-split tables for report subscribers.
Competitive landscape: positioning and recent moves
The competitive field combines consumer electronics veterans, GPS specialists, pet-health start-ups, and modular hardware vendors. Market concentration is moderate: the top three firms control a meaningful minority of market value while the top five increase that footprint — indicating both consolidation potential and continued opportunity for niche differentiation.
- Fi (New York, US) — Known for long-battery GPS collars, Fi has advanced into AI-enhanced health telemetry with its Series 3+ product and expanded into the UK and EU in early 2026. Their strengths are integrated hardware/software optimization and a clear retail and direct-to-consumer positioning.
- Tractive (Austria) — A strong GPS-tracker incumbent that has broadened health and behavior analytics in its DOG and CAT series. Recent launches (including larger and mini variants) underscore a playbook focused on product line breadth and differentiated user experiences.
- PetPace (Burlington, MA) — Differentiates on medical-grade vital-sign monitoring and 24/7 vet-alert integration, targeting health‑centric use cases and B2B veterinary partnerships.
- Nuzzle (US) — Focuses on detachable tracker modules for modularity and retrofitting existing collars, a strategy attractive to channel partners and consumers who prefer upgradeable hardware.
- LINK AKC, Garmin, Petsafe, Whistle, KYON, Marco Polo, Gibi, WÜF, Loc8tor — These firms range from premium GPS and sports-tracking brands to specialist pet-tech vendors. Competition is defined by tradeoffs: platform ecosystems and data services versus hardware robustness and battery economics.
Recent product and market developments included several 2026 launches (notably AI-enabled collars and expanded form factors) and regulatory milestones that are accelerating product certification timelines. These moves create near-term opportunities for licensing, OEM partnerships, and white-label offerings.
Regulatory, data and reimbursement dynamics
Regulatory developments are a defining variable for 2026 strategies. The EU adopted GPS-tracking standards intended to increase safety and accuracy, and North American RF guidance was clarified to enable broader certification pathways. At the same time, data sovereignty and privacy regimes (notably GDPR in Europe and divergent state-level requirements in North America) create conflicting documentation and storage demands that can materially affect cloud architecture and time-to-market.
- Certification playbook: Build a compliance roadmap aligned to EU GPS standards and FCC RF specifications early in product development to avoid costly rework.
- Data strategy: Adopt a privacy-by-design approach with options for regional data residency and consent-first telemetry to address competing legal regimes.
- Reimbursement & monetization: An emerging trend is insurer and veterinary reimbursement for collar-derived health data — a nascent but accelerating channel that can underpin subscription economics.
Strategic recommendations for 2026 (by stakeholder)
- Incumbent hardware vendors: Prioritize AI analytics partnerships and capitalize on software-as-a-service margins. Invest in certification and supply-chain redundancy to shorten certification cycles and avoid single-source risks.
- New entrants: Focus on niche value propositions — modularity, veterinary-grade monitoring, or specialized geofencing — and use channel partnerships with insurers and clinics to de-risk customer acquisition.
- Retail and veterinary channels: Leverage data-driven services to expand recurring revenue (telehealth, data-enabled wellness plans) and create bundled offerings that lower churn.
- Investors and M&A teams: Target tuck‑ins that add analytics IP, regional certification expertise, or distribution capabilities — consolidation is likely as the market professionalizes.
Methodology and access to the full intelligence
The full PW Consulting Smart Dog Collar Market report uses a blended approach: bottom-up device and subscription telemetry, primary interviews across manufacturing, retail and veterinary channels, and cross-validated macro assumptions. Base year is 2025 with historical coverage 2020–2025 and a forecast to 2032. Revenue figures are expressed in USD (Million) and forecasts incorporate scenario-testing around regulatory adoption, component-price declines, and subscription conversion rates.
Subscribers receive a comprehensive Excel model, regional and application breakdowns, go-to-market playbooks, vendor scorecards, and an M&A shortlist. For reasons of confidentiality and to preserve competitive value, the preview intentionally omits the granular tables that segment the market by region, device type and application — these are available in the full report package.
Next steps
For executives preparing decisions in 2026 — whether refining product roadmaps, negotiating distribution agreements, or sizing acquisition targets — this market is at an inflection point. PW Consulting’s full report converts the macro momentum and regulatory detail summarized here into step‑by‑step commercial plans and financial models. Contact our research team to request the report, arrange a tailored briefing, or license the underlying model for internal scenario planning.
PW Consulting remains committed to delivering operational foresight that converts market intelligence into executable advantage. The smart dog collar market will reward those who align product design, compliance and services strategy in the next 12–24 months; our report shows how to do that without sacrificing speed to market.
For detailed analysis of this topic, please visit the official page: Smart Dog Collar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Engineering Tech Center Market to Grow from USD 145 Million in 2025 to USD 203 Million by 2032 at a 5.25% CAGR
By pmarketresearch, 2026-06-30
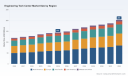
PW Consulting Releases Strategic Market Brief: Engineering Tech Center Market — Critical Guidance for 2026 Decision-Making
Executive summary
PW Consulting today published a focused market brief, the Engineering Tech Center Market Report (base year 2025, historical window 2020–2025, forecast 2026–2032). Built for senior leaders making capital allocation, site strategy, and product development decisions in 2026, the brief synthesizes quantitative market modeling with on‑the‑ground facility assessments and vendor benchmarking. Our core forecast shows the market expanding from approximately USD 145 million in 2025 to an estimated USD 203 million by 2032 — a compounded annual growth rate of roughly 5.25% — underscoring steady, investment‑grade growth driven by product innovation cycles, localized prototyping needs, and increased demand for controlled testing environments.
Engineering Tech Center Market
Why this report matters for 2026 strategic planning
-
Timing of investment: 2026 is a hinge year for companies that must decide between centralized lab consolidation and distributed “edge” Engineering Tech Centers designed for rapid prototyping and customer co‑development. Our analysis quantifies the valuation implications of each approach and maps the operational tradeoffs that matter most to executive boards.
Engineering Tech Center Market -
Funding and portfolio choices: With predictable mid‑single digit CAGR and identifiable pockets of premium margin activity, boards and PE sponsors can prioritize investments that accelerate time‑to‑customer and reduce NPI cycle time without materially increasing fixed overhead.
Engineering Tech Center Market -
Talent and regulatory planning: The brief links facility requirements to talent sourcing strategies and regulatory exposures that tend to surface as Tech Centers scale from pilot to production support roles.
What you’ll find in the report — practical, decision‑ready content
This is deliberately an operationally focused study designed to move leaders from analysis to action. Highlights include:
-
Investment playbook: step‑by‑step decision matrices for greenfield versus retrofit Tech Centers, including CapEx/Opex modelling templates and sensitivity scenarios tailored to different product types (optical, electro‑optical, digital visualization).
-
Site selection framework: a scoring model that blends accessibility to talent, supply‑chain proximity, real estate costs, utility and permitting risk, and time‑to‑operational readiness.
-
Facility design and layout templates: sample lab footprints (cleanroom gradings, test bays, collaborative demo spaces), equipment lists, and throughput simulations that translate strategic intent into square‑foot and staffing plans.
-
Operational playbook: SOPs for rapid prototyping workflows, test protocol checklists, quality gates, and supplier integration guidelines to compress NPI timelines while safeguarding IP.
-
Commercialization and customer engagement models: go‑to‑market templates for using Tech Centers as sales accelerators, co‑development hubs, and training centers.
-
Risk and compliance toolkits: a regulatory matrix, hazardous materials handling checklist, and market entry considerations for defense‑adjacent optical and imaging technologies.
-
M&A and partnership playbook: diligence checklists and integration roadmaps for bolt‑on acquisitions of lab assets, technology license arrangements, and strategic alliances.
Methodology and confidence
The report blends quantitative market-sizing with qualitative validation. Key inputs include: proprietary revenue modeling (reporting in USD millions), primary interviews with facility operators and technology buyers, on‑site assessments of exemplar Tech Centers, equipment vendor benchmarks, and scenario analysis across alternative adoption curves. We deliberately use a base year of 2025 and a forecast horizon through 2032 to align with typical capital planning cycles and to support multi‑year budgeting decisions.
Competitive landscape — who to watch and why
The Engineering Tech Center market exhibits moderate concentration; top three firms account for a material but not dominant share, while the top five capture roughly half of industry revenue—an environment that rewards both specialized niche players and scale‑enabled platforms. Our qualitative analysis identifies two distinct strategic archetypes that are particularly instructive for 2026 planning:
-
High‑specialization, mission‑driven facilities: companies that invest in deep lab capabilities aligned to a narrow product class (for example, precision electro‑optics for defense and high‑accuracy imaging). These operators compete on technical differentiation, integrated testing capabilities, and IP protection strategies.
-
Customer‑facing collaboration centers: vendors and OEMs that design Tech Centers primarily to accelerate adoption, training, and demonstration for commercial customers. These centers emphasize immersive demo spaces, training curricula, and rapid customization pipelines.
Recent facility investments — practical implications
Two recent facility openings illustrate the strategic calculus that executives should consider when evaluating their own Tech Center plans.
-
EOTECH (Plymouth, Michigan) inaugurated a new Engineering Tech Center in Orofino, Idaho in early 2025. The facility features a purpose‑built optics lab with cleanroom capabilities and precision test gear intended to shorten R&D cycles for weapon sights and camera systems. For competitors and partners, the move signals a commitment to in‑house prototyping and vertically integrated testing — a model that raises the bar for suppliers that rely on legacy external labs.
-
Vision Engineering Ltd (Send, UK) launched a West Coast Tech and Training Center in Irvine, California, also in 2025, focused on immersive visualization and digital microscopy demonstrations. The center emphasizes customer co‑development and hands‑on training with the latest product portfolio. This underscores a contrasting strategy: using Tech Centers to drive adoption and product stickiness rather than to centralize complex manufacturing testing.
Both examples highlight a central strategic choice: prioritize deep technical testing vs. prioritize customer engagement. Many mid‑market players will pursue hybrid models, but the path chosen has immediate capex, talent, and partnership implications that we map in the report.
Market dynamics and strategic implications
-
Structural growth with pockets of premium: Moderate market expansion at roughly 5.25% CAGR suggests that well‑timed investments can be accretive if they capture adjacent service revenue or improve product commercialization velocity.
-
Fragmentation creates opportunities: With a meaningful share held by specialized players, there are acquisition and partnership opportunities for companies seeking rapid capability build‑out without incurring full greenfield costs.
-
Operational complexity is underestimated: Our fieldwork shows that the hidden costs in facility qualification, staffing, and certification frequently extend payback timelines unless managed with explicit gating and milestone economics.
Actionable recommendations for 2026
-
Run a defend vs. expand decision: Use our CapEx/Opex template to model a defend‑or‑expand scenario for each product line in 60–90 day decision cycles. Prioritize experiments that demonstrate measurable reductions in NPI lead times.
-
Adopt a two‑tier hub strategy: Consider a compact central lab for high‑complexity testing paired with regional demo/validation hubs to accelerate sales and shorten feedback loops. The report provides a decision matrix to quantify this tradeoff.
-
Lock in supplier roadmaps early: Negotiate equipment and service contracts with performance SLAs tied to throughput and qualification timelines to protect against backlogs that can derail go‑to‑market launch plans.
-
Embed scalability criteria: Design facilities with modularity in mind so they can pivot between R&D, pilot production, and customer demonstration without major rework.
How to use this brief and where to access detailed datasets
This market brief is intentionally positioned as a high‑value preview: it outlines core forecasts, strategic frameworks, and operational checklists that senior teams can act on immediately while withholding select granular segment tables and regional/application breakdowns that form the basis for executable site and investment decisions. The full report includes comprehensive, downloadable models, regional and application splits, facility benchmarking data, and appendices with interview summaries and sample contractual terms.
To download the complete report, view Excel modeling workbooks, and access the proprietary benchmarking dataset, please visit our report page. The full dataset is available to subscribers and corporate clients who require the granular inputs for budgeting, M&A, and site selection exercises.
Closing perspective
Engineering Tech Centers are becoming a strategic lever: not merely a line item on an operations budget but an active part of product strategy and customer engagement. With predictable mid‑single digit growth and evolving competitive dynamics — including targeted investments from both equipment specialists and customer‑facing OEMs — 2026 is the year to convert strategy into tangible assets or strategic partnerships. PW Consulting’s Engineering Tech Center Market Report equips leaders with the frameworks and templates to do exactly that, while preserving the granular datasets that will inform definitive capital and partnership decisions.
For detailed analysis of this topic, please visit the official page: Engineering Tech Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cryotherapy Units Market to Grow from USD 228.19 Million in 2025 to USD 359.3 Million by 2032 at a 6.7% CAGR
By pmarketresearch, 2026-06-30
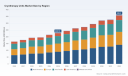
Cryotherapy Units Market — Strategic Outlook for 2026: A PW Consulting Industry Brief
Executive snapshot
As demand for non-opioid pain therapies and sports/rehabilitation recovery continues to mature, the cryotherapy units market is entering a decisive phase of commercialization and regulatory standardization. Using 2025 as the report base year and projecting across 2026–2032, PW Consulting’s newly released study quantifies a market that expanded materially through the first half of the decade and is projected to grow at a compound annual growth rate (CAGR) of 6.7% across the forecast window. In concrete terms, total industry revenues rose from the low hundreds of USD Million in 2020 to USD 228.19 Million in 2025 and are modelled to reach USD 359.3 Million by 2032 under our central case.
Cryotherapy Units Market
Why this report matters for 2026 decision-makers
-
Regulatory inflection: The introduction of the FDA’s Quality Management System Regulation (QMSR) in February 2026 — with ISO 13485:2016 alignment as a de facto requirement for finished medical devices — changes the compliance baseline for new and incumbent manufacturers. Firms that invest early in compliant systems will reduce time-to-market friction and preserve reimbursement pathways.
Cryotherapy Units Market -
Reimbursement acceleration: Recent payer moves extending coverage for temperature-regulated electric cryotherapy solutions under non-opioid device codes and qualifying Medicare outpatient reimbursements materially improve the economic case for clinical deployments. This transforms many go-to-market packages from discretionary spend to billable interventions in post-surgical care.
Cryotherapy Units Market -
Technology transition: The market is negotiating a shift in the cooling architecture mix (e.g., liquid nitrogen vs. electrically regulated cooling). Electric systems compress operating cost over the lifetime but typically require higher initial capital expenditure — a trade-off that alters sales models, financing needs, and lifecycle service revenue strategies.
-
Fragmented competitive landscape: While recognized vendors hold leading product portfolios, overall market concentration remains relatively low, leaving room for strategic consolidation, niche specialization, and service-led differentiation. Our CR3 and CR5 metrics quantify this fragmentation and inform M&A and partner-screening approaches.
-
Commercial runway: The combination of a predictable CAGR and emerging reimbursement creates an actionable 36–60 month commercialization window for companies that align product development, regulatory clearance, and payer engagement now.
What’s inside the PW Consulting report — practical, executable content
This study was designed as an operator’s toolkit for strategists, product leaders, and corporate development teams. It deliberately balances market intelligence with executable playbooks rather than high-level theory. Key deliverables include:
-
Transparent market sizing and growth methodology (TAM / SAM / SOM frameworks), including historical tracking (2020–2025) and scenario-driven forecasts for 2026–2032.
-
Regulatory and reimbursement playbooks: step-by-step roadmaps to satisfy QMSR/ISO 13485 requirements, prepare 510(k) submissions, and operationalize reimbursement capture under current coding guidance.
-
CapEx / OpEx comparative models: lifecycle cost models that compare nitrogen-based and electric cooling architectures, sensitivity to utilization, and financing options (purchase, lease, shared models).
-
Commercial and channel blueprints: segmented go-to-market funnels for hospital outpatient, clinic/studio, sports medicine, and corporate wellness channels, plus detailed pricing and bundling strategies to convert early adopters under emerging reimbursement rules.
-
Competitive scorecards and product benchmarking: independent evaluation of device performance, clinical evidence, installation footprint, and aftermarket service economics.
-
M&A and partnership maps: prioritized target lists, valuation heuristics, and integration risk matrices for inorganic growth or strategic alliances.
-
Operational playbooks: supplier sourcing checklists, manufacturing vs. contract production decision trees, and a parts-and-service playbook to generate annuity revenue and preserve customer lifetime value.
-
100-day and 12-month tactical roadmaps: prioritized actions for launching or scaling in 2026, including KPI dashboards and milestone templates.
Competitive landscape — players to watch and strategic positioning
The report synthesizes company-level intelligence to help readers identify competitors, partners, and acquisition targets. A short, non-exhaustive view of core participants and their strategic posture:
-
Zimmer MedizinSysteme GmbH (Neu‑Ulm, Germany) — A legacy European player with deep clinical and sports-rehab reach. Recent product development (January 2026) shows a clear pivot to electric temperature-regulated clinical systems, signaling a strategic bet on lowering lifecycle operating costs while meeting clinical-grade expectations.
-
CRYO Science (Poland, with North American operations) — Focused on both nitrogen and electric platforms for professional and sports markets. Maintains flexible manufacturing and distribution footprints that can be leveraged for regional scaling or rapid product iteration.
-
CRYONiQ s.r.o. (Slovakia, with U.S. presence) — Known for whole-body and localized lines and a manufacturing environment with ISO-controlled processes. The company’s dual EU/US positioning is a source of regulatory know-how and cross‑market product adaptation.
-
Cryo Innovations (Newport Beach, CA) — A U.S.-centric developer of advanced chamber and localized devices geared to clinics and corporate wellness programs. Strengths include channel access to alternative wellness buyers and agility in product customization.
-
CryoBuilt (USA) — A domestic manufacturer with an established installed base exceeding several hundred clinics and studios. This installed base demonstrates a route to service and aftermarket revenue, and is a strategic asset for any firm looking to scale quickly in North America.
PW Consulting’s competitive matrices combine product features, regulatory readiness, installed base metrics, and service economics to help executives decide whether to compete, partner, or acquire in specific subsegments.
Regulatory & reimbursement dynamics — constraints and strategic levers
-
QMS and approval: With QMSR enforcement and the industry expectation of ISO 13485 alignment, product teams must budget for quality systems workstreams and third‑party audits early in 2026. This is a gating factor for clinical sales and reimbursement capture.
-
FDA 510(k) and standards: Device classification and adherence to FDA-recognized consensus standards remain necessary for safe clinical use and hospital procurement. The report includes a checklist of recommended standards and FDA submission strategies.
-
Payer engagement: The extension of coverage for certain electrically regulated cryotherapy systems under non-opioid codes and updated Medicare outpatient policy meaningfully impact commercial models. The report provides payer-specific engagement templates and outcomes evidence requirements to secure coverage and appropriate billing.
Manufacturing, supply chain, and cost structure considerations
Strategic choices about cooling architecture and manufacturing footprint strongly influence economics. Electric systems reduce consumables and recurring logistics complexity, improving predictability for high-utilization sites but requiring higher upfront investment and different service competencies. Conversely, nitrogen-based designs can have lower initial equipment cost but introduce supply chain dependencies for consumables and facility requirements. The study contains supply‑chain stress tests, vendor scorecards, and recommended contracting language to mitigate downtime and spare-parts risk.
Concrete strategic playbook for 2026
-
Prioritize regulatory readiness: complete ISO 13485 alignment and map 510(k) pathways in the first two quarters of 2026.
-
Design financing options: offer leasing, subscription, or revenue-share models to offset higher CapEx of electric systems and accelerate adoption under reimbursement.
-
Invest in clinical evidence: generate targeted outcomes studies that support payer coverage and clinician adoption, focused on post-surgical analgesia and outpatient rehabilitation endpoints.
-
Monetize service: build a scalable parts-and-service organization to create annuity revenue and protect installed base economics.
-
Pursue selective M&A: use consolidation to gain installed base, cross-border regulatory expertise, or manufacturing capacity, informed by the report’s M&A scoring framework.
-
Differentiate commercially: bundle device, training, and data analytics to move from a one-time capital sale to an outcomes-based solution that aligns with payer incentives.
How PW Consulting’s report accelerates execution
Clients who adopt the report as their operational playbook receive not just market maps but tools that shorten execution cycles: ready-to-run financial models, go-to-market templates, regulatory checklists, payer engagement scripts, and a prioritized action plan calibrated to the 2026 regulatory and reimbursement environment. For executives evaluating acquisition targets or new product launches, our strategic dashboards make trade-offs explicit and provide near-term milestones to de‑risk commercial entry.
Next steps
The Cryotherapy Units Market is no longer an experimental niche; it is a regulated, reimbursable, and investable category with clear winners and losers emerging in 2026. PW Consulting’s full report includes the confidential segmentation detail, company-level financials, and drill-down scenario models intentionally omitted from this brief to preserve the report’s role as a primary advisory asset. To access the complete intelligence package — including downloadable models and bespoke advisory options — contact PW Consulting or visit our report page for an executive excerpt and licensing information.
For detailed analysis of this topic, please visit the official page: Cryotherapy Units Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Photo Printing and Merchandise Market Poised for 6.5% CAGR — Strategic Outlook for 2026–2032
By pmarketresearch, 2026-06-30
Photo Printing and Merchandise Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
Executive preview — why C-suite leaders must read this before finalizing 2026 plans
As the intersection of physical memories and mass-customized merchandise continues to evolve, executives face a pivotal planning window for 2026. PW Consulting’s latest market study, with a 2025 base year and a detailed forecast through 2032, synthesizes five years of historical performance and forward-looking scenarios to convert industry complexity into boardroom-ready choices. The global market expanded materially from the early-decade baseline and, under our central forecast, is set to grow at a steady mid-single-digit compound rate—reflecting durable demand for physical photo products even as digital channels mature.
Photo Printing and Merchandise Market
Headline macro view
-
Market trajectory: The industry recorded sustained growth through 2020–2025, reaching a robust base in 2025 and, by our forecast, will continue expanding across the 2026–2032 horizon at a compound annual growth rate of 6.5%.
Photo Printing and Merchandise Market -
Consolidation signal: Competitive concentration remains modest. Aggregate shares of the largest three and five market participants indicate a market that still favours regional champions and niche specialists rather than dominant global monopolies—creating attractive windows for focused scale plays and targeted M&A.
Photo Printing and Merchandise Market -
Channel evolution: Digital ordering, same-day retail pickup, and embedded merchandising within social/photo apps are driving revenue mix shifts and operational implications for fulfillment networks and CAPEX planning.
What this means for 2026 corporate decision-making
2026 will be a year where optionality—rather than mere survival—defines winners. Firms that convert the industry’s steady top-line trajectory into differentiated operating models will capture outsized margins. Specifically, three high-impact implications should shape 2026 decisions:
-
Prioritize modular manufacturing investment. With demand remaining resilient, investments in flexible print lines, digital embellishment technologies, and short-run finishing reduce unit economics risk while enabling premium SKUs.
-
Rebalance channel economics. Omnichannel fulfilment strategies—combining direct-to-consumer digital storefronts, retail kiosk partnerships, and strategic B2B agreements—will be decisive for customer acquisition cost (CAC) control and lifetime value (LTV) optimization.
-
Apply disciplined M&A and partnership frameworks. Given a market where top players hold meaningful but non-overwhelming shares, acquisitive growth should prioritize capability gaps (e.g., color management, photo-editing platforms) over scale-only deals.
Competitive landscape — targeted analysis of leading players
Our report provides a pragmatic, comparative view of incumbent and challenger strategies across the value chain. Highlights include:
-
Shutterfly, Inc.: A consumer-oriented platform with deep expertise in personalized books and gift assortments. Recent product launches and editorial recognitions underscore its continued focus on seasonal and lifestyle collections, while operational rationalizations in select regions reflect active cost optimization.
-
Snapfish and Mpix: Both maintain strong consumer-facing storefronts; Mpix emphasizes higher-margin, premium photographic output while Snapfish emphasizes scale and broad accessibility through promotional channels.
-
Nations Photo Lab and specialist silver-halide providers: These firms continue to defend margins through premium archival positioning and pro-market relationships—key for channels where archival quality is the purchase driver.
-
Blurb, Photobox, CEWE, Fujifilm, Kodak Alaris and Vistaprint (Cimpress): These incumbents illustrate a spectrum from premium bookmaking to mass-customization platforms. Recent innovation awards and product programs from some of these players reinforce the competitive role of technology-led differentiation.
Collectively, market concentration metrics confirm an environment where specialized product/capability leadership can deliver meaningful returns without having to displace entrenched scale players outright.
Operational and regulatory dynamics to factor into 2026 plans
-
Labor and cost pressure: Strategic cost management remains front and center. Several industry participants have undertaken workforce realignments and are investing in automation—important context for outsourcing, nearshoring and CAPEX decisions.
-
Regulatory and trade considerations: Trade-related regulation and cross-border compliance continue to influence sourcing choices and capital allocation. Expect incremental costs in certain export-sensitive workflows; contingency planning for tariffs and trade friction is prudent.
-
Demand signals: Despite strong digitalization, end-consumer appetite for physical products—photo prints, books and branded merchandise—remains persistent. Production data points from major imaging firms underscore sustained unit volumes and the ongoing importance of product innovation.
Actionable strategic playbook for 2026
Based on quantitative modeling and scenario stress tests, PW Consulting recommends a five-point strategic playbook to convert market momentum into profit growth:
-
Segment-to-profit focus: Instead of broad-based expansion, prioritize customer segments and product lines with the highest margin elasticity under different cost and demand scenarios. Use rapid A/B pilots to validate product-market fit before full rollouts.
-
Platform and partnership doubling-down: Invest selectively in digital platforms that lower CAC and increase repeat purchase frequency. Where internal development is slow or capital-intensive, pursue bolt-on partnerships to accelerate capability acquisition.
-
Manufacturing flexibility: Adopt a hybrid capacity model—core facilities for premium, archival-grade products and distributed micro-fulfillment for commoditized SKUs—to reduce lead times and logistics costs while preserving product differentiation.
-
Pricing architecture and promotions: Transition from discount-led acquisition to value-capture pricing—tiered offerings, subscription bundles, and event-driven merchandising—to stabilize margins and raise lifetime value.
-
Environmental and brand governance: Embed sustainability metrics into procurement and product design. Consumers increasingly reward brands that transparently demonstrate material and operational stewardship.
What’s inside PW Consulting’s full report (practical deliverables)
We built this study as an operator’s toolkit, not a static market narrative. The full deliverable includes:
-
Executive dashboards with scenario-based topline forecasts, sensitivity tables and break-even analyses tailored to common business models in photo printing and merchandise.
-
Detailed competitor fiches and capability heatmaps to triangulate product, channel and technology strengths and weaknesses—designed to shorten due diligence cycles.
-
Operational playbooks: sample P&L templates, capital allocation models for print-line investments, and a supplier scorecard you can adapt for vendor negotiations.
-
Go-to-market blueprints: customer personas, promotions playbooks, and channel margin models that link acquisition levers to unit economics.
-
M&A and partnership framework: a prioritized pipeline of capability gaps, valuation assumptions, and integration risk checklists to accelerate execution.
To preserve commercial value for subscribers and prospective clients, the report intentionally does not publish granular segment revenue splits in our public summary. The full data tables, including regional and product-level scenarios and model inputs, are available to purchasers and licensed subscribers.
Methodology and credibility
The study combines five years of historical trend analysis with a bottoms-up supply-chain assessment and primary interviews across the value chain. We blended stated and revealed preference data, production-volume indicators, and technology adoption signals to construct a high-resolution forecast model. Key quality controls include scenario validation with industry finance heads, triangulation against major equipment OEM production data, and sensitivity testing for labor and trade shocks.
Final counsel: what to do next
For executives formalizing 2026 budgets, there are three immediate, measurable steps to take in the next 60–90 days:
-
Commission a rapid cost-to-serve audit across top SKUs to quantify the ROI threshold for automation and nearshoring.
-
Run a two-month digital promotion experiment to isolate CAC drivers and validate subscription or bundle economics for repeat buyers.
-
Map the top three capability gaps that would most improve margin mix—then evaluate build vs. buy across those capabilities using a short-list from our M&A framework.
PW Consulting’s Photo Printing and Merchandise Market report is structured to convert these actions into measurable outcomes. For organizations that need the full data tables, scenario models, and supplier scorecards to underpin 2026 investment or acquisition decisions, full access and licensing options are available through our report page. Contact PW Consulting to arrange a briefing and receive a tailored executive summary aligned to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Photo Printing and Merchandise Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Soy Lecithin Market to Climb from USD 195.25 Million in 2025 to USD 309.9 Million by 2032 at a 6.98% CAGR, While Top 3 Players Hold 65.5% Share
By pmarketresearch, 2026-06-30
Soy Lecithin Market 2026 Outlook — Strategic Imperatives for Boards, Procurement and R&D Leaders
PW Consulting’s latest market study on Soy Lecithin delivers an executive-grade synthesis of the industry’s trajectory through 2032, framed expressly to inform high-stakes decisions for the 2026 planning cycle. Anchored on a 2025 base year and a historical review covering 2020–2025, the study projects the global soy lecithin market from a 2025 revenue base of USD 195.25 Million to USD 309.90 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.98% over the forecast horizon. The 2026 opening year for strategic action is quantified in the report and is forecasted at USD 215.53 Million — a pivotal inflection point for capacity, sourcing and innovation choices.
Soy Lecithin Market
Why this study matters for 2026 decision cycles
-
Data-driven clarity: With macro continuity established across 2020–2025 and forward-looking scenario runs to 2032, the report converts market momentum into actionable thresholds for capital allocation, procurement contracts and product investment.
Soy Lecithin Market -
Concentration matters: The market demonstrates a high degree of supplier concentration; our competitive concentration metrics (CR3 and CR5) highlight oligopolistic dynamics that amplify the strategic importance of supplier relationships, contingency sourcing and vertical integration options.
Soy Lecithin Market -
Regulatory and logistics shock sensitivity: The combination of new regulatory regimes and persistent freight/insurance volatility materially alters delivered costs and compliance risk profiles — factors that must be embedded into 2026 budgets and supplier scorecards.
Report composition — practical deliverables (what you’ll find inside)
-
Market sizing and trend analysis: Baseline market values, multi-year historical series, and forecast scenarios with sensitivity to raw material throughput, price inflation and regulatory drag.
-
Supply chain and trade flows: Mapping of upstream soybean processing capacity, co-product dynamics, seasonal availability and logistics vectors that influence origin-to-destination lead times.
-
Regulatory & sustainability playbook: Practical compliance matrices for EUDR-style requirements, Non-GMO and organic verification, GRAS considerations, and buyer-level documentation checklists.
-
Competitor landscaping and strategic profiles: Comparative assessments of global processors (integrated crushers), specialty lecithin producers and regional players — including strategic moves, capacity shifts and innovation focus areas.
-
Commercial benchmarking and price architecture: Delivered-cost models, premium segmentation logic (e.g., Non-GMO/organic vs commodity grades), and margin impact simulations to guide pricing and negotiation tactics.
-
Decision frameworks and tools: Investment scorecards, procurement RFP templates, M&A screening models, scenario-based stress tests, and an operational playbook for scaling production or entering premium niches.
Note: To preserve the report’s integrity as a subscription-grade intelligence product and to encourage direct engagement, this release intentionally omits granular line-item subsegment tables and region/application breakouts. These are included in full within the PW Consulting report package and accompanying interactive dashboards.
Key market dynamics shaping 2026 strategies
-
Upstream supply abundance vs. quality segmentation — The record-level US soybean crush projected for MY2025/26 materially supports lecithin availability as a co-product of oil degumming. However, abundance at the commodity level coexists with growing demand for verified-sourced, non-GMO and organic lecithin — forcing firms to choose between volume plays and premium differentiation.
-
Regulatory inflection — New sourcing regulations taking effect from late 2025 place documentation and traceability at the center of commercial negotiations. Exporters dependent on certain origins must now demonstrate deforestation-free sourcing, changing the risk calculus for buyers that lack robust supplier traceability.
-
Premiumization & certification economics — Verified Non-GMO status continues to command a material price premium in mature markets; our synthesis of market intelligence places the premium in a double-digit band, altering go-to-market choices for both ingredient suppliers and branded formulators.
-
Logistics and delivered cost pressure — Geopolitical tensions and disruptions to key maritime chokepoints have elevated freight, insurance and inventory carrying costs. Delivered market values now reflect these risk premia and should be modeled into contract length, incoterms and hedging strategies for 2026.
-
Regulatory continuity — FDA GRAS recognition remains the primary U.S. food regulatory enabler for soy lecithin use, although allergen declaration requirements persist and should be embedded into labeling and product development roadmaps.
Competitive landscape — strategic implications
The soy lecithin market’s supplier structure presents a two-speed dynamic: a cohort of global integrated processors with scale and integrated crushing operations, and a diversified group of specialty manufacturers delivering high-purity, certified and niche-grade lecithins. High-level observations include:
-
Integrated scale players (e.g., longstanding global crushers and refiners) continue to leverage scale advantages in feedstock access, operational integration and logistics. Recent industry activity illustrates this consolidation thesis: a major global processor completed a strategic merger and simultaneously expanded capacity through targeted asset acquisitions in 2025, consolidating processing throughput and downstream lecithin supply.
-
Tiered specialization — Several firms have doubled down on organic, non-GMO or pharma-grade capabilities, positioning themselves for higher-margin niches. These specialists are likely to capture disproportionate growth in health-focused and nutraceutical applications.
-
Regional players and co-product producers remain relevant for spot volumes and regional supply security. Their strategic importance rises in scenarios where trade barriers or documentation requirements limit cross-border flows.
-
M&A and capacity moves are active levers — The market’s structure and recent corporate actions signal continued consolidation and targeted acquisitions as rational responses to both demand growth and the need for secure, certified supply chains.
For procurement and corporate strategy teams, the actionable implication is clear: scale can secure base volumes and cost advantage, but differentiated certification and traceability capabilities are rapidly becoming determinants of commercial access to premium channels.
Five strategic moves to prioritize in 2026
-
Embed traceability into supplier selection: Require compliance-ready documentation (including deforestation-free evidence where applicable) and build supplier scorecards that weight traceability equal to price for contracted volumes.
-
Hedge delivered cost risk: Revisit incoterms, diversify ports of loading, and secure multi-origin sourcing lanes to mitigate freight and insurance volatility; include delivered-cost scenarios in capital and pricing models.
-
Segment product strategy: Adopt a dual-path go-to-market — defend commodity volumes through scale partnerships and captive supply, while investing in premium, certified lecithins for health, nutraceutical and pharma applications.
-
Operationally future-proof capacity: Use the report’s ROI models and sensitivity analyses to set go/no-go thresholds for capacity additions, contract manufacturing partnerships or tolling arrangements.
-
Activate M&A and JV screening: Where market access or certification capabilities are lacking, prioritize bolt-on acquisitions or joint ventures with specialty producers rather than greenfield investments that delay market entry.
How PW Consulting’s deliverables accelerate your 2026 playbook
-
Interactive dashboards — Scenario-enabled models allow teams to simulate price, volume and regulatory outcomes under alternative assumptions and to export procurement- and finance-ready stress tests.
-
Supplier dossiers and scorecards — Comparable profiles, capability maps, and risk matrices for major integrated processors and specialty producers to fast-track due diligence.
-
Commercial negotiation toolkits — RFP templates, contract clauses for traceability and quality, and pricing architectures that capture certification premiums without sacrificing base-volume competitiveness.
-
Executive briefings and workshops — Board-level one-pagers, investment scorecards and live scenario walkthroughs to align the executive team on prioritized actions for 2026.
PW Consulting’s study is designed as a decision-grade resource: it surfaces the high-impact levers, quantifies trade-offs, and supplies executable tools so that procurement, strategy and R&D leaders can convert market intelligence into measurable outcomes in 2026.
Next steps — where to get the full intelligence
This release highlights the report’s strategic value and provides the high-level signals necessary for immediate planning. For organizations that require the underlying subsegment breakouts, regional and application-level tables, supplier-level volumes and price benchmarks, as well as the downloadable financial and procurement models, the full report and interactive dashboards are available through PW Consulting’s report portal.
Engage PW Consulting for a tailored briefing or a bespoke workshop where we’ll walk your leadership team through scenario results, run customized sensitivity analyses against your sourcing plan, and co-develop an execution roadmap calibrated to your risk appetite and capability profile.
For detailed analysis of this topic, please visit the official page: Soy Lecithin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glassware Market Poised to Grow from USD 173.85 Million in 2025 to USD 270.6 Million by 2032 at a 6.5% CAGR (2026–2032)
By pmarketresearch, 2026-06-30
Glassware Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
PW Consulting’s latest Glassware Market report (base year 2025; forecast period 2026–2032) translates market trajectories, supplier dynamics and regulatory headwinds into a decision-ready playbook for executives planning capital allocation, commercial strategy and operational resilience in 2026. The global glassware market has demonstrably accelerated over the past half decade — rising from roughly USD 132 million in 2020 to an estimated USD 174 million in 2025 — and is projected to reach the high USD 200 millions by 2032, tracking at a compound annual growth rate of approximately 6.5% through the forecast horizon. This note highlights the report’s strategic value, summarizes the dynamics shaping 2026 choices, and signals the tactical frameworks included in the full study.
Glassware Market
Why this report matters to executives in 2026
-
Actionable macro-to-micro translation: The brief converts headline market expansion into concrete scenarios for capacity planning, product portfolio prioritization, and pricing strategy — showing how a 6.5% CAGR materially changes capacity utilization and return profiles across plausible five- and seven-year horizons.
Glassware Market -
Risk-focused capital allocation: With raw-material and energy volatility front-and-center, the report provides a prioritised capital spending matrix — helping leaders choose between combustion-to-electric retrofit, automation to reduce variable cost exposure, or geographically targeted brownfield expansion.
Glassware Market -
Regulatory and sustainability compliance as a profit lever: Rather than treating environmental compliance purely as cost, we show how targeted investments (e.g., electric furnaces, circular feedstock programs) reduce long-term cost-per-unit and create differentiated value propositions for sophisticated buyers.
-
Competitive playbook: For both incumbents and new entrants, the report synthesizes observable moves from global players into defensible offensive and defensive options — from premiumization and specialty glass to commoditized tableware strategies.
Key market dynamics shaping 2026 decisions
-
Raw-material dislocation and grade differentiation: Silica supply and price swings are the immediate tactical consideration. Early 2026 saw silica sand price spikes in certain trade corridors due to energy and freight impacts, while other basins experienced inventory-driven price relief in 2025. High-purity feedstocks commanding meaningful premiums remain essential for pharmaceutical and laboratory glass businesses; procuring qualified feedstock is therefore a strategic sourcing priority, not simply a procurement checkbox.
-
Energy transformation as a competitive frontier: Manufacturers adopting electric furnace technology or other low-carbon thermal solutions are not only reducing emissions but materially lowering operating cost per tonne in energy-intensive glass categories. The operational and capex implications of such transitions are quantified in the report’s ROI model.
-
Regulatory cost burden and its operational implications: The report models a significant environmental compliance cost burden across production facilities, quantifying how incremental compliance requirements affect operating margins and location economics. This is critical for decisions on where to expand production vs. where to optimize through automation or outsourcing.
-
Concentration and strategic positioning: The market exhibits meaningful concentration at the top — our analysis shows the three largest firms account for a majority share of market value, with the top five approaching three quarters of market revenue. For challengers, this implies that scale, specialty capability, or relentless cost discipline are prerequisites for sustained competitive traction.
What the full report delivers — practical, implementable tools
-
Prioritized strategic initiatives: Ten near-term imperatives mapped by impact and ease of execution — covering product innovation, channel reconfiguration, sustainability investments, and partner ecosystems.
-
Supply-chain risk matrix: Scenario-based supplier tiering (raw-material, energy, logistics) with contingency playbooks and suggested contractual constructs to mitigate freight and feedstock shocks.
-
Capex decision model: A modular ROI model for furnace upgrades, automation lines, and new-line investments that integrates energy price sensitivity, regulatory compliance costs, and projected market demand under three growth scenarios.
-
Commercial playbooks: Channel-specific pricing, segmentation frameworks and go-to-market tactics tailored for tableware, drinkware, laboratory and pharmaceutical glass — informed by buyer willingness to pay and switching costs.
-
M&A and partnership playbook: A target-screening grid that prioritizes bolt-on acquisitions, technology partnerships and joint ventures by strategic fit, integration risk and expected synergies.
-
Sustainability roadmap: Stepwise levers to lower carbon intensity, reduce waste and monetize circularity — including case-level returns for furnace electrification and recycled glass content strategies.
Competitive landscape and what recent moves mean for strategy
The report assesses leading incumbents across capability sets: specialty borosilicate and pharmaceutical-grade producers, laboratory glass specialists, and high-volume consumer and hospitality tableware manufacturers. A concentrated top-tier — where the three largest firms control a decisive portion of value and the five largest approach roughly 76% of revenue — means competitive interaction among these leaders dictates pricing bands, innovation trajectories and distribution partnerships.
-
SCHOTT AG (Mainz, Germany) — An entrenched specialty glass and borosilicate leader with strong pharmaceutical credentials. SCHOTT’s recent expansion of vial production capacity in the United States underscores the strategic need to anchor pharmaceutical glass supply chains closer to end markets. For competitors and buyers, SCHOTT’s move signals increased regional resilience in pharma glass supply and a higher bar for quality assurance and lead-time expectations.
-
Corning Incorporated (Corning, NY, USA) — Corning’s PYREX and technical-ceramics portfolio continues to straddle laboratory, life-science and specialty glass applications. Their dual focus on high-performance product lines and materials innovation makes them a bellwether for technology-driven premiumization in the lab and pharma segments.
-
DWK Life Sciences (Germany) and Gerresheimer AG (Düsseldorf, Germany) — Specialists in laboratory and pharmaceutical glass that compete on precision, regulatory compliance and channel relationships with OEMs and pharma customers. Their capabilities in Type I and precision containers highlight the non-commodity value in regulated segments.
-
Borosil Limited (Mumbai, India), Anchor Hocking and Libbey (USA), Bormioli Rocco (Italy) and Pasabahce/Şişecam (Turkey) — These players exemplify divergent strategies: industrial-scale tableware and drinkware for hospitality/consumer channels versus differentiated, heat-resistant or sustainable product offers. Recent research alliances and product launches signal an industry balancing cost efficiency with sustainability-led differentiation.
Signals from recent industry developments
-
Capacity and product launches: Product introductions and capacity expansions across multiple firms reflect an industry preparing for broad-based demand recovery and premium-segmentation growth in technical applications.
-
Energy- and carbon-focused innovation: Operational shifts like the commissioning of low-energy electric furnaces in Europe demonstrate pathway options that deliver both compliance relief and unit-cost benefit.
-
R&D and academic partnerships: Renewed research collaborations targeting sustainable glass formulations point to a near-term pipeline of commercially viable alternatives and process improvements that could reframe material cost structures within the forecast period.
Five strategic questions every C-suite should be able to answer in 2026
-
How will projected market growth alter our capacity needs and pricing discipline for the next three budget cycles?
-
Which segments should we treat as margin-creation engines (specialty, pharma, lab) vs. margin-weighted volume plays (tableware, beverage) without diluting our cost structure?
-
What is our plan to secure high-purity feedstock and to hedge against silica and freight volatility?
-
Which sustainability investments offer credible payback within our planning horizon, and how do they affect our competitive positioning against top-tier concentration players?
-
Do we have the M&A and partnership pipeline to access missing capabilities, and are our integration plans stress-tested for cultural and regulatory risk?
How PW Consulting’s report supports operationalizing these answers
Our Glassware Market report blends quantitative forecasts with executable frameworks: scenario-based capacity plans, supplier stratification and contracting templates, a prioritized capital investment calculator for energy and automation, and a playbook for customer segmentation and premiumization. The objective is to move firms from strategic intent to a prioritized two-year implementation plan that aligns finance, operations and commercial functions.
Closing — the strategic invitation
For executives making portfolio and capital decisions in 2026, the choice is simple: treat the glassware sector as a passive commodity market and risk margin erosion and supply fragility — or use the data-informed, risk-adjusted frameworks in PW Consulting’s report to convert current market expansion into durable competitive advantage. We present the full analysis, models and recommended action steps in the complete report; the executive summary here is intentionally selective to highlight strategic thrusts while preserving the granular scenario and segment intelligence behind our guidance.
To access the comprehensive dataset, granular scenario matrices and firm-level implications that underpin these recommendations, please consult the full PW Consulting Glassware Market report and the downloadable tools on the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Glassware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyurethane Sealants Market to Reach USD 4,097 Million by 2032, Growing at a 4.23% CAGR — Asia‑Pacific Leads with USD 1,156.41 Million
By pmarketresearch, 2026-06-30
Polyurethane Sealants Market Outlook 2026: Strategic Imperatives for Resilient Growth
PW Consulting today releases its authoritative market study on the global Polyurethane Sealants market — a practical, decision-grade resource for executives preparing strategies in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the research combines rigorous top-down sizing with scenario-tested planning tools. Our modeling shows the market reached approximately USD 3,052 Million in 2025 and, at a 4.23% compound annual growth rate, is projected to expand toward the low‑USD 4,000 Millions territory by the end of the forecast window. This trajectory masks important short-term volatility and structural change that strategic leaders must address now.
Polyurethane Sealants Market
Why this report matters to 2026 decision-makers
- Macro clarity with tactical guidance: We translate headline growth into actionable implications for procurement, product roadmaps, capital allocation, and commercial strategy — without overwhelming teams with raw tables that lack synthesis.
- Scenario readiness: The report includes stress-tested scenarios for feedstock shocks, regulatory tightening, and trade disruptions so leaders can quantify P&L and supply‑chain outcomes before making irreversible investments.
- Competitive intelligence that informs moves: Our competitive heatmaps, capability matrices, and regional network overlays show where incumbents are reinforcing strengths and where gaps create entry or consolidation opportunities.
Key market dynamics shaping 2026 outcomes
- Feedstock volatility and cost pass‑through: Isocyanate (MDI) and polyol feedstock pricing endured elevated volatility across 2025–2026, with documented sharp increases in early 2026. These movements materially compress margins for formulators without disciplined hedging or local raw‑material access.
- Trade and tariff friction: Recent tariff policies on certain imports have altered trade flows and created localized cost differentials. Manufacturers with globally distributed, flexible supply networks are better positioned to neutralize duty-driven price swings.
- Sustainability and regulatory pull: Low‑VOC formulations are rapidly transitioning from niche to baseline in multiple high-value applications (notably marine and green-certified construction). New maritime and indoor-air-quality standards are accelerating demand for compliant product lines.
- Demand heterogeneity and infrastructure timing: Construction and refurbishment cycles, combined with targeted infrastructure spending in several regions, create pockets of outsized demand — but timing and specification variability require nimble commercial execution.
What’s inside the PW Consulting study (practical content overview)
- Top-line market sizing (2020–2025 historical) and detailed forecasts (2026–2032) with high-, base-, and low-case scenarios accounting for raw-material and regulatory swings.
- End‑use insight packs that translate performance requirements (adhesion, movement capability, cure profile, VOC limits) into product design principles and commercialization checklists.
- Supplier and channel economics models that let procurement teams run “what‑if” analyses on hedging, near‑sourcing, and contractual price pass‑through.
- Manufacturing footprint optimization playbook — a templated approach for determining when to localize production versus leverage global capacity.
- Competitive benchmarking and M&A screen: capability maps, manufacturing and R&D footprints, and adjacency plays that support rapid target screening.
- Regulatory compliance toolkit and certification roadmaps for low‑VOC and maritime standards, including recommended testing partners and cost/timing estimates.
Note: This public summary demonstrates the depth of our analysis while intentionally withholding granular segment and regional splits. The full report contains the complete segmentation tables, regional demand curves, and application-specific revenue series used to construct our forecasts.
Polyurethane Sealants Market
Competitive landscape — who’s shaping the next wave
The polyurethane sealants market is moderately concentrated, with the top three global players capturing a meaningful portion of industry revenue and the top five firms accounting for an even larger share. This concentration drives scale advantages in formulation R&D, distribution, and regulatory compliance.
Polyurethane Sealants Market
- Sika AG (Baar, Switzerland) — Sika’s Sikaflex® franchise remains a reference platform across construction, automotive bonding, and marine applications. Their 2025 moves — introducing low‑VOC marine grades and investing in production capacity in Asia and Eastern Europe — illustrate a two‑pronged play: product premiumization for compliant applications and localized production to shorten supply chains and mitigate tariff exposure.
- H.B. Fuller Company (Vadnais Heights, US) — H.B. Fuller leverages application-engineering strengths in transportation and HVAC. Their emphasis on chemical resistance and flexible formulations positions them well where performance and regulatory compliance are prerequisites.
- Henkel AG & Co. KGaA (Düsseldorf, Germany) — Henkel’s LOCTITE® and adjacent portfolios serve structural aerospace and marine niches. Their global regulatory expertise and channel reach support premiumization strategies where specification-driven buyers dominate.
- 3M Company (St. Paul, US) — Known for fast‑cure and durable marine/industrial sealants, 3M competes on formulation innovation and brand trust in high‑performance segments.
- Dow Inc. (Midland, US) and Wacker Chemie AG (Munich, Germany) — As major raw‑material suppliers and system providers, these firms influence formulation cost structures and offer integrated solution sales that can lock in customers via systems‑level benefits.
- Bostik SA, Mapei S.p.A., Tremco Incorporated, RPM (Tremco brand), and other regional champions — These firms combine regional application expertise, focused product ranges, and channel incumbency to protect margins in localized markets. Recent product introductions and R&D investments by players such as Tremco and Soudal indicate continuing emphasis on climate-resilient and sustainability‑oriented formulations.
Recent strategic moves and market signals
- Sika expanded its marine-grade, low‑VOC range (early 2025) and opened new sites in Asia and Eastern Europe during 2025 to increase responsiveness and reduce landed cost exposure.
- Soudal inaugurated an R&D center in 2025 specifically focused on sustainability innovations, signifying R&D intensity as a differentiator.
- Tremco launched weather‑extreme polyurethane formulations in 2025, targeting infrastructure projects with elevated performance requirements.
- Industry pricing data in early 2026 recorded a pronounced increase in MDI feedstock costs, amplifying the urgency for procurement strategies that blend hedging, forward contracts, and localization.
- Trade measures and tightening environmental rules have created both a compliance cost and a market opportunity for first movers on low‑VOC product lines in regulated sectors.
Strategic playbook for 2026 — prioritized actions
- Short term (0–12 months)
- Execute a rapid procurement audit: quantify exposure to MDI and polyol price swings and establish layered hedging and forward-purchase programs for critical feedstocks.
- Fast-track low‑VOC product registrations and third‑party certifications for prioritized markets where regulatory timing is accelerating demand.
- Introduce tactical price-adjustment mechanisms in customer contracts to protect margins while preserving share in key accounts.
- Medium term (12–36 months)
- Pursue selective capacity localization in tariff‑sensitive regions to eliminate duty leakage and reduce lead times for specification-driven customers.
- Invest in formulation platforms that reduce MDI intensity or enable blended chemistries to manage feedstock dependency and sustainability claims.
- Conduct bolt‑on M&A or JV activity to secure niche capabilities (marine low‑VOC, extreme‑weather formulations, or application engineering) and accelerate route-to-market.
- Long term (36+ months)
- Transition R&D and product roadmaps toward systems solutions that combine sealants, primers, and adhesives for higher switching costs and lifetime value.
- Build predictive supply-chain capability (digital twin + commodity analytics) to convert scenario planning into automated sourcing decisions.
How PW Consulting supports implementation
Beyond the forecast and competitive map, our advisory engagement includes executable templates: procurement playbooks, capex sizing models for localization, a compliance roadmap for low‑VOC certification, and an M&A prioritization matrix calibrated to client balance‑sheet metrics. We also deliver a financial impact simulator that lets your finance team stress-test EBITDA under alternative raw‑material, pricing, and volume trajectories.
Next steps
For strategy teams preparing budgets, negotiating supply contracts, or evaluating acquisition targets in 2026, the choices you make now will determine whether you capture asymmetric upside or concede margin as input prices and regulatory demands intensify. PW Consulting’s full Polyurethane Sealants Market report contains the proprietary segmentation, regional demand curves, application-level forecasts, and the downloadable financial models underpinning these recommendations.
To access the full dataset and client-grade advisory appendices, visit our report page or contact PW Consulting’s Chemicals & Materials practice for a tailored briefing and model walkthrough. The path to a resilient, high‑margin position in the polyurethane sealants market begins with disciplined scenario planning — and now is the time to act.
For detailed analysis of this topic, please visit the official page: Polyurethane Sealants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Shimmering Surge: PW Consulting Forecasts Holographic Lamination Film Market to Grow at a 7.35% CAGR During 2026–2032
By pmarketresearch, 2026-06-30
Holographic Lamination Film Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
As brand owners chase shelf-stopping appeal and regulators tighten anti-counterfeiting controls, holographic lamination films have moved from novelty to a strategic material in packaging, security, and premium surface decoration. PW Consulting’s latest market study—anchored on a 2025 base year with a forward-looking forecast window of 2026–2032—distills the macro trajectory, competitive dynamics, and actionable pathways that will shape investment and product decisions throughout 2026 and beyond.
Holographic Lamination Film Market
Market snapshot: momentum, not hype
The market for holographic lamination films has expanded steadily in recent years, rising from approximately USD 163 million in 2020 to roughly USD 215 million in 2025. Our forecasting model—calibrated with primary supply-chain interviews, proprietary pricing scenarios, and demand-driver elasticity analysis—projects a continued compound annual growth rate (CAGR) of about 7.35% over the 2026–2032 horizon, taking the global market toward the mid-hundreds of millions of dollars by 2032. This is not a short-lived premiumization bubble: the growth reflects structural shifts in packaging differentiation, security requirements, and the migration of holographic effects into mainstream laminates and films.
Holographic Lamination Film Market
Why this matters to decision-makers in 2026
- Procurement and supplier strategy: The rise in demand and ongoing technological differentiation (from metallized and transparent films to embossed Fresnel and lens-based effects) requires procurement teams to evolve beyond price-only sourcing. The report equips leaders to evaluate suppliers on technical capabilities (electroforming, cold transfer, in-line embossing), IP position, and integration potential—factors that are increasingly determinative of total cost of ownership and time-to-market.
- Product and packaging innovation: For brand teams, holographic lamination films are a high-impact lever for premiumization and anti-counterfeiting. Our analysis shows that embedding holographic elements into multi-layer structures—rather than surface-applied labels—accelerates differentiation and raises the barrier to replication. The study outlines practical design and manufacturing considerations for embedding holographics into tubes, cartons, and pouches while preserving recyclability targets.
- CapEx and converters’ playbook: Converters and film manufacturers face a near-term decision matrix: invest in narrow- vs. wide-web capabilities, adopt in-house electroforming, or pursue partnerships for tooling. The report provides scenario-based CapEx models to help plant managers balance utilization uplift against technology risk and product lifecycle timelines.
- Regulatory and security readiness: As regulators and brand protection teams intensify anti-counterfeiting measures, holographic films increasingly function as a forensic and visible control. We map the intersection of standards, testing protocols, and authentication workflows to help compliance teams prioritize investments in tamper-evident and covert features.
What the report contains: practical, decision-grade deliverables
- Comprehensive market sizing and a 2026–2032 quantitative forecast model, including revenue trajectories, scenario variants, and sensitivity to raw-material and energy inputs.
- Demand-driver analysis across brand premiumization, anti-counterfeiting spending, regulatory changes, and packaging format shifts—each linked to realistic adoption curves.
- Supplier and technology benchmarking, highlighting manufacturing footprints, core competencies (e.g., embossing, metallization, transparent film production, Fresnel/lens effects), and commercialization pathways.
- Practical go-to-market playbooks for brand owners, converters, and manufacturers: product launch checklists, design-for-manufacturing guidelines, and validation protocols for integrating holographic films into laminate structures.
- Risk matrices covering raw-material volatility, recycling and circularity constraints, and IP/standardization exposure, paired with mitigation roadmaps.
- Investment and M&A screening tools to prioritize targets and deal structures that accelerate capability acquisition while minimizing integration risk.
- Case studies and recent development dossiers that translate strategy into action—documented deployments, supplier commercialization roadmaps, and lessons from early integrators.
Competitive landscape: regional specialists meet global technology houses
The competitive map is characterized by an eclectic mix of specialized regional producers and advanced diffractive technology houses. Market participants range from converters with deep in-house electroforming and embossing capabilities to manufacturers focused on high-end finishing foils and transfer technologies.
Holographic Lamination Film Market
- UFlex Limited (Noida, India) : A vertically integrated player that has recently commercialized anti-counterfeiting holographic films embedded as part of multi-layer laminate tubes for pharmaceutical and cosmetic applications. This move—shifting holographic features from surface embellishments to integral structural elements—illustrates a broader industry trend toward engineering holographic functionality into the substrate to improve durability and raise replication costs for counterfeiters.
- Kiran Holographics (Jaipur, India) : A PET-film specialist notable for its embossed and transparent offerings across packaging and security labels. The company’s recent product-catalog refresh signals ongoing investments in higher-clarity and decorative transparencies tailored to premium labels and flexible packaging converters.
- Longyou Synponh Packaging Materials (Longyou, China) : Focused on metallized PET transfer films and lamination solutions, with expertise in specialized packaging segments. Their profile typifies players who leverage sectoral depth—such as tobacco or luxury product packaging—to sustain margins through tailored solutions.
- LEONHARD KURZ GmbH & Co. KG (Fürth, Germany) : A technology-driven supplier delivering advanced diffractive finishing foils and 3D effects for cold transfer and hot stamping applications. Kurz’s strength is in high-value aesthetic effects and patented diffractive structures, positioning them as a preferred partner for label converters and luxury packaging manufacturers.
Together, these profiles indicate a market where competitive advantage stems from a combination of in-house tooling and diffractive expertise, the ability to deliver anti-counterfeiting uniqueness, and the operational scale to serve global brands.
Recent market movements that matter for 2026 strategies
- Commercialization of embedded holographic films for laminates (May 2026): UFlex’s May 2026 commercialization marks a significant inflection—embedding holographic film directly into laminates expands application durability and complicates counterfeiting vectors. For packaging engineers and brand security teams, this raises important specifications considerations for lamination chemistry, barrier performance, and downstream recyclability.
- Catalog and product refreshes among PET specialists (May 2026): Kiran Holographics’ updated portfolio underlines continued product innovation in transparent and embossed PET films—relevant to converters targeting high-clarity labels and flexible pouches.
Opportunities and headwinds: a pragmatic assessment
Opportunities:
- Premiumization across FMCG, cosmetics, and spirits drives willingness to pay for premium visual effects and provenance cues.
- Escalating anti-counterfeiting budgets among pharmaceuticals and electronics create recurring demand for both overt and covert holographic features.
- Design-led innovation—such as integrating Fresnel effects or multilayer embedding—opens high-margin niches for early adopters.
Headwinds:
- Recycling and circularity pressures force trade-offs: metallized and multi-material laminates complicate mono-stream recycling targets and may attract regulatory scrutiny.
- Raw material and energy price volatility amplify operating cost risks across film manufacturers and converters.
- IP and tooling costs (e.g., electroforming, embossing dies) create scale advantages that can limit new entrants without strategic partnerships or licensing models.
Actionable recommendations for 2026
- Brands: Treat holographic film as a cross-functional asset—security, marketing, and sustainability teams must align on feature specification to avoid costly retrofits. Prioritize pilot programs that measure uplift in authentication success and purchase intent, not just visual appeal.
- Converters and manufacturers: Run a three-year capability roadmap assessing narrow-web vs. wide-web investments, electroforming adoption, and potential co-investment with anchor brands to secure volume commitments and de-risk tooling spend.
- Investors and M&A teams: Screen targets for unique diffractive IP, an established electroforming footprint, and secured commercial partnerships within high-growth verticals (e.g., pharmaceuticals, cosmetics). Use our provided valuation scenarios that incorporate technology obsolescence and capex amortization profiles.
- Policy and sustainability leads: Engage early with recyclers and industry consortia to pilot designs that balance holographic functionality with end-of-life considerations. The report’s circularity playbook offers pilot specifications and test protocols to accelerate compliant product launches.
Why PW Consulting’s report is a must-have for 2026 planning
This study goes beyond high-level narrative by providing the operational tools executives need to convert strategic intent into measurable outcomes. It combines a rigorously built quantitative model (with historical 2020–2025 baselines and a 2026–2032 forecast), supplier and technology deep-dives, and practical playbooks that help stakeholders prioritize investments, structure pilots, and evaluate M&A targets.
To preserve the strategic advantage of our subscribers—and in keeping with the “trailer” principle—this release intentionally omits detailed regional and application-level splits, segmented growth curves, and granular competitive shares. Those detailed segmentations, the full financial model, and company-level scorecards are included in the report’s downloadable analyst workbook and interactive dashboards.
Next steps
If your 2026 planning cycle involves packaging differentiation, anti-counterfeiting, converter capacity planning, or M&A in the specialty film space, PW Consulting’s Holographic Lamination Film Market report is designed to be both a roadmap and an execution toolkit. Access the full intelligence pack to obtain segment-level forecasts, supplier scorecards, and Excel-ready models that translate market signals into executable plans.
For detailed analysis of this topic, please visit the official page: Holographic Lamination Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com