

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Soy Lecithin Market to Climb from USD 195.25 Million in 2025 to USD 309.9 Million by 2032 at a 6.98% CAGR, While Top 3 Players Hold 65.5% Share

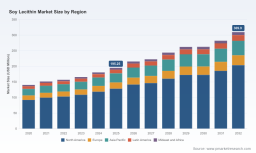
Soy Lecithin Market 2026 Outlook — Strategic Imperatives for Boards, Procurement and R&D Leaders
PW Consulting’s latest market study on Soy Lecithin delivers an executive-grade synthesis of the industry’s trajectory through 2032, framed expressly to inform high-stakes decisions for the 2026 planning cycle. Anchored on a 2025 base year and a historical review covering 2020–2025, the study projects the global soy lecithin market from a 2025 revenue base of USD 195.25 Million to USD 309.90 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.98% over the forecast horizon. The 2026 opening year for strategic action is quantified in the report and is forecasted at USD 215.53 Million — a pivotal inflection point for capacity, sourcing and innovation choices.
Soy Lecithin Market
Why this study matters for 2026 decision cycles
-
Data-driven clarity: With macro continuity established across 2020–2025 and forward-looking scenario runs to 2032, the report converts market momentum into actionable thresholds for capital allocation, procurement contracts and product investment.
Soy Lecithin Market -
Concentration matters: The market demonstrates a high degree of supplier concentration; our competitive concentration metrics (CR3 and CR5) highlight oligopolistic dynamics that amplify the strategic importance of supplier relationships, contingency sourcing and vertical integration options.
Soy Lecithin Market -
Regulatory and logistics shock sensitivity: The combination of new regulatory regimes and persistent freight/insurance volatility materially alters delivered costs and compliance risk profiles — factors that must be embedded into 2026 budgets and supplier scorecards.
Report composition — practical deliverables (what you’ll find inside)
-
Market sizing and trend analysis: Baseline market values, multi-year historical series, and forecast scenarios with sensitivity to raw material throughput, price inflation and regulatory drag.
-
Supply chain and trade flows: Mapping of upstream soybean processing capacity, co-product dynamics, seasonal availability and logistics vectors that influence origin-to-destination lead times.
-
Regulatory & sustainability playbook: Practical compliance matrices for EUDR-style requirements, Non-GMO and organic verification, GRAS considerations, and buyer-level documentation checklists.
-
Competitor landscaping and strategic profiles: Comparative assessments of global processors (integrated crushers), specialty lecithin producers and regional players — including strategic moves, capacity shifts and innovation focus areas.
-
Commercial benchmarking and price architecture: Delivered-cost models, premium segmentation logic (e.g., Non-GMO/organic vs commodity grades), and margin impact simulations to guide pricing and negotiation tactics.
-
Decision frameworks and tools: Investment scorecards, procurement RFP templates, M&A screening models, scenario-based stress tests, and an operational playbook for scaling production or entering premium niches.
Note: To preserve the report’s integrity as a subscription-grade intelligence product and to encourage direct engagement, this release intentionally omits granular line-item subsegment tables and region/application breakouts. These are included in full within the PW Consulting report package and accompanying interactive dashboards.
Key market dynamics shaping 2026 strategies
-
Upstream supply abundance vs. quality segmentation — The record-level US soybean crush projected for MY2025/26 materially supports lecithin availability as a co-product of oil degumming. However, abundance at the commodity level coexists with growing demand for verified-sourced, non-GMO and organic lecithin — forcing firms to choose between volume plays and premium differentiation.
-
Regulatory inflection — New sourcing regulations taking effect from late 2025 place documentation and traceability at the center of commercial negotiations. Exporters dependent on certain origins must now demonstrate deforestation-free sourcing, changing the risk calculus for buyers that lack robust supplier traceability.
-
Premiumization & certification economics — Verified Non-GMO status continues to command a material price premium in mature markets; our synthesis of market intelligence places the premium in a double-digit band, altering go-to-market choices for both ingredient suppliers and branded formulators.
-
Logistics and delivered cost pressure — Geopolitical tensions and disruptions to key maritime chokepoints have elevated freight, insurance and inventory carrying costs. Delivered market values now reflect these risk premia and should be modeled into contract length, incoterms and hedging strategies for 2026.
-
Regulatory continuity — FDA GRAS recognition remains the primary U.S. food regulatory enabler for soy lecithin use, although allergen declaration requirements persist and should be embedded into labeling and product development roadmaps.
Competitive landscape — strategic implications
The soy lecithin market’s supplier structure presents a two-speed dynamic: a cohort of global integrated processors with scale and integrated crushing operations, and a diversified group of specialty manufacturers delivering high-purity, certified and niche-grade lecithins. High-level observations include:
-
Integrated scale players (e.g., longstanding global crushers and refiners) continue to leverage scale advantages in feedstock access, operational integration and logistics. Recent industry activity illustrates this consolidation thesis: a major global processor completed a strategic merger and simultaneously expanded capacity through targeted asset acquisitions in 2025, consolidating processing throughput and downstream lecithin supply.
-
Tiered specialization — Several firms have doubled down on organic, non-GMO or pharma-grade capabilities, positioning themselves for higher-margin niches. These specialists are likely to capture disproportionate growth in health-focused and nutraceutical applications.
-
Regional players and co-product producers remain relevant for spot volumes and regional supply security. Their strategic importance rises in scenarios where trade barriers or documentation requirements limit cross-border flows.
-
M&A and capacity moves are active levers — The market’s structure and recent corporate actions signal continued consolidation and targeted acquisitions as rational responses to both demand growth and the need for secure, certified supply chains.
For procurement and corporate strategy teams, the actionable implication is clear: scale can secure base volumes and cost advantage, but differentiated certification and traceability capabilities are rapidly becoming determinants of commercial access to premium channels.
Five strategic moves to prioritize in 2026
-
Embed traceability into supplier selection: Require compliance-ready documentation (including deforestation-free evidence where applicable) and build supplier scorecards that weight traceability equal to price for contracted volumes.
-
Hedge delivered cost risk: Revisit incoterms, diversify ports of loading, and secure multi-origin sourcing lanes to mitigate freight and insurance volatility; include delivered-cost scenarios in capital and pricing models.
-
Segment product strategy: Adopt a dual-path go-to-market — defend commodity volumes through scale partnerships and captive supply, while investing in premium, certified lecithins for health, nutraceutical and pharma applications.
-
Operationally future-proof capacity: Use the report’s ROI models and sensitivity analyses to set go/no-go thresholds for capacity additions, contract manufacturing partnerships or tolling arrangements.
-
Activate M&A and JV screening: Where market access or certification capabilities are lacking, prioritize bolt-on acquisitions or joint ventures with specialty producers rather than greenfield investments that delay market entry.
How PW Consulting’s deliverables accelerate your 2026 playbook
-
Interactive dashboards — Scenario-enabled models allow teams to simulate price, volume and regulatory outcomes under alternative assumptions and to export procurement- and finance-ready stress tests.
-
Supplier dossiers and scorecards — Comparable profiles, capability maps, and risk matrices for major integrated processors and specialty producers to fast-track due diligence.
-
Commercial negotiation toolkits — RFP templates, contract clauses for traceability and quality, and pricing architectures that capture certification premiums without sacrificing base-volume competitiveness.
-
Executive briefings and workshops — Board-level one-pagers, investment scorecards and live scenario walkthroughs to align the executive team on prioritized actions for 2026.
PW Consulting’s study is designed as a decision-grade resource: it surfaces the high-impact levers, quantifies trade-offs, and supplies executable tools so that procurement, strategy and R&D leaders can convert market intelligence into measurable outcomes in 2026.
Next steps — where to get the full intelligence
This release highlights the report’s strategic value and provides the high-level signals necessary for immediate planning. For organizations that require the underlying subsegment breakouts, regional and application-level tables, supplier-level volumes and price benchmarks, as well as the downloadable financial and procurement models, the full report and interactive dashboards are available through PW Consulting’s report portal.
Engage PW Consulting for a tailored briefing or a bespoke workshop where we’ll walk your leadership team through scenario results, run customized sensitivity analyses against your sourcing plan, and co-develop an execution roadmap calibrated to your risk appetite and capability profile.
For detailed analysis of this topic, please visit the official page: Soy Lecithin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com