

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Glassware Market Poised to Grow from USD 173.85 Million in 2025 to USD 270.6 Million by 2032 at a 6.5% CAGR (2026–2032)

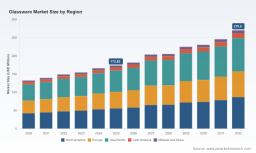
Glassware Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
PW Consulting’s latest Glassware Market report (base year 2025; forecast period 2026–2032) translates market trajectories, supplier dynamics and regulatory headwinds into a decision-ready playbook for executives planning capital allocation, commercial strategy and operational resilience in 2026. The global glassware market has demonstrably accelerated over the past half decade — rising from roughly USD 132 million in 2020 to an estimated USD 174 million in 2025 — and is projected to reach the high USD 200 millions by 2032, tracking at a compound annual growth rate of approximately 6.5% through the forecast horizon. This note highlights the report’s strategic value, summarizes the dynamics shaping 2026 choices, and signals the tactical frameworks included in the full study.
Glassware Market
Why this report matters to executives in 2026
-
Actionable macro-to-micro translation: The brief converts headline market expansion into concrete scenarios for capacity planning, product portfolio prioritization, and pricing strategy — showing how a 6.5% CAGR materially changes capacity utilization and return profiles across plausible five- and seven-year horizons.
Glassware Market -
Risk-focused capital allocation: With raw-material and energy volatility front-and-center, the report provides a prioritised capital spending matrix — helping leaders choose between combustion-to-electric retrofit, automation to reduce variable cost exposure, or geographically targeted brownfield expansion.
Glassware Market -
Regulatory and sustainability compliance as a profit lever: Rather than treating environmental compliance purely as cost, we show how targeted investments (e.g., electric furnaces, circular feedstock programs) reduce long-term cost-per-unit and create differentiated value propositions for sophisticated buyers.
-
Competitive playbook: For both incumbents and new entrants, the report synthesizes observable moves from global players into defensible offensive and defensive options — from premiumization and specialty glass to commoditized tableware strategies.
Key market dynamics shaping 2026 decisions
-
Raw-material dislocation and grade differentiation: Silica supply and price swings are the immediate tactical consideration. Early 2026 saw silica sand price spikes in certain trade corridors due to energy and freight impacts, while other basins experienced inventory-driven price relief in 2025. High-purity feedstocks commanding meaningful premiums remain essential for pharmaceutical and laboratory glass businesses; procuring qualified feedstock is therefore a strategic sourcing priority, not simply a procurement checkbox.
-
Energy transformation as a competitive frontier: Manufacturers adopting electric furnace technology or other low-carbon thermal solutions are not only reducing emissions but materially lowering operating cost per tonne in energy-intensive glass categories. The operational and capex implications of such transitions are quantified in the report’s ROI model.
-
Regulatory cost burden and its operational implications: The report models a significant environmental compliance cost burden across production facilities, quantifying how incremental compliance requirements affect operating margins and location economics. This is critical for decisions on where to expand production vs. where to optimize through automation or outsourcing.
-
Concentration and strategic positioning: The market exhibits meaningful concentration at the top — our analysis shows the three largest firms account for a majority share of market value, with the top five approaching three quarters of market revenue. For challengers, this implies that scale, specialty capability, or relentless cost discipline are prerequisites for sustained competitive traction.
What the full report delivers — practical, implementable tools
-
Prioritized strategic initiatives: Ten near-term imperatives mapped by impact and ease of execution — covering product innovation, channel reconfiguration, sustainability investments, and partner ecosystems.
-
Supply-chain risk matrix: Scenario-based supplier tiering (raw-material, energy, logistics) with contingency playbooks and suggested contractual constructs to mitigate freight and feedstock shocks.
-
Capex decision model: A modular ROI model for furnace upgrades, automation lines, and new-line investments that integrates energy price sensitivity, regulatory compliance costs, and projected market demand under three growth scenarios.
-
Commercial playbooks: Channel-specific pricing, segmentation frameworks and go-to-market tactics tailored for tableware, drinkware, laboratory and pharmaceutical glass — informed by buyer willingness to pay and switching costs.
-
M&A and partnership playbook: A target-screening grid that prioritizes bolt-on acquisitions, technology partnerships and joint ventures by strategic fit, integration risk and expected synergies.
-
Sustainability roadmap: Stepwise levers to lower carbon intensity, reduce waste and monetize circularity — including case-level returns for furnace electrification and recycled glass content strategies.
Competitive landscape and what recent moves mean for strategy
The report assesses leading incumbents across capability sets: specialty borosilicate and pharmaceutical-grade producers, laboratory glass specialists, and high-volume consumer and hospitality tableware manufacturers. A concentrated top-tier — where the three largest firms control a decisive portion of value and the five largest approach roughly 76% of revenue — means competitive interaction among these leaders dictates pricing bands, innovation trajectories and distribution partnerships.
-
SCHOTT AG (Mainz, Germany) — An entrenched specialty glass and borosilicate leader with strong pharmaceutical credentials. SCHOTT’s recent expansion of vial production capacity in the United States underscores the strategic need to anchor pharmaceutical glass supply chains closer to end markets. For competitors and buyers, SCHOTT’s move signals increased regional resilience in pharma glass supply and a higher bar for quality assurance and lead-time expectations.
-
Corning Incorporated (Corning, NY, USA) — Corning’s PYREX and technical-ceramics portfolio continues to straddle laboratory, life-science and specialty glass applications. Their dual focus on high-performance product lines and materials innovation makes them a bellwether for technology-driven premiumization in the lab and pharma segments.
-
DWK Life Sciences (Germany) and Gerresheimer AG (Düsseldorf, Germany) — Specialists in laboratory and pharmaceutical glass that compete on precision, regulatory compliance and channel relationships with OEMs and pharma customers. Their capabilities in Type I and precision containers highlight the non-commodity value in regulated segments.
-
Borosil Limited (Mumbai, India), Anchor Hocking and Libbey (USA), Bormioli Rocco (Italy) and Pasabahce/Şişecam (Turkey) — These players exemplify divergent strategies: industrial-scale tableware and drinkware for hospitality/consumer channels versus differentiated, heat-resistant or sustainable product offers. Recent research alliances and product launches signal an industry balancing cost efficiency with sustainability-led differentiation.
Signals from recent industry developments
-
Capacity and product launches: Product introductions and capacity expansions across multiple firms reflect an industry preparing for broad-based demand recovery and premium-segmentation growth in technical applications.
-
Energy- and carbon-focused innovation: Operational shifts like the commissioning of low-energy electric furnaces in Europe demonstrate pathway options that deliver both compliance relief and unit-cost benefit.
-
R&D and academic partnerships: Renewed research collaborations targeting sustainable glass formulations point to a near-term pipeline of commercially viable alternatives and process improvements that could reframe material cost structures within the forecast period.
Five strategic questions every C-suite should be able to answer in 2026
-
How will projected market growth alter our capacity needs and pricing discipline for the next three budget cycles?
-
Which segments should we treat as margin-creation engines (specialty, pharma, lab) vs. margin-weighted volume plays (tableware, beverage) without diluting our cost structure?
-
What is our plan to secure high-purity feedstock and to hedge against silica and freight volatility?
-
Which sustainability investments offer credible payback within our planning horizon, and how do they affect our competitive positioning against top-tier concentration players?
-
Do we have the M&A and partnership pipeline to access missing capabilities, and are our integration plans stress-tested for cultural and regulatory risk?
How PW Consulting’s report supports operationalizing these answers
Our Glassware Market report blends quantitative forecasts with executable frameworks: scenario-based capacity plans, supplier stratification and contracting templates, a prioritized capital investment calculator for energy and automation, and a playbook for customer segmentation and premiumization. The objective is to move firms from strategic intent to a prioritized two-year implementation plan that aligns finance, operations and commercial functions.
Closing — the strategic invitation
For executives making portfolio and capital decisions in 2026, the choice is simple: treat the glassware sector as a passive commodity market and risk margin erosion and supply fragility — or use the data-informed, risk-adjusted frameworks in PW Consulting’s report to convert current market expansion into durable competitive advantage. We present the full analysis, models and recommended action steps in the complete report; the executive summary here is intentionally selective to highlight strategic thrusts while preserving the granular scenario and segment intelligence behind our guidance.
To access the comprehensive dataset, granular scenario matrices and firm-level implications that underpin these recommendations, please consult the full PW Consulting Glassware Market report and the downloadable tools on the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Glassware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com