

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
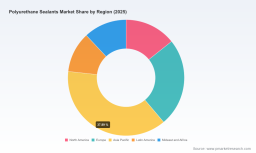
PW Consulting: Polyurethane Sealants Market to Reach USD 4,097 Million by 2032, Growing at a 4.23% CAGR — Asia‑Pacific Leads with USD 1,156.41 Million

Polyurethane Sealants Market Outlook 2026: Strategic Imperatives for Resilient Growth
PW Consulting today releases its authoritative market study on the global Polyurethane Sealants market — a practical, decision-grade resource for executives preparing strategies in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the research combines rigorous top-down sizing with scenario-tested planning tools. Our modeling shows the market reached approximately USD 3,052 Million in 2025 and, at a 4.23% compound annual growth rate, is projected to expand toward the low‑USD 4,000 Millions territory by the end of the forecast window. This trajectory masks important short-term volatility and structural change that strategic leaders must address now.
Polyurethane Sealants Market
Why this report matters to 2026 decision-makers
- Macro clarity with tactical guidance: We translate headline growth into actionable implications for procurement, product roadmaps, capital allocation, and commercial strategy — without overwhelming teams with raw tables that lack synthesis.
- Scenario readiness: The report includes stress-tested scenarios for feedstock shocks, regulatory tightening, and trade disruptions so leaders can quantify P&L and supply‑chain outcomes before making irreversible investments.
- Competitive intelligence that informs moves: Our competitive heatmaps, capability matrices, and regional network overlays show where incumbents are reinforcing strengths and where gaps create entry or consolidation opportunities.
Key market dynamics shaping 2026 outcomes
- Feedstock volatility and cost pass‑through: Isocyanate (MDI) and polyol feedstock pricing endured elevated volatility across 2025–2026, with documented sharp increases in early 2026. These movements materially compress margins for formulators without disciplined hedging or local raw‑material access.
- Trade and tariff friction: Recent tariff policies on certain imports have altered trade flows and created localized cost differentials. Manufacturers with globally distributed, flexible supply networks are better positioned to neutralize duty-driven price swings.
- Sustainability and regulatory pull: Low‑VOC formulations are rapidly transitioning from niche to baseline in multiple high-value applications (notably marine and green-certified construction). New maritime and indoor-air-quality standards are accelerating demand for compliant product lines.
- Demand heterogeneity and infrastructure timing: Construction and refurbishment cycles, combined with targeted infrastructure spending in several regions, create pockets of outsized demand — but timing and specification variability require nimble commercial execution.
What’s inside the PW Consulting study (practical content overview)
- Top-line market sizing (2020–2025 historical) and detailed forecasts (2026–2032) with high-, base-, and low-case scenarios accounting for raw-material and regulatory swings.
- End‑use insight packs that translate performance requirements (adhesion, movement capability, cure profile, VOC limits) into product design principles and commercialization checklists.
- Supplier and channel economics models that let procurement teams run “what‑if” analyses on hedging, near‑sourcing, and contractual price pass‑through.
- Manufacturing footprint optimization playbook — a templated approach for determining when to localize production versus leverage global capacity.
- Competitive benchmarking and M&A screen: capability maps, manufacturing and R&D footprints, and adjacency plays that support rapid target screening.
- Regulatory compliance toolkit and certification roadmaps for low‑VOC and maritime standards, including recommended testing partners and cost/timing estimates.
Note: This public summary demonstrates the depth of our analysis while intentionally withholding granular segment and regional splits. The full report contains the complete segmentation tables, regional demand curves, and application-specific revenue series used to construct our forecasts.
Polyurethane Sealants Market
Competitive landscape — who’s shaping the next wave
The polyurethane sealants market is moderately concentrated, with the top three global players capturing a meaningful portion of industry revenue and the top five firms accounting for an even larger share. This concentration drives scale advantages in formulation R&D, distribution, and regulatory compliance.
Polyurethane Sealants Market
- Sika AG (Baar, Switzerland) — Sika’s Sikaflex® franchise remains a reference platform across construction, automotive bonding, and marine applications. Their 2025 moves — introducing low‑VOC marine grades and investing in production capacity in Asia and Eastern Europe — illustrate a two‑pronged play: product premiumization for compliant applications and localized production to shorten supply chains and mitigate tariff exposure.
- H.B. Fuller Company (Vadnais Heights, US) — H.B. Fuller leverages application-engineering strengths in transportation and HVAC. Their emphasis on chemical resistance and flexible formulations positions them well where performance and regulatory compliance are prerequisites.
- Henkel AG & Co. KGaA (Düsseldorf, Germany) — Henkel’s LOCTITE® and adjacent portfolios serve structural aerospace and marine niches. Their global regulatory expertise and channel reach support premiumization strategies where specification-driven buyers dominate.
- 3M Company (St. Paul, US) — Known for fast‑cure and durable marine/industrial sealants, 3M competes on formulation innovation and brand trust in high‑performance segments.
- Dow Inc. (Midland, US) and Wacker Chemie AG (Munich, Germany) — As major raw‑material suppliers and system providers, these firms influence formulation cost structures and offer integrated solution sales that can lock in customers via systems‑level benefits.
- Bostik SA, Mapei S.p.A., Tremco Incorporated, RPM (Tremco brand), and other regional champions — These firms combine regional application expertise, focused product ranges, and channel incumbency to protect margins in localized markets. Recent product introductions and R&D investments by players such as Tremco and Soudal indicate continuing emphasis on climate-resilient and sustainability‑oriented formulations.
Recent strategic moves and market signals
- Sika expanded its marine-grade, low‑VOC range (early 2025) and opened new sites in Asia and Eastern Europe during 2025 to increase responsiveness and reduce landed cost exposure.
- Soudal inaugurated an R&D center in 2025 specifically focused on sustainability innovations, signifying R&D intensity as a differentiator.
- Tremco launched weather‑extreme polyurethane formulations in 2025, targeting infrastructure projects with elevated performance requirements.
- Industry pricing data in early 2026 recorded a pronounced increase in MDI feedstock costs, amplifying the urgency for procurement strategies that blend hedging, forward contracts, and localization.
- Trade measures and tightening environmental rules have created both a compliance cost and a market opportunity for first movers on low‑VOC product lines in regulated sectors.
Strategic playbook for 2026 — prioritized actions
- Short term (0–12 months)
- Execute a rapid procurement audit: quantify exposure to MDI and polyol price swings and establish layered hedging and forward-purchase programs for critical feedstocks.
- Fast-track low‑VOC product registrations and third‑party certifications for prioritized markets where regulatory timing is accelerating demand.
- Introduce tactical price-adjustment mechanisms in customer contracts to protect margins while preserving share in key accounts.
- Medium term (12–36 months)
- Pursue selective capacity localization in tariff‑sensitive regions to eliminate duty leakage and reduce lead times for specification-driven customers.
- Invest in formulation platforms that reduce MDI intensity or enable blended chemistries to manage feedstock dependency and sustainability claims.
- Conduct bolt‑on M&A or JV activity to secure niche capabilities (marine low‑VOC, extreme‑weather formulations, or application engineering) and accelerate route-to-market.
- Long term (36+ months)
- Transition R&D and product roadmaps toward systems solutions that combine sealants, primers, and adhesives for higher switching costs and lifetime value.
- Build predictive supply-chain capability (digital twin + commodity analytics) to convert scenario planning into automated sourcing decisions.
How PW Consulting supports implementation
Beyond the forecast and competitive map, our advisory engagement includes executable templates: procurement playbooks, capex sizing models for localization, a compliance roadmap for low‑VOC certification, and an M&A prioritization matrix calibrated to client balance‑sheet metrics. We also deliver a financial impact simulator that lets your finance team stress-test EBITDA under alternative raw‑material, pricing, and volume trajectories.
Next steps
For strategy teams preparing budgets, negotiating supply contracts, or evaluating acquisition targets in 2026, the choices you make now will determine whether you capture asymmetric upside or concede margin as input prices and regulatory demands intensify. PW Consulting’s full Polyurethane Sealants Market report contains the proprietary segmentation, regional demand curves, application-level forecasts, and the downloadable financial models underpinning these recommendations.
To access the full dataset and client-grade advisory appendices, visit our report page or contact PW Consulting’s Chemicals & Materials practice for a tailored briefing and model walkthrough. The path to a resilient, high‑margin position in the polyurethane sealants market begins with disciplined scenario planning — and now is the time to act.
For detailed analysis of this topic, please visit the official page: Polyurethane Sealants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com