

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Water Recycling & Reuse Market to Grow at a Robust 11.25% CAGR Through 2032
By pmarketresearch, 2026-07-01
Water Recycling And Reuse Market — Strategic Briefing for 2026: How Corporates Should Act Now
Overview
PW Consulting's new Water Recycling And Reuse Market report synthesizes five years of historical performance with seven-year forward projections to create an actionable guide for executives making capital allocation, technology, and partnership decisions in 2026. The market has accelerated from an estimated USD 13,171.21 Million in 2020 to USD 22,450.00 Million in 2025, and our baseline forecast projects growth to approximately USD 47,349.62 Million by 2032 — a compound annual growth rate (CAGR) of 11.25% over the 2026–2032 forecast window. Market concentration remains moderately fragmented: the top three players account for roughly 22% of market value, while the top five account for about 35% — a structure that favors strategic alliances, roll-up M&A, and regional scale plays.
Water Recycling And Reuse Market
Why this report matters for 2026 decision cycles
- Capital planning: The strong mid-double-digit growth trajectory pressures procurement, construction, and O&M budgets; the report provides scenario-based capex/opex models to stress-test multi-year investment plans against regulatory and energy-price shocks.
- Technology selection: Membrane systems, modular MBRs, tertiary polishing, and digital process controls are maturing at different cadence. The report maps technology readiness, total cost of ownership levers, and integration risk by application to shorten technology selection timelines.
- Regulatory compliance and market access: New national and subnational mandates are reshaping demand profiles. Executives need a prioritized regulatory heat map and a decision tree for compliance investments — both are included.
- M&A and partnering strategies: Fragmentation and rising service-contract volumes make the market ripe for consolidation and alliance formation. The report contains a proprietary vendor scorecard and M&A playbook tailored to corporate buyers and private equity.
What the report contains — practical components for busy leaders
- Market model and forecast engine: an interactive model that lets users run alternate macro, regulatory, and technology-adoption scenarios and export customized forecasts for internal planning.
- Commercial playbooks: procurement templates, contract structures (capex vs performance-based O&M), and negotiation checklists for long-term reuse offtake and water-as-a-service agreements.
- Technology decision matrix: side-by-side techno-economic comparisons (including lifecycle capex/opex, energy intensity, footprint, and water quality outcomes) of membrane technologies, biological and advanced tertiary approaches.
- Project and pipeline intelligence: anonymized, stage-graded project pipeline covering municipal, industrial, and decentralized initiatives — prioritized by execution risk and commercial opportunity.
- Regulatory and standards toolkit: a concise interpretation of emerging requirements (including federal and state-level guidance, and key certification standards) and templates to align technical specifications with permitting expectations.
- Vendor diagnostics: qualitative and quantitative benchmarking of leading suppliers, including service-model evaluation, supply-chain risk, and technology roadmaps.
- Case studies and implementation playbooks: operational lessons from large-scale and decentralized reuse projects, with templates for pilot design, monitoring programs, and community engagement.
Reading the market trajectory: key takeaways for 2026
The trajectory from 2020 to 2025 shows accelerating adoption as scarcity, regulatory pressure, and corporate sustainability targets converge. The projected near-doubling of market value by 2032 underscores that water reuse is moving from niche sustainability programs to core utility and industrial infrastructure. For 2026 specifically, organizations should treat water reuse investments as strategic infrastructure rather than discretionary projects — timing and sequencing matter because procurement lead times, permitting cycles, and construction timelines will compress strategic windows.
Water Recycling And Reuse Market
Strategic imperatives — three priorities for executives
- Embed reuse into infrastructure masterplans: Treat recycled water supply as a long-duration asset with dedicated refinancing and risk-transfer instruments. Use our forecast engine to align offtake contracts with plausible demand scenarios.
- Design for modularity and flexibility: Modular MBRs and packaged tertiary systems enable phased deployments and risk-limited pilots that can scale. The report’s decision matrix helps select the point solution that offers the best balance of performance, footprint, and expansion cost.
- Invest in digital and analytics: Real-time monitoring and process automation materially reduce energy consumption and chemical use. Vendors combining membrane hardware with analytics and service contracts increasingly capture higher lifetime value — a shift the report documents and quantifies.
Competition and vendor strategy — what to watch
The competitive landscape is a mix of global system integrators, specialized membrane and chemical suppliers, and fast-growing modular players. Key industry participants profiled in the report include household names and specialists that shape solutions across municipal and industrial segments. Recent market activity highlights strategic moves worth noting:
Water Recycling And Reuse Market
- Major pump-and-infrastructure players are expanding through acquisitions to integrate membrane and analytics capabilities, consolidating service contracts and improving lifecycle margins.
- Global operators are securing long-duration project agreements and O&M contracts on large industrial reuse plants, underscoring the value of demonstrated construction-to-operations capabilities.
- Modular and decentralized providers are winning municipal and industrial pilots where speed-to-deploy and lower upfront risk matter most.
Our vendor scorecard ranks suppliers on technical performance, service footprint, balance-sheet strength, and innovation trajectory — a practical tool for procurement and corporate development teams evaluating suppliers or targets.
Regulation, standards and the policy impulse
Policy developments are a primary demand lever. Recent federal and subnational initiatives are expanding reuse applications into heavy industries, data centers, and energy sectors. Standards for onsite reuse systems are gaining traction in plumbing codes and permit frameworks, while state-level rules are already mandating recycled water use in certain oil and gas operations. These changes compress the timeline for compliance investments and create differentiated opportunity for firms that can navigate complex permitting regimes efficiently.
Operational risks and how the report helps de-risk execution
- Performance risk: The report provides commissioning and verification protocols, recommended monitoring suites, and acceptance criteria aligned with emerging certification standards.
- Supply-chain and capital risk: We offer a procurement timeline template and alternative sourcing strategies to mitigate single-supplier exposure for membranes and high-lead-time components.
- Energy and O&M cost volatility: Scenario analysis shows sensitivity of unit water cost to electricity and chemical prices, and provides hedging and operational levers to preserve margins.
Use cases and commercial playbooks
From centralized municipal "pure water" programs to industrial process reuse and decentralized greywater systems, our report dissects use cases and provides tailored playbooks. Each playbook includes design heuristics, typical contract structures, lifecycle cost ranges, and stakeholder engagement templates. These are intended to shorten procurement cycles and improve capital efficiency for first-of-a-kind and scale projects alike.
Actionable next steps for corporate leaders in 2026
- Commission a 12–24 month pilot with clear success metrics tied to an explicit scale-up decision — use the report’s pilot templates to set technical and commercial gates.
- Run the report’s scenario model against your internal demand forecasts and budget cycles to identify fiscal years where investment yields the highest risk-adjusted return.
- Re-assess supplier shortlists using our vendor diagnostics and include service-contract performance guarantees to align incentives across construction and operations phases.
- Engage regulators early using the report’s permit-play checklist to compress approval timelines and reduce the risk of stop-work conditions.
Why PW Consulting’s report is the right tool this year
This publication combines a rigorously validated market forecast with practitioner-focused tools: an interactive modeling engine, hands-on procurement and pilot templates, and a vendor benchmarking framework keyed to execution risk. The report surfaces strategic inflection points — not only where demand will grow, but where timing, contracting, and technology choices will determine winners and losers.
Next steps and how to obtain the full intelligence
This briefing is intended as a strategic preview. The full report contains the granular segmentation, project-level pipelines, vendor scorecards, and downloadable Excel models that corporate strategy, procurement, and engineering teams will need to implement the actions outlined here. For secure access to the complete dataset, model, and bespoke briefing sessions, please contact PW Consulting or visit our Water Recycling And Reuse Market report page to request the full deliverable and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Water Recycling And Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Ethernet Market Poised for a 19.5% CAGR Through 2032
By pmarketresearch, 2026-07-01
Automotive Ethernet Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
As automotive OEMs and Tier‑1 suppliers transition toward software‑defined vehicles, Automotive Ethernet is no longer an optional enabler — it is the architecture. PW Consulting’s latest Automotive Ethernet Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes the macro trajectory, competitive dynamics, regulatory drivers and technology bottlenecks that will determine winners and losers through the next planning cycle. All figures are expressed in USD Million.
Automotive Ethernet Market
Market Snapshot: growth, scale and concentration
Our analysis shows the market accelerating from a modest base in the early 2020s to a pronounced expansion by 2025, reflecting increasing in‑vehicle bandwidth demands and zonal or centralized electrical/electronic architectures. The report quantifies a compound annual growth rate of 19.52% over the forecast horizon, underscoring a rapid scale‑up that reshapes supplier economics, supply chain risk profiles and platform strategies.
Automotive Ethernet Market
This growth is accompanied by moderate market concentration: the top three suppliers control a material share of market revenues, and the top five approach a dominant position. These concentration metrics indicate that while innovation remains distributed across a broad vendor ecosystem, strategic partnerships and qualification cycles are increasingly decisive — a dynamic that procurement and product planning teams must internalize for 2026 program decisions.
Automotive Ethernet Market
Why this matters for 2026 decision cycles
- Program sourcing windows are narrowing. With vehicle programs now specifying higher Ethernet port counts and multi‑gigabit links, qualification lead times for PHYs, switches and certified test tooling need to be locked in earlier in the development cycle. Delays in component qualification cascade into software validation and vehicle cybersecurity approval.
- Bandwidth economics change platform choices. Higher link speeds and centralized compute options create a tradeoff between copper PHY investments and optical or multi‑domain consolidation strategies. Total cost of ownership modeling must include not only BOM cost but qualification, serviceability and cybersecurity lifecycle costs.
- Standards and regulation are shifting the risk profile. New ISO and OPEN Alliance standards for high‑speed PHYs and multi‑drop topologies, together with regulatory mandates on in‑vehicle cybersecurity, are reshaping architecture requirements and supplier selection criteria for 2026 vehicle launches.
Actionable insights for executives (how to use this report)
- Procurement: prioritize multi‑supplier qualification pathways for critical PHYs and switches to mitigate single‑supplier risk while negotiating volume‑based terms for emerging high‑bandwidth products.
- Product Strategy: adopt a hybrid zonal/centralized architecture assessment framework that compares latency, wiring harness complexity and software update surfaces across candidate topologies.
- R&D Investment: accelerate signal‑processing capabilities for 10G and 1G PHYs and invest in deterministic switching and time‑sensitive networking stacks where ADAS and domain convergence are priorities.
- Safety & Cybersecurity: embed UN ECE R155 compliance and ISO 26262 considerations into early architecture tradeoffs; Ethernet design choices affect attack surfaces and safety partitioning.
- M&A & Partnerships: identify targets that complement platform roadmaps — for example, software stacks, diagnostic tooling or deterministic switch IP — rather than standalone PHY suppliers whose value can be squeezed by major semiconductor players.
Report contents — what PW Consulting delivers to your strategy team
The study blends quantitative forecasting with practical, executable deliverables designed for 2026 planning cycles:
- Proprietary demand model (2026–2032) calibrated to vehicle program timelines, port counts and migration curves for multi‑gigabit links.
- Scenario analysis that quantifies upside/downside across three adoption pathways (baseline, accelerated, conservative), enabling risk‑adjusted capital planning.
- Supplier scorecards and qualification matrices covering performance, cost, compliance footprint and ecosystem support (software, test tooling, reference designs).
- Architecture playbooks that translate standardization and regulatory drivers into actionable design patterns for OEMs and Tier‑1s (including harness topologies, zonal partitioning and gateway strategies).
- Procurement templates and negotiation levers tailored to the semiconductor and module lifecycle specificities of Automotive Ethernet components.
To preserve the competitive integrity of our clients and to encourage direct engagement with the full dataset, the report intentionally withholds granular regional and application‑level revenue splits in this release. The comprehensive tables, regional breakouts and application matrices are available in the full report.
Competitive landscape — who matters and why
Automotive Ethernet is now a multi‑layered ecosystem spanning PHY suppliers, switch vendors, SoC integrators, software and test tool providers. Our competitive assessment highlights different classes of players and practical implications for selection and alliance strategies:
- Tier‑A semiconductor platforms. Companies providing integrated MAC‑PHY solutions and SoCs play a critical role in enabling centralized compute architectures. Their roadmaps determine how quickly OEMs can consolidate domains and increase internal bandwidth demands.
- PHY and switch specialists. Established PHY providers continue to push the performance envelope (100BASE‑T1 through 10GBASE‑T1), and their compliance with OPEN Alliance and ISO standards materially reduces integration risk for OEMs.
- Deterministic networking innovators. Vendors focusing on time‑sensitive networking, hardware offload and deterministic switches are differentiators for ADAS and software‑defined vehicle use cases.
- Testing and diagnostics ecosystem. As link speeds increase, so do the demands on validation tooling and diagnostics. Providers of purpose‑built test hardware and software play an outsized role in reducing time‑to‑market.
Representative vendor profiles featured in the study include global semiconductor leaders delivering PHYs and integrated switches, specialist deterministic‑networking firms, and a cohort of tooling and validation vendors. Recent industry developments — such as major product launches, OPEN Alliance certifications and vehicle integrations announced in 2025 — are discussed in context to illustrate near‑term shifts in supplier viability and strategic fit.
Selected recent developments — implications for 2026
- OPEN Alliance compliance and certifications for higher‑speed PHY families materially shorten validation timelines for OEMs planning 2026 launches; certification news in late 2025 signals production readiness for certain 10G components.
- Vehicle integrations of 10G PHYs in high‑bandwidth platforms demonstrate the immediate ADAS use cases for multi‑gigabit links, and create pressure on suppliers to deliver scaled production and consistent test results.
- Joint development agreements between semiconductor vendors and automotive tier suppliers illustrate the strategic push toward combined silicon‑software solutions; such collaborations should be considered potential risks or opportunities depending on your supplier positioning.
Standards, regulation and technology bottlenecks
Regulatory and standards developments are not background noise — they are active drivers of architecture and procurement choices:
- ISO standards outlining high‑speed PHY requirements and OPEN Alliance specifications for multi‑drop and multi‑gigabit topologies directly influence supplier roadmaps and interoperability requirements.
- UN ECE R155 cybersecurity requirements have elevated the importance of secure boot, segmented communications and in‑vehicle intrusion detection — all of which are impacted by Ethernet topology choices.
- Technical bottlenecks remain, notably in mitigating electromagnetic interference for high‑density unshielded twisted pair deployments and in deploying reliable 1000BASE‑T1 implementations; overcoming these requires investments in signal processing, cable engineering and system‑level testing.
Practical recommendations for 2026 planning
- Start supplier qualification today for any program with expected MY2026 production start — assume multi‑vendor pathways for critical PHY and switch components.
- Embed standards and regulatory compliance checkpoints into architecture gates; certification status should be a weighted criterion in supplier selection.
- Invest in test tooling and signal integrity expertise to accelerate debug cycles for high‑speed links; validated diagnostics reduce program risk and warranty exposure.
- Design procurement contracts that reflect technology lifecycle acceleration — include clauses for roadmap access, compliance milestones and volume flexibility to accommodate shifting port counts.
How to access the full intelligence
This brief is a strategic preview. PW Consulting’s full Automotive Ethernet Market report includes the complete dataset, regional and application breakouts, supplier scorecards and the proprietary demand model used to generate the forecasts. Because granular segmentation and supplier revenue matrices are commercially sensitive and critical to program execution, they are intentionally excluded from this preview. For enterprise access, bespoke advisory sessions or licensing of our forecast model for internal scenario planning, please visit our report page or contact a PW Consulting industry analyst.
PW Consulting’s Automotive Ethernet Market study is designed to convert macro trends into operational decisions for 2026 program cycles. Whether you are an OEM architecting zonal ECUs, a Tier‑1 sizing harnesses, a semiconductor supplier plotting a roadmap, or an investor assessing consolidation targets, this analysis provides the framework to prioritize investments and to reduce execution risk in an era of rapid bandwidth adoption.
For detailed analysis of this topic, please visit the official page: Automotive Ethernet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Inorganic Feed Mycotoxin Binders & Modifiers Market to Reach USD 1,308.21 Million by 2032, Expanding at a 5.15% CAGR
By pmarketresearch, 2026-07-01
Inorganic Feed Mycotoxins Binders and Modifiers Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
As supply chains, regulatory regimes, and feed production economics converge under intensified global scrutiny, inorganic mycotoxin binders and modifiers have moved from niche risk-mitigation products to strategic levers in animal nutrition portfolios. PW Consulting’s latest market study — based on a 2020–2025 historical review with a 2026–2032 forecast horizon — quantifies that transition and frames specific decisions executives must make in 2026 to capture durable value.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Market trajectory at a glance
Key macro context from our report: the global Inorganic Feed Mycotoxins Binders and Modifiers market base year is 2025 (USD, Million), and the category has expanded from an estimated USD 716.1M in 2020 to USD 920.5M in 2025. Our forecast projects continued growth through 2032, reaching an estimated USD 1,308.2M, underpinned by a compound annual growth rate (CAGR) of approximately 5.15% over the 2026–2032 period.
Inorganic Feed Mycotoxins Binders And Modifiers Market
These headline metrics reflect more than raw demand — they signal structural forces reshaping market economics: sustained feed-industry exposure to mycotoxin risk; broadening acceptance of mineral-based interventions across species; and an innovation premium for products that demonstrably balance efficacy with nutrient safety. PW Consulting’s report unpacks these drivers and translates them into investment and portfolio decisions for 2026.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Why 2026 is a pivotal year for corporate strategy
-
Operationalizing scale: With mid-single-digit market growth entrenched, 2026 will differentiate companies that convert R&D credibility into commercial scale. Firms that can move from lab and controlled-trial efficacy to predictable supply and validated on-farm ROI will command pricing power and channel preference.
-
Regulatory alignment wins market access: Regulatory clarity — for example, authorizations that recognize certain bentonites for aflatoxin mitigation — favors players who align product dossiers to jurisdictional frameworks while proactively generating data on nutrient bioavailability and animal safety as required by agencies such as EFSA.
-
Raw-material security as a competitive moat: Because key products are mined aluminosilicates and related minerals (bentonite, montmorillonite, HSCAS, sepiolite, zeolites), companies that secure upstream access, diversify sourcing, or vertically integrate processing will alleviate margin volatility and guarantee product consistency.
Competitive landscape — concentration, positioning, and recent moves
The market remains moderately concentrated. Our analysis indicates that the top three players account for approximately 28.5% of market revenues (CR3), while the top five reach about 39.2% (CR5). That means meaningful share remains accessible to fast-moving challengers and specialty players who can combine technical differentiation with channel execution.
Headline competitor profiles in the report include:
-
Amlan International (Oil-Dri Corporation of America) — Focused on proprietary mineral-based binders such as Calibrin-A and Calibrin-Z, with product positioning that emphasizes rapid aflatoxin binding and broad-spectrum biotoxin capture. Amlan has been active in product commercialization and partnerships — notably launching clay-based formulations in strategic markets and showcasing innovations at major trade events in 2025.
-
Kemin Industries — Offers the TOXFIN range leveraging activated adsorbents and argillaceous minerals for broad-spectrum binding and aflatoxin B1 reduction. Kemin’s strength is integrated technical services and established sales reach in feed additive channels.
-
Tolsa — European clay-specialist with blended products combining bentonite, sepiolite, and activated carbon for mycotoxin sequestration; their asset base is oriented to mineral processing and feed applications.
-
Bentoli Inc. — A focused supplier of clay-based mycotoxin binders and feed additives, oriented to livestock and poultry markets with pragmatic formulations addressing toxin control.
Recent developments documented in the industry underscore commercial momentum: product launches and strategic showcases by leading players in 2025–2026 demonstrate both market validation and competitive escalation. PW Consulting’s report analyzes these moves and the implied playbooks, including regional go-to-market sequencing, channel partnerships, and co-development models.
Regulatory and raw-material dynamics that will shape strategy
-
Regulatory expectations: Authorities increasingly require evidence not only of mycotoxin sequestration but also of neutral impact on nutrient bioavailability and animal safety. The report maps the testing frameworks and dossier requirements across key jurisdictions and offers a prioritized certification pathway for market entry and claims substantiation.
-
Raw material reality: Inorganic binders are predominantly mined minerals with variable properties. Particle size distribution, thermal processing, and activation treatments materially affect binding spectrum and capacity. Our technical annex evaluates supply concentration, beneficiation costs, and potential pinch points that could affect 2026 sourcing strategies.
-
Standards and lab validation: Standardized in vitro and in vivo assay protocols matter for buyer confidence. The report recommends a test matrix that balances regulatory acceptability, commercial relevance, and cost-efficiency for product qualification programs.
What the PW Consulting report delivers — practical, transaction-ready intelligence
PW Consulting’s market study is deliberately action-oriented. Beyond market sizing and forecast scenarios, the deliverables include:
-
Commercial playbooks for product launch and channel expansion, including pricing strategies, distributor scorecards, and on-farm trial sequencing.
-
M&A and partnership screening frameworks to identify targets that deliver mineral supply, processing capability, or route-to-market reach. Our due-diligence checklist covers technical validation, regulatory dossiers, and integration risk markers.
-
Operational templates for supply-security: sourcing maps, contingency plans for material variability, and processing tolerances that preserve product efficacy.
-
Decision-support models that translate technical performance (binding spectrum, adsorption capacity) into commercial outcomes (feed conversion, mortality reduction, return on investment) under multiple farm-level scenarios.
-
Competitive battlecards summarizing rival product claims, technological differentiators, and likely responses — enabling rapid strategy alignment for marketing and sales teams.
Strategic recommendations for executives planning 2026 moves
-
Prioritize validation that regulators and buyers accept: Invest in a dual-track evidence program — regulatory-grade dossiers for market access and pragmatic field trials that speak to feed mills and integrators. Demonstrated safety with no nutrient impairment is a gating factor for mainstream adoption.
-
Secure and optimize the supply chain: Lock in multi-source access to critical clays, evaluate beneficiation partnerships to standardize product quality, and consider toll-processing agreements to scale quickly without heavy capex.
-
Differentiate beyond basic adsorption: The winners will be those who articulate product stories around spectrum breadth (polar and nonpolar mycotoxins), kinetics (speed of binding), and formulation compatibility (premix, pelleting resilience). Strategic investments in surface modification and hybrid adsorbent blends will pay off.
-
Leverage partnerships for faster market penetration: Distribution alliances with feed additive companies, co-marketing with veterinary pharmaceutical partners, and region-specific launch partners can compress commercialization cycles and share trial costs.
-
Prepare M&A playbooks now: Given moderate concentration and available specialty assets, build a shortlist of targets that provide either upstream mineral control or complementary technologies (e.g., activated carbons, sepiolite-based formulations). The report’s M&A framework makes this plug-and-play for corporate development teams.
How to use PW Consulting’s insight for board-level decision making
Boards and executive teams should treat inorganic mycotoxin binders as both a defensive necessity and an offensive growth vector. The decision lens we recommend for 2026 revolves around three questions:
-
Can we ensure supply and technical consistency at target scale?
-
Do our product claims meet the evidentiary bar demanded by regulators and large feed buyers?
-
Where on the spectrum of build, partner, or buy do we maximize shareholder value within an acceptable timeline?
PW Consulting’s report provides tailored scenario analyses and financial templates that attach probabilities and expected value to each path, enabling boards to set funded initiatives for 2026 with clarity and accountability.
Closing — why this report matters now
The market’s historical climb from a mid-2020s base to the forecasted 2032 figure reflects persistent demand for risk mitigation in feed systems and an openness to mineral-based solutions. However, the market will reward only those players who can translate laboratory efficacy into validated supply-grade products, navigate evolving regulatory expectations, and secure resilient raw material sources.
Our research balances technical depth with commercial pragmatism: it reveals where structural value exists, where competitive pressures will intensify, and what operational and regulatory investments are non-negotiable in 2026. For executives charting next-year budgets and strategic priorities, the report is a decision-ready guide that connects science to P&L outcomes without leaving risk unquantified.
Next steps
PW Consulting invites industry leaders to a concise executive briefing to explore tailored implications for their portfolios, including scenario-based ROI modeling and a prioritized action plan for 2026. The full report contains detailed segmentation, territorial and application breakdowns, and granular competitor profiles for executives and deal teams — access it through our official release channels to unlock the supporting datasets and proprietary templates referenced above.
For detailed analysis of this topic, please visit the official page: Inorganic Feed Mycotoxins Binders And Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sleep Apnea Masks Market Poised to Expand at 8.15% CAGR from 2026–2032
By pmarketresearch, 2026-07-01
Sleep Apnea Masks Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
PW Consulting’s latest market research on the Sleep Apnea Masks market provides an evidence-driven playbook for executive teams preparing critical 2026 decisions. The global market has moved from roughly USD 2.06 billion in 2020 to an estimated USD 3.15 billion in 2025, and is projected to reach approximately USD 5.45 billion by 2032 at a compound annual growth rate (CAGR) of about 8.15% over the forecast horizon. These macro dynamics, combined with a high degree of industry concentration (CR3 ~78.4%; CR5 ~89.6%), materially change the geometry of competitive opportunity—favoring scale, differentiated clinical value, and payor-aware commercialization.
Sleep Apnea Masks Market
Why this report matters for 2026 strategic decisions
2026 is a watershed year for sleep-therapy stakeholders: regulatory clarity is crystallizing, new entrants and incumbents are introducing differentiated interfaces and AI-enabled features, and reimbursement pathways continue to evolve in core markets. Our study translates these external forces into an actionable decision framework for product managers, business development leads, procurement directors, and private equity firms. The research combines a rigorous top-down market sizing with bottom-up validation across clinical, regulatory, and channel inputs to produce a practicable roadmap—not an academic exercise.
Sleep Apnea Masks Market
Core market dynamics — concise, actionable signals
-
Steady market expansion: The market’s trajectory from 2020 through 2025 demonstrates durable demand as diagnosis rates, treatment adherence programs, and device compatibility improve. The forecast to 2032 at an 8.15% CAGR signals sustained commercial upside for firms that can convert clinical efficacy into patient-preferred interfaces and payor-aligned value propositions.
Sleep Apnea Masks Market -
High concentration: The top three and five players together control a substantial share of market value, which elevates the importance of partnership, niche specialization, and selective M&A to attain competitive scale.
-
Regulatory and reimbursement contours: CPAP masks remain regulated as Class II devices under 510(k) pathways in the U.S., and public payors like Medicare maintain established HCPCS coverage and replacement schedules for mask interfaces—both elements that shape product rollout timing and commercial models.
-
Materials and manufacturing: Medical-grade silicone continues to be the dominant cushion material due to biocompatibility and cleaning durability—an operational constraint that influences supplier selection and cost curves.
Competitive landscape: what incumbents and newcomers reveal
Our qualitative and transactional analysis profiles leading OEMs and relevant new entrants, mapping technology vectors, channel footprints, and regulatory milestones that materially affect go-to-market choices:
-
ResMed (San Diego): Continues to invest in integrated therapy ecosystems—AI-enabled comfort and personalization are now cleared and increasingly embedded as a differentiator for mask-device pairing. For partners, the lesson is clear: compatibility with device-side intelligence is a near-term commercial must.
-
Fisher & Paykel Healthcare (Auckland): Advances in cushion and headgear design—aimed at fit and seal consistency—underscore the continued yield from engineering-led differentiation in core mask types.
-
Philips Respironics (Amsterdam/Pittsburgh operations): Remains a scale competitor with broad interface portfolios; integration of user experience innovations into established channels is their primary lever for retention.
-
Inogen (Goleta): The Aurora entry demonstrates that adjacent respiratory players can rapidly introduce credible CPAP masks when supported by clinical-use studies—new entrants should plan for rapid evidence generation to accelerate channel acceptance.
-
REMSleep (Blackshear): Recent expanded FDA 510(k) clearance for a nasal pillow system exemplifies how regulatory wins can unlock institutional channels and broaden patient applicability—especially relevant for companies targeting hospitals and sleep labs.
-
Other OEMs (Drive DeVilbiss, React Health, Bleep, BMC Medical): These companies highlight alternative routes to market—from value-focused OEM supply to design-led niche products—illustrating multiple commercialization archetypes beyond incumbent strategies.
Recent product and regulatory developments: strategic takeaways
Key events through early 2026 underscore the bifurcation of competitive advantage into (a) clinical/regulatory credibility and (b) user-centered design integrated with device ecosystems. Examples include AI-enabled comfort features now cleared for market, new cushion/headgear launches, and regulatory clearances that extend product usage into institutional settings. For strategic planners, the implications are straightforward: prioritize regulatory roadmaps and clinical evidence generation concurrent with design investments to compress time-to-revenue.
What’s inside the PW Consulting report (practical deliverables)
Our report is structured as an executive-grade decision toolkit rather than a purely descriptive market brief. Key deliverables include:
-
Macro and micro market sizing with a validated forecast model and scenario analyses to stress-test 2026–2032 revenue paths.
-
Competitive matrix and capability heatmaps describing product portfolios, regulatory status, and channel strength—designed to support rapid partner/target screening.
-
Commercial playbooks for four go-to-market archetypes: incumbent OEM scale, challenger specialist, value/OEM supply, and platform-integrated device partnerships.
-
Regulatory and reimbursement maps with timing assumptions and risk buffers to accelerate launch approvals and payer contracting.
-
Supplier and cost structure benchmarks focused on cushion materials, headgear sourcing, and high-volume manufacturing levers.
-
M&A and partnership target shortlists with acquisition valuation frameworks and integration checklists tailored for 2026 deal pacing.
-
Clinical adoption levers and patient adherence frameworks—translating mask design and comfort features into measurable adherence uplift and downstream device utilization.
Recommended actions for leadership teams in 2026
The following strategic actions distill our analysis into immediate next steps for companies looking to capture disproportionate share of the forecast growth:
-
Prioritize regulatory sequencing: align 510(k) or equivalent filings with parallel clinical-use studies to shorten commercialization cycles, particularly if targeting institutional channels.
-
Invest in compatibility partnerships: ensure mask designs are interoperable with AI-enabled therapy features from major device OEMs to avoid exclusion from integrated ecosystems.
-
Optimize supplier base for silicone cushions: secure biocompatible material supply and dual-sourcing plans to mitigate cost and availability risks.
-
Map reimbursement timing and documentation: build HCPCS-aligned product lifecycles and replacement plans into commercial contracts to protect unit economics.
-
Segment route-to-market: deploy differentiated routes (direct for premium platforms, distributors for mid-market, OEM supply for scale) rather than a one-size-fits-all distribution model.
-
Consider bolt-on M&A for rapid feature acquisition (e.g., headgear technology, AI comfort algorithms) instead of multi-year internal development for near-term market access.
-
Document adherence economics: quantify how small improvements in seal and comfort translate into measurable increases in therapy compliance and downstream device revenue.
Why PW Consulting’s approach reduces strategic execution risk
Our methodology blends time-series market modeling with primary interviews across clinicians, procurement officers, and payor representatives, producing high-confidence forecasts and executable commercial plans. Importantly, while we present overall market size and concentration metrics to guide portfolio sizing and capital allocation, the report intentionally withholds granular public disclosure of proprietary subsegment splits in this release—those detailed segmentation tables, regional builds, and customer-level insights are included in the full report to support transaction-level diligence.
Next steps and how to use this study
For boards, this report serves as an input to 2026 capital allocation decisions: whether to greenlight product investments, pursue M&A, or shift distribution strategies. For commercial teams, the implementation playbooks provide immediate templates for payer engagement and channel rollout. For R&D leaders, the product-pricing-supplier nexus in the report helps prioritize features that materially improve adherence while protecting margins.
PW Consulting invites decision-makers to access the full report for the detailed segmentation tables, regional and application breakdowns, and our proprietary scenario models that underpin the revenue forecasts. The complete dataset and executable annexes are designed to be directly reusable in strategic planning, investment memos, and transaction diligence.
Conclusion
The Sleep Apnea Masks market offers predictable growth and concentrated competitive structures that reward focused strategic moves in 2026. Companies that synchronize regulatory strategy, evidence generation, supply resilience, and channel design will capture the bulk of the opportunity. PW Consulting’s study is structured to turn these insights into executable plans—download the full report to see the proprietary subsegment data, calibrated scenarios, and operative templates that will make your 2026 choices decisive.
For detailed analysis of this topic, please visit the official page: Sleep Apnea Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Robust 7.51% CAGR for Gas Humidity Sensors Market in 2026–2032 Outlook
By pmarketresearch, 2026-07-01
Gas Humidity Sensors Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
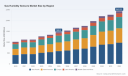
The global market for gas humidity sensors has entered a phase of sustained expansion driven by converging forces: electrification and autonomy in transportation, tighter environmental and safety regulations, broader IoT adoption, and the maturation of MEMS and digital sensing technologies. Our newest study (base year 2025) models the market in USD Million terms and tracks a multi-year climb from the early-2020s to a materially larger TAM by the end of the decade. Between 2026 and 2032 the market is projected to expand at a compound annual growth rate (CAGR) of 7.51%, reflecting continued capital spending in industrial controls, HVAC modernization, automotive environmental sensing (including LiDAR systems), and healthcare applications.
Gas Humidity Sensors Market
This release is a strategic "trailer": it highlights the report’s value to boardrooms, corporate strategy teams, and product leaders making 2026 investment decisions, while intentionally omitting granular segment tables and region-specific shares to encourage direct engagement with the full report for transaction-grade data.
Gas Humidity Sensors Market
Why this matters for 2026 decision-makers
- Timing: 2026 will be a make-or-break year for product roadmaps and supplier contracts. Organizations that lock in design-wins, secure diversified supply agreements, and align sensor-specs with new regulatory safety standards will gain durable advantage.
- Capital allocation: With the market expanding at ~7.5% CAGR over the 2026–2032 forecast window, executives must balance incremental R&D in sensor robustness and functional safety against near-term supply-chain and materials volatility that can stress margins.
- Risk management: Trade-policy shifts and materials lead-time inflation mean procurement and sourcing strategies require scenario-planning rather than static supplier scorecards.
Market trajectory at a glance (high-level)
Our model tracks the market through a recent five-year historical window (2020–2025) and an extended forecast (2026–2032). The market more than recovered and expanded after the 2020–2021 disruptions, showing accelerated adoption across industrial and consumer-facing use cases by 2023–2025. Looking forward, the total market value approaches the mid-2030s with steady year-on-year growth, driven by product miniaturization, integrated environmental sensor packages, and an increase in safety-rated humidity sensing requirements in automotive and industrial systems.
Gas Humidity Sensors Market
Competitive landscape: what leaders and challengers are doing
The market displays moderate concentration: the top three players control a material share but the top five still leave room for regional specialists and technology-focused challengers. This structure creates both entry pockets and consolidation rationale for private equity or larger OEMs seeking vertical integration.
- Sensirion AG (Stäfa, Switzerland) — Sensirion continues to push at the intersection of high-precision digital sensing and automotive-grade robustness. Their recent investor communications emphasize ASIL-rated humidity sensing and multiple design-wins with LiDAR OEMs, signalling a strategy to capture the automotive environmental sensing upgrade cycle. For partners and buyers, Sensirion represents a benchmark for design-in support and long-lifecycle device planning.
- Honeywell International Inc. (Charlotte, USA) — Honeywell leverages broad channel reach and building automation credentials. Its Building Technologies segment makes it a go-to for HVAC and industrial automation integrators. Expect Honeywell to compete on system-level bundling and service-backed offerings rather than pure-component price.
- Texas Instruments (Dallas, USA) — TI’s digital humidity sensors target low-power, high-accuracy embedded applications. TI’s strength is in reference designs and high-volume supply to electronics OEMs, making it attractive to consumer and industrial embedded-system designers.
- Bosch Sensortec (Reutlingen, Germany) — Bosch’s combo sensor approach (multi-parameter MEMS modules) is optimized for IoT and wearable ecosystems where integrated environmental telemetry reduces BOM and design complexity.
- Amphenol, TE Connectivity, Vaisala, E+E Elektronik — These players occupy differentiated niches: ruggedized sensors for harsh environments, aerospace and defense distribution partnerships, meteorological-grade instruments, and thin-film-based transmitters for regulated industries. Their strategic moves (distribution agreements, specialized product launches) underscore a bifurcated market of commodity modules and premium, application-specific instruments.
Recent industry signals that should shape strategy in 2026
- Sensirion’s April 2026 investor presentation spotlighted ASIL-rated humidity sensing and design-wins with top LiDAR OEMs — a signal that automotive buyers are elevating humidity sensing from ancillary to safety-relevant system element.
- Product innovation continues: 2025–2026 launches included new digital humidity-temperature families and integrated MEMS elements targeted at indoor air quality and IAQ analytics, illustrating the trend toward combo sensors and embedded analytics.
- Channel and distribution plays (e.g., franchised agreements for aerospace/defense pathways) reveal go-to-market diversification that fast-tracks adoption in regulated end-markets.
- Macro tailwinds and headwinds: supply chain disruptions—particularly increased lead times for rare-earth-related components—and new tariff regimes since 2025 are elevating procurement risk. These are not short-term noise; they will re-shape sourcing strategies and regionalization debates.
What the full PW Consulting report delivers (practical, transaction-ready content)
Our report is designed as a hands-on toolkit for 2026 planning cycles. Key deliverables include:
- Robust market sizing (USD Million, base year 2025), historical trend analysis (2020–2025) and a granular forecasting model through 2032 with scenario toggles to stress-test assumptions.
- Competitive benchmarking with technology stacks, qualification timelines (including ASIL and other safety standards), go-to-market maps, and supplier scorecards calibrated for high-volume vs. niche procurement.
- Commercial playbooks: pricing corridors, value-based positioning for combo sensors vs. discrete components, and OEM procurement negotiation templates.
- Supply-chain risk matrix: supplier concentration analysis, raw-material dependencies, mitigation strategies, and inventory/lead-time playbooks linked to tariff and geopolitical scenarios.
- Product development guidance: recommended spec sheets for automotive-grade humidity sensors, industrial probe durability requirements, and test protocols for environmental drift and lifetime calibration.
- M&A and partnership scouting: target identification, valuation frameworks, and integration checklists for bolt-on acquisitions or strategic alliances.
- Case studies and deployment blueprints across HVAC modernization, LiDAR-enriched automotive sensor stacks, industrial process control, and healthcare monitoring.
Recommended 2026 actions — concise playbook
- Prioritize ASIL and safety-aligned product roadmaps if you supply or integrate with automotive LiDAR and critical control systems. The market is shifting to treat humidity sensing as part of the safety envelope.
- Move from single-sourcing to a multi-tier supplier architecture for critical components. Workable strategies include dual-sourcing, regional buffers, and strategic inventory reserves for long-lead materials.
- Invest in system-level differentiation: bundled sensor modules with embedded calibration, diagnostics, and OEM-friendly software stacks reduce total cost of ownership and accelerate design-ins.
- Use the moderate market concentration to explore consolidation opportunities — selectively acquiring or partnering with specialized sensor firms can accelerate entry into premium segments (meteorological, life sciences, aerospace).
- Stress-test pricing and margin models against 40%+ increases in lead times reported for certain critical components, and incorporate tariff scenario impacts into supplier contracts and product costing.
How executives should use this preview
Consider this article a strategic briefing: it points to the forces that will shape procurement, product development, and M&A decisions in 2026. For board-level strategy sessions, use the macro market trajectory and concentration insights to set investment thresholds and risk tolerances. For product and procurement teams, deploy the recommended mitigations and technology choices in forthcoming RFQs and BOM reviews.
Why the full report is essential
We intentionally withhold detailed segment shares, region-specific breakdowns, and confidential company-level revenue tables from this public preview. Those analytics are integrated into the full report’s models and are necessary for precise budgeting, supplier negotiations, and valuation work. The report’s interactive model allows you to re-run forecasts under custom scenarios (tariff shocks, accelerated EV adoption, or supply-chain restructurings) and export transaction-ready tables for finance and procurement teams.
Next steps
PW Consulting is scheduling limited, live briefings with C-suite teams and strategic buyers in Q3–Q4 2026 to walk through bespoke scenarios and model customizations. If your 2026 plan includes design-win pursuits in automotive LiDAR, scaling plans for HVAC retrofit programs, or M&A activity to capture premium niches, secure a briefing slot to review the full dataset and executable playbooks.
For access to the complete Gas Humidity Sensors Market report, including the interactive forecasting model and supplier scorecards, please visit our report landing page (link available in the PW Consulting client portal). The full intelligence package is designed to convert insight into measurable action in 2026.
For detailed analysis of this topic, please visit the official page: Gas Humidity Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HFO Cooling Fluids for Data Centers Poised for Explosive Growth, Forecasting an 18.02% CAGR
By pmarketresearch, 2026-07-01
Hfo Cooling Fluids For Data Center Market — Strategic Briefing for 2026 Decision-Makers
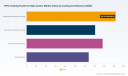
The market for HFO cooling fluids in data centers has moved from niche pilot projects to an investment-grade industry in under a decade. Our latest market model shows global revenues expanding from USD 285.4 Million in 2020 to USD 610.5 Million in 2025, and accelerating through the forecast window to reach USD 1,947.03 Million by 2032. The forecast period (2026–2032) carries a projected compound annual growth rate (CAGR) of 18.02% (USD, revenue in Million). For corporate leaders planning capital allocation, procurement strategies, or R&D roadmaps in 2026, these dynamics are no longer hypothetical — they will materially affect supplier selection, partner strategies, and regulatory compliance pathways.
Hfo Cooling Fluids For Data Center Market
Why this report is strategically material for 2026
-
Regulatory inflection points are concentrated in the 2026–2028 window. The U.S. EPA Technology Transitions rule establishes binding GWP limits (effectively reshaping equipment eligibility from 2027), while regional frameworks such as the EU F‑Gas regime and the Kigali Amendment continue to accelerate substitution away from high‑GWP refrigerants. China’s quota and encouragement mechanisms further alter the timetable for global supply and deployment decisions. These rules change not only product eligibility but also procurement risk profiles and inventory strategies.
Hfo Cooling Fluids For Data Center Market -
Supply‑side realities — raw material concentration and price volatility — are already showing in the market. Manufacturers cite dependency on specialized fluorinated feedstocks and olefins; producers have taken price adjustments to pass through input cost inflation. These dynamics make multi‑supplier strategies and long‑term offtake agreements a practical necessity for large-scale data center deployments.
Hfo Cooling Fluids For Data Center Market -
Market concentration is significant: the top three suppliers control a dominant share of commercialized HFO cooling fluid supply, and the top five firms extend that dominance further. Concentration elevates counterparty risk and increases the strategic value of early qualification and partnership agreements.
What PW Consulting’s report delivers to executives
This report was written to convert technical complexity into decision‑grade outputs. It is not a catalogue of raw tables; it is a toolkit designed for Chief Technology Officers, Head of Procurement, Head of Data Center Operations, and Corporate Strategy teams who must make investment calls in 2026. Key deliverables include:
- Transparent market sizing and an auditable methodology for historic and forward estimates (2020–2032), presented in USD Millions and stress‑tested through scenario analysis.
- A regulatory impact map tying global and regional policy milestones to equipment eligibility, compliance cost impacts, and deployment timing windows.
- Supply chain mapping and supplier risk scoring, including feedstock exposure, manufacturing capacity posture, and ease of qualification for hyperscaler and colocation environments.
- Techno‑economic models (modular TCO) that capture energy, water, maintenance, compatibility testing, and end‑of‑life disposals; these models are designed to be instantiated on real deployment parameters.
- Operational playbooks: step‑by‑step qualification checklists, sample test protocols, vendor scorecards, and compatibility matrices required for safe field deployment.
- Investment and procurement decision frameworks for CAPEX and OPEX trade‑offs, including alternative scenarios for single‑phase and two‑phase immersion, direct‑to‑chip cold plates, and chiller integration strategies.
- Case studies and first‑mover learnings from commercial trials and full‑scale pilots, with practical recommendations for scaling from rack‑level trials to multi‑MW deployments.
To preserve the commercial value of the dataset and to drive responsible disclosure, this release intentionally highlights trends and strategic implications while withholding granular segment and regional tables. The full report contains the detailed splits and downloadable data tables that drive the models summarized here.
Competitive landscape — players, posture, and what it means for 2026
The HFO cooling fluid market today is defined by a small set of industrial chemical incumbents and specialised fluid innovators. We profile both types and assess commercial posture rather than simply cataloguing products.
-
The Chemours Company — With its Opteon™ 2P50 family and related dielectric heat transfer offerings, Chemours has positioned itself as a commercial anchor for two‑phase immersion applications. Recent milestones (strategic manufacturing agreements and third‑party qualifications) indicate a deliberate move to secure supply chain and co‑development pathways with equipment providers and hyperscalers. For buyers this means established qualification tracks exist, but counterparty negotiation leverage is tied to proven compatibility and volume commitments.
-
Solstice Advanced Materials (formerly Honeywell Advanced Materials) — Solstice‑branded HFOs are being positioned for high‑performance cooling with a strong emphasis on lifecycle environmental performance. The supplier community has faced raw material cost pressures and has implemented measured price adjustments to protect margin. For procurement teams, this underscores the need to model both nominal price and volatility over contract durations.
-
Arkema S.A. — Arkema’s HFO portfolio (including formulations positioned for chillers and immersion) and recent capacity ramp‑up activities suggest an intent to secure both commodity and speciality demand. Increased capacity reduces some upstream supply risk but also signals more aggressive competitive positioning over contract terms and local production advantages.
-
TMC Industries — As a specialised supplier of dielectric HFOs for immersion, TMC represents the category of smaller, agile actors that can move quickly on bespoke formulations and fast qualification cycles. Their presence is critical for operators seeking rapid pilot schedules or niche compatibility requirements.
-
Daikin Industries, Ltd. — Leveraging deep refrigerant experience, Daikin is notable for bridging HVAC/R manufacturing with data center cooling needs. For integrators, this kind of supplier offers end‑to‑end system design capabilities that can simplify vendor management.
Recent public milestones (product qualifications with major storage OEMs, strategic manufacturing agreements, and targeted capacity expansions) validate the pace of commercialization. These developments also change the timetable for decisive procurement: a year’s delay in qualification or contracting can translate into meaningful cost and availability asymmetries.
Strategic recommendations for 2026 — what to do next quarter
-
Prioritise supplier qualification now. Build test plans that include multi‑vendor compatibility tests with target server/storage OEMs and firmware revisions; start with rack‑level trials that replicate full heat density and cycling profiles.
-
Secure conditional supply commitments and consider staged offtake contracts tied to qualification milestones. Where feasible, negotiate price adjustment bands tied to raw material indices to hedge against sudden feedstock cost moves.
-
Embed regulatory scenarios into procurement specifications. Define acceptable GWP thresholds, labelling and documentation requirements, and transition clauses for equipment shipped before regulatory cut‑off dates.
-
Run TCO comparisons that incorporate non‑energy benefits such as water savings, data center PUE improvements, and reduced facility footprint. Use scenario outputs to quantify trade‑offs between single‑phase vs two‑phase immersion and hybrid cooling architectures.
-
Plan manufacturing and logistics footwork around regional regulatory windows. Early local production or secured regional inventory can be a competitive advantage in markets that transition on different timelines.
-
Explore strategic partnerships: co‑development deals with fluid suppliers, white‑label agreements with integrators, or minority investments in specialised chemistry firms can unlock preferential supply and co‑innovation benefits.
Decision‑grade tools included in the report
For teams ready to act, the report includes modular decision tools that translate the analysis into executable programs: a configurable TCO calculator, supplier scorecard templates, a regulatory compliance calendar linked to deployment milestones, manufacturing CAPEX and OPEX build‑out templates, and a risk heat map for supply‑chain shocks.
These instruments are built to be populated with your internal data and to generate board‑level decision memos within weeks, not months.
Next steps — where to get the full dataset
This briefing is intentionally selective: we show the market trajectory, the competitive topology, and the practical levers executives should use in 2026, while the full segment-level tables, regional splits, product-level forecasts, and downloadable model files are reserved for the comprehensive report. For procurement teams, engineering leaders, and strategy groups looking to operationalise these insights, the complete report contains the granular forecasts, vendor scorecards, and test‑protocol annexes necessary to implement the recommendations above.
To obtain the full Hfo Cooling Fluids For Data Center Market report and its decision‑grade toolset, visit the PW Consulting publications page or contact our industry practice. The window to secure advantageous supplier terms and to align deployment schedules with fast‑moving regulatory deadlines is narrow — the best time to start is now.
For detailed analysis of this topic, please visit the official page: Hfo Cooling Fluids For Data Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mp System On A Chip Market to Surge from USD 195,500 Million in 2025 to USD 363,159 Million by 2032 (2026–2032 Forecast) at 9.25% CAGR — Asia Pacific Leads with USD 98,312 Million
By pmarketresearch, 2026-07-01
MP System-on-a-Chip (SoC) Market — Strategic Outlook 2026: A PW Consulting Preview
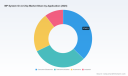
As global systems architects and corporate strategists prepare capital allocations and product roadmaps for 2026, our new Mp System On A Chip Market study provides a focused, decision-grade synthesis of where the industry is headed and how executives should act. The total market for Mp SoCs has expanded materially in the first half of the decade, rising from a mid-four-figure base (USD Million) in 2020 to an estimated USD 195,500 Million in 2025. Under our baseline forecast the market continues to scale, tracking toward roughly USD 215,088 Million in 2026 and reaching the high hundreds of billions by 2032 at a compound annual growth rate (CAGR) of about 9.25% through the forecast window (2026–2032). This growth, combined with a measured market concentration (CR3 ≈ 48.7%; CR5 ≈ 62.1%), frames a landscape of expanding opportunity where a handful of platform leaders coexist with specialized challengers.
Mp System On A Chip Market
Why this preview matters for 2026 decision-making
Two dynamics make 2026 a strategic inflection point: first, the convergence of next-generation process nodes and advanced packaging that materially reshapes performance-per-watt and system integration economics; second, an intensifying policy and supply-chain backdrop that alters geographies of risk and partnership strategies. For boards and product leaders, the immediate questions are whether to accelerate in-house SoC development, pursue chiplet strategies and packaging partnerships, or lean on contract design and foundry ecosystems. Our report is structured to answer those questions with scenario-tested pathways and investment trigger points rather than bright-line prescriptions.
Mp System On A Chip Market
Key technology and market inflection points
- Advanced process adoption and product timing: Leading SoC designers are moving to sub-3nm nodes in 2026 for flagship devices. The performance and efficiency gains are real, but the capital and supply constraints require precise go-to-fab timing to capture value without over-investing.
- Packaging and heterogeneous integration: CoWoS-class solutions and multi-die interposers enable integration of HBM and multiple chiplets with yields that make high-bandwidth, high-performance SoCs commercially viable at scale. This changes the calculus for firms that previously depended solely on monolithic scaling.
- Chiplet standardization: Industry efforts to standardize interconnects are reducing technical friction for heterogeneous integration, creating a market for modular SoC building blocks and enabling new supplier roles across compute, I/O, and accelerator domains.
- Regulatory and incentive landscape: Export controls, national incentives, and procurement policies shape long-term supplier selection and capital deployment. Public funding for domestic fabrication and research increases local capability but also fragments supplier footprints.
What the PW Consulting report delivers (actionable contents)
- Market sizing and multi-scenario forecasts through 2032, with transparent assumptions and sensitivity analyses tied to node adoption, packaging uptake, and macro demand cycles.
- Supply-chain mapping and a layered vendor ecosystem model that identifies single points of failure and strategic suppliers across IP, foundry, packaging, test, and assembly.
- Technology roadmaps and cost-curve modelling for advanced nodes, packaging options, and chiplet vs monolithic approaches—showing breakeven horizons for alternate strategies.
- Competitive playbooks and capability matrices for platform owners, fab-lite firms, foundries, and systems integrators—actionable for M&A prioritization, partnerships, and licensing decisions.
- Commercial go-to-market templates for consumer, telecom, automotive and industrial system OEMs that align product features with procurement cycles and regulatory constraints.
- Risk register and mitigation checklist covering export-control exposure, IP leakage, talent scarcity, and capital intensity—scored by impact and probability.
- Executive dashboards and downloadable datasets suitable for board briefings and investment committees, plus procurement negotiation playbooks for securing advanced-node capacity.
Competitive landscape: what leaders are doing now
The market exhibits a dual structure: a concentrated set of platform leaders and a diverse set of specialized players. Strategic positioning differs markedly by firm focus—mobile & consumer, compute & data center, automotive & industrial, and imaging/embedded SoCs.
Mp System On A Chip Market
- Qualcomm Technologies: Continues to anchor itself in mobile and automotive with integrated modem-to-application platforms. Its value proposition centers on modem-IP integration, connectivity stacks and ecosystem partnerships.
- Apple: Pursues vertical integration with tightly-coupled silicon-software optimization in consumer and computing products—setting performance benchmarks and raising the bar for system-level integration.
- MediaTek: Aggressively pursuing advanced-node leadership while balancing cost-sensitive product tiers. Recent tape-out activity on next-gen nodes signals intent to close the gap with incumbents on flagship performance.
- Samsung: Combines SoC design with foundry and packaging capabilities, enabling strategic product-fabric ecosystem plays particularly attractive to vertically integrated OEMs.
- AMD, Intel, NVIDIA: Each is reshaping SoC boundaries through processor-accelerator convergence for client, data-center and edge applications—competing on heterogeneous architectures and software stacks.
- Broadcom, NXP, STMicro, TI: Strengthen niches in networking, automotive, industrial control and mixed-signal integration—areas where reliability, real-time characteristics and certification matter more than peak FLOPS/W.
- OMNIVISION, Socionext: Maintain strategic footholds in imaging and custom solution SoCs for automotive and embedded markets where application-specific integration yields differentiated system outcomes.
Recent developments shaping 2026 strategies
- Major design houses preparing to adopt 2nm-class process nodes in 2026, accelerating the frontier of energy-efficient compute for flagship and premium segments.
- Awards and product demonstrations for real-time automotive microcontrollers and I/O interfaces point to near-term commercialization pathways for L3–L4 autonomous stacks.
- Standardization initiatives for chiplet interconnects and advanced packaging technologies (including high-yield interposers) are lowering integration costs and enabling new supplier roles.
- Policy moves—both incentives and export controls—continue to bifurcate global supply chains, making partner selection and intellectual-property strategy a core executive concern.
Practical strategic recommendations for 2026
- Adopt a portfolio timing approach: Stagger investments across monolithic advanced-node projects and packaged chiplet systems to capture near-term gains while retaining upgrade paths for next-node performance.
- Secure foundry commitments early: Locking capacity through strategic supply agreements or joint ventures reduces lead-time risk and provides leverage as node supply tightens.
- Prioritize packaging partnerships: Invest in advanced packaging capability either via partners or strategic minority stakes to obtain early access to CoWoS-like solutions and HBM integration.
- Design for modularity and standards: Embrace chiplet-friendly architectures and industry interconnect standards to shorten time-to-market and lower integration risk across product lines.
- Stress-test regulatory exposure: Map product roadmaps against export control regimes and subsidy conditions; create alternative sourcing and dual-supply routes for constrained inputs.
- Use value-based M&A: Target acquisitions that fill capability gaps (IP blocks, packaging expertise, or automotive-grade validation labs) and provide immediate go-to-market acceleration.
Risk outlook and mitigation
Primary risks for 2026 center on access to advanced process capacity, packaging lead times, and geopolitical/legal constraints on certain high-end manufacturing technologies. Secondary risks include software-hardware co-design talent shortages and fluctuating demand cycles across consumer and enterprise segments. Mitigation steps include multi-sourcing, strategic inventory policies for critical fab inputs, localized R&D investments supported by government incentives, and aggressive cross-training programs to build systems-level design teams.
Conclusion — how to use this preview
This preview synthesizes the directional insights and executive implications from our full Mp System On A Chip Market study. It is designed to orient boardrooms, product leaders, corporate development teams and procurement heads as they set 2026 priorities. For decision-makers who require the underlying region- and application-level breakouts, proprietary model tables, vendor scorecards, and the detailed scenario assumptions that drive our forecasts, the full report provides downloadable datasets and executable playbooks. Contact PW Consulting or visit our report page to access the complete datasets, vendor matrices and an executive briefing tailored to your organization’s strategy.
For detailed analysis of this topic, please visit the official page: Mp System On A Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dried Fruit Ingredients Market Valued at USD 9,547.42 Million in 2025, Set to Expand at 5.45% CAGR Over 2026–2032
By pmarketresearch, 2026-07-01
PW Consulting: Strategic Brief — Dried Fruit Ingredients Market (2026 Planning Lens)
Executive snapshot
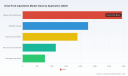
Our newly published Dried Fruit Ingredients Market report positions senior executives to make confident 2026 investments and commercial decisions in a market that remains resilient and increasingly strategic to food formulation. The global dried-fruit-ingredients market reached approximately USD 9.55 billion in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of about 5.45% through the 2026–2032 horizon, reaching an estimated USD 13.84 billion by 2032. Market concentration is moderate: the top three suppliers account for low twenties percent share while the top five reach the mid-thirties—enough room for scale advantages, but material opportunity for focused challengers and specialty players.
Dried Fruit Ingredients Market
Why this report matters for 2026 decision cycles
-
Timing and resource allocation: As companies set budgets and supply-chain strategies for 2026, the report translates high-level growth into practical investment priorities—ingredient development, supplier diversification, and channel-specific innovation—so leadership can prioritize capital and commercial effort where returns will be greatest.
Dried Fruit Ingredients Market -
Risk-informed sourcing: The dried-fruit complex remains exposed to crop cycles, weather-driven volatility and trade frictions. Our analysis synthesizes these drivers into near-term scenario plans, enabling procurement teams to balance cost, continuity and quality with explicit hedging and contracting tactics.
Dried Fruit Ingredients Market -
Commercial differentiation: For CPG and ingredient firms, the report maps where plain supply meets commoditization versus where value accrues (clean-label, functionalization, low-moisture formats, inclusion-ready blends). That mapping is designed to inform 2026 NPD and shelf-space strategies without waiting for quarterly results.
What the report contains — practical, action-oriented modules
-
Market framework and forecasts: A clear topline historical series and forward projection to 2032 (base year 2025), with scenario sensitivity that isolates the impact of raw-material shocks, tariff shifts and label/regulatory changes on volume and revenue trajectories.
-
Supply-chain heat maps: Granular flowcharts from grower to co-packer, highlighting pinch points for logistics, cold chain (where applicable) and processing capacity. Each heat map includes mitigation levers (contract structures, strategic buffer inventories, co-manufacturing partnerships).
-
Formulation playbooks: Technical guidance for integrating dried fruit ingredients into bakery, cereal, snack and dairy matrices—covering moisture control, particle sizing, sugar dynamics and shelf-life trade-offs. Includes lab-to-line scale considerations and cost-vs-performance matrices.
-
Commercial and pricing intelligence: Benchmarking dashboards that translate raw-material trends and regional demand drivers into actionable pricing corridors and supplier negotiation anchors.
-
Regulatory and recall readiness: Compliance checklists and response templates tied to recent regulatory updates and recall case studies to reduce time-to-containment and reputational damage.
-
M&A and partner scouting: Criteria-based shortlists and diligence frameworks for strategic acquisitions, minority stakes and co-development partnerships—prioritizing capabilities in specialty formats, value-added processing and premium sourcing.
Market dynamics & outlook (what to watch into 2026)
The dried fruit ingredients market is on an upward path led by demand for natural, convenience and functional claim sets. Growth is steady rather than hyperbolic—the mid-single-digit CAGR reflects broad-based consumption across bakery, cereals, snacks and new adjacencies such as nutrition bars and functional food inclusions.
Key dynamics shaping the next 12–24 months:
-
Raw-material volatility: Grower economics and harvest variability matter. For context, average grower returns for California natural seedless raisins and reported shifts in prune production have both exerted pricing pressure and supply tightness in recent seasons; buyers should assume intermittent price spikes and prepare flex contracts and multi-origin sourcing as default planning tools.
-
Labeling and composition scrutiny: FDA updates on Nutrition Facts and added-sugar disclosure remain a practical constraint for formulators. Expect reformulation projects to accelerate in 2026, particularly for items positioned on health or reduced-sugar claims.
-
Trade and tariff noise: Geopolitical and trade-policy shifts continue to redirect flows and raise landed-cost complexity. Recent retaliatory tariffs and trade measures have tangible P&L implications for suppliers and manufacturers that rely on cross-border ingredient flows.
-
Format innovation: Interest in low-moisture diced blends, inclusion-ready particulates and puree concentrates (for bar and dairy systems) is increasing. Product launches from suppliers and trade-show innovations signal that customers will prioritize format convenience and shelf-stable functionality in 2026 RFPs.
Competitive landscape — players to watch and strategic posture
The market combines long-established commodity leaders with nimble specialty suppliers. Together they shape pricing, product development and route-to-market norms.
-
Sun‑Maid Growers of California — As the globally recognized leader in raisin ingredients, Sun‑Maid retains scale advantages and deep channel relationships in baking and confectionery. Their playbook centers on cost-efficient supply and brand-driven co-marketing with large manufacturers.
-
Sunsweet Growers, Inc. — Focused on prunes/dried plums, Sunsweet has moved into ingredient innovation with inclusion-friendly formats. Their introduction of premix bits demonstrates how heritage suppliers are migrating up the value chain toward ready-to-use formats for industrial bakers and bar-makers.
-
Ocean Spray Cranberries, Inc. — Leveraging consumer-facing brand equity, Ocean Spray’s approach fuses ingredient supply with marketing lift, especially in trail-mix, bakery and snack applications that benefit from recognizable fruit provenance.
-
Regional and specialty players such as Graceland Fruit, Traina Foods, Mariani, and Monterey Bay Foods specialize in premium, diced or infused formats and serve brand-conscious CPGs. Their agility in developing low-moisture blends and customized cut/size profiles is a competitive differentiator for premium NPD.
-
Recent tactical moves—product launches, trade-show showcases and certification upgrades—signal that incumbents are investing defensively into format and claim innovation rather than competing purely on raw volume. This creates acquisition and partnership angles for firms seeking rapid capability build.
Strategic recommendations for 2026 (actionable levers)
-
Supply resilience first: Establish multi-origin contracts, incorporate price-adjustment clauses tied to transparent indices, and create a two-tier safety inventory for critical SKUs. Treat dried fruit as a strategic raw material, not a routine commodity.
-
Productization over commodity: Invest in format innovation (diced, low-moisture, inclusion-ready bits, purees standardized for processing) and secure co-development agreements with specialty suppliers to shorten time-to-shelf for premium claims.
-
Fast-track reformulation capability: Set a cross-functional reformulation sprint in 2026 with prioritization rules based on margin resilience and brand risk from labeling changes (e.g., added-sugars disclosure).
-
Commercial segmentation and channel playbooks: Use differential pricing and packaging for industrial vs. retail channels; for private-label and large co-manufacturers, focus on total-cost-of-use benefits (mixing behavior, yield, shelf-life) rather than per-kilo ingredient price.
-
M&A and partnership criteria: Target capabilities in high-margin formats, traceable provenance systems, or processing capacity in underserved geographies. Use a two-stage diligence checklist emphasizing processing yield, quality controls, and customer concentration.
Risk, compliance & reputation checklist
-
Recall readiness: Maintain rapid-traceability systems and pre-approved recall scripts. Recent supply-side recalls underscore that time-to-communication is as important as containment.
-
Labeling compliance: Keep a rolling program to monitor Nutrition Facts and sugar disclosure requirements; any product with added sugar or sweeteners should be evaluated for consumer claim exposure during 2026 relaunches.
-
Tariff and trade monitoring: Implement an early-warning desk to capture tariff updates and origin-based cost impact. Scenario-based landed-cost models will reduce procurement surprises during 2026 budgeting cycles.
How different stakeholders should use the report
-
Ingredient suppliers: Use the playbooks to prioritize format investments and to structure long-term contracts with large industrial buyers. Benchmark your position against the market concentration metrics and the competitive behaviors documented.
-
Food manufacturers and co-packers: Leverage the formulation matrices and risk dashboards to accelerate NPD and to negotiate favorable supply terms that reflect service-level needs, not just commodity pricing.
-
Private equity and strategics: Apply the M&A filters and integration scorecards to shortlist targets that can unlock margin via format premiuming or channel extension.
Closing — the trailer invitation
Our Dried Fruit Ingredients Market report combines macro clarity (with a 2025 market of roughly USD 9.55 billion and a 5.45% CAGR into 2032) with hands-on modules designed to shorten decision cycles in 2026. We deliberately balance depth with confidentiality: this brief highlights strategic implications and practical levers, while the full report contains the proprietary subsegment tables, regional splits, and supplier-level benchmarks required for transaction- and operational-grade decisions. For the complete dataset, scenario models and downloadable toolkits that boards and procurement teams can act on immediately, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Dried Fruit Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com