

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sleep Apnea Masks Market Poised to Expand at 8.15% CAGR from 2026–2032

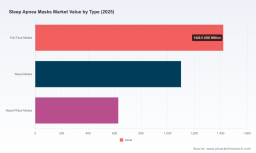
Sleep Apnea Masks Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
PW Consulting’s latest market research on the Sleep Apnea Masks market provides an evidence-driven playbook for executive teams preparing critical 2026 decisions. The global market has moved from roughly USD 2.06 billion in 2020 to an estimated USD 3.15 billion in 2025, and is projected to reach approximately USD 5.45 billion by 2032 at a compound annual growth rate (CAGR) of about 8.15% over the forecast horizon. These macro dynamics, combined with a high degree of industry concentration (CR3 ~78.4%; CR5 ~89.6%), materially change the geometry of competitive opportunity—favoring scale, differentiated clinical value, and payor-aware commercialization.
Sleep Apnea Masks Market
Why this report matters for 2026 strategic decisions
2026 is a watershed year for sleep-therapy stakeholders: regulatory clarity is crystallizing, new entrants and incumbents are introducing differentiated interfaces and AI-enabled features, and reimbursement pathways continue to evolve in core markets. Our study translates these external forces into an actionable decision framework for product managers, business development leads, procurement directors, and private equity firms. The research combines a rigorous top-down market sizing with bottom-up validation across clinical, regulatory, and channel inputs to produce a practicable roadmap—not an academic exercise.
Sleep Apnea Masks Market
Core market dynamics — concise, actionable signals
-
Steady market expansion: The market’s trajectory from 2020 through 2025 demonstrates durable demand as diagnosis rates, treatment adherence programs, and device compatibility improve. The forecast to 2032 at an 8.15% CAGR signals sustained commercial upside for firms that can convert clinical efficacy into patient-preferred interfaces and payor-aligned value propositions.
Sleep Apnea Masks Market -
High concentration: The top three and five players together control a substantial share of market value, which elevates the importance of partnership, niche specialization, and selective M&A to attain competitive scale.
-
Regulatory and reimbursement contours: CPAP masks remain regulated as Class II devices under 510(k) pathways in the U.S., and public payors like Medicare maintain established HCPCS coverage and replacement schedules for mask interfaces—both elements that shape product rollout timing and commercial models.
-
Materials and manufacturing: Medical-grade silicone continues to be the dominant cushion material due to biocompatibility and cleaning durability—an operational constraint that influences supplier selection and cost curves.
Competitive landscape: what incumbents and newcomers reveal
Our qualitative and transactional analysis profiles leading OEMs and relevant new entrants, mapping technology vectors, channel footprints, and regulatory milestones that materially affect go-to-market choices:
-
ResMed (San Diego): Continues to invest in integrated therapy ecosystems—AI-enabled comfort and personalization are now cleared and increasingly embedded as a differentiator for mask-device pairing. For partners, the lesson is clear: compatibility with device-side intelligence is a near-term commercial must.
-
Fisher & Paykel Healthcare (Auckland): Advances in cushion and headgear design—aimed at fit and seal consistency—underscore the continued yield from engineering-led differentiation in core mask types.
-
Philips Respironics (Amsterdam/Pittsburgh operations): Remains a scale competitor with broad interface portfolios; integration of user experience innovations into established channels is their primary lever for retention.
-
Inogen (Goleta): The Aurora entry demonstrates that adjacent respiratory players can rapidly introduce credible CPAP masks when supported by clinical-use studies—new entrants should plan for rapid evidence generation to accelerate channel acceptance.
-
REMSleep (Blackshear): Recent expanded FDA 510(k) clearance for a nasal pillow system exemplifies how regulatory wins can unlock institutional channels and broaden patient applicability—especially relevant for companies targeting hospitals and sleep labs.
-
Other OEMs (Drive DeVilbiss, React Health, Bleep, BMC Medical): These companies highlight alternative routes to market—from value-focused OEM supply to design-led niche products—illustrating multiple commercialization archetypes beyond incumbent strategies.
Recent product and regulatory developments: strategic takeaways
Key events through early 2026 underscore the bifurcation of competitive advantage into (a) clinical/regulatory credibility and (b) user-centered design integrated with device ecosystems. Examples include AI-enabled comfort features now cleared for market, new cushion/headgear launches, and regulatory clearances that extend product usage into institutional settings. For strategic planners, the implications are straightforward: prioritize regulatory roadmaps and clinical evidence generation concurrent with design investments to compress time-to-revenue.
What’s inside the PW Consulting report (practical deliverables)
Our report is structured as an executive-grade decision toolkit rather than a purely descriptive market brief. Key deliverables include:
-
Macro and micro market sizing with a validated forecast model and scenario analyses to stress-test 2026–2032 revenue paths.
-
Competitive matrix and capability heatmaps describing product portfolios, regulatory status, and channel strength—designed to support rapid partner/target screening.
-
Commercial playbooks for four go-to-market archetypes: incumbent OEM scale, challenger specialist, value/OEM supply, and platform-integrated device partnerships.
-
Regulatory and reimbursement maps with timing assumptions and risk buffers to accelerate launch approvals and payer contracting.
-
Supplier and cost structure benchmarks focused on cushion materials, headgear sourcing, and high-volume manufacturing levers.
-
M&A and partnership target shortlists with acquisition valuation frameworks and integration checklists tailored for 2026 deal pacing.
-
Clinical adoption levers and patient adherence frameworks—translating mask design and comfort features into measurable adherence uplift and downstream device utilization.
Recommended actions for leadership teams in 2026
The following strategic actions distill our analysis into immediate next steps for companies looking to capture disproportionate share of the forecast growth:
-
Prioritize regulatory sequencing: align 510(k) or equivalent filings with parallel clinical-use studies to shorten commercialization cycles, particularly if targeting institutional channels.
-
Invest in compatibility partnerships: ensure mask designs are interoperable with AI-enabled therapy features from major device OEMs to avoid exclusion from integrated ecosystems.
-
Optimize supplier base for silicone cushions: secure biocompatible material supply and dual-sourcing plans to mitigate cost and availability risks.
-
Map reimbursement timing and documentation: build HCPCS-aligned product lifecycles and replacement plans into commercial contracts to protect unit economics.
-
Segment route-to-market: deploy differentiated routes (direct for premium platforms, distributors for mid-market, OEM supply for scale) rather than a one-size-fits-all distribution model.
-
Consider bolt-on M&A for rapid feature acquisition (e.g., headgear technology, AI comfort algorithms) instead of multi-year internal development for near-term market access.
-
Document adherence economics: quantify how small improvements in seal and comfort translate into measurable increases in therapy compliance and downstream device revenue.
Why PW Consulting’s approach reduces strategic execution risk
Our methodology blends time-series market modeling with primary interviews across clinicians, procurement officers, and payor representatives, producing high-confidence forecasts and executable commercial plans. Importantly, while we present overall market size and concentration metrics to guide portfolio sizing and capital allocation, the report intentionally withholds granular public disclosure of proprietary subsegment splits in this release—those detailed segmentation tables, regional builds, and customer-level insights are included in the full report to support transaction-level diligence.
Next steps and how to use this study
For boards, this report serves as an input to 2026 capital allocation decisions: whether to greenlight product investments, pursue M&A, or shift distribution strategies. For commercial teams, the implementation playbooks provide immediate templates for payer engagement and channel rollout. For R&D leaders, the product-pricing-supplier nexus in the report helps prioritize features that materially improve adherence while protecting margins.
PW Consulting invites decision-makers to access the full report for the detailed segmentation tables, regional and application breakdowns, and our proprietary scenario models that underpin the revenue forecasts. The complete dataset and executable annexes are designed to be directly reusable in strategic planning, investment memos, and transaction diligence.
Conclusion
The Sleep Apnea Masks market offers predictable growth and concentrated competitive structures that reward focused strategic moves in 2026. Companies that synchronize regulatory strategy, evidence generation, supply resilience, and channel design will capture the bulk of the opportunity. PW Consulting’s study is structured to turn these insights into executable plans—download the full report to see the proprietary subsegment data, calibrated scenarios, and operative templates that will make your 2026 choices decisive.
For detailed analysis of this topic, please visit the official page: Sleep Apnea Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com